
 South Africa Digital Twin Market | 2026-2036
South Africa Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Digital Twin Market Insights
The capability gap between cloud-native platform developers and legacy automation incumbents is redrawing competitive boundaries in South Africa. Siemens AG leverages its TIA Portal ecosystem to anchor large-scale industrial deployments across Eskom power stations and Transnet port facilities. ANSYS, Inc. specializes in physics-based simulation layers that differentiate its offering for automotive tooling and aerospace component testing in the Eastern Cape.
A digital twin constitutes a dynamic virtual replica of a physical asset, system, or process that ingests real-time sensor data and applies computational models to simulate behavior, predict failure modes, and optimize operational parameters. In South African industry, these systems primarily serve to reduce unplanned downtime in capital-intensive sectors where single-hour outages can cost millions in lost throughput. Manufacturing application deployments currently occupy the largest revenue share as automotive and minerals processing plants retrofit legacy lines with IoT-enabled monitoring infrastructure. Cloud-based deployment models represent the fastest-expanding segment, driven by Microsoft's Azure data center presence in Johannesburg and the declining cost of fiber connectivity to industrial zones.
South Africa's national regulator for communications, ICASA, governs spectrum allocation for industrial IoT networks that underpin twin connectivity, while the South African Bureau of Standards (SBS) develops conformity assessment protocols for cyber-physical systems. The Department of Science and Innovation's Cybersecurity Hub increasingly shapes procurement requirements for critical infrastructure operators seeking digital twin platforms. Stakeholders must monitor whether ICASA's planned spectrum auction reforms will expand private 5G network licensing for mine sites and manufacturing campuses.
Market Dynamics
The convergence of private 5G spectrum licensing and edge computing infrastructure is restructuring how South African asset operators deploy real-time simulation layers across geographically dispersed sites.
Growth Catalysts
- ICASA spectrum reforms:Planned private 5G network licensing for mine sites and manufacturing campuses eliminates connectivity bottlenecks that previously constrained sensor density in remote Northern Cape operations.
- Advanced manufacturing incentives:The Department of Trade, Industry and Competition's fiscal support programs reduce capital barriers for automotive and minerals processing plants retrofitting legacy lines with IoT-enabled monitoring infrastructure.
- Cloud data center presence:Microsoft's Azure Johannesburg facility enables sub-20 millisecond latency for cloud-based twin deployments, compressing fiber-to-edge costs for Gauteng industrial corridor headquarters.
Market Restraints
- Specialized systems integration scarcity:Gauteng and Western Cape host the only dense clusters of qualified implementers, creating procurement bottlenecks for Mpumalanga and Limpopo mining operations.
- Legacy automation lock-in:Decades of Siemens S7 and Rockwell PLC deployments impose protocol translation costs that inflate integration timelines by 40-60 percent for brownfield sites.
- Cyber-physical security mandates:The Department of Science and Innovation's Cybersecurity Hub procurement requirements impose certification delays that extend vendor qualification cycles for critical infrastructure operators.
Strategic Opportunities
- Eastern Cape aerospace testing:Physics-based simulation layers for component stress testing remain underdeployed relative to automotive and mining saturation in other provinces.
- Water-energy nexus applications:Convergence of digital twin platforms with smart metering infrastructure opens municipal and agricultural water management as adjacent verticals beyond industrial manufacturing.
- Skills pipeline partnerships:Tertiary institutions in Pretoria and Stellenbosch are developing dedicated programs, creating captive talent channels for platform vendors establishing local delivery centers.
Industry Challenges
- Interdisciplinary talent scarcity:Operators require personnel blending mechanical engineering, data science, and OT security expertise, a combination absent from conventional South African technical training pipelines.
- Multi-vendor integration complexity:Deployments spanning ANSYS physics engines, Azure cloud layers, and Siemens edge hardware generate interface debugging burdens that strain in-house IT teams.
- Conformity assessment timelines:South African Bureau of Standards protocols for cyber-physical systems lack prescriptive digital twin annexes, forcing case-by-case certification negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Digital Twin Market |
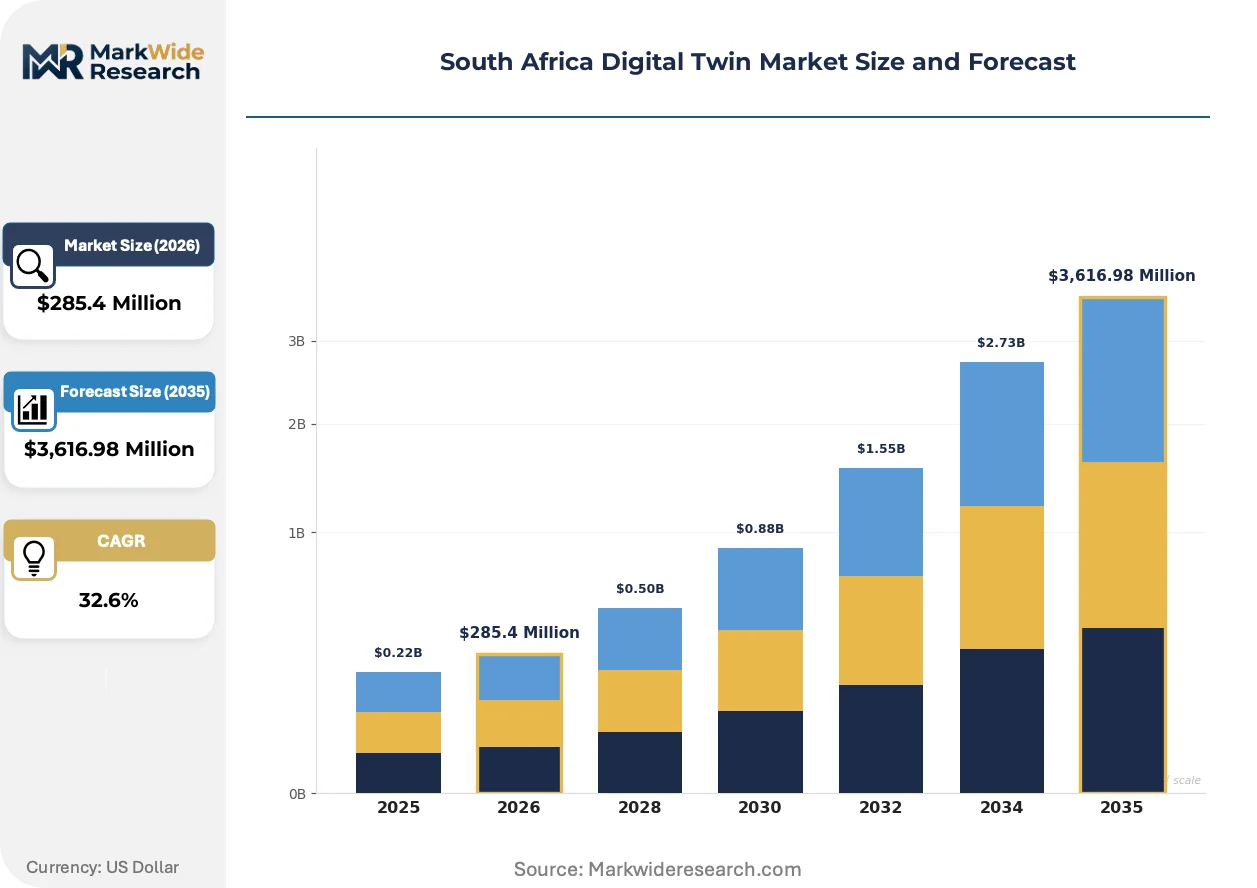
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $3,616.98 Million |
| CAGR (2026 – 2036) | 32.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Urban Planning, Healthcare, Automotive Technology: IoT, AI, Machine Learning, Cloud Computing End User: Industrial Sector, Construction Firms, Healthcare Providers, Smart Cities Deployment: On-Premises, Cloud-Based, Hybrid, Edge |
| Companies Covered | General Electric, ANSYS, Inc., Siemens AG, Oracle Corporation, PTC Inc., IBM Corporation, Dassault Systèmes, Accenture, Microsoft Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Digital Twin Market Trends and Innovations
Edge-native simulation architectures are displacing centralized cloud processing for latency-critical applications, while regulatory pressure on critical infrastructure cybersecurity reshapes procurement specifications.
Physics-informed neural networks are decomposing traditional finite element analysis workflows in South African mining applications. Anglo American and Sibanye-Stillwater pilot programs embed these models directly on haul truck edge gateways, enabling 50-millisecond vibration anomaly detection without round-trip cloud latency. This compression of simulation topology eliminates dependency on continuous fiber connectivity in Northern Cape pit operations.
The Department of Science and Innovation's Cybersecurity Hub mandates now require multi-factor authentication and encrypted telemetry for all critical infrastructure digital twin deployments. Industrial operators in Eskom and Transnet facilities must demonstrate zero-trust architecture compliance before platform commissioning. Eastern Cape automotive suppliers report 90-day procurement delays as they reconfigure supplier qualification documentation to satisfy these protocols.
Asset operators increasingly unbundle hardware procurement from simulation software licensing, reversing the bundled system sales that dominated early deployments. Johannesburg-headquartered mining houses now issue separate RFPs for sensor infrastructure, platform licenses, and integration services, compressing vendor margins but expanding qualified supplier pools. This disaggregation is most visible in Gauteng platinum processing plants, where procurement teams cite flexibility advantages in multi-site standardization programs.
South Africa Digital Twin Market Segmentation
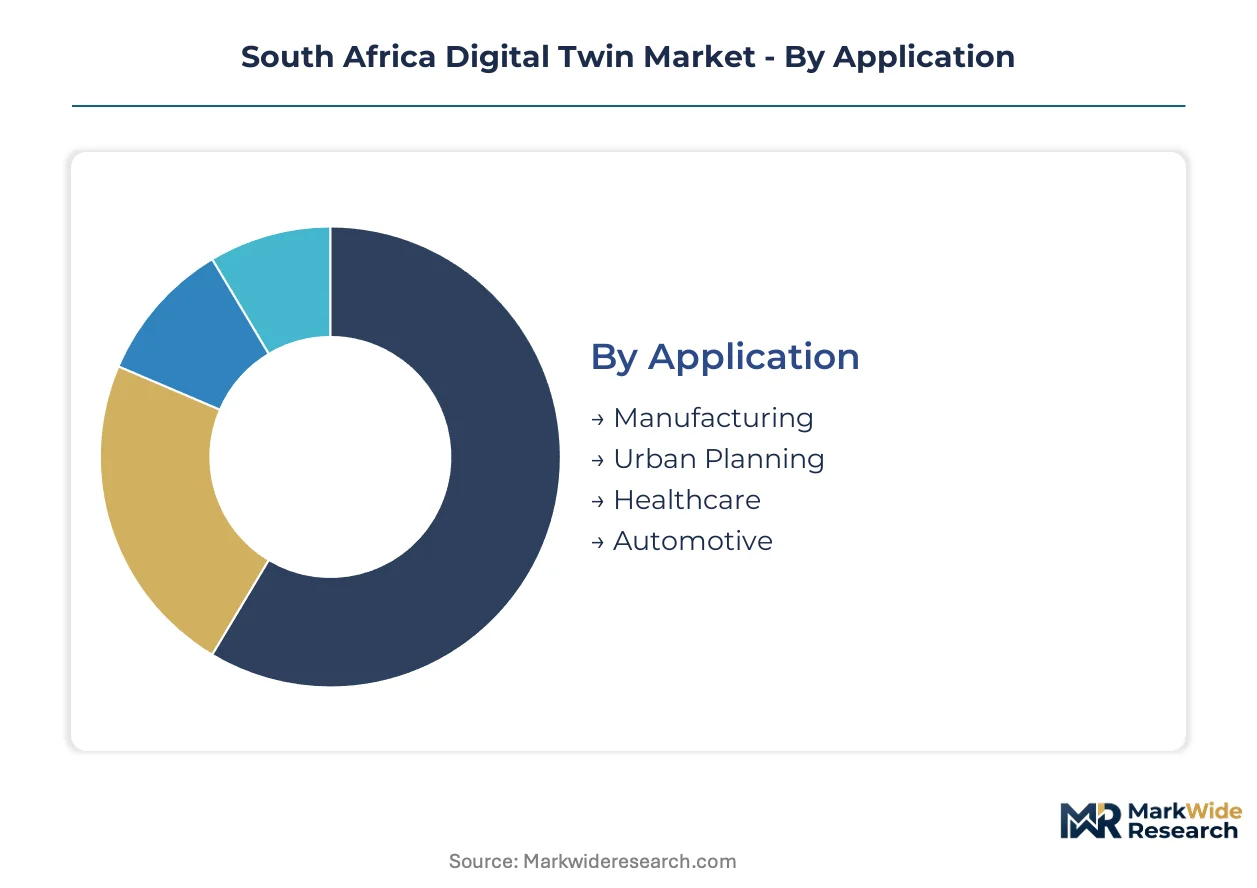
Segmentation reveals how digital twin deployments concentrate across South Africa's capital-intensive industries. Each dimension exposes distinct procurement patterns, technology requirements, and geographic clustering that vendors must navigate.
Application:
Domestic demand anchors manufacturing and automotive applications in Gauteng and the Eastern Cape, while urban planning solutions increasingly serve municipal export advisory contracts across Sub-Saharan Africa.
- Manufacturing:IoT-enabled monitoring infrastructure retrofitted onto legacy automotive and minerals processing lines. Demand clusters in Johannesburg-Pretoria industrial corridor where platinum processing plants and vehicle assembly operations drive platform procurement.
- Automotive:Component stress testing and production line optimization for OEM suppliers. Eastern Cape tooling facilities anchor this segment, with physics-based simulation layers differentiating vendor offerings for export-certified production.
- Urban Planning:Infrastructure simulation for municipal water-energy nexus management. Smart metering convergence opens adjacent verticals beyond industrial manufacturing.
- Healthcare:Patient flow optimization and medical device lifecycle management. Deployment lags industrial applications due to stricter data sovereignty requirements.
Manufacturing commands the established base. The steepest expansion runs through automotive as Eastern Cape suppliers retrofit for export compliance.
Technology:
Cost tier stratification separates capital-intensive edge-AI deployments from subscription-based cloud layers accessible to mid-market construction firms.
- IoT:Sensor infrastructure for real-time asset telemetry. Northern Cape mining operations deploy dense haul truck monitoring networks where private 5G spectrum reforms eliminate prior connectivity bottlenecks.
- AI:Physics-informed neural networks decomposing finite element analysis workflows. Anglo American and Sibanye-Stillwater embed these models directly on edge gateways for 50-millisecond anomaly detection.
- Machine Learning:Predictive maintenance algorithms trained on historical failure data. Mpumalanga processing plants leverage these for unplanned downtime reduction.
- Cloud Computing:Subscription-based simulation platforms hosted in Microsoft's Azure Johannesburg facility. Sub-20 millisecond latency enables headquarters-level deployment without fiber-to-mine infrastructure.
IoT and AI absorb the largest capital allocation. Cloud Computing climbs the fastest as fiber cost compression expands addressable mid-market demand.
End User:
Customer type determines procurement complexity, with critical infrastructure operators facing extended cybersecurity certification cycles compared to private construction firms.
- Industrial Sector:Mining houses and energy operators across Northern Cape, Mpumalanga, and Limpopo. Eskom power stations and Transnet port facilities mandate zero-trust architecture compliance before platform commissioning.
- Smart Cities:Municipal infrastructure operators in Johannesburg, Cape Town, and eThekwini. Water-energy nexus applications dominate procurement specifications.
- Construction Firms:Building information modeling integration for large-scale developments. Western Cape and Gauteng host the densest vendor engagement.
- Healthcare Providers:Hospital networks and medical device operators. Procurement delays persist as facilities reconfigure documentation for Cybersecurity Hub protocols.
Industrial Sector commands the established base. Smart Cities gain share fastest as municipal digitization budgets expand.
Deployment:
Maturity stage separates legacy on-premises installations from emerging edge-native architectures displacing centralized processing.
- Cloud-Based:Subscription platforms leveraging Azure Johannesburg presence. Fastest-expanding segment driven by declining fiber connectivity costs to industrial zones.
- Edge:Native simulation architectures processing data at haul truck gateways and pit operations. Eliminates dependency on continuous fiber connectivity in remote Northern Cape sites.
- On-Premises:Legacy server installations retained by operators with strict data sovereignty requirements. Declining share as hybrid alternatives mature.
- Hybrid:Split processing between local edge nodes and cloud analytics layers. Emerging preference for multi-site mining house standardization programs.
On-Premises retains the installed base. Edge deployment expands most quickly as physics-informed neural networks compress simulation topology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import intensity for digital twin platforms runs high across South Africa's industrial heartland, with Gauteng-based headquarters sourcing sensor infrastructure and cloud compute services while export-oriented Eastern Cape automotive suppliers drive specialized simulation demand.
Gauteng
Johannesburg and Pretoria host the densest clusters of system integrators and asset-intensive headquarters. The Department of Trade, Industry and Competition's advanced manufacturing incentives compress capital barriers for platinum processing plants retrofitting legacy lines. Microsoft's Azure Johannesburg facility enables sub-20 millisecond latency for cloud-based deployments across the industrial corridor.
Northern Cape
Mining houses deploy predictive maintenance systems for haul trucks and processing plants in remote pit operations. ICASA's planned private 5G spectrum reforms eliminate connectivity bottlenecks that previously constrained sensor density. Dense haul truck monitoring networks now operate independently of continuous fiber infrastructure.
Mpumalanga
Coal and minerals processing plants leverage machine learning algorithms for unplanned downtime reduction. The national Department of Science and Innovation's Cybersecurity Hub procurement requirements extend vendor qualification cycles for critical infrastructure operators. Local procurement bottlenecks persist due to scarce qualified systems integrators outside Gauteng and Western Cape clusters.
Eastern Cape
Automotive tooling facilities anchor physics-based simulation demand for export-certified production. ANSYS, Inc. specializes in component stress testing layers that differentiate offerings for aerospace applications. Supplier qualification documentation reconfigurations impose 90-day procurement delays under zero-trust architecture mandates.
Western Cape
Stellenbosch tertiary institutions develop dedicated digital twin skills programs, creating captive talent channels for platform vendors. Municipal water-energy nexus applications open adjacent verticals beyond industrial manufacturing. Construction firms in Cape Town drive building information modeling integration for large-scale developments.
South Africa Digital Twin Market Competitive Landscape
Concentration sits with legacy automation incumbents anchoring brownfield integration, while cloud-native platform developers capture greenfield expansion. Siemens AG leverages established TIA Portal ecosystems at Eskom and Transnet facilities. ANSYS, Inc. occupies specialized physics-based simulation niches. Strategic moves center on unbundling hardware procurement from software licensing and forming skills pipeline partnerships with Pretoria and Stellenbosch institutions.
Within the legacy automation tier, Siemens AG anchors large-scale industrial deployments through its established ecosystem relationships. ANSYS, Inc. exemplifies the physics-simulation specialist archetype serving automotive and aerospace testing requirements. Microsoft Corporation represents cloud-native platform expansion through its Johannesburg data center presence and Azure infrastructure services.
| Leading Market Players |
|---|
| General Electric |
| ANSYS, Inc. |
| Siemens AG |
| Oracle Corporation |
| PTC Inc. |
| IBM Corporation |
| Dassault Systèmes |
| Accenture |
| Microsoft Corporation |
| Others |
Pricing and Supply Chain Analysis
Azure Johannesburg's sub-20 millisecond latency capacity compresses fiber-to-edge costs and concentrates cloud-native platform pricing power among hyperscalers, while legacy automation incumbents defend premium tiers through bundled hardware-software contracts at brownfield industrial sites.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle physics-based simulation layers with dedicated integration support for Eastern Cape automotive suppliers, while subscription SaaS models serve mid-market construction firms via Azure Johannesburg. Price differentiation rests on certification grade under Cybersecurity Hub protocols and deployment complexity at multi-site mining houses. Cost compression in standard tiers intensifies as unbundled procurement separates sensor infrastructure from platform licenses. Municipal water-energy operators exhibit highest price sensitivity due to constrained digitization budgets, whereas Eskom and Transnet facilities absorb premium pricing for zero-trust architecture compliance.
Supply Chain Analysis
Strategic stockpiling of edge gateway hardware dominates over just-in-time preferences as ICASA spectrum auction timelines create procurement uncertainty for Northern Cape mining operations. Component supply concentrates in Germany, China, and the USA for industrial automation hardware, with sensor infrastructure drawing from Taiwan and South Korea. Raw material dependencies span silicon wafers for edge-AI processors, rare earth elements for vibration sensors, and fiber optic cable for pit-to-headquarters connectivity. Single-source vulnerability runs through Siemens S7 and Rockwell PLC protocol stacks that impose translation costs on brownfield retrofits. Distribution runs through Johannesburg-based system integrators serving Gauteng industrial corridor headquarters, with Western Cape clusters handling Eastern Cape automotive supplier demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's digital twin market occupies early-cycle expansion as private 5G spectrum reforms and cloud data center presence compress adoption barriers for asset-intensive operators previously constrained by connectivity costs.
For Market Incumbents: Consolidate ecosystem lock-in through deeper TIA Portal integration at Eskom and Transnet facilities before cloud-native platforms capture greenfield expansion. Acquire specialized physics-simulation capabilities to defend against ANSYS niche penetration in Eastern Cape aerospace testing. Prioritize certification pre-clearance under Cybersecurity Hub protocols to compress vendor qualification cycles that currently delay competitor entry. For New Entrants and Emerging Players: Differentiate on edge-native architectures that eliminate fiber dependency for Northern Cape pit operations where Anglo American and Sibanye-Stillwater pilot programs demonstrate demand. Target water-energy nexus applications in Western Cape municipalities as the most penetrable adjacent vertical beyond saturated industrial manufacturing. Pursue skills pipeline partnerships with Stellenbosch and Pretoria institutions to secure captive talent channels before incumbent vendors establish local delivery centers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform developers leveraging Azure Johannesburg infrastructure to serve mid-market construction firms and municipal operators. Long-term viability favors vendors with demonstrated zero-trust architecture compliance and established relationships with the Department of Science and Innovation. Acquisition target archetype: physics-simulation specialists with Eastern Cape automotive supplier traction and unbundled procurement flexibility. The signal to watch is ICASA spectrum auction timing and private 5G licensing uptake rates across Northern Cape mining houses.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unbundled procurement patterns favor vendors offering modular sensor-to-cloud architectures compatible with Siemens and Rockwell legacy stacks. |
| Strategic Partnership | Skills pipeline agreements with Stellenbosch and Pretoria institutions create captive talent channels for platform vendors establishing local delivery. |
| Geographic Expansion | Eastern Cape aerospace testing remains underdeployed relative to Gauteng mining and automotive saturation, offering white-space capture. |
| Product Launch | Edge-native simulation architectures with 50-millisecond anomaly detection capability address Northern Cape connectivity constraints. |
| Acquisition of Specialist Firm | Physics-based simulation capabilities differentiate offerings for automotive export compliance and aerospace component testing requirements. |
Research Methodology
Initial hypotheses were tested against primary input from mining house chief digital officers, automotive plant engineers, municipal infrastructure managers, and cybersecurity procurement leads, and refined through secondary validation against ICASA spectrum policy documents, Department of Trade Industry and Competition incentive filings, Microsoft Azure capex disclosures, and South African Bureau of Standards conformity assessment protocols. Bottom-up deployment counts across Northern Cape, Mpumalanga, and Gauteng industrial sites were triangulated against top-down platform vendor revenue segmentation.
Variance decomposition across the projection horizon isolates technology adoption curves, regulatory implementation timelines, and infrastructure investment cycles as primary uncertainty sources. Segmentation dimensions modeled span deployment model, end-use vertical, application complexity, and provincial adoption pattern. CAGRs were derived from fitted S-curve penetration models calibrated to historical industrial IoT diffusion rates in comparable emerging markets. Industry-specific forecast inputs include private 5G licensing uptake assumptions and Cybersecurity Hub procurement compliance trajectories.
The analysis sits within stated boundaries; outcomes outside sustained ICASA spectrum reform implementation and stable fiber cost compression would require recalibration. Forecasts reflect documented assumptions regarding edge-AI processor cost decline curves and mining house capital allocation priorities. Revision becomes warranted when Cybersecurity Hub protocol adoption crosses threshold penetration among critical infrastructure operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Global Website Builders Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Supplier Contract Management Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Desktop Virtualization in Manufacturing Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Product Engineering Services Market