
 Global Transport Management Software Market | 2026-2036
Global Transport Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transport Management Software Market Outlook
The EU AI Act is pivoting compliance costs upward for TMS vendors serving European shippers. SAP SE leverages its embedded ERP footprint to anchor multimodal planning inside existing enterprise workflows. WiseTech Global (CargoWise) sustains dominance in international freight forwarding through deep customs and compliance functionality.
Global Transport Management Software comprises digital platforms that optimize freight movement through algorithmic route planning, carrier selection, and real-time visibility across road, rail, ocean, and air modes. These systems integrate with warehouse management and ERP layers to reduce empty miles, consolidate shipments, and automate freight audit processes. Cloud-based deployment is capturing the fastest expansion as shippers and 3PLs abandon capital-intensive on-premises infrastructure for elastic, API-first architectures. Route optimization solutions command the deepest margin pools because fuel and labor savings translate directly to quantifiable ROI for fleet operators.
The US Department of Transportation, the EU's F-Gas Regulation framework, and China's MIIT are each tightening emissions tracking and digital reporting mandates that force carriers to upgrade from spreadsheet-based dispatch to integrated TMS platforms. The US EPA and NHTSA are layering fuel-efficiency benchmarks onto commercial trucking fleets, creating compliance-driven procurement cycles. Stakeholders must monitor which regulatory jurisdictions mandate API-accessible emissions data first, as this will determine where platform standardization accelerates and where fragmented national systems persist.
Market Dynamics
Cloud-native architectures are compressing deployment cycles from months to weeks, forcing legacy on-premise vendors to re-platform or lose enterprise accounts to API-first competitors. This infrastructure shift redistributes margin from software licenses toward data integration services.
Growth Catalysts
- EU Green Deal emissions mandates:Freight operators in Germany, France, and the Netherlands must digitize fuel tracking and route optimization to meet tightening CO2 reporting thresholds for cross-border haulage.
- Automotive export corridor digitization:German automotive OEMs and tier suppliers are consolidating fragmented carrier networks onto unified TMS platforms to synchronize just-in-sequence parts delivery across multimodal lanes.
- API-first integration standards:Real-time visibility protocols are enabling shippers to embed TMS data directly into customer-facing order management portals without middleware layers.
Market Restraints
- Concentrated cloud infrastructure:Three hyperscalers control over 70% of TMS-hosting capacity, creating single-point-of-failure risk and limiting vendor negotiation leverage on compute pricing.
- Legacy ERP lock-in:SAP and Oracle embedded transport modules capture renewal budgets before standalone TMS vendors can displace them, particularly in North American manufacturing.
- Telematics hardware shortages:Semiconductor supply constraints for onboard diagnostic devices delay fleet sensor deployment, pushing software ROI realization timelines outward.
Strategic Opportunities
- India's logistics digitization:The country's PLI scheme for automotive and electronics manufacturing is creating first-mover advantage for TMS vendors offering GST-compliant e-waybill integration and regional language interfaces.
- Blockchain-IoT convergence:Immutable cargo documentation combined with sensor-verified condition monitoring is expanding into pharmaceutical cold chain and high-value electronics verticals where liability transfer requires audit trails.
- CSRD-aligned carbon accounting:The EU's Corporate Sustainability Reporting Directive mandates granular Scope 3 transport emissions disclosure, opening subscription revenue for TMS platforms with embedded CO2 calculation engines.
Industry Challenges
- API interoperability gaps:Carrier EDI standards vary across road, rail, and ocean modes, forcing TMS vendors to maintain expensive adapter libraries that fragment development resources.
- Cyber-physical security certification:ISO/SAE 21434 automotive cybersecurity standards and NIS2 network security directives impose compliance timelines that smaller vendors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transport Management Software Market |
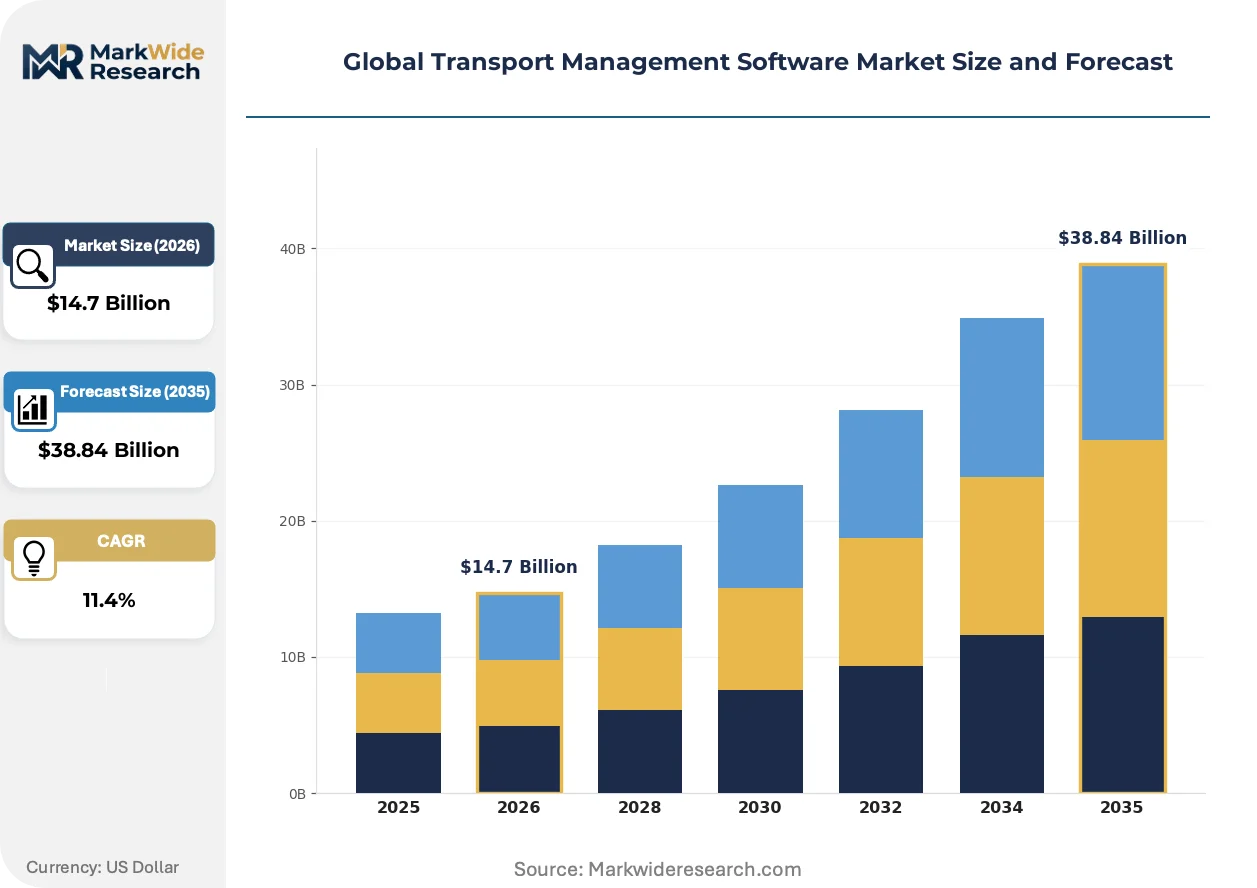
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Shippers, Freight Forwarders, 3PLs, Carriers Solution: Route Optimization, Freight Audit, Shipment Tracking, Inventory Management Application: Logistics, Supply Chain, Fleet Management, E-commerce |
| Companies Covered | Manhattan Associates, Inc., WiseTech Global (CargoWise), SAP SE, FourKites, Inc., Samsara Inc., Oracle Corporation, The Descartes Systems Group Inc., Trimble Transportation, Blue Yonder, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transport Management Software Market Strategic Shifts
Algorithmic decision layers are migrating from planning to execution, compressing the latency between freight visibility and automated carrier reallocation. This shift elevates real-time data quality above historical analytics as the primary competitive differentiator.
Digital freight matching platforms are expanding into contract freight procurement, displacing traditional broker relationships with dynamic pricing engines that algorithmically pair shipper loads against carrier capacity in 15-minute windows. Large retail distributors in the United States are piloting these systems for seasonal surge lanes, treating transport capacity as a spot-commodity rather than a negotiated annual commitment.
The EU AI Act's risk-based classification system is reclassifying autonomous dispatch algorithms as high-risk AI systems, requiring TMS vendors serving European shippers to implement explainability features and human oversight protocols. German chemical manufacturers and French food distributors are delaying procurement cycles to evaluate vendor compliance roadmaps, creating temporary demand concentration among early-certified platforms.
Shippers are unbundling freight audit and payment services from core TMS subscriptions, treating invoice validation as a standalone procurement category evaluated on recovery rate rather than software functionality. This pattern is most visible among North American consumer packaged goods companies with high invoice volumes and complex accessorial charge disputes, which now separately contract specialized audit firms while running leaner TMS configurations.
Global Transport Management Software Market Segmentation
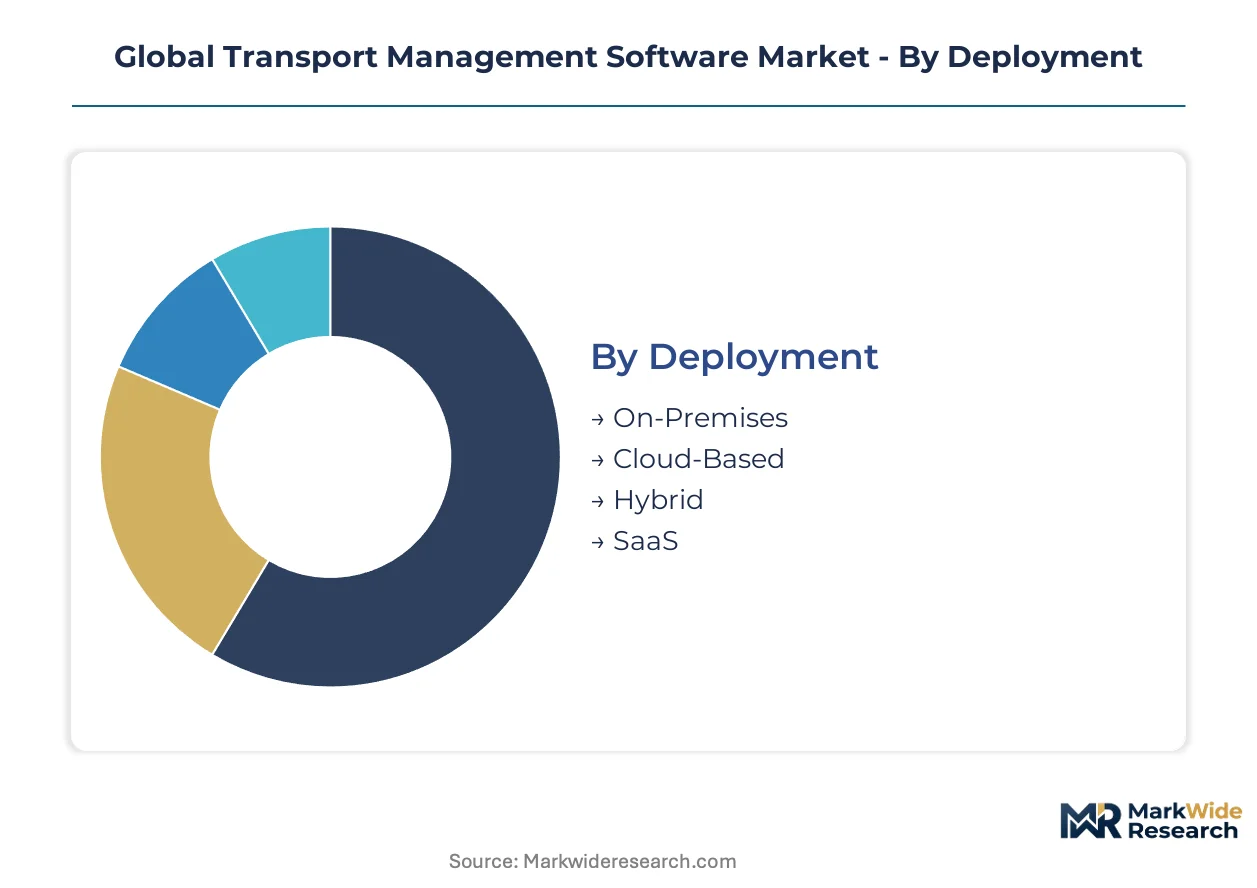
Transport management software segments diverge sharply by capital requirements and integration complexity. Deployment architecture determines upfront infrastructure spend, while end-user category shapes contract value and renewal dynamics. Solution type and application vertical further stratify margin profiles across the value chain.
Deployment:
Cloud-native architectures demand lower initial capital outlay than on-premise installations, though total cost of ownership shifts toward recurring subscription streams.
- On-Premises:Legacy server infrastructure requiring dedicated IT staff and hardware refresh cycles. German automotive manufacturers and French chemical conglomerates maintain these installations for air-gapped security compliance with EU NIS2 directives.
- Cloud-Based:Elastic compute resources provisioned across hyperscaler networks. Third-party logistics providers in the Netherlands and freight brokers in the United States are migrating here fastest to avoid data center capital expenditure.
- Hybrid:Split architectures keeping sensitive dispatch data on-premise while pushing analytics to cloud nodes. Appeals to Japanese automotive tier suppliers balancing IP protection with AI-enabled optimization.
- SaaS:Multi-tenant platforms with API-first integration. Indian electronics exporters leverage these for rapid GST e-waybill compliance without customization overhead.
Most installed capacity flows through On-Premises legacy estates. Expansion is steepest in Cloud-Based configurations.
End User:
Contract sophistication and procurement authority vary dramatically across buyer categories, reshaping vendor sales motion and pricing architecture.
- Shippers:Manufacturing and retail enterprises buying transport as a service. German automotive OEMs dominate this segment, consolidating fragmented carrier networks onto unified platforms for just-in-sequence parts delivery.
- Freight Forwarders:Intermediaries requiring deep customs and multi-modal documentation capabilities. Concentrated in Singapore and Rotterdam corridor operators serving Asia-Europe trade lanes.
- 3PLs:Asset-light logistics providers white-labeling capacity. These buyers prioritize white-label customer portals and embedded freight audit tools.
- Carriers:Asset-owning trucking and vessel operators. US long-haul fleets and EU road haulage cooperatives adopt these systems for fuel-efficiency benchmarking against EPA and EU Green Deal mandates.
Shippers command the largest aggregate contract values. 3PLs are gaining share fastest as outsourced logistics penetration deepens.
Solution:
Functional modules compete for platform centrality based on quantifiable ROI visibility and integration friction.
- Route Optimization:Algorithmic planning engines minimizing empty miles and fuel burn. US retail distributors and German grocery chains deploy these for last-mile density improvement.
- Freight Audit:Automated invoice validation against contracted rates and accessorial rules. North American consumer packaged goods companies now unbundle this as a standalone procurement category.
- Shipment Tracking:Real-time visibility protocols feeding customer-facing portals. Critical for pharmaceutical cold chain operators in Switzerland and high-value electronics shippers in South Korea.
- Inventory Management:Warehouse-TMS synchronization for yard management and cross-dock coordination. Japanese automotive suppliers prioritize this for sequencing precision.
Route Optimization absorbs the deepest R&D investment. Freight Audit is climbing fastest as shippers recover margin from invoice leakage.
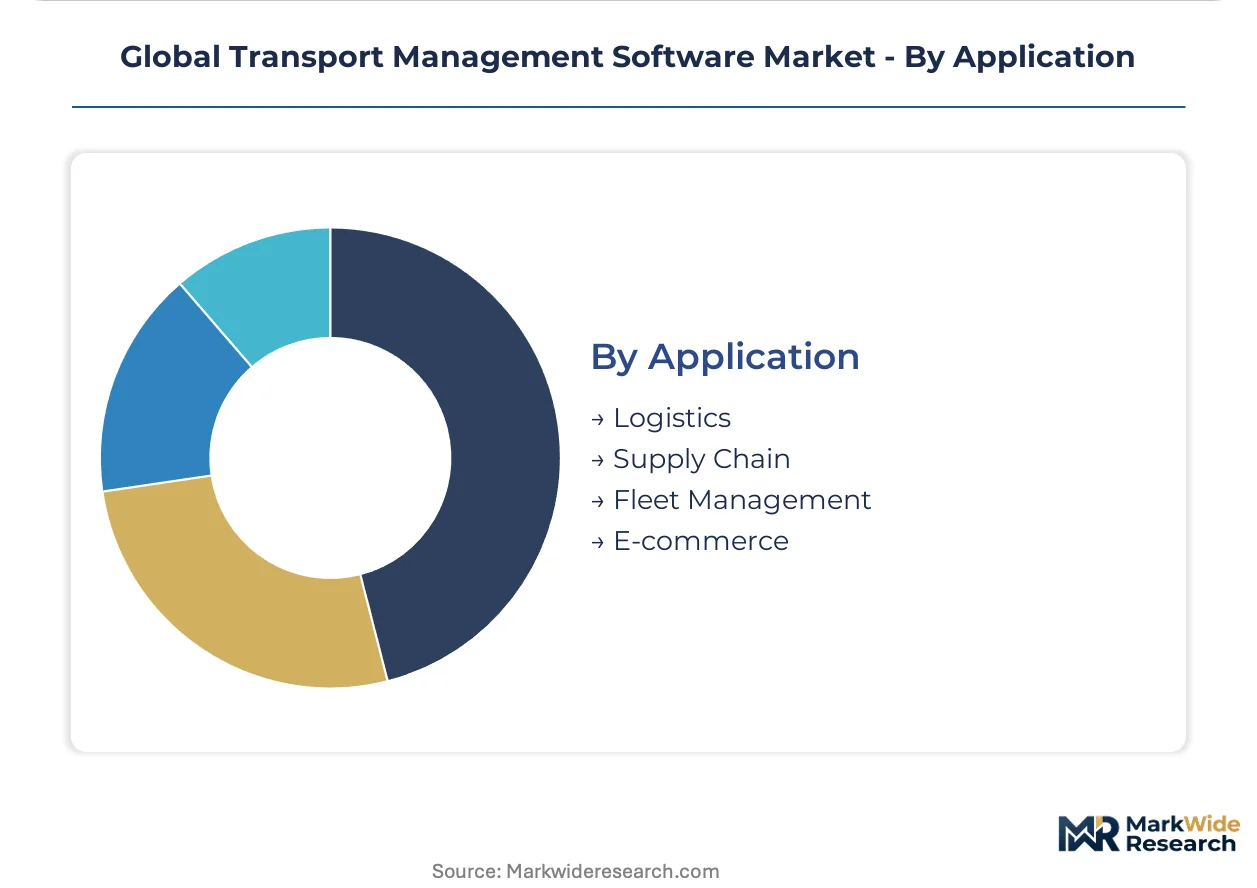
Application:
Vertical-specific compliance regimes and operational tempo dictate feature prioritization and deployment urgency.
- Logistics:General freight coordination across modal handoffs. Serves third-party warehouses and distribution centers in the US Midwest and German Ruhr industrial cluster.
- Supply Chain:End-to-end orchestration from procurement to delivery. Chemical manufacturers in Belgium and semiconductor fabricators in Taiwan require these for CSRD-aligned Scope 3 emissions reporting.
- Fleet Management:Asset utilization and driver compliance for owned vehicle pools. US EPA fuel-efficiency benchmarks and EU tachograph mandates drive replacement cycles here.
- E-commerce:High-velocity parcel sorting and returns processing. Dominant in Chinese cross-border export hubs and Indian metropolitan last-mile networks.
Supply Chain applications carry the highest per-seat pricing. E-commerce is expanding most quickly as parcel volumes surge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in the United States, Germany, and India anchor platform development capacity for transport management systems. Regulatory divergence across jurisdictions is fragmenting deployment standards while industrial corridor digitization concentrates demand in specific metropolitan zones.
United States
Retail distributors and long-haul fleets drive cloud migration as fuel-efficiency mandates from the EPA and NHTSA force spreadsheet-based dispatch into obsolescence. The Department of Transportation layers digital reporting requirements onto commercial trucking operations. Chicago and Dallas-Fort Worth logistics hubs host dense concentrations of 3PLs adopting API-first visibility platforms.
Germany
Automotive OEMs and chemical exporters consolidate fragmented carrier networks onto unified platforms for just-in-sequence parts delivery. The EU Green Deal and F-Gas Regulation tighten emissions tracking thresholds for cross-border haulage. The Ruhr industrial cluster and Stuttgart automotive corridor digitize fleet coordination at accelerated pace.
China
E-commerce parcel volumes and cross-border export manufacturing propel demand for high-velocity sorting systems. MIIT mandates digital infrastructure upgrades across commercial transport networks. Yangtze River Delta logistics zones deploy multimodal coordination platforms linking Shanghai port operations with inland manufacturing hubs.
India
Electronics exporters and automotive manufacturers adopt GST-compliant e-waybill integration under the PLI scheme incentive structure. The country's logistics digitization push creates first-mover advantage for vendors offering regional language interfaces. Maharashtra and Gujarat industrial corridors lead TMS adoption for pharmaceutical and textile export lanes.
Netherlands
Rotterdam corridor operators and freight forwarders serving Asia-Europe trade lanes prioritize deep customs and multi-modal documentation capabilities. EU AI Act compliance costs pivot procurement decisions toward early-certified platforms. Amsterdam and Rotterdam logistics clusters concentrate demand for real-time visibility protocols.
Global Transport Management Software Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Enterprise software incumbents leverage embedded ERP footprints to anchor multimodal planning inside existing workflows, while cloud-native challengers compress deployment cycles through API-first architectures. Three strategic archetypes dominate: ERP-integrated suites, freight-forwarding specialists, and fleet-centric visibility platforms. Competitive moves center on re-platforming legacy infrastructure and expanding data integration service portfolios.
Within the ERP-integrated tier, SAP SE exemplifies the enterprise workflow anchoring strategy. WiseTech Global occupies a position representing freight-forwarding specialization with customs and compliance depth. Manhattan Associates, Inc. sits within the supply chain execution archetype, bridging warehouse and transport coordination. These three entities collectively illustrate how vendor positioning diverges by buyer category and integration complexity.
| Leading Market Players |
|---|
| Manhattan Associates, Inc. |
| WiseTech Global (CargoWise) |
| SAP SE |
| FourKites, Inc. |
| Samsara Inc. |
| Oracle Corporation |
| The Descartes Systems Group Inc. |
| Trimble Transportation |
| Blue Yonder, Inc. |
| Others |
Value Chain & Pricing Dynamics
Diesel futures volatility at the Rotterdam hub cascades through transport management software tiers, compressing margins for on-premise legacy vendors while amplifying pricing power for cloud-native platforms that monetize fuel-savings ROI through outcome-based contracts.
Pricing Analysis
The bundled-vs-unbundled service split now defines TMS pricing architecture. SaaS subscription tiers stratify across enterprise, mid-market, and entry-level configurations, with API call volumes and integration node counts driving differentiation. Price differentiation rests on CSRD-aligned carbon calculation certification and real-time visibility protocol compliance. Pricing pressure stems from hyperscaler compute cost pass-throughs, with North American retail distributors exhibiting highest price sensitivity and German automotive OEMs showing lowest due to compliance-driven procurement urgency.
Supply Chain Analysis
Reverse-logistics flows for telematics hardware refurbishment concentrate in Malaysia, Mexico, and Poland, creating secondary component channels that temper semiconductor shortage impacts. The TMS supply chain draws from Taiwanese chip fabrication, German sensor engineering, and Indian software development centers. Single-source vulnerability concentrates in cloud infrastructure where three hyperscalers dominate hosting capacity. Distribution runs through direct enterprise sales for large shippers and channel partners serving mid-market 3PLs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU AI Act implementation milestones accelerate procurement cycles among risk-averse European shippers.
For Market Incumbents: Acquire specialized customs compliance engines to neutralize WiseTech Global's documentation moat. Consolidate fragmented adapter libraries through API standardization investments, addressing interoperability gaps that drain R&D resources. Threat vectors include cloud-native challengers compressing deployment cycles and EU cybersecurity certification timelines that smaller vendors cannot fund. For New Entrants and Emerging Players: Mid-tier Indian electronics exporters represent the most penetrable buyer archetype, underserved by legacy ERP modules lacking GST e-waybill integration. White-label TMS configurations for asset-light 3PLs in Southeast Asia offer second white-space entry. Go-to-market leverage rests on regional language interfaces and PLI scheme-aligned compliance roadmaps. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native visibility platforms possessing embedded carbon accounting engines. Long-term viability favors vendors with early EU AI Act certification and API-first architectures over legacy re-platforming efforts. Monitor CSRD Scope 3 disclosure enforcement timelines as the critical inflection signal for subscription revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures compress deployment cycles from months to weeks for 3PLs. |
| Acquisition of Specialist Firm | Customs compliance depth anchors multimodal planning in Rotterdam corridor operators. |
| Strategic Partnership | Hyperscaler alliances distribute compute pricing risk across elastic infrastructure pools. |
| Geographic Expansion | India's PLI scheme creates first-mover advantage for GST-compliant e-waybill vendors. |
| Product Launch | CSRD-aligned carbon calculation engines open subscription revenue from chemical manufacturers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged TMS product managers at enterprise software vendors, logistics procurement directors at German automotive OEMs, compliance officers at EU freight forwarders, and integration specialists at cloud hyperscalers. Secondary validation drew from SEC 10-K software segment disclosures, EU transport emissions reporting databases, and hyperscaler capex allocation filings. Bottom-up deployment model sizing and top-down enterprise IT spend analysis triangulated market estimates.
Segment-weighting approaches distributed value across cloud-native, hybrid, and on-premise deployment architectures, with further stratification by shipper, 3PL, freight forwarder, and carrier end-user categories. Modeled dimensions included solution type, application vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and compliance-driven replacement cycle analysis. Forecast inputs incorporated EU Green Deal enforcement timelines and semiconductor availability trajectories for telematics hardware.
Underlying measurement precision varies by segment; cloud-based deployment and route optimization solution sizing carry tighter precision than hybrid configurations and freight audit modules. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hyperscaler pricing stability. Practitioners should monitor EU AI Act certification deadlines and CSRD Scope 3 disclosure rollout for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Business As a Service Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Global Online Classifieds Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Event Apps Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
System Integrator Market
Digital Solutions
Data Converter Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Global Digital Accessibility Software Market