
 Product Prototyping Market | 2026-2036
Product Prototyping Market Size, Share, and Industry Trends Forecast 2026-2036
Product Prototyping Market Analytics
A shift from captive in-house shops to distributed on-demand networks is realigning how OEMs source early-stage parts. Stratasys leverages its polymer expertise to anchor high-fidelity aerospace mockup programs. Protolabs sustains competitive velocity through automated quoting platforms that compress RFQ-to-delivery windows. Xometry controls marketplace liquidity by aggregating thousands of qualified machine shops under unified quality standards.
Product prototyping encompasses the iterative fabrication of pre-production models to validate form, fit, and function before mass manufacturing commitment. Methods span fused deposition modeling with layer resolutions down to 0.1 mm, five-axis CNC machining of aluminum tool steel, and silicone vacuum casting for ten-unit pilot runs. Additive manufacturing dominates conceptual-phase work where geometry complexity outweighs unit cost, while CNC machining captures functional testing segments requiring tight tolerances and production-grade metals. Healthcare end users increasingly specify biocompatible resins and sterilizable polymers, creating premium material tiers within prototyping workflows.
FDA's quality system regulation and the EU Machinery Directive impose traceability and repeatability standards that filter which prototyping vendors qualify for medical and industrial device development. ISO 9001 and AS9100 certifications function as gatekeeping credentials for aerospace and defense prototype contracts. Stakeholders must monitor how NIST's additive manufacturing standards evolve, as qualification protocols will determine which service bureaus retain access to regulated end-use segments.
Market Dynamics
Automotive OEMs are compressing design cycles through outsourced prototype programs, forcing a structural shift from captive machine shops to distributed on-demand manufacturing networks that prioritize speed over vertical integration.
Growth Catalysts
- FDA's 510(k) pathway:Medical device manufacturers accelerate iterative prototyping to secure regulatory clearance, expanding demand for biocompatible resins and sterilizable polymers.
- Germany's industrial clusters:Tier-one suppliers co-locate prototyping capacity with assembly plants around Stuttgart and Munich, creating dense supplier ecosystems that reduce logistics friction.
- Five-axis CNC machining:Aerospace contractors specify aluminum and tool steel prototypes for functional testing, pulling work from additive systems where tolerances tighten.
Market Restraints
- Aluminum and titanium price volatility:Metal feedstock costs swing with commodity markets, squeezing margins on CNC-machined functional prototypes.
- Supply concentration in German industrial corridors:Tier-one prototyping capacity clusters in Bavaria and Baden-Württemberg, creating geographic single-point vulnerability.
- ISO 9001 and AS9100 certification timelines:Aerospace and defense contracts gatekeep on credential completion, filtering out smaller service bureaus.
Strategic Opportunities
- India's PLI scheme for manufacturing:Contract electronics and automotive component makers seek local prototyping partners to meet domestic content thresholds.
- Multi-material jetting convergence:Polymer and metal deposition systems combine in single platforms, enabling functional electronics enclosures with integrated heat dissipation.
- Silicone vacuum casting for healthcare:Ten-unit pilot runs using medical-grade elastomers address surgical tool validation gaps left by rigid thermoplastics.
Industry Challenges
- CAD-to-machine programming talent scarcity:Five-axis toolpath optimization requires specialized operators that machine shops struggle to recruit.
- NIST additive manufacturing qualification delays:Evolving standards for part repeatability slow service bureau access to regulated end-use segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Prototyping Market |
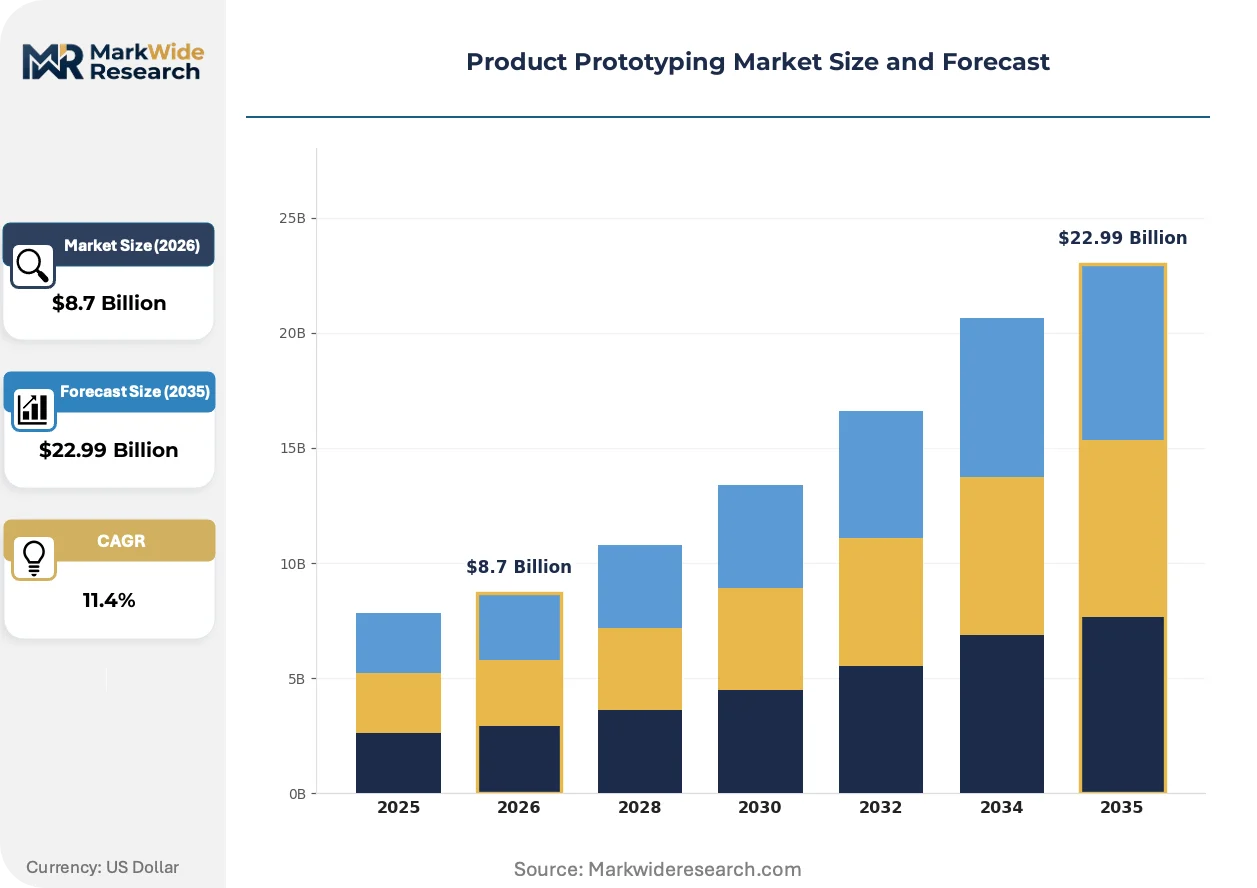
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printing, CNC Machining, Injection Molding, Vacuum Casting Material: Plastic, Metal, Composite, Resin End User: Automotive, Aerospace, Consumer Electronics, Healthcare Technology: Rapid Prototyping, Additive Manufacturing, Subtractive Manufacturing, Laser Cutting |
| Companies Covered | StudioRed, Stratasys, Protolabs, MASS Precision, 3D Systems, Xometry, Sculpteo, Formlabs, Fictiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Prototyping Market Evolving Landscape
Digital thread integration is compressing the RFQ-to-delivery window, replacing email-based quoting with automated platforms that ingest CAD files and return machined parts in days rather than weeks.
Continuous fiber reinforcement is electrifying structural prototyping by embedding carbon or glass strands within thermoplastic deposition paths. Automotive chassis teams adopt these parts for crash-test surrogates, cutting aluminum tooling costs while preserving load-path fidelity. The technology is electrifying supplier selection criteria, favoring bureaus with multi-axis robotic layup over conventional filament systems.
REACH substance restrictions are tightening material specifications for prototypes entering European industrial supply chains. ECHA's candidate list expansion forces reformulation of photopolymer resins used in conceptual mockups, pushing service bureaus toward bio-based alternatives. Medical device exporters face dual compliance overhead, reconciling REACH with FDA biocompatibility requirements.
Buyer concentration among automotive and aerospace primes is consolidating vendor relationships around performance guarantees rather than unit pricing. Tier-one suppliers now demand captive capacity reservations with SLA-backed delivery windows, displacing spot-market transactions. This pattern is most visible in Germany's supplier parks, where OEMs embed prototyping cells within final assembly footprints.
Product Prototyping Market Segmentation
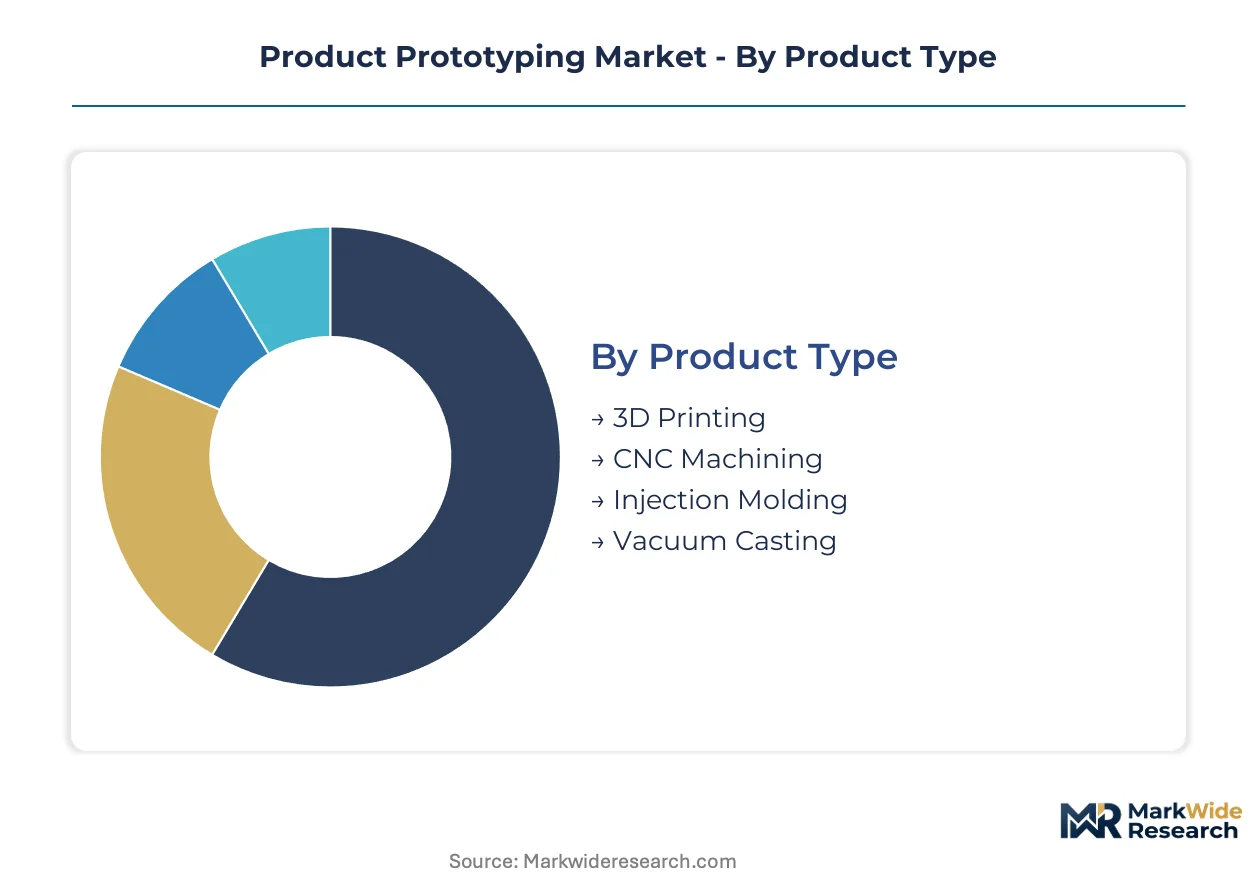
Prototyping service bureaus configure equipment portfolios around distinct process economics. Segment boundaries determine which vendors capture automotive volume contracts versus aerospace qualification work.
Product Type:
Capital intensity separates segments by equipment depreciation schedules and facility footprints.
- 3D Printing:Fused deposition systems with layer resolutions down to 0.1 mm dominate conceptual-phase geometry validation. Healthcare end users in Germany's Stuttgart corridor specify biocompatible resins for surgical tool iterations.
- CNC Machining:Five-axis centers machine aluminum and tool steel for functional testing where tolerances tighten below additive capabilities. Aerospace contractors in Munich supplier parks pull work toward subtractive systems for production-grade metal validation.
- Injection Molding:Steel tooling costs limit deployment to bridge-to-production volumes above 1,000 units.
- Vacuum Casting:Silicone molds enable ten-unit pilot runs without hard tooling investment.
CNC Machining absorbs the bulk of installed capacity; 3D Printing is expanding most quickly.
Material:
Regulatory compliance costs stratify material tiers by certification burden.
- Metal:Aluminum and titanium feedstock commands premium pricing tied to commodity volatility. Functional prototypes for automotive crash testing concentrate in Germany's industrial clusters.
- Plastic:ABS and nylon filaments serve high-volume concept modeling with fastest turnaround times. Consumer electronics teams in Bavaria specify these for ergonomic mockups ahead of mass tooling commitment.
- Composite:Continuous fiber reinforcement embeds carbon strands within thermoplastic deposition paths.
- Resin:Photopolymers face REACH reformulation pressure from ECHA candidate list expansions.
Metal captures the highest revenue per part; Plastic moves the largest unit volumes.
End User:
Procurement sophistication divides buyers by qualification requirements and contract structures.
- Automotive:OEMs compress design cycles through outsourced prototype programs with SLA-backed delivery windows. Tier-one suppliers co-locate capacity with assembly plants around Stuttgart and Munich.
- Healthcare:FDA's 510(k) pathway accelerates iterative prototyping for device clearance. Biocompatible resins and sterilizable polymers create premium material tiers within medical workflows.
- Aerospace:AS9100 certification gates access to defense prototype contracts.
- Consumer Electronics:Rapid aesthetic iteration drives demand for overnight turnaround services.
Automotive absorbs the bulk of contract value; Healthcare is climbing the fastest.
Technology:
Process maturity determines which segments qualify for regulated end-use applications.
- Additive Manufacturing:Powder bed fusion and material jetting dominate geometry-complex work where unit cost matters less than design freedom. NIST qualification protocols filter which service bureaus retain access to aerospace and medical segments.
- Subtractive Manufacturing:Milling and turning centers deliver production-grade tolerances for functional validation. Five-axis toolpath optimization requires specialized operators that machine shops struggle to recruit.
- Rapid Prototyping:Stereolithography and selective laser sintering bridge concept to functional phases.
- Laser Cutting:Sheet metal prototyping serves enclosure and chassis applications with minimal setup cost.
Subtractive Manufacturing holds the largest installed base; Additive Manufacturing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive and medical device manufacturers concentrate prototyping demand in industrial corridors where tier-one suppliers co-locate with assembly plants. Regulatory convergence around FDA and EU Machinery Directive standards shapes vendor qualification requirements across major economies.
Germany
Automotive OEMs in Stuttgart and Munich compress design cycles through outsourced prototype programs with SLA-backed delivery windows. The EU Machinery Directive imposes traceability standards that filter qualified vendors for industrial device development. Bavaria and Baden-Württemberg host dense supplier ecosystems where tier-one prototyping capacity clusters with final assembly footprints.
United States
Medical device manufacturers accelerate iterative prototyping under FDA's 510(k) pathway to secure regulatory clearance. FDA quality system regulations mandate repeatability standards that determine service bureau access to healthcare segments. Aerospace contractors in California and Texas specify AS9100-certified vendors for defense prototype contracts.
China
Contract electronics makers seek local prototyping partners to meet domestic content thresholds under industrial policy incentives. MIIT and GB standards govern equipment qualification for regulated end-use applications. Yangtze River Delta and Pearl River Delta industrial zones concentrate additive manufacturing capacity for consumer electronics validation.
India
Automotive component suppliers leverage PLI scheme incentives to establish captive prototyping capacity near assembly plants. BIS certification requirements shape material specifications for prototypes entering domestic supply chains. Maharashtra and Gujarat industrial corridors attract tier-one suppliers co-locating rapid validation facilities with manufacturing operations.
Japan
Precision equipment manufacturers specify tight-tolerance prototypes for robotics and semiconductor tooling validation. METI industrial standards and JIS certification protocols determine vendor qualification for high-reliability segments. Kanto and Kansai manufacturing belts concentrate CNC machining capacity serving automotive and electronics primes.
Product Prototyping Market Competitive Landscape
Capacity expansion dominates the current landscape as service bureaus deploy automated quoting platforms to compress RFQ-to-delivery windows. The vendor base organizes around three strategic archetypes: polymer-focused additive specialists, metals-capable CNC operators, and marketplace aggregators controlling liquidity through unified quality standards. M&A activity and geographic expansion represent the dominant competitive moves as players seek to anchor regional industrial clusters.
Among established additive manufacturing specialists, Stratasys and 3D Systems occupy positions exemplifying equipment-anchored service models. Protolabs and Xometry represent the automated-platform archetype, aggregating distributed machine shop capacity under standardized quality protocols. These four companies illustrate the structural tension between captive technology development and marketplace liquidity aggregation that defines current competitive positioning.
| Leading Market Players |
|---|
| StudioRed |
| Stratasys |
| Protolabs |
| MASS Precision |
| 3D Systems |
| Xometry |
| Sculpteo |
| Formlabs |
| Fictiv |
| Others |
Value Network & Pricing Analysis
AS9100-certified aerospace tier pricing diverges sharply from spot-market additive bureau rates, creating a bifurcation where premium validation workflows command captive capacity reservations while commodity concept modeling competes on RFQ velocity. This certification ladder shapes supply chain geography, concentrating high-margin metal prototyping in Germany's Baden-Württemberg corridor while pushing price-sensitive polymer work toward distributed on-demand networks.
Pricing Analysis
Volume-massive automotive programs compress margins through SLA-backed delivery contracts, while medical device prototyping sustains premium pricing under FDA 510(k) iteration timelines. Three-tier pricing structure across certified aerospace, qualified industrial, and unqualified concept tiers separates buyers by traceability requirements. Price differentiation hinges on ISO 9001 credential completion and biocompatible resin specification. Pricing pressure stems from aluminum commodity volatility squeezing CNC-machined functional prototypes. Consumer electronics teams exhibit highest price sensitivity, demanding overnight turnaround at spot-market rates.
Supply Chain Analysis
Dual-sourcing mandates from automotive and aerospace primes require qualified machine shop networks spanning Germany, the United States, and China to mitigate geographic concentration risk. Raw material flows draw from aluminum smelters in Norway, titanium sponge processors in Japan, and photopolymer resin formulators in the Netherlands. Single-source vulnerability concentrates in Bavaria's tier-one supplier parks, where embedded prototyping cells create captive dependency. Distribution runs through OEM-integrated supplier ecosystems rather than independent distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's quality system regulation and EU Machinery Directive traceability requirements erect a cost-of-compliance barrier that filters smaller service bureaus from regulated end-use segments, entrenching certified incumbents with sunk credential investment.
For Market Incumbents: Cement market position through captive capacity reservations in Stuttgart and Munich supplier parks, locking in SLA-backed delivery windows that displace spot-market competitors. Deepen backward integration into biocompatible resin formulation to capture premium medical device workflows. Threat from automated quoting platforms demands continuous investment in digital thread integration to match Protolabs and Xometry velocity. For New Entrants and Emerging Players: Mid-tier automotive suppliers in India's Maharashtra and Gujarat corridors present an underserved buyer archetype seeking local prototyping partners under PLI scheme domestic content thresholds. Target silicone vacuum casting for ten-unit healthcare pilot runs, a segment neglected by rigid thermoplastic-focused incumbents. Go-to-market angle: multi-material jetting convergence platforms combining polymer and metal deposition for functional electronics enclosures. For Investors and Strategic Acquirers: Re-rating potential sits with AS9100-certified CNC operators given defense procurement acceleration and aerospace contractor vendor consolidation. Long-term viability favors bureaus with geographic diversification across German industrial clusters and US medical device corridors. Signal to watch: NIST additive manufacturing qualification protocol finalization, which will determine service bureau access to regulated aerospace and medical segments.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Unlocks defense prototype contracts from Boeing and Lockheed Martin procurement teams. |
| Biocompatible Resin Formulation | Captures FDA 510(k) iteration workflows from Medtronic and Boston Scientific device pipelines. |
| Automated Quoting Platform Deployment | Compresses RFQ-to-delivery windows to match Protolabs velocity in consumer electronics. |
| German Supplier Park Co-location | Embeds prototyping cells within BMW and Mercedes-Benz final assembly footprints. |
| Multi-material Jetting Convergence | Enables functional electronics enclosures with integrated heat dissipation for automotive Tier 1s. |
Research Methodology
Multi-period observation of prototyping equipment deployment, certification completion timelines, and OEM outsourcing contract structures anchored the trend analysis, supplemented by interviews with additive manufacturing service bureau operators, CNC machining center managers, automotive Tier 1 procurement directors, medical device regulatory affairs leads, and aerospace supplier quality engineers. Secondary validation drew from FDA 510(k) submission databases, EU Machinery Directive implementation guidance, NIST additive manufacturing standards documentation, and customs data on aluminum and titanium feedstock trade flows. Bottom-up vendor capacity estimates triangulated against top-down end-use demand projections.
Input-output matrices mapped equipment utilization rates, material cost pass-through coefficients, and certification-driven price premiums across segmentation dimensions including process technology, material tier, end-use industry, and geographic regulatory cluster. CAGRs were derived from regression analysis against automotive design cycle compression rates and medical device regulatory clearance timelines. Forecast inputs incorporated NIST qualification protocol evolution scenarios and REACH substance restriction implementation schedules.
Revisions become necessary when NIST additive manufacturing standards materialize ahead of or behind projected timelines, when aluminum and titanium commodity volatility exceeds historical bands, or when FDA 510(k) pathway modifications alter medical device iteration economics. Deviation in German automotive OEM outsourcing intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
UX Services Market
Digital Solutions
Bahrain ICT Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Cheque Scanner Market