
 Function As a Service (Faas) Market | 2026-2036
Function As a Service (Faas) Market Size, Share, and Industry Trends Forecast 2026-2036
Function As a Service (Faas) Market Insights
GDPR is recalibrating how European enterprises evaluate cloud-native compute platforms, forcing providers to certify data residency and processing transparency. Amazon Web Services leverages its Lambda platform to anchor serverless market presence across regulated industries. Microsoft competes through Azure Functions' deep integration with enterprise identity and compliance stacks. Google differentiates via Cloud Run's container-native flexibility, appealing to developers seeking portability between on-premise and public environments.
Function As a Service (FaaS) is a cloud computing model where providers execute discrete code functions in ephemeral, auto-scaling containers triggered by events or API calls, eliminating server management overhead for users. The architecture abstracts infrastructure provisioning, charging only for actual execution time measured in milliseconds, which drives cost efficiency for variable workloads. Public Cloud deployment dominates current consumption patterns due to minimal upfront investment and elastic capacity, while Hybrid Cloud configurations are attracting financial and healthcare sectors with strict data sovereignty requirements. Event-Driven functions lead transaction volumes as organizations replace polling-based systems with reactive architectures for IoT telemetry and payment processing.
The EU AI Act and GDPR jointly shape European FaaS demand by mandating algorithmic accountability and data processing logs for automated decision systems. The US Federal Risk and Authorization Management Program (FedRAMP) controls market access for government workloads, filtering providers by security certification depth. India's Digital Personal Data Protection Act is emerging as a parallel compliance benchmark for Asian deployments. Stakeholders must monitor how sovereignty requirements fragment previously unified cloud strategies into jurisdiction-specific infrastructure decisions.
Market Dynamics
Event-driven architecture migration is compressing server provisioning cycles from weeks to milliseconds, forcing infrastructure providers to reprice compute around execution granularity rather than reserved capacity.
Growth Catalysts
- EU AI Act compliance:Automated decision systems in financial services now require auditable execution logs, pushing banks toward FaaS platforms with built-in observability chains.
- Automotive telemetry pipelines:German OEMs are replacing batch ETL with real-time function chains for connected vehicle data, creating demand spikes in industrial cloud regions.
- Edge-to-core synchronization:5G rollouts in manufacturing clusters are triggering function execution at network boundaries, requiring ultra-low latency container spin-up.
Market Restraints
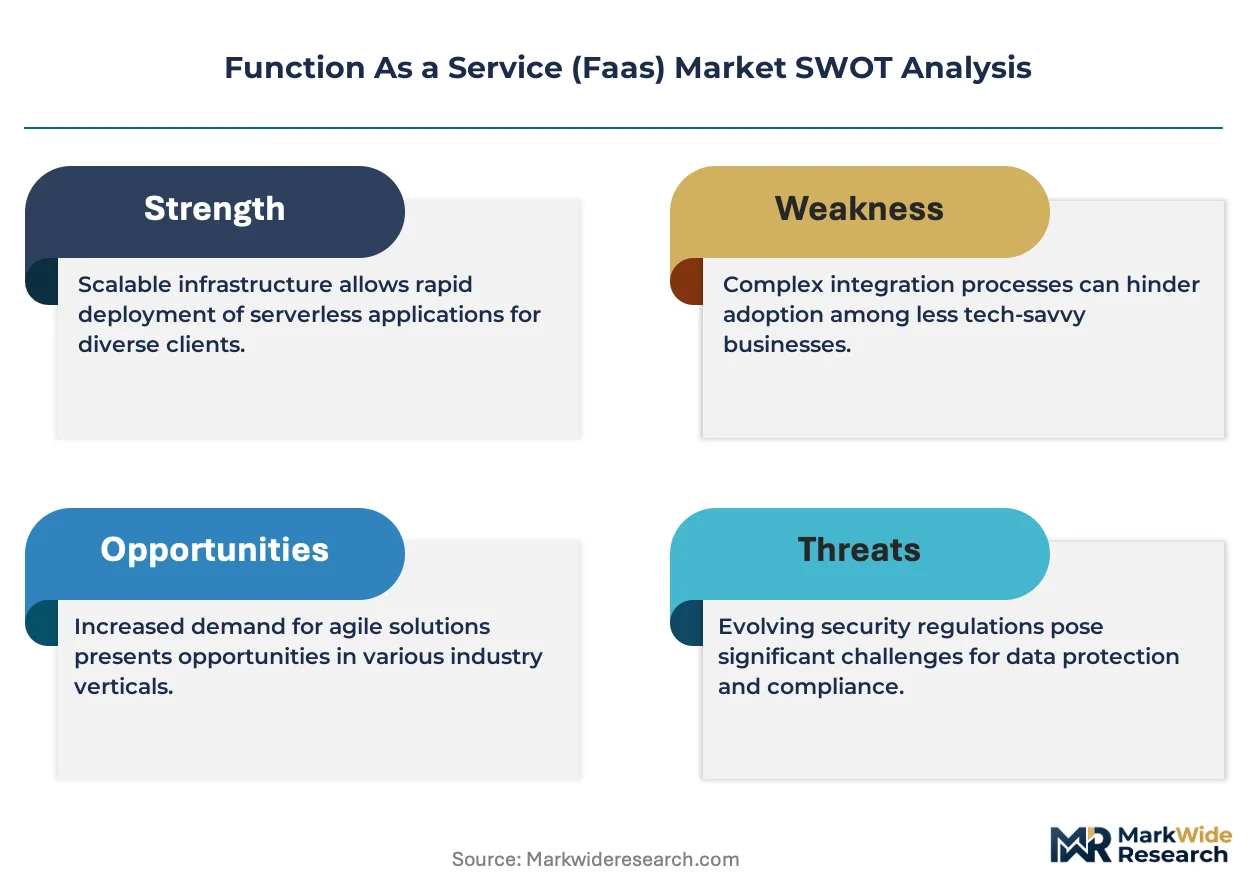
- Cold start latency:Python and Java runtime initialization delays persist above 100ms in resource-constrained regions, degrading user experience for synchronous API workloads.
- Vendor runtime lock-in:Proprietary extension APIs across AWS Lambda, Azure Functions, and Google Cloud Run fragment portability, raising switching costs for multi-cloud strategies.
- Observability cost inflation:Distributed tracing and log aggregation for ephemeral functions can exceed execution costs by 4-7x at scale, eroding the pay-per-use value proposition.
Strategic Opportunities
- India's Digital Personal Data Protection Act:Data localization mandates are creating demand for sovereign FaaS infrastructure, with domestic cloud providers capturing regulated workloads.
- Healthcare IoT convergence:Remote patient monitoring devices paired with HIPAA-compliant function execution are opening clinical trial automation and real-time adverse event detection.
- WebAssembly runtime standardization:WASI interfaces enabling language-agnostic, near-native performance functions are attracting high-frequency trading and gaming workloads.
Industry Challenges
- Serverless-native security expertise:Traditional perimeter defense models fail against ephemeral attack surfaces, forcing enterprises to retrain SOC teams on identity-centric threat detection.
- Stateful workload orchestration:Function choreography patterns struggle with long-running transactions, requiring complex saga implementations that reintroduce operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Function As a Service (Faas) Market |
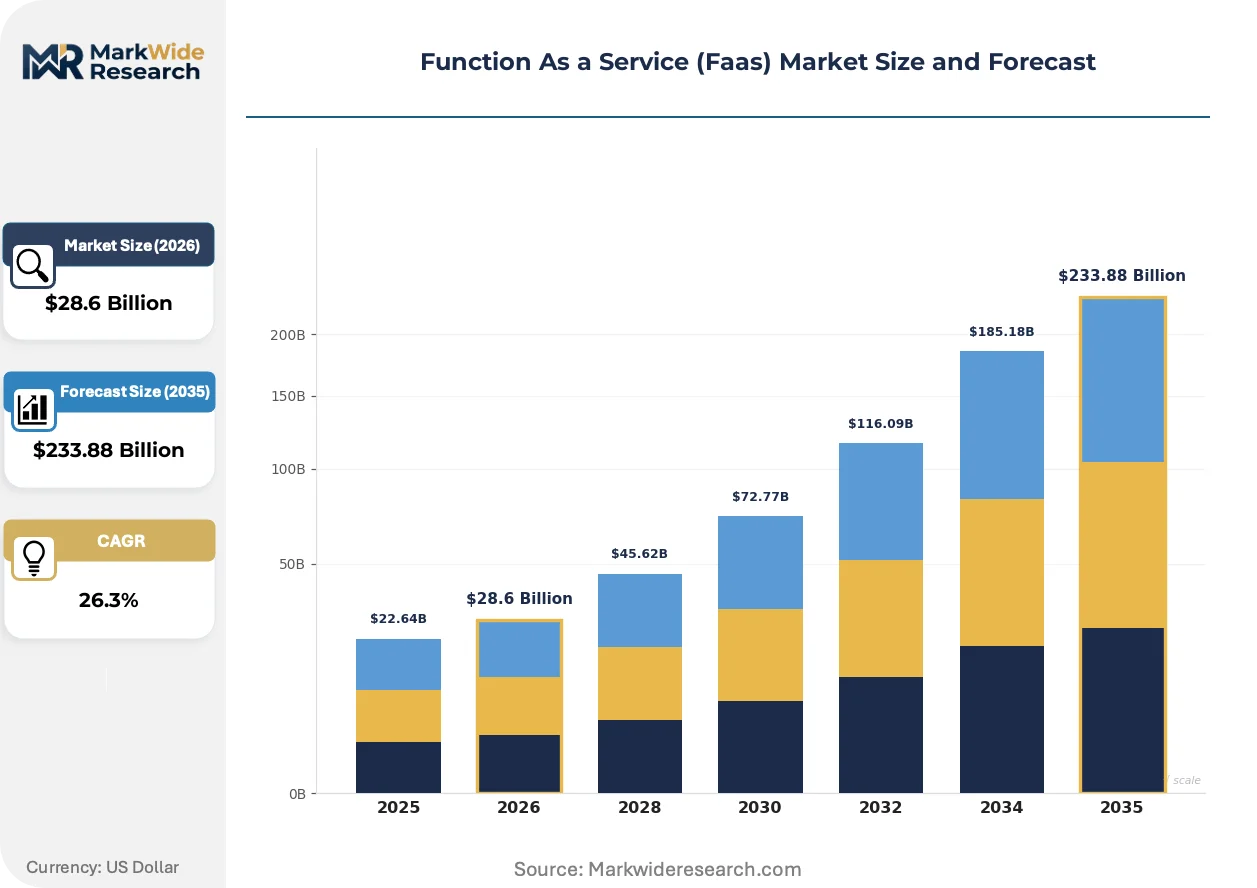
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $233.88 Billion |
| CAGR (2026 – 2036) | 26.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Function Type: Event-Driven, API-Triggered, Scheduled, Stream Processing Service Tier: Free Tier, Pay-As-You-Go, Subscriptions, Enterprise Solutions End User: Startups, Enterprises, Developers, Government |
| Companies Covered | Amazon Web Services, Microsoft, Google, IBM, Oracle, SAP SE, Alibaba Cloud, Tencent Cloud, Red Hat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Function As a Service (Faas) Market Trends and Innovations
Compute abstraction is racing toward zero-infrastructure visibility, with developers demanding seamless portability across edge, on-premise, and hyperscale environments without rewriting deployment logic.
WebAssembly is rewriting how functions execute at the edge. The binary instruction format enables sandboxed, near-native performance across heterogeneous hardware. Telecommunications providers embedding WASM runtimes in 5G base stations are cutting latency for industrial automation use cases. This runtime portability is compressing the traditional container orchestration stack into single-binary deployments.
The EU AI Act's algorithmic accountability requirements are forcing FaaS providers to embed provenance tracking and decision logging into execution environments. Automated credit scoring and insurance underwriting functions now carry immutable audit trails from input to output. Financial services firms in Frankfurt and Amsterdam are selecting platforms with native compliance instrumentation over generic alternatives.
Consumption-based procurement is displacing annual cloud commitments in enterprise software buying. Infrastructure teams are negotiating function-execution tiers with granular burst pricing rather than reserved instance contracts. This shift is most visible among SaaS vendors in the Bay Area and Bangalore, where product engineering teams directly control infrastructure spend through developer-centric billing dashboards.
Function As a Service (Faas) Market Segmentation
Segmentation in the Function As a Service market reveals how workload characteristics dictate infrastructure procurement patterns. Deployment topology, execution triggers, commercial terms, and buyer sophistication each create distinct vendor selection criteria and margin profiles.
Deployment Model:
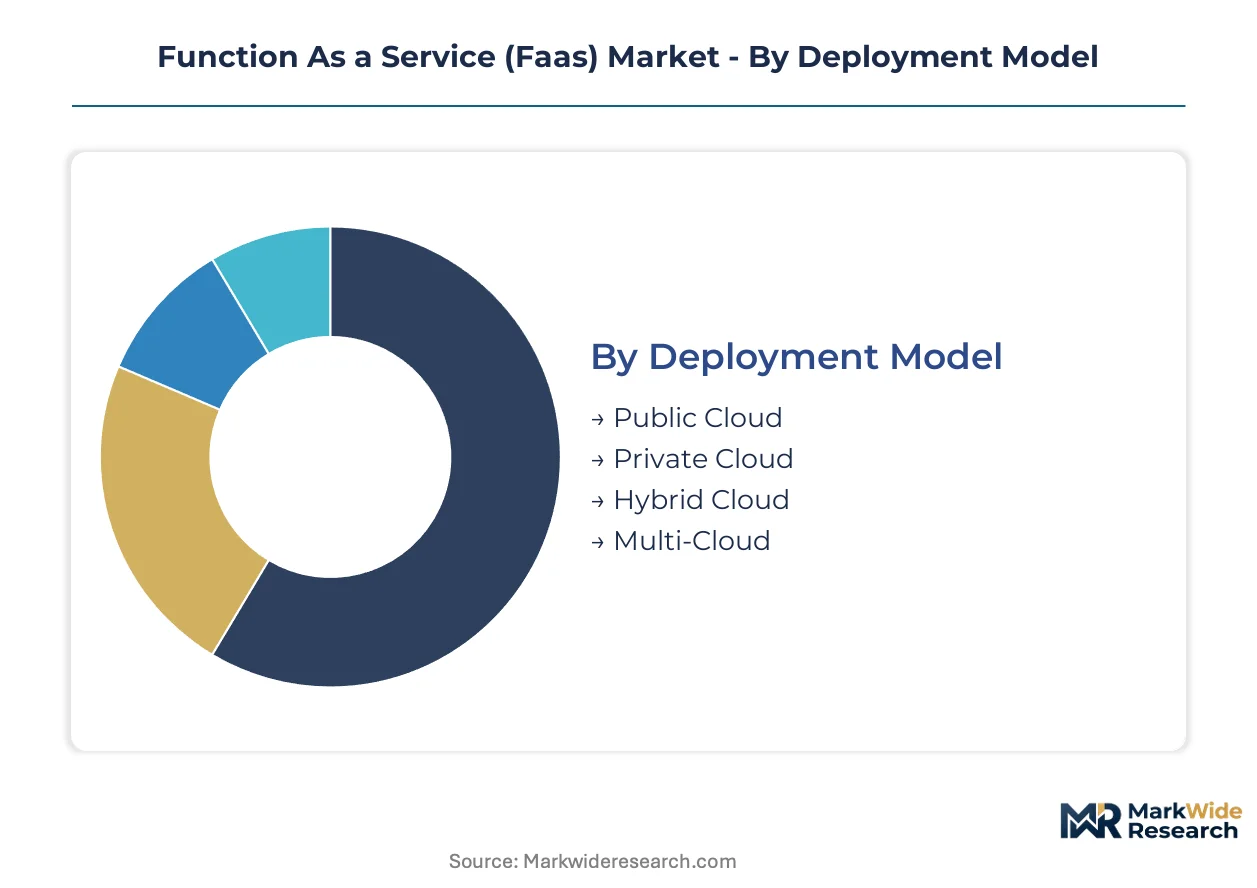
Public Cloud deployments require no specialized certifications beyond standard SOC 2 and ISO 27001, while Hybrid and Private Cloud configurations demand FedRAMP, GDPR, and sector-specific attestations that extend sales cycles.
- Public Cloud:Providers execute functions on shared infrastructure with millisecond provisioning and elastic scaling. German automotive OEMs and Bangalore SaaS vendors concentrate demand here for variable workloads with unpredictable traffic patterns.
- Hybrid Cloud:Workloads split between on-premise and public execution environments based on data sensitivity. Financial services firms in Frankfurt and healthcare systems in Amsterdam select this model to satisfy GDPR data residency mandates while retaining burst capacity.
- Private Cloud:Dedicated infrastructure isolates execution environments for single-tenant compliance. Defense contractors and classified government workloads in the US require this topology for FedRAMP High authorization.
- Multi-Cloud:Functions deploy across AWS, Azure, and Google Cloud simultaneously to mitigate vendor lock-in. Large enterprises with sophisticated platform engineering teams drive adoption to optimize regional latency and pricing arbitrage.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest as sovereignty requirements harden across European and Asian jurisdictions.
Function Type:
Execution patterns separate high-frequency micro-transactions from batch workloads, with pricing models and infrastructure optimization diverging sharply across these patterns.
- Event-Driven:Functions trigger automatically from IoT telemetry, payment gateways, or message queues without polling overhead. Connected vehicle pipelines from Munich to Stuttgart and real-time fraud detection in Singapore concentrate demand here.
- API-Triggered:Synchronous HTTP requests invoke functions for user-facing applications where sub-100ms response times matter. Mobile backends and e-commerce checkout flows in London and New York represent core consumption.
- Scheduled:Time-based cron expressions execute functions at fixed intervals for report generation and data synchronization. Legacy batch migration projects favor this pattern during mainframe modernization.
- Stream Processing:Continuous data flows from Kafka or Kinesis drive function chains for real-time analytics. High-frequency trading platforms in Chicago and Tokyo require this topology for market data ingestion.
Event-Driven functions dominate transaction volumes, while Stream Processing gains share fastest as 5G telemetry and industrial IoT deployments accelerate.
Service Tier:
Commercial structures align buyer sophistication with operational support depth, from individual experimentation to mission-critical production guarantees.
- Pay-As-You-Go:Per-execution billing measured in milliseconds eliminates upfront commitment. Startups in Tel Aviv and product engineering teams at mid-market SaaS vendors prefer this for unpredictable development cycles.
- Enterprise Solutions:Custom contracts bundle dedicated support, reserved concurrency, and compliance attestations. Regulated banks in Zurich and pharmaceutical manufacturers in Basel require these terms for production workloads.
- Free Tier:Limited monthly execution quotas enable developer experimentation and proof-of-concept validation. Individual developers and university research projects drive consumption with minimal revenue contribution.
- Subscriptions:Fixed monthly fees cover predictable baseline execution with overage rates for burst traffic. Mature SaaS vendors with stable usage patterns select this to simplify forecasting.
Pay-As-You-Go commands the highest transaction volume, with Enterprise Solutions expanding most quickly as regulated industries migrate core systems to serverless architectures.
End User:
Buyer type determines procurement authority, technical requirements, and price sensitivity across the adoption spectrum.
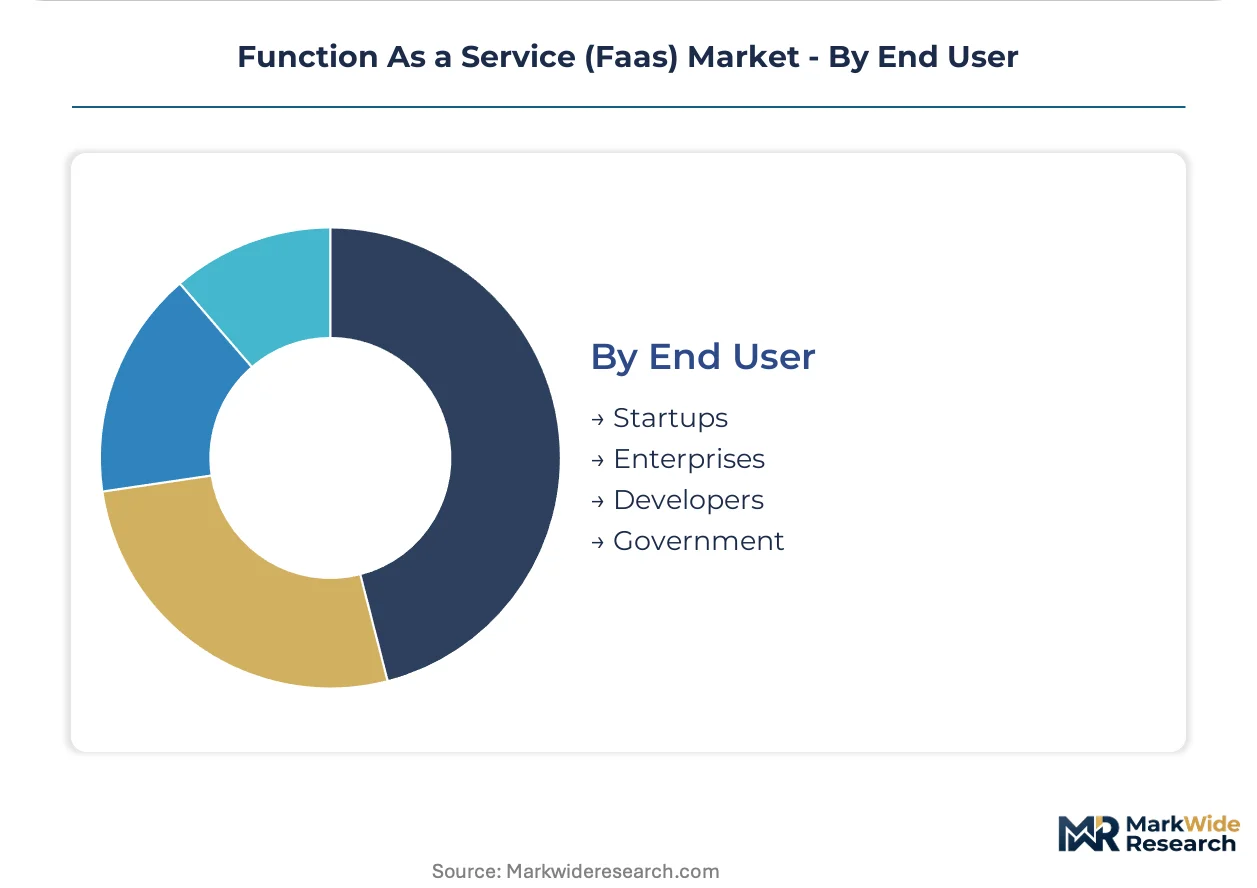
- Enterprises:Centralized cloud centers of excellence negotiate enterprise agreements with governance guardrails. Fortune 500 manufacturers in Detroit and energy majors in Houston drive six and seven-figure annual commitments.
- Developers:Individual practitioners and small teams self-provision through credit-card billing with minimal organizational oversight. Independent software vendors and digital agencies in Lisbon and Warsaw represent this segment.
- Startups:Venture-backed companies prioritize speed-to-market over infrastructure optimization until Series B scale. Fintech founders in Lagos and SaaS builders in Jakarta cluster here during pre-revenue phases.
- Government:Public sector entities require FedRAMP, IRAP, or equivalent national certifications with extended procurement timelines. Federal agencies in Washington DC and state healthcare exchanges mandate these controls.
Enterprises generate the largest revenue concentration, with Government climbing fastest as sovereign cloud mandates expand across NATO and Five Eyes jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Serverless computing originated in Silicon Valley's hyperscale data centers during the mid-2010s, with AWS Lambda's 2014 launch establishing the architectural template that European and Asian markets later adapted to local regulatory constraints.
United States
Financial services firms in Manhattan and Chicago drive enterprise FaaS consumption for real-time payment processing and algorithmic trading systems. FedRAMP authorization requirements filter government workload access to certified providers. The San Francisco Bay Area hosts the densest concentration of SaaS vendors negotiating consumption-based procurement contracts.
Germany
Automotive OEMs in Stuttgart and Munich are migrating legacy manufacturing workloads to event-driven architectures for connected vehicle telemetry. The EU AI Act mandates auditable execution logs for automated credit scoring functions deployed by Frankfurt-based banks. Bavaria's industrial cloud regions report the steepest demand growth for sovereign-compliant serverless infrastructure.
United Kingdom
London's fintech cluster consumes API-triggered functions for mobile payment backends requiring sub-100 millisecond response times. GDPR data residency requirements push healthcare systems in Cambridge and Oxford toward hybrid cloud configurations. The Financial Conduct Authority's operational resilience rules accelerate mainframe modernization projects using scheduled function patterns.
India
Bangalore's SaaS product engineering teams directly control infrastructure spend through developer-centric billing dashboards. The Digital Personal Data Protection Act creates demand for sovereign FaaS infrastructure with domestic cloud providers capturing regulated workloads. Mumbai's banking sector deploys event-driven functions for real-time fraud detection across UPI transaction volumes.
Japan
Tokyo's manufacturing conglomerates embed serverless functions in 5G-enabled industrial automation systems. METI's data governance guidelines influence procurement criteria for financial services firms modernizing core banking platforms. Osaka's logistics providers leverage stream processing functions for supply chain telemetry across the Kansai industrial corridor.
Function As a Service (Faas) Market Competitive Landscape
The competitive structure tilts toward hyperscale cloud providers with vertically integrated infrastructure stacks. Three global technology conglomerates dominate transaction volumes through serverless platforms tightly coupled to broader cloud service ecosystems. Strategic differentiation centers on runtime portability, compliance instrumentation depth, and edge-to-core synchronization capabilities. Market participants pursue geographic expansion through sovereign cloud partnerships and technology licensing arrangements with telecommunications operators.
Among hyperscale providers, Amazon Web Services, Microsoft, and Google occupy positions representing distinct architectural philosophies. AWS anchors the event-driven compute segment with Lambda's first-mover integration across its service mesh. Microsoft exemplifies enterprise identity-centric positioning through Azure Functions' deep Active Directory and compliance stack embedding. Google sits within the container-native flexibility tier, appealing to developer segments prioritizing portability between on-premise Kubernetes and public cloud execution environments.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Oracle |
| SAP SE |
| Alibaba Cloud |
| Tencent Cloud |
| Red Hat |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud providers with vertically integrated infrastructure stacks anchor supply-side concentration, translating compute scarcity into tiered execution pricing that segments buyers by compliance depth and burst capacity requirements.
Pricing Analysis
Millisecond-granularity billing measured in gigabyte-seconds dominates commercial structures, with price differentiation resting on reserved concurrency guarantees and FedRAMP certification tiers. AWS Lambda, Azure Functions, and Google Cloud Run compress spot pricing for variable workloads while extracting premiums for dedicated execution environments. Cost inflation in distributed tracing and observability tooling is intensifying total cost of ownership calculations. Developer-led startups exhibit highest price sensitivity, whereas Frankfurt-based banks and defense contractors absorb premium tiers for immutable audit trails.
Supply Chain Analysis
FedRAMP authorization and GDPR data residency certifications gate supplier participation, filtering execution infrastructure to providers with sovereign cloud partnerships in Germany, India, and Japan. Hyperscale data center construction draws from specialized cooling systems, custom ARM-based silicon, and fiber interconnects. Single-source vulnerability in cloud region concentration threatens continuity for latency-sensitive automotive telemetry pipelines. Distribution runs through direct enterprise sales teams and self-service developer portals with usage-based billing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Function As a Service procurement functions as a geographic-arbitrage play, with EU AI Act compliance costs in Frankfurt and Amsterdam running substantially above Bangalore and Singapore deployment economics.
For Market Incumbents: Deploy sovereign cloud partnerships as the primary defensive lever. AWS, Microsoft, and Google must extend FedRAMP High certifications into classified workloads while building domestic infrastructure in India under the Digital Personal Data Protection Act. Cold start latency below 100 milliseconds represents the critical technical moat against container-native challengers. Certification depth in algorithmic accountability instrumentation separates winners in financial services procurement. For New Entrants and Emerging Players: Developer-centric billing dashboards and WebAssembly runtime standardization offer the most penetrable entry vectors. Target India's sovereign infrastructure gap with domestic cloud providers capturing regulated workloads from Mumbai banks. Edge-to-core synchronization for 5G manufacturing clusters in Stuttgart and Osaka presents whitespace with minimal hyperscaler penetration. Lead with consumption-based procurement tools that displace annual cloud commitments. For Investors and Strategic Acquirers: Telecommunications operators are the most active acquirer in this space, embedding serverless runtimes in 5G base stations for industrial automation. Long-term viability hinges on runtime portability that transcends vendor lock-in. Acquisition targets should display WebAssembly expertise and sovereign cloud partnerships. Watch for cold start latency breakthroughs below 50 milliseconds as inflection indicators for synchronous API workload capture.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Domestic providers in India and Germany capture regulated workloads under data localization mandates. |
| WebAssembly Runtime Integration | Near-native performance functions attract high-frequency trading platforms in Chicago and Tokyo. |
| Algorithmic Accountability Instrumentation | Immutable audit trails satisfy EU AI Act requirements for Frankfurt-based automated credit scoring. |
| Edge Infrastructure Deployment | 5G base station embedding cuts latency for Stuttgart automotive telemetry pipelines. |
| Consumption-Based Procurement Platform | Developer-centric billing dashboards displace reserved instance contracts among Bangalore SaaS vendors. |
Research Methodology
Direct dialogue with platform engineering directors, cloud procurement officers, regulatory compliance leads, and automotive telemetry architects grounded qualitative findings. Secondary validation drew from hyperscaler capex disclosures, SEC 10-K infrastructure segment filings, EU AI Act implementation guidance, and FedRAMP authorization databases. Bottom-up execution volume estimates triangulated against top-down cloud services revenue attribution.
Segmentation outputs across deployment topology, function type, service tier, and end user category structured the analytical framework over the projection horizon. CAGRs derived from execution volume trajectories in event-driven and stream processing workloads, cross-referenced with sovereign cloud infrastructure buildout timelines and 5G manufacturing cluster activation schedules.
Regulatory enforcement variance, cold start latency breakthroughs, and sovereign cloud partnership failures are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in EU AI Act algorithmic accountability implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
G2P Systems Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Social Networking App Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
North America API Management Market
Digital Solutions
AI In Packaging Design Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Global DDI Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
Cloud Based Manufacturing Market