
 Latin America and Europe Digital Signature Market | 2026-2036
Latin America and Europe Digital Signature Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America and Europe Digital Signature Market Foresight
Channel partnerships between software integrators and local certification authorities is reconfiguring how digital signature platforms penetrate mid-market enterprises across Latin America and Europe. Thales Group leverages its hardware security module expertise to anchor qualified trust service deployments in regulated European sectors. DocuSign Inc. competes through extensive API integrations with enterprise productivity suites, while D4Sign specializes in localized compliance workflows for Brazilian notarial requirements.
A digital signature constitutes a cryptographically secured electronic seal bound to signer identity through public-key infrastructure, typically employing X.509 certificates with SHA-256 hashing to ensure non-repudiation and document integrity. Cloud-based deployment leads segment momentum as organizations abandon on-premises hardware maintenance, though hybrid architectures persist where data sovereignty rules apply. Certificate-based authentication dominates enterprise procurement for its audit trail reliability, while biometric methods are gaining traction in mobile-first Latin American banking applications where USB token distribution remains logistically constrained.
eIDAS regulation across European Union member states mandates qualified electronic signatures for cross-border legal validity, while Brazil's ICP-Brasil framework enforces hierarchical certificate authority accreditation for government contracting. Spain's national mint operates as a supervised trust service provider under ETSI standards, reinforcing technical interoperability demands that shape vendor certification roadmaps. Stakeholders must monitor evolving eIDAS 2.0 wallet specifications and Brazil's LGPD data localization intersecting with signature custody requirements.
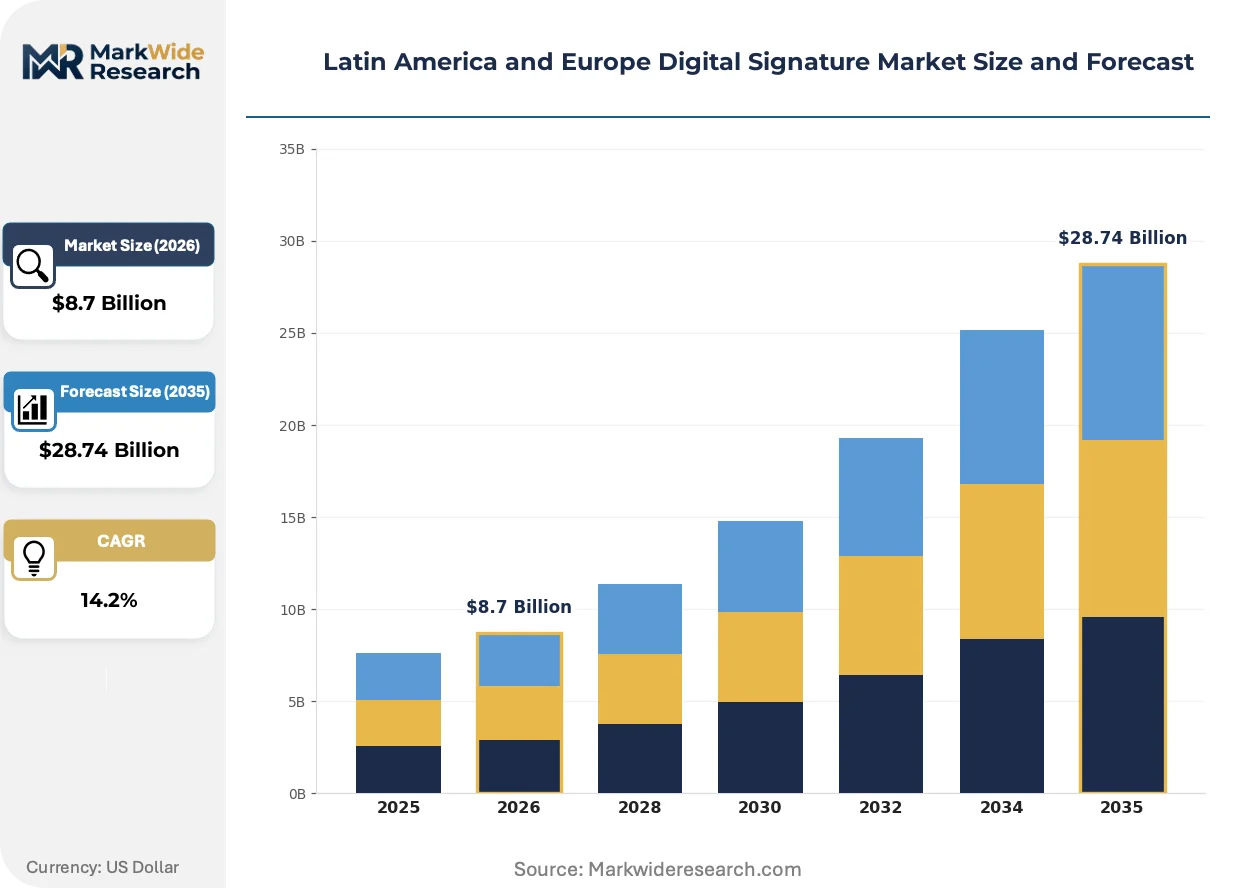
Market Dynamics
Cloud-based signing infrastructure is compressing deployment timelines for mid-market enterprises across Iberian financial hubs and Brazilian fintech corridors, forcing legacy on-premises hardware vendors to reconfigure service architectures or exit SME segments entirely.
Growth Catalysts
- ICP-Brasil framework mandates:Brazil's hierarchical certificate authority accreditation requirements for government contracting create guaranteed procurement volumes for qualified trust service providers serving public-sector workflows.
- Mobile-first banking adoption:Latin American financial institutions are bypassing USB token distribution through biometric authentication methods that reduce logistical friction in remote customer onboarding.
- eIDAS cross-border validity:The EU regulation's qualified electronic signature recognition across member states generates compliance-driven demand for interoperable signing platforms in cross-border contract execution.
Market Restraints
- Data sovereignty compliance costs:Brazil's LGPD localization requirements intersecting with signature custody obligations force cloud providers to maintain separate infrastructure instances, elevating operational expenditure.
- Certificate authority concentration:Spain's national mint operates as a supervised trust service provider under ETSI standards, creating single-point dependencies for qualified signature issuance in Iberian markets.
- Legacy system integration friction:On-premises hardware security module architectures persist in regulated European sectors where audit trail reliability requirements exceed current cloud-native capabilities.
Strategic Opportunities
- eIDAS 2.0 wallet specifications:The evolving European digital identity framework creates white space for wallet-integrated signing solutions that displace standalone platform deployments.
- Notarial workflow digitization:Brazilian localized compliance requirements for notarial processes remain underpenetrated by standardized global platforms, favoring specialized regional providers.
- API-native distribution:Enterprise productivity suite integrations are emerging as a channel innovation that compresses procurement cycles for mid-market software buyers.
Industry Challenges
- PKI specialist scarcity:Shortages of cryptographers and public-key infrastructure engineers are extending implementation timelines for qualified trust service deployments.
- ETSI certification latency:Vendor roadmaps face compression from extended conformance testing periods required for supervised provider status under European technical standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America and Europe Digital Signature Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Managed Service Sector: Banking, Healthcare, Education, Real Estate Authentication Method: USB Token, Certificate-based, Biometric, One-time Password End User: Small Enterprises, Large Corporations, Government, Non-Profit Organizations |
| Companies Covered | Thales Group, D4Sign, DocuSign Inc., Ascertia, Zoho, Adobe Systems Inc., Entrust, PandaDoc Inc., OneSpan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America and Europe Digital Signature Market Shifts & Advancements
Signing technology is fragmenting across deployment models as data sovereignty rules and mobile accessibility requirements pull enterprise architectures in opposing directions.
Biometric authentication methods are migrating from experimental pilots to production systems in Latin American retail banking. Brazilian neobanks deploy facial recognition and voiceprint verification for high-volume consumer onboarding where physical token distribution remains economically unviable. This migration from certificate-based to behavioral biometric trust anchors is compressing customer acquisition costs while elevating fraud detection integration requirements.
eIDAS 2.0 wallet specifications are reshaping European digital identity infrastructure. The framework's European Digital Identity Wallet mandates will require qualified trust service providers to rearchitect signature issuance around wallet-native key custody rather than centralized certificate authority models. Financial services and healthcare sectors face the most extensive compliance recertification cycles as member states transpose the directive into national law.
Mid-market procurement patterns are rotating toward consumption-based licensing for signing volumes. Enterprise buyers in Spanish manufacturing and Brazilian logistics sectors are displacing perpetual seat licenses with transaction-metered contracts that align costs to actual document execution frequency. This behavioral shift is most visible in organizations with seasonal contract cycles or project-based workforce scaling.
Latin America and Europe Digital Signature Market Segmentation
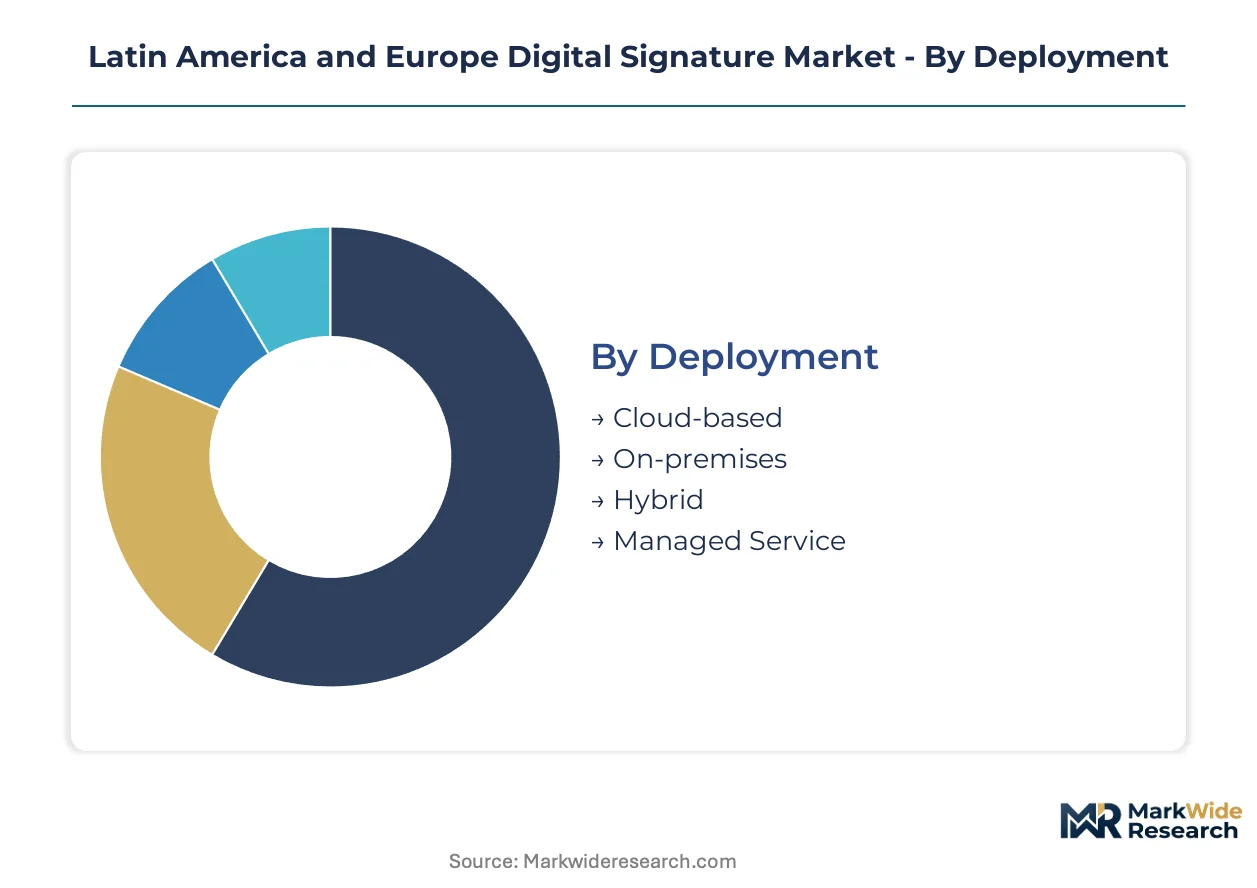
Digital signature procurement patterns diverge sharply across deployment architectures, regulatory environments, and organizational scale. Understanding these fault lines reveals where platform vendors must reconfigure pricing, compliance certification, and integration depth to capture wallet share.
Deployment:
Cost tier segmentation separates organizations by infrastructure ownership preference and operational expenditure tolerance.
- Cloud-based:Multi-tenant SaaS architectures eliminate hardware maintenance burdens while enabling elastic scaling for seasonal contract volumes. Brazilian fintech corridors and Iberian financial services hubs are absorbing these platforms at scale as data sovereignty solutions mature.
- On-premises:Dedicated hardware security modules and localized certificate storage persist in regulated European sectors where audit trail reliability requirements exceed current cloud-native capabilities. Spain's national mint and supervised trust service providers anchor this segment.
- Hybrid:Split architectures partition sensitive key generation on-site while pushing document workflow orchestration to cloud layers. Organizations with LGPD localization obligations in Brazil favor this model for signature custody compliance.
- Managed Service:Third-party operated infrastructure with dedicated tenancy addresses mid-market enterprises lacking PKI specialist resources. Channel partnerships between software integrators and local certification authorities are expanding this tier.
Cloud-based deployments command the established base. The steepest expansion runs through hybrid architectures as data sovereignty rules harden.
Sector:
Application-driven demand concentrates where regulatory mandates intersect with high-volume document execution workflows.
- Banking:Mobile-first consumer onboarding and cross-border trade finance documentation drive biometric authentication adoption. Brazilian neobanks deploy facial recognition and voiceprint verification to bypass USB token distribution logistics.
- Healthcare:Patient consent management and clinical trial documentation require qualified electronic signatures under eIDAS and ICP-Brasil frameworks. Spain's ETSI-certified trust service providers dominate procurement in this segment.
- Education:Credential verification and enrollment agreements generate moderate volumes with seasonal concentration patterns. Transaction-metered licensing is displacing perpetual seat contracts in this sector.
- Real Estate:Property transfer notarization and lease execution remain partially paper-dependent due to localized compliance requirements. Brazilian notarial workflow digitization lags standardized global platform penetration.
Banking commands the established base. The steepest expansion runs through healthcare as eIDAS 2.0 wallet specifications reshape digital identity infrastructure.
Authentication Method:
Security posture and user experience trade-offs segment procurement across cryptographic assurance levels.
- USB Token:Physical hardware storing private keys delivers maximum non-repudiation assurance for qualified electronic signatures. Distribution economics constrain adoption in remote Latin American markets.
- Certificate-based:X.509 credentials with SHA-256 hashing anchor enterprise audit trail reliability. Thales Group leverages hardware security module expertise to anchor deployments in regulated European sectors.
- Biometric:Facial recognition and voiceprint verification compress customer acquisition costs in mobile-first banking applications. Behavioral trust anchors are migrating from experimental pilots to production systems.
- One-time Password:SMS or app-delivered codes provide lightweight authentication for low-risk document categories. Regulatory acceptance varies across eIDAS member states and ICP-Brasil accreditation tiers.
Certificate-based methods command the established base. The steepest expansion runs through biometric authentication as mobile-first banking adoption accelerates.
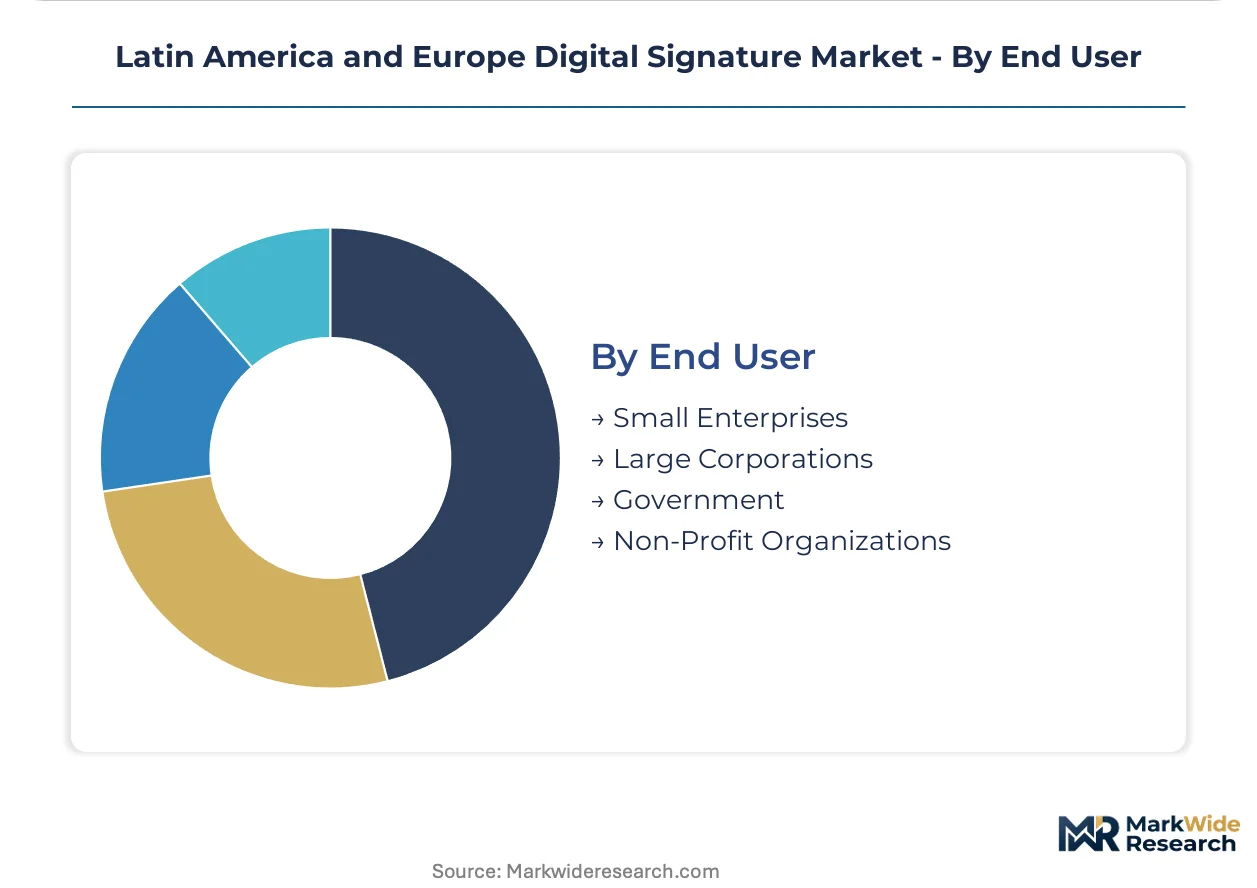
End User:
Customer type segmentation reflects organizational scale, procurement sophistication, and compliance obligation intensity.
- Small Enterprises:Limited IT resources and seasonal workforce scaling favor consumption-based licensing and API-native distribution through productivity suite integrations.
- Large Corporations:Complex multi-jurisdictional operations require qualified trust service providers with ETSI certification and cross-border eIDAS validity guarantees.
- Government:ICP-Brasil framework mandates create guaranteed procurement volumes for hierarchical certificate authority accreditation in Brazilian public-sector workflows.
- Non-Profit Organizations:Grant compliance and donor documentation generate modest signing volumes with high price sensitivity and simplified authentication requirements.
Large corporations command the established base. The steepest expansion runs through small enterprises as API-native distribution compresses procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lisbon-Madrid digital corridor anchors Iberian cross-border document flows, while submarine fiber links between São Paulo and Lisbon underpin transatlantic trust service interoperability for qualified electronic signatures.
Brazil
Brazilian fintech corridors in São Paulo and Rio de Janeiro drive cloud-based signing platform absorption at scale. The ICP-Brasil framework mandates hierarchical certificate authority accreditation for government contracting, creating guaranteed procurement volumes for qualified trust service providers. São Paulo's neobank cluster deploys biometric authentication methods to bypass USB token distribution logistics in remote customer onboarding.
Spain
Spanish financial services hubs in Madrid and Barcelona absorb enterprise productivity suite integrations for document execution workflows. The national mint operates as a supervised trust service provider under ETSI standards, reinforcing technical interoperability demands that shape vendor certification roadmaps. Madrid anchors qualified trust service deployments for cross-border contract validity under eIDAS regulation.
Portugal
Lisbon's emerging tech ecosystem concentrates API-native distribution channels for mid-market software buyers. The country's transposition of eIDAS 2.0 wallet specifications positions it as a testbed for wallet-integrated signing solutions. Porto manufacturing clusters are rotating toward consumption-based licensing for seasonal contract volumes.
Germany
German automotive and industrial machinery sectors in Bavaria and Baden-Württemberg maintain on-premises hardware security module architectures where audit trail reliability requirements exceed cloud-native capabilities. The country's federal trust service supervision under BSI technical guidelines creates extended conformance testing periods for supervised provider status. Munich anchors hybrid deployment models partitioning sensitive key generation on-site.
France
French healthcare and financial services in Île-de-France face extensive compliance recertification cycles as eIDAS 2.0 wallet specifications reshape digital identity infrastructure. The ANSM and CNIL intersect with signature custody requirements for clinical trial documentation. Parisian enterprise buyers displace perpetual seat licenses with transaction-metered contracts aligned to actual document execution frequency.
Latin America and Europe Digital Signature Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cryptographic modules and certificate infrastructure. The vendor base stratifies across three tiers: multinational SaaS platforms with API-native distribution, regional compliance specialists with localized certification authority relationships, and hardware security module fabricators anchoring qualified trust service deployments. Two dominant competitive moves are reshaping positioning: strategic partnerships between software integrators and local certification authorities, and portfolio diversification into wallet-integrated signing solutions ahead of eIDAS 2.0 mandates.
Among France-based diversified technology groups, Thales Group exemplifies the hardware security module archetype anchoring qualified trust service deployments in regulated European sectors. DocuSign Inc. and D4Sign represent contrasting platform strategies—the former occupying a position through extensive API integrations with enterprise productivity suites, the latter exemplifying regional specialization in localized compliance workflows for Brazilian notarial requirements.
| Leading Market Players |
|---|
| Thales Group |
| D4Sign |
| DocuSign Inc. |
| Ascertia |
| Zoho |
| Adobe Systems Inc. |
| Entrust |
| PandaDoc Inc. |
| OneSpan |
| Others |
Supply & Pricing Matrix
The Lisbon-São Paulo submarine fiber corridor carries asymmetric cost dynamics that amplify pricing power for ETSI-certified trust service providers while compressing margins for cloud-native platform vendors serving mid-market Brazilian enterprises. This logistics infrastructure simultaneously concentrates supply-side cryptographic module sourcing and creates tiered delivery cost differentials that vendors pass through as certification-grade price stratification.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts across Iberian financial services and Brazilian fintech corridors, with transaction-metered SaaS pricing displacing perpetual seat licenses in seasonal-workforce segments. Pricing stratifies across qualified electronic signature tiers, standard cloud-based authentication, and lightweight biometric verification levels, with differentiation resting on eIDAS compliance depth and ICP-Brasil accreditation status. Cost compression in standard-tier cloud deployments is intensifying because API-native distribution channels reduce switching friction for price-sensitive small enterprises. Government buyers under ICP-Brasil mandates exhibit lowest price sensitivity, while Brazilian neobanks and Portuguese manufacturing clusters drive hardest bargain on per-transaction rates.
Supply Chain Analysis
Export-control regimes restricting hardware security module technology flows from France and Germany to non-EU trust service providers are fragmenting procurement channels for qualified signature infrastructure. Supply concentrates in Thales Group's French fabrication facilities, Spanish national mint certification operations, and Brazilian ICP-Brasil-accredited local certificate authorities, with cryptographic processors, secure element chips, and FIPS-validated key storage modules forming critical input dependencies. Single-source vulnerability runs through ETSI certification bottlenecks for supervised provider status. Distribution runs through channel partnerships between software integrators and local certification authorities rather than direct platform sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat, where eIDAS and ICP-Brasil certification timelines create switching costs that protect incumbent qualified trust service providers from disruptive cloud-native challengers.
For Market Incumbents: Insulate market position by accelerating ETSI pre-certification investments ahead of eIDAS 2.0 wallet mandates, while acquiring biometric authentication specialists to neutralize mobile-first banking threats from neobank challengers. Deepen channel control through exclusive partnerships with Spanish and Brazilian software integrators serving government procurement workflows. Prioritize hybrid deployment architectures that address LGPD data localization obligations without surrendering cloud economics entirely. For New Entrants and Emerging Players: Brazilian notarial workflow digitization represents the most penetrable entry point, as localized compliance requirements have blocked standardized global platform penetration and left mid-tier legal services providers underserved. API-native distribution through Microsoft and Google productivity suite marketplaces offers the cleanest go-to-market angle for small enterprise segments in Portuguese manufacturing and Spanish logistics corridors. eIDAS 2.0 wallet-integrated signing solutions present white space ahead of member state transposition deadlines. For Investors and Strategic Acquirers: Regional compliance specialists with established ICP-Brasil or ETSI certification relationships and captive local certificate authority partnerships offer the strongest acquisition target archetype for portfolio positioning. Long-term viability rests on regulatory entrenchment depth rather than technology differentiation, with five-to-ten-year windows favoring incumbent trust service providers over speculative biometric challengers. Watch eIDAS 2.0 wallet specification finalization as the critical inflection signal for platform rearchitecture requirements and compliance recertification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI Pre-Certification Investment | Accelerates supervised trust service provider status ahead of eIDAS 2.0 mandates in Madrid and Barcelona financial hubs. |
| Biometric Authentication Acquisition | Neutralizes mobile-first banking threats from Brazilian neobanks deploying facial recognition for remote onboarding. |
| API-Native Platform Integration | Compresses procurement cycles for small enterprises through Microsoft and Google productivity suite marketplaces. |
| Hybrid Deployment Architecture | Addresses LGPD data localization obligations in São Paulo fintech corridors without sacrificing cloud scalability. |
| Notarial Workflow Specialization | Captures underpenetrated Brazilian legal services segment blocked from standardized global platform adoption. |
Research Methodology
Operator-level perspectives from trust service provider executives, bank CTOs in São Paulo and Madrid, certification authority technical directors, and enterprise procurement officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through eIDAS regulatory filings, ICP-Brasil accreditation databases, ETSI technical standards documentation, and SEC disclosures from listed platform vendors. Bottom-up segmentation modeling triangulated against top-down market sizing derived from supervisory authority trust service statistics.
Scenario-bracketing framed the analytical approach across the projection horizon, with deployment architecture, authentication method, and end-user scale serving as core segmentation dimensions for volume and value disaggregation. CAGRs were derived from trend extrapolation of qualified electronic signature issuance volumes, cloud platform subscription growth, and biometric authentication pilot-to-production conversion rates in Latin American retail banking. PKI specialist labor availability and ETSI certification queue lengths provided industry-specific forecast constraints.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real volatility, EU digital infrastructure investment cycles, or transatlantic data transfer policy would shift the trajectory. Forecasts reflect documented assumptions regarding eIDAS 2.0 implementation timelines and ICP-Brasil framework stability. Material shifts in ETSI technical standards or Brazil's LGPD enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
File Sharing Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
System Integration Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Digital Signage Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Europe Multichannel Order Management Market