
 Global Website Builders Market | 2026-2036
Global Website Builders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Website Builders Market Outlook
Platform unbundling is pivoting how buyers evaluate website builders, with specialized modules for e-commerce, booking, and membership now sold separately from core site construction. Wix.com leverages its App Market ecosystem to sustain developer loyalty across freelance and small business segments. Shopify anchors merchant services through in-house payment processing and fulfillment integrations. Squarespace differentiates through design-forward templates that occupy premium positioning among creative professionals.
Website builders are cloud-native software platforms that enable users to construct, publish, and manage websites through graphical interfaces without manual code authoring, typically incorporating WYSIWYG editing, responsive layout engines, and integrated hosting infrastructure. Their primary commercial purpose is reducing technical barriers to digital presence for non-developer organizations and individuals. Drag-and-Drop interfaces dominate volume due to intuitive onboarding, while E-Commerce features command the highest margin pools as transaction fees compound over time. Cloud-Based deployment leads adoption curves because it eliminates server maintenance burdens, though Hybrid configurations are gaining traction among enterprises with legacy compliance requirements.
The EU AI Act and GDPR impose strict transparency and data minimization obligations on platforms processing European user data, forcing architectural investments in consent management and automated content classification. The US lacks comprehensive federal privacy legislation, though state-level frameworks like California's CCPA create compliance patchworks that increase operational complexity for cloud-hosted services. Stakeholders must monitor whether emerging AI-generated content capabilities trigger additional regulatory scrutiny under existing consumer protection statutes.
Market Dynamics
Platform unbundling is fragmenting the website builder value chain, with specialized modules for commerce, booking, and membership now decoupling from core site construction. This structural shift forces vendors to defend integration depth while partners capture margin pools at the edge.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European transparency obligations are accelerating architectural investments in consent management and automated content classification, creating upgrade cycles across installed bases.
- Small business retail digitization:Independent merchants in the United States and India are deploying commerce-enabled builders to replace legacy point-of-sale systems with unified online-offline operations.
- Cloud-native deployment models:Elimination of server maintenance burdens is pulling micro-enterprises and freelance professionals off self-hosted WordPress configurations toward managed SaaS platforms.
Market Restraints
- Payment processor concentration:Dependency on Stripe, PayPal, and Adyen for embedded checkout creates margin compression and operational vulnerability for mid-market platforms.
- Input cost volatility in CDN and compute:Cloud infrastructure pricing fluctuations directly compress gross margins for unlimited-bandwidth pricing tiers.
- Technical limitation in legacy data portability:Proprietary content formats lock customers into incumbent platforms, suppressing competitive switching and innovation velocity.
Strategic Opportunities
- Underpenetrated professional services in Germany:Law firms, consultancies, and medical practices remain underserved by design-forward platforms optimized for visual portfolios rather than credential presentation.
- Regulatory tailwind from India's Digital India initiative:Government-mandated MSME digitization programs are subsidizing first website adoption among manufacturing clusters in Gujarat and Tamil Nadu.
- Technology convergence of AI content generation and no-code interfaces:Natural language site construction is collapsing the time-to-publish gap between template selection and live deployment.
Industry Challenges
- Frontend-to-backend integration complexity:Connecting third-party CRM, ERP, and marketing automation systems requires scarce full-stack engineering talent that mid-size vendors struggle to retain.
- Certification timeline friction under ISO 27001:Enterprise security audits extend sales cycles by four to eight months, straining cash conversion for subscription-revenue models.
- Cross-border data localization requirements:Divergent national regulations on data residency force redundant infrastructure investments that fragment operational scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Website Builders Market |
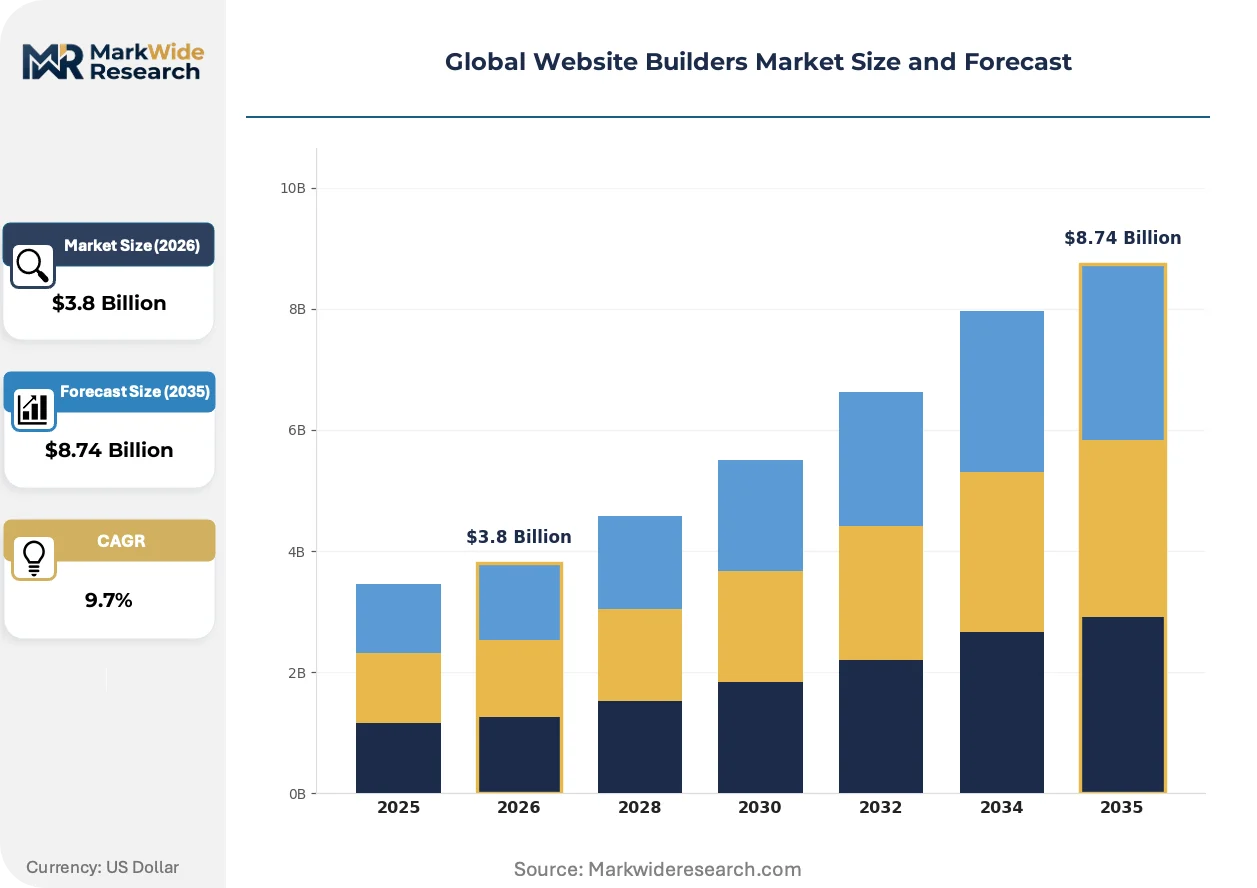
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drag-and-Drop, Template-Based, Code-Free, E-Commerce Customer Type: Small Businesses, Freelancers, Enterprises, Startups Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Feature: SEO Tools, Hosting Services, Analytics, Multi-Language Support |
| Companies Covered | Wix.com, Squarespace, WordPress.org, Shopify, GoDaddy, Webflow, Automattic Inc., Duda, BigCommerce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Website Builders Market Strategic Shifts
Artificial intelligence is rewriting the production economics of website creation, compressing design iteration cycles from days to minutes. Three interconnected developments are determining competitive positioning through 2035.
Generative layout engines are modularizing the site construction process, enabling users to assemble pages from AI-generated component libraries rather than fixed templates. Freelance designers and boutique agencies in the United States are adopting these tools fastest, cutting client delivery times by half. The technology is modularizing the traditional agency model by collapsing the boundary between design and development roles.
The EU AI Act's transparency requirements for automated decision-making are forcing platforms to document content generation provenance and implement human-in-the-loop review workflows. This industrial consequence elevates compliance costs but creates differentiation for vendors with pre-built audit trails. European small businesses and publishers face the steepest adaptation burden, driving consolidation toward platforms with native regulatory tooling.
Subscription fatigue among micro-entrepreneurs is compressing free-to-paid conversion timelines and elevating demand for usage-based pricing. Self-employed professionals in India and Germany are migrating toward builders offering pay-per-transaction commerce models rather than fixed monthly fees. This behavioral shift pressures legacy platforms with rigid tier structures to restructure revenue recognition and customer lifetime value calculations.
Global Website Builders Market Segmentation
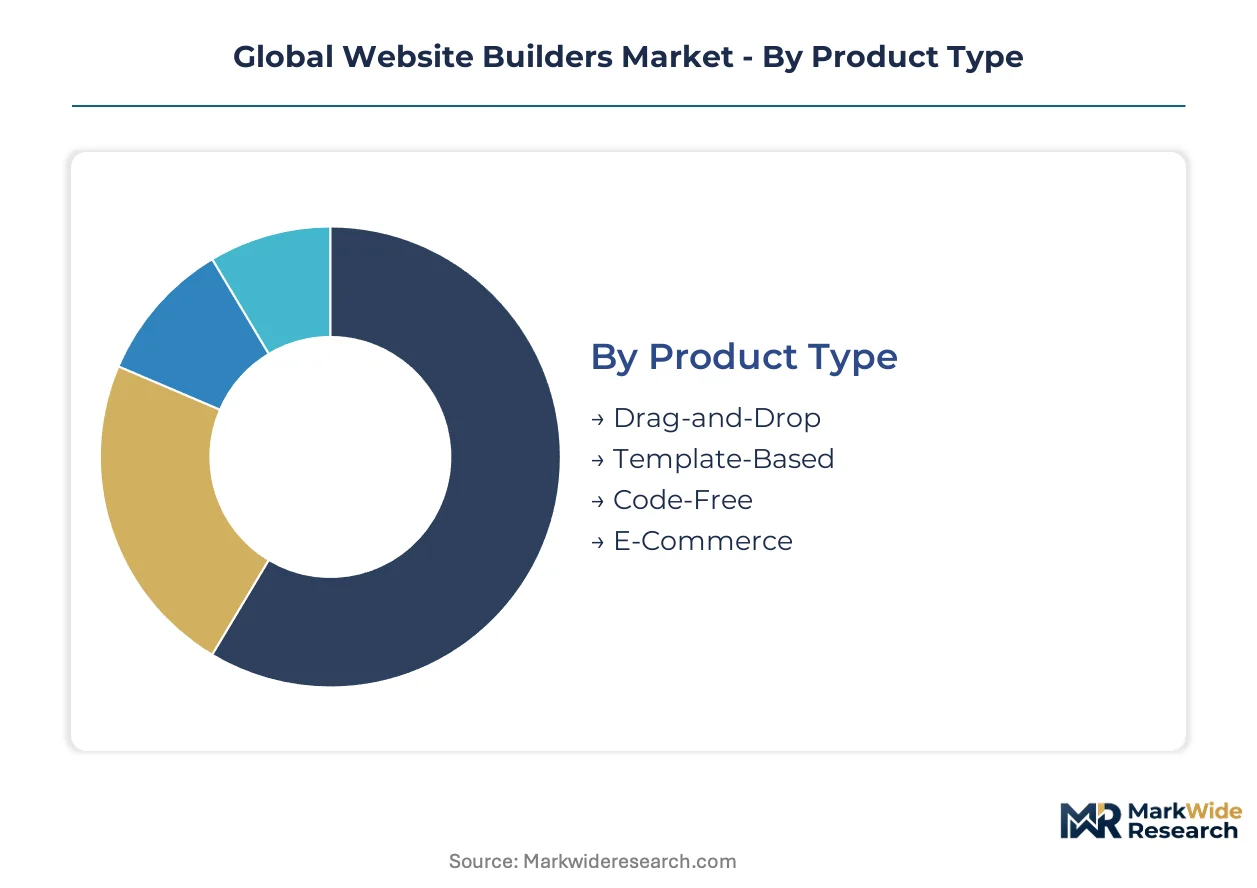
Website builders fragment across four critical dimensions that determine vendor architecture and go-to-market economics. Product type governs technical onboarding complexity, while customer type dictates pricing elasticity and support burden. Deployment models shape infrastructure cost structures, and feature depth separates commodity platforms from premium positioning.
Product Type:
Upgrade cycles in this market accelerate when incumbent platforms fail to match the visual fidelity or commerce depth of newer entrants, forcing replacement decisions every three to five years.
- Drag-and-Drop:Graphical interfaces enable pixel-level positioning of page elements without CSS knowledge. Freelance designers in the United States adopt these tools fastest, driven by client pressure for same-day mockup delivery.
- E-Commerce:Native inventory management, payment processing, and fulfillment integrations transform static sites into transaction engines. Small business retailers in India deploy these capabilities to replace legacy point-of-sale systems with unified online-offline operations.
- Template-Based:Pre-designed page structures accelerate launch timelines for users prioritizing speed over customization.
- Code-Free:AI-assisted natural language interfaces collapse the boundary between intent and deployment, attracting non-technical entrepreneurs.
Volume placements concentrate in Drag-and-Drop; the faster expansion belongs to E-Commerce.
Customer Type:
Cost tier stratification separates self-service onboarding from white-glove implementation, with annual contract values spanning two orders of magnitude across this spectrum.
- Small Businesses:Independent merchants and professional service firms require unified presence management without dedicated IT staff. Law firms and medical practices in Germany remain underserved by design-forward platforms optimized for visual portfolios rather than credential presentation.
- Freelancers:Solo practitioners trade off template flexibility against monthly subscription burden, gravitating toward pay-per-transaction models.
- Enterprises:Procurement teams mandate ISO 27001 certification and SSO integration, extending sales cycles substantially.
- Startups:Venture-backed teams prioritize speed-to-market over long-term platform flexibility, accepting migration costs later.
Volume placements concentrate in Small Businesses; Freelancers are climbing the fastest.
Deployment:
Margin structures diverge sharply between multi-tenant SaaS architectures and single-tenant configurations bearing compliance overhead.
- Cloud-Based:Elimination of server maintenance burdens pulls micro-enterprises off self-hosted WordPress configurations toward managed platforms. GDPR and EU AI Act transparency obligations are accelerating architectural investments in consent management across European deployments.
- Hybrid:Split architectures satisfy enterprises with legacy data residency requirements while capturing cloud scalability for customer-facing layers. Financial services firms in Germany and healthcare providers in the United States drive demand here.
- On-Premise:Air-gapped installations persist in defense and classified government environments.
- Mobile:Native iOS and Android builders address creator economies prioritizing content velocity over desktop precision.
Volume placements concentrate in Cloud-Based; Hybrid configurations are gaining share fastest.
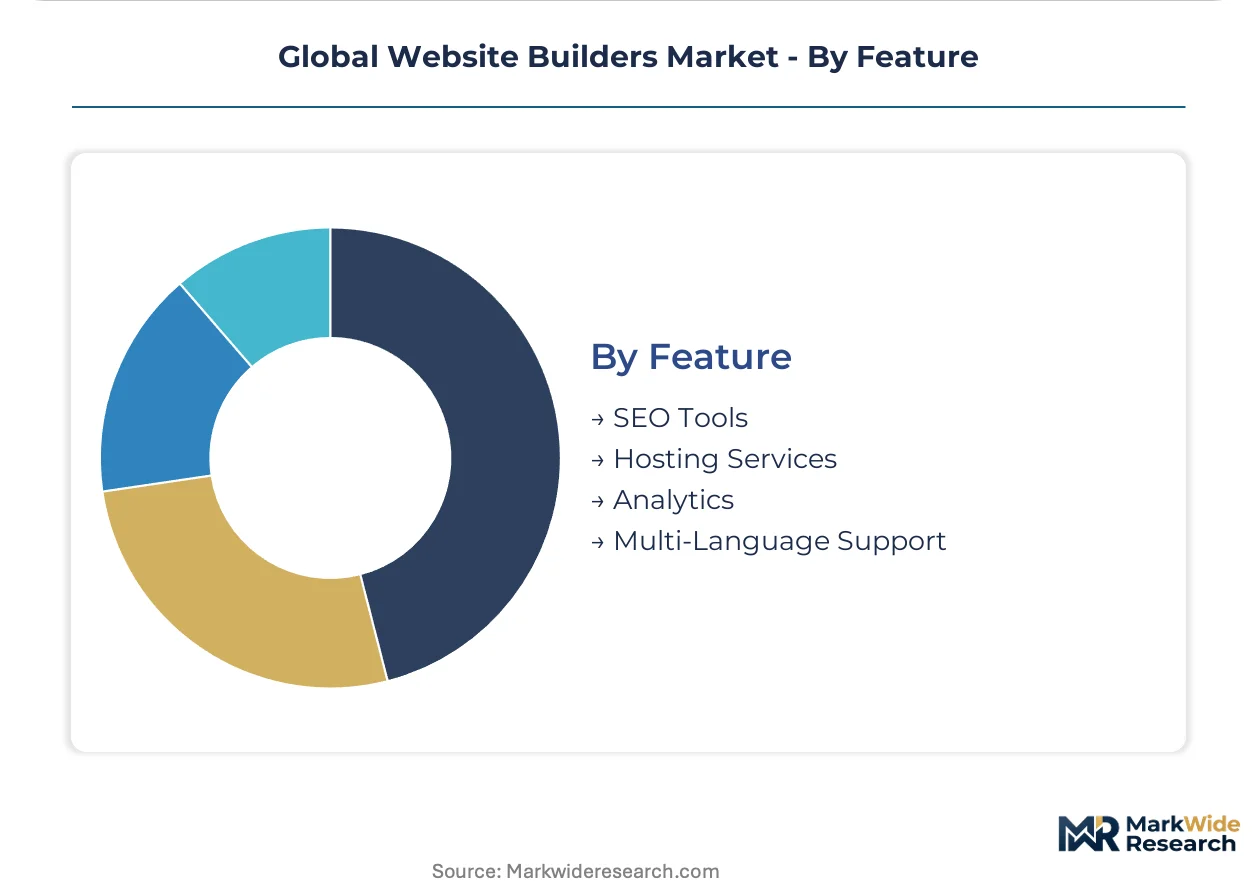
Feature:
Application maturity separates table-stakes functionality from differentiated modules commanding pricing premiums.
- SEO Tools:Automated metadata generation, schema markup, and Core Web Vitals optimization determine discoverability outcomes. Marketing agencies in the United States bundle these capabilities into retainer services for local business clients.
- Hosting Services:Global CDN distribution and DDoS protection eliminate infrastructure management burden. India's Digital India initiative subsidizes first website adoption among manufacturing clusters in Gujarat and Tamil Nadu, pulling hosting decisions toward domestic data centers.
- Analytics:Privacy-compliant visitor tracking replaces third-party cookie dependencies under GDPR enforcement.
- Multi-Language Support:Automated translation and hreflang management enable single-site globalization for cross-border merchants.
Volume placements concentrate in Hosting Services; SEO Tools are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Tamil Nadu are accelerating small business digitization through subsidized SaaS adoption. India's Digital India initiative channels public investment into manufacturing cluster modernization. The United States, Germany, and India concentrate entrepreneurial density with divergent compliance burdens shaping platform architecture.
United States
Freelance designers and boutique agencies drive drag-and-drop platform volume through client pressure for rapid mockup delivery. State-level privacy frameworks including California's CCPA create compliance patchworks that increase operational complexity for cloud-hosted services. Marketing agencies in New York and Los Angeles bundle SEO capabilities into retainer services for local business clients.
Germany
Law firms, consultancies, and medical practices in Bavaria and North Rhine-Westphalia remain underserved by design-forward platforms. The EU AI Act and GDPR impose strict transparency and data minimization obligations forcing architectural investments in consent management. Financial services firms in Frankfurt drive demand for hybrid deployment configurations satisfying legacy data residency requirements.
India
Independent merchants in manufacturing clusters across Gujarat and Tamil Nadu deploy commerce-enabled builders to replace legacy point-of-sale systems. The Digital India initiative subsidizes first website adoption among micro-enterprises through domestic data center requirements. Self-employed professionals in Bangalore and Hyderabad migrate toward pay-per-transaction commerce models rather than fixed monthly fees.
United Kingdom
Creative professionals in London prioritize design-forward templates occupying premium positioning for visual portfolios. The Information Commissioner's Office enforces GDPR compliance through consent management audits extending vendor certification timelines. Marketing automation integrators in Manchester and Edinburgh face frontend-to-backend complexity requiring scarce full-stack engineering talent.
Japan
Enterprise procurement teams in Tokyo mandate ISO 27001 certification and SSO integration extending platform sales cycles substantially. METI guidelines on data localization influence hybrid architecture decisions for financial services and healthcare providers. Small business retailers in Osaka and Nagoya adopt cloud-native deployment to eliminate server maintenance burdens from legacy self-hosted configurations.
Global Website Builders Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between design-forward template providers, commerce-anchored transaction platforms, and modular app ecosystem operators. Three strategic archetypes dominate: template-first visual platforms, commerce-native merchant services, and extensible developer ecosystems. M&A activity concentrates on AI content generation capabilities while geographic expansion targets underpenetrated professional services segments.
Within the design-forward tier, Squarespace exemplifies premium positioning among creative professionals through template specialization. Wix.com anchors the modular ecosystem archetype with its App Market sustaining developer loyalty across freelance segments. Shopify represents the commerce-native merchant services model through integrated payment processing and fulfillment infrastructure. These three companies occupy distinct competitive vectors without direct feature overlap, enabling parallel expansion rather than zero-sum displacement.
| Leading Market Players |
|---|
| Wix.com |
| Squarespace |
| WordPress.org |
| Shopify |
| GoDaddy |
| Webflow |
| Automattic Inc. |
| Duda |
| BigCommerce |
| Others |
Value Chain & Pricing Dynamics
Captive control over payment processing infrastructure anchors both supply security and pricing power for commerce-native platforms, insulating margin pools from Stripe and PayPal concentration while forcing competitors into unfavorable revenue-sharing terms. This integration choice separates transaction-fee compounders from subscription-revenue builders facing perpetual churn pressure.
Pricing Analysis
Short lead-time deployment commands premium positioning, with same-day site launches justifying 40-60% markups over standard provisioning windows. The dominant structure stratifies across premium, standard, and economy tiers, with price differentiation driven by ISO 27001 certification status and after-sales support depth. Cost compression in the economy tier intensifies because cloud infrastructure pricing fluctuations directly squeeze unlimited-bandwidth offerings. Freelancers and micro-entrepreneurs exhibit highest price sensitivity, while enterprise procurement teams prioritize compliance over unit cost.
Supply Chain Analysis
ISO 27001 and SOC 2 qualification gating restricts viable infrastructure partners to a narrow tier of certified cloud providers, concentrating supply leverage among AWS, Google Cloud, and Microsoft Azure. Geographic supply concentration centers on the United States, Ireland, and Singapore for primary data center footprints. Raw material dependencies span compute silicon, CDN bandwidth, and payment gateway APIs. Single-source vulnerability in payment processor relationships creates operational fragility. Distribution runs through direct self-service portals and agency channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act and GDPR compliance architecture functions as a cost-of-compliance moat, elevating barrier-to-entry for undercapitalized entrants while rewarding incumbents with pre-built audit tooling and consent management infrastructure.
For Market Incumbents: Cement regulatory differentiation by accelerating human-in-the-loop review workflow deployment before the EU AI Act enforcement window tightens. Threaten emerging AI-native entrants through ISO 27001 certification depth that extends enterprise sales cycles beyond their cash runway. Prioritize backward integration into domestic data center infrastructure in Germany and India to satisfy localization mandates without third-party dependency. For New Entrants and Emerging Players: Enter via underpenetrated professional services verticals in Germany, where law firms and medical practices remain underserved by design-forward incumbents. Target pay-per-transaction pricing models for India's self-employed professionals, where subscription fatigue creates migration tailwinds. Anchor go-to-market through agency channel partnerships rather than direct consumer acquisition. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays, with AI content generation capabilities commanding strategic premiums. Long-term viability favors vendors with native regulatory tooling that transforms compliance cost into competitive moat. Watch for inflection in India's Digital India subsidy disbursement rates as a signal for MSME adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Content Generation Integration | Natural language site construction collapses time-to-publish from days to minutes for freelance designers. |
| Regulatory Compliance Certification | Pre-built GDPR and EU AI Act audit trails differentiate European platform offerings against non-compliant rivals. |
| Payment Processing Captive Control | In-house transaction infrastructure insulates margin pools from Stripe and PayPal concentration risk. |
| Hybrid Deployment Architecture | Split cloud configurations satisfy German financial services data residency without sacrificing scalability. |
| Agency Channel Partnership Expansion | Boutique design firms in the United States bundle platform capabilities into retainer services for local clients. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with platform product managers, enterprise IT procurement officers, freelance web designers, and SaaS channel partners. Secondary validation drew from SEC 10-K disclosures, EU AI Act implementation guidance, and India's Digital India program documentation. Bottom-up triangulation across customer segmentation databases reconciled with top-down market sizing from cloud infrastructure spend analysis.
Reconciliation of deployment velocity metrics, customer acquisition cost trajectories, and churn rate benchmarks informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, customer archetype, deployment configuration, and feature depth. CAGRs derived from fitted adoption curves incorporating regulatory compliance investment cycles and small business digitization program subsidies. Industry-specific inputs included payment processor fee structures and CDN bandwidth pricing indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or India's subsidy program suspension. Forecasts reflect documented assumptions regarding cloud infrastructure cost trajectories and cross-border data localization expansion. A model refresh is warranted upon material change in payment processor market concentration or GDPR fine precedent magnitude.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Product Engineering Services Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Global Multichannel Campaign Management Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Service Mesh Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Customer-To-Customer (C2C) Community Market