
 Mexico ICT Market | 2026-2036
Mexico ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico ICT Market Outlook
Enterprise-grade fiber connectivity is rotating toward higher-specification service tiers across Mexican commercial corridors. América Móvil leverages its national infrastructure footprint to sustain wholesale dominance in backbone provisioning. Oracle anchors enterprise software demand through localized cloud region operations. Megacable Holdings competes in the residential and SME broadband segment with hybrid fiber-coaxial deployments.
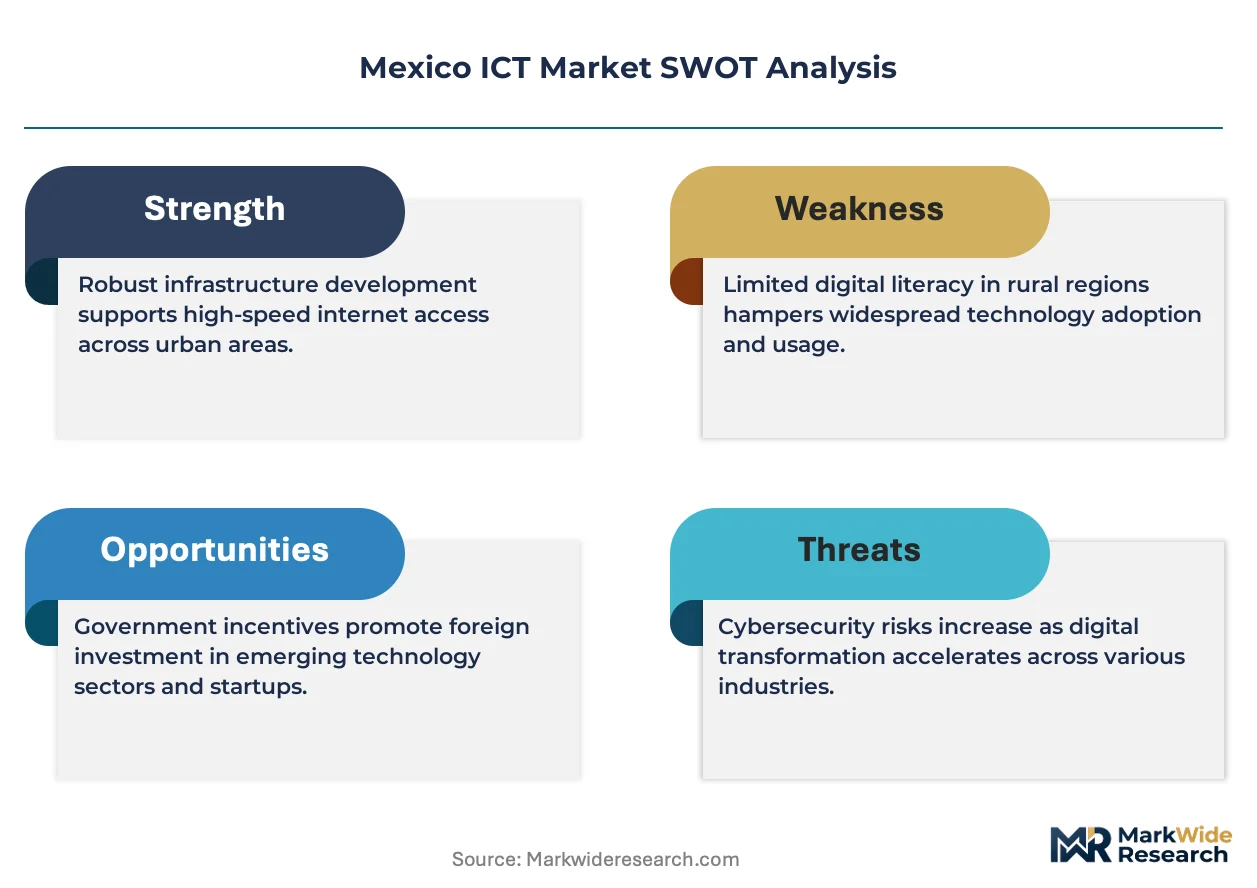
Information and communications technology in Mexico spans hardware systems, software platforms, telecommunications services, and network infrastructure operating across copper, fiber-optic, and wireless spectrums with latency thresholds under 50 milliseconds for enterprise-grade offerings. The primary purpose is enabling data exchange, automation, and digital commerce across public and private sectors. Software and cloud-based deployment segments capture expanding margin pools as enterprises migrate from legacy on-premises installations. Hardware retains volume concentration in device refresh cycles for government and educational procurement. AI and cybersecurity technologies within the technology dimension attract specialized investment as threat surfaces widen.
Federal Telecommunications Institute licensing frameworks shape market access for spectrum-dependent operators, while COFEPRIS data-protection protocols govern health-sector ICT procurement standards. The Secretariat of Economy's digital transformation incentives direct SME technology adoption patterns across state-level development zones. Stakeholders must monitor pending spectrum auction schedules and state-level digital infrastructure tenders to align capacity investments with regulatory pacing.
Market Dynamics
Federal digitalization mandates under the Secretariat of Finance and Public Credit are compressing procurement timelines across Mexican state agencies while enterprise cloud migration accelerates in manufacturing corridors.
Growth Catalysts
- Federal Telecommunications Institute licensing:Spectrum auction frameworks are expanding carrier capacity for 5G deployment in metropolitan corridors.
- Nearshoring manufacturing demand:Automotive and electronics assembly plants in Querétaro and Tijuana require enterprise fiber and edge computing infrastructure.
- Secretariat of Economy digital incentives:SME technology adoption subsidies in Guanajuato and Nuevo León are accelerating ERP and cybersecurity procurement.
Market Restraints
- Copper-to-fiber transition costs:Legacy last-mile infrastructure replacement requires substantial capital outlay in secondary cities.
- COFEPRIS data-protection compliance:Health-sector ICT procurement faces extended certification timelines for cross-border data handling.
- Concentrated backbone ownership:Wholesale fiber provisioning depends on limited national infrastructure footprints.
Strategic Opportunities
- Yucatán Peninsula logistics corridor:Mérida-Cancún trade route expansion creates demand for industrial IoT and warehouse automation systems.
- AI-cybersecurity convergence:Threat detection platforms integrating machine learning algorithms address widening enterprise attack surfaces.
- State-level digital infrastructure tenders:Jalisco and Puebla development zones offer preferential terms for cloud region establishment.
Industry Challenges
- Cloud architecture specialization gap:Mexican engineering programs produce insufficient certified solutions architects for hybrid deployment complexity.
- Legacy system integration friction:On-premises SAP and Oracle installations resist API-based connectivity with modern SaaS platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico ICT Market |
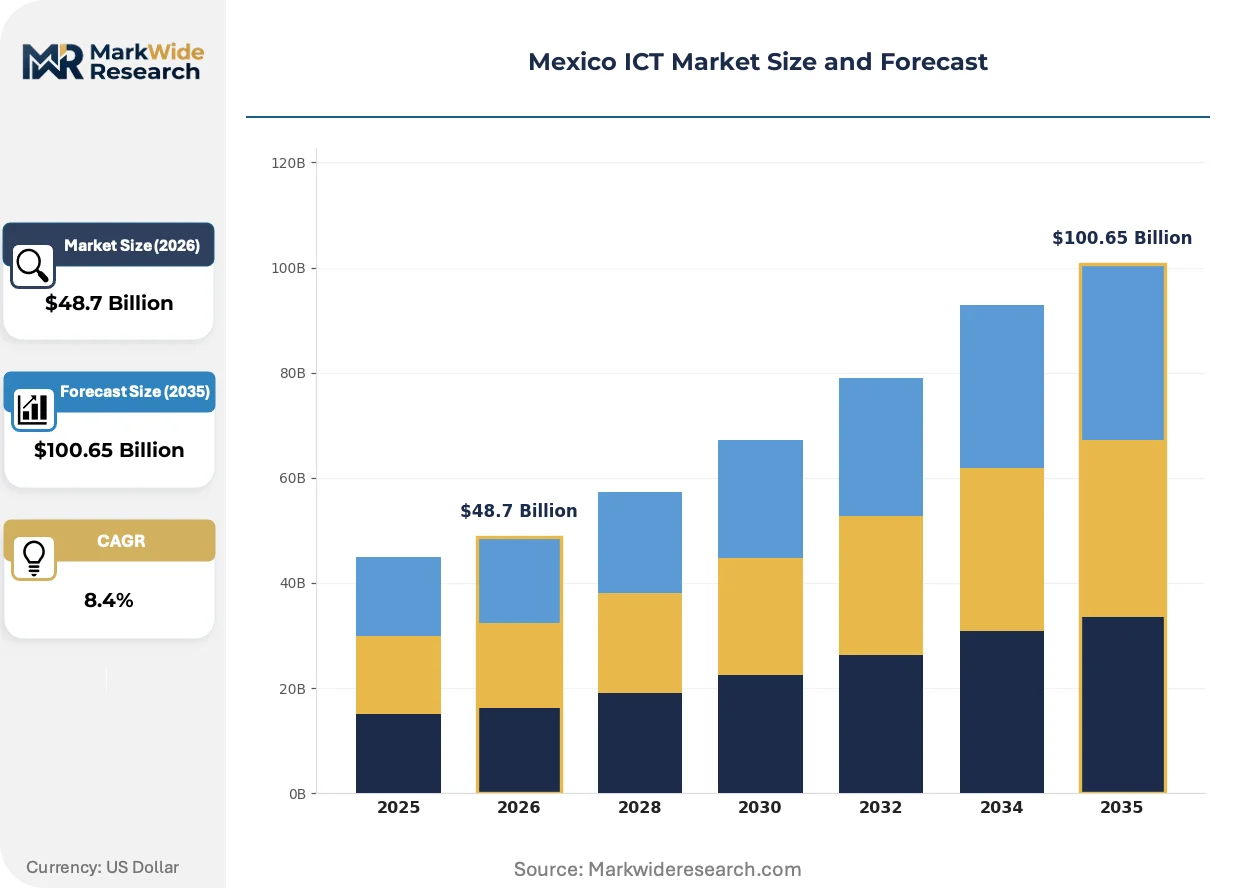
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Network Solutions End User: Government, Enterprises, SMEs, Educational Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: AI, Big Data, IoT, Cybersecurity |
| Companies Covered | Grupo Televisa, Oracle, América Móvil, Apple, Google, AT&T, Megacable Holdings, Kavak, Telefónica México, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico ICT Market Strategic Shifts
Edge computing hardware is migrating from centralized data centers to factory floors and retail locations across Mexican commercial corridors. Three developments are compressing deployment timelines and reshaping competitive requirements.
Edge server infrastructure is miniaturizing from rack-mounted units to fanless embedded devices capable of operating in unconditioned industrial environments. Automotive suppliers in Aguascalientes and appliance manufacturers in Saltillo are deploying these units for sub-10-millisecond latency in quality control applications. This form-factor reduction is miniaturizing the physical footprint required for AI inference at production lines, enabling retrofit installation without facility expansion.
The Federal Telecommunications Institute's 2024 spectrum reallocation framework prioritizes mid-band frequencies for industrial private networks. Manufacturing campuses in Monterrey and Toluca are securing localized 5G licenses to bypass public network congestion. Medical device assemblers in Baja California report the most acute compliance pressure as COFEPRIS mandates real-time sterilization monitoring with guaranteed connectivity uptime.
Enterprise buyers are unbundling hardware procurement from managed service obligations that previously locked in decade-long vendor relationships. Mid-market manufacturers in León and Chihuahua now source servers and networking equipment through distribution channels while contracting cloud management separately. This purchasing pattern shift is most visible in the textile and food processing verticals where capital constraints favor operational expenditure models over asset ownership.
Mexico ICT Market Segmentation
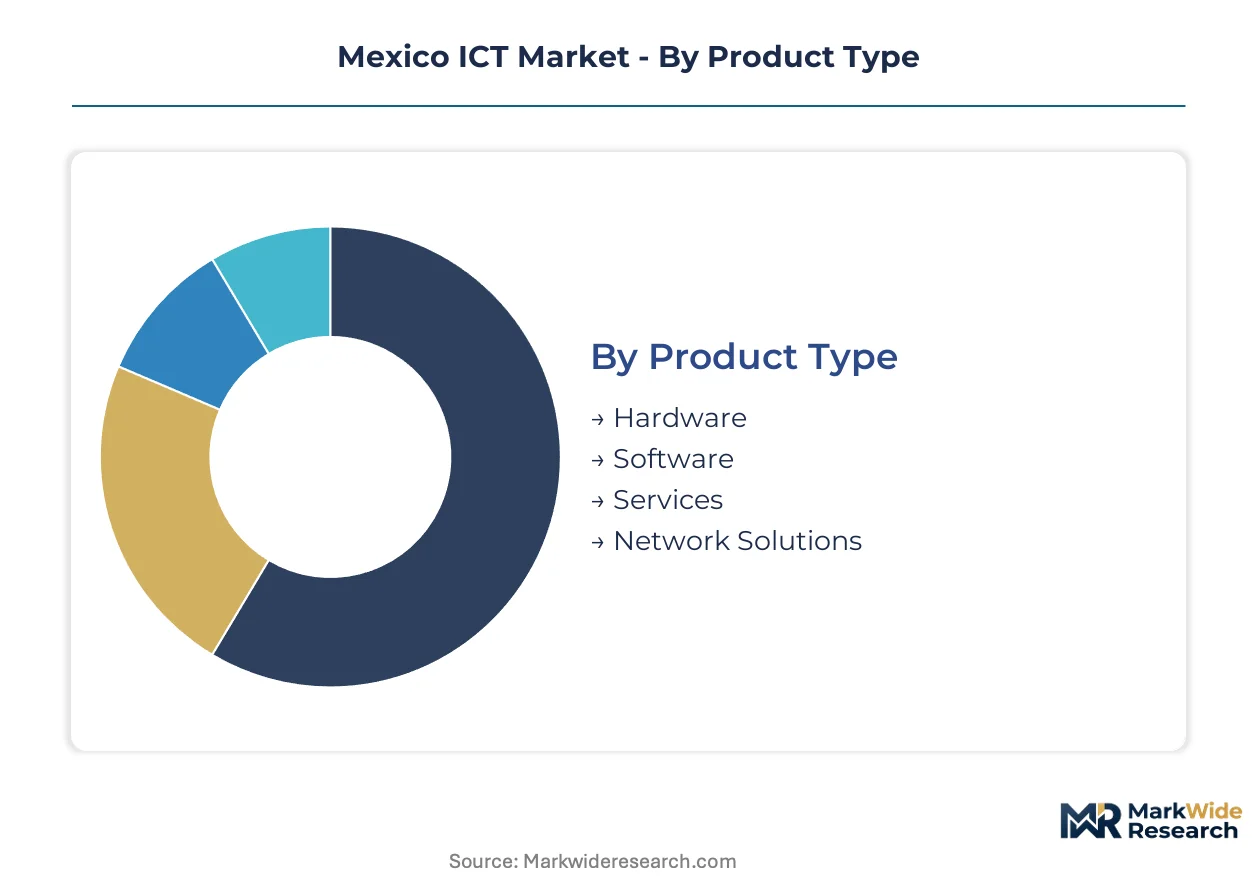
Segmentation in the Mexico ICT market reveals distinct procurement patterns across federal, enterprise, and SME tiers. Each dimension exposes different infrastructure requirements, compliance pressures, and vendor engagement models that shape competitive positioning.
Product Type:
Domestic demand concentrates in hardware and network solutions serving government and manufacturing corridors, while software and services show stronger export-linked growth through nearshoring operations.
- Hardware:Server infrastructure, endpoint devices, and networking equipment form the procurement backbone for federal digitalization mandates. State agencies in Mexico City and Monterrey drive refresh cycles for data center equipment under Secretariat of Finance directives.
- Software:Enterprise resource planning and cybersecurity platforms capture expanding margin pools as manufacturers migrate from legacy installations. Automotive assemblers in Querétaro and Guanajuato prioritize localized licensing to meet data residency requirements.
- Services:System integration and managed support contracts dominate SME procurement in Jalisco and Puebla development zones.
- Network Solutions:Fiber backbone and 5G infrastructure deployments concentrate in metropolitan corridors with Federal Telecommunications Institute licensing.
Hardware commands the established base. The steepest expansion runs through software.
End User:
Cost tier differentiation separates high-compliance federal procurement from price-sensitive SME adoption patterns across state-level incentive zones.
- Government:Federal and state agencies operate under compressed procurement timelines with stringent data localization mandates. The Secretariat of Finance and Public Credit directives accelerate infrastructure spending in Mexico City administrative clusters.
- Enterprises:Manufacturing multinationals in Baja California and Nuevo León drive enterprise fiber and edge computing investments. Nearshoring automotive and electronics plants require sub-50-millisecond latency guarantees for quality control systems.
- SMEs:Subsidized technology adoption in Guanajuato and Nuevo León accelerates ERP and basic cybersecurity procurement through Secretariat of Economy programs.
- Educational Institutions:Device refresh cycles and connectivity upgrades concentrate in metropolitan university corridors with federal procurement support.
Enterprises anchor current revenue concentration. SMEs are expanding most quickly through state-level incentive penetration.
Deployment:
Application complexity determines architecture choice, with hybrid models dominating manufacturing environments requiring legacy system coexistence.
- On-Premises:Legacy SAP and Oracle installations persist in financial services and government agencies with strict data custody requirements. Regulatory friction slows migration timelines for COFEPRIS-governed health sector operators.
- Cloud-Based:Public cloud adoption accelerates in manufacturing corridors with localized region availability. Oracle's cloud operations in Mexico address data residency concerns for enterprise software workloads.
- Hybrid:Split architectures dominate automotive and appliance manufacturing where production line latency requirements conflict with centralized analytics needs. Aguascalientes and Saltillo facilities deploy edge-to-cloud pipelines for quality control.
- Managed Services:Operational expenditure models gain traction in textile and food processing verticals with capital constraints. León and Chihuahua mid-market manufacturers unbundle hardware procurement from management contracts.
On-premises retains the installed base. Cloud-based deployment shows the steepest trajectory as localized infrastructure matures.
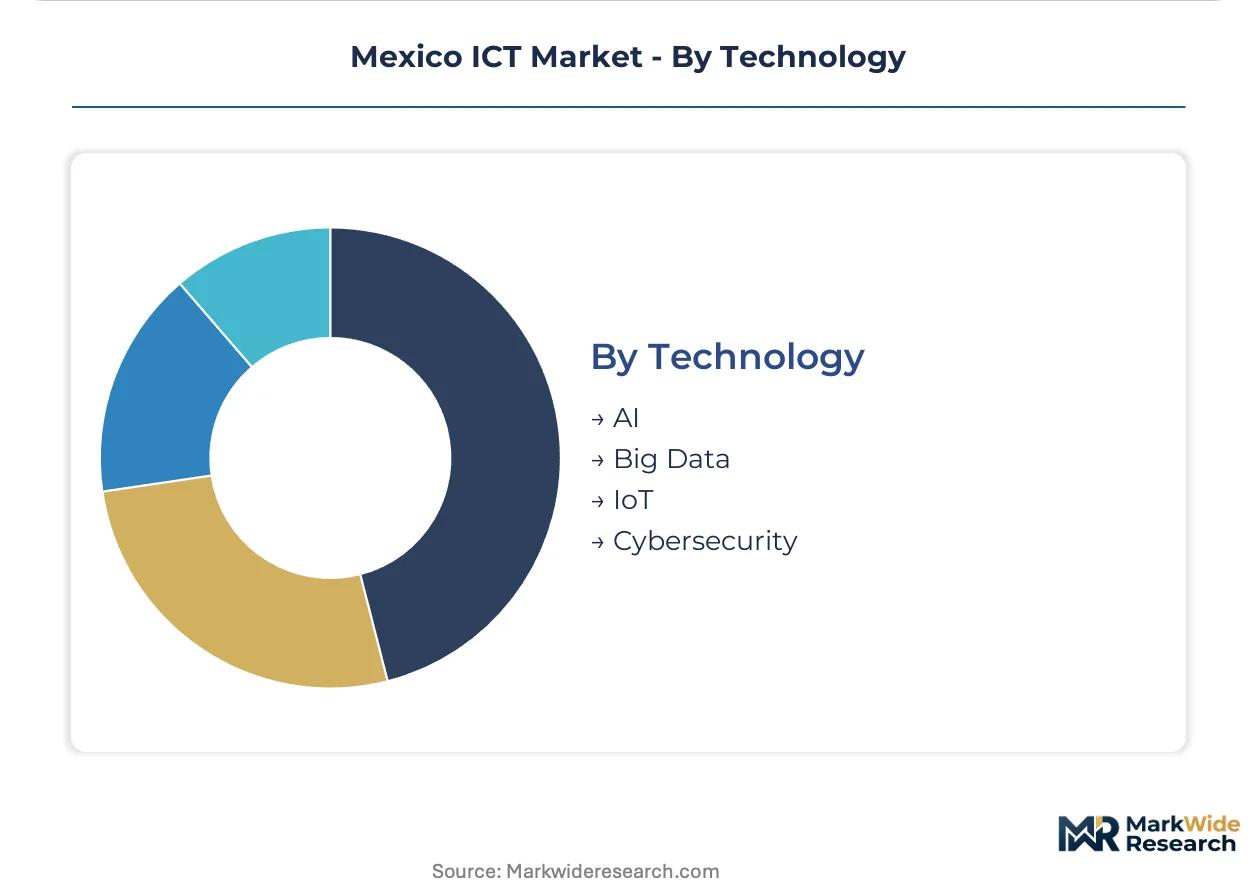
Technology:
Supply concentration in specialized engineering talent shapes adoption velocity, with cybersecurity and AI facing acute capability scarcity.
- AI:Machine learning inference at production lines drives miniaturized edge server deployment in unconditioned industrial environments. Quality control applications in automotive supply chains demand sub-10-millisecond response thresholds.
- Big Data:Analytics platforms support logistics optimization across the Mérida-Cancún trade corridor expansion. Warehouse automation systems generate real-time demand forecasting for Yucatán Peninsula distribution networks.
- IoT:Industrial sensor networks and private 5G licenses enable manufacturing campus connectivity bypassing public network congestion. Monterrey and Toluca facilities secure localized spectrum through Federal Telecommunications Institute frameworks.
- Cybersecurity:Threat detection platforms integrating AI algorithms address widening attack surfaces in financial services and health sectors. COFEPRIS mandates real-time sterilization monitoring with guaranteed uptime for Baja California medical device assemblers.
Big data commands established enterprise investment. Cybersecurity is gaining share fastest through regulatory compliance pressure and threat surface expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier infrastructure ownership concentrates in Mexico City, Guadalajara, and Monterrey, with state-level digital incentive programs expanding procurement reach into secondary manufacturing corridors.
Mexico City Metro
Federal digitalization mandates under the Secretariat of Finance compress procurement timelines for data center and connectivity infrastructure. The Federal Telecommunications Institute licensing frameworks govern spectrum allocation for 5G deployment across the capital region. Administrative clusters in Polanco and Santa Fe anchor enterprise software demand from financial services and government agencies.
Nuevo León
Automotive and electronics assembly plants drive enterprise fiber and edge computing investments with sub-50-millisecond latency requirements. Secretariat of Economy digital incentives accelerate SME technology adoption for ERP and cybersecurity procurement. Monterrey manufacturing campuses secure localized 5G licenses through Federal Telecommunications Institute frameworks to bypass public network congestion.
Jalisco
Nearshoring operations in software development and IT services create demand for cloud region establishment and data residency compliance. State-level digital infrastructure tenders offer preferential terms for hyperscale facility investment. Guadalajara technology clusters deepen around Oracle's localized cloud operations serving enterprise workloads.
Bajío Region
Automotive suppliers in Aguascalientes and appliance manufacturers in Saltillo deploy miniaturized edge servers for quality control applications. The Federal Telecommunications Institute's 2024 spectrum reallocation prioritizes mid-band frequencies for industrial private networks. Querétaro and Guanajuato facilities prioritize localized software licensing to meet data residency requirements.
Northern Border States
Medical device assemblers in Baja California face COFEPRIS compliance pressure for real-time sterilization monitoring with guaranteed connectivity uptime. Tijuana electronics plants require enterprise fiber infrastructure for cross-border supply chain integration. Chihuahua mid-market manufacturers unbundle hardware procurement from managed service contracts to favor operational expenditure models.
Mexico ICT Market Competitive Environment
Concentration sits with integrated telecommunications carriers and hyperscale cloud operators that control national backbone infrastructure and localized data center capacity. The market structure tiers between wholesale fiber provisioners, enterprise software platforms, and hybrid connectivity specialists serving SME segments. Strategic archetypes include infrastructure-integrated carriers, cloud-anchored software vendors, and fiber-coaxial broadband competitors. Dominant competitive moves center on spectrum license acquisition and cloud region establishment.
Within the infrastructure-integrated tier, América Móvil and Megacable Holdings represent contrasting scale positions in backbone and last-mile provisioning. Oracle anchors the cloud-anchored software archetype through localized region operations addressing data residency requirements. AT&T and Telefónica México occupy positions within the multinational carrier segment competing for enterprise connectivity contracts.
| Leading Market Players |
|---|
| Grupo Televisa |
| Oracle |
| América Móvil |
| Apple |
| AT&T |
| Megacable Holdings |
| Kavak |
| Telefónica México |
| Others |
Value Chain & Pricing Dynamics
Cloud-based service models replacing perpetual software licenses simultaneously reshape supply geography toward hyperscale data centers and compress pricing economics across Mexican enterprise procurement. This substitution dynamic redirects margin capture from hardware distributors to managed service providers while Federal Telecommunications Institute spectrum auctions alter infrastructure cost structures for carrier-dependent deployments.
Pricing Analysis
Federal Telecommunications Institute licensing frameworks dictate the pricing tier structure across connectivity services, separating premium enterprise fiber with guaranteed latency from standard broadband and economy residential tiers. Price differentiation rests on certification grade for COFEPRIS-governed health sector procurement and volume scale for state agency consolidated purchasing. Cost compression in mid-market SME segments is intensifying because Secretariat of Economy subsidies cap out-of-pocket expenditure. Government buyers show least price sensitivity due to mandated digitalization timelines, while textile and food processing verticals in León and Chihuahua exhibit acute expenditure control.
Supply Chain Analysis
Strategic stockpiling of edge computing hardware dominates procurement patterns as manufacturers secure miniaturized server inventory ahead of Federal Telecommunications Institute spectrum reallocation deadlines. Component sourcing draws from Taiwan for semiconductors, China for networking equipment, and the United States for enterprise software licensing. Single-source vulnerability concentrates in fiber-optic cable supply for backbone expansion. Distribution runs through América Móvil's national wholesale infrastructure and direct hyperscaler channels for cloud services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated manufacturing multinationals in Nuevo León and Baja California, fragmenting pricing leverage previously held by carrier incumbents and forcing unbundled procurement terms.
For Market Incumbents: Consolidate cloud region capacity investments in Jalisco and Nuevo León development zones to preempt hyperscaler encroachment on enterprise workloads. Deepen backward integration into fiber backbone infrastructure to defend margin position against wholesale access pressure from Federal Telecommunications Institute licensing expansions. For New Entrants and Emerging Players: Managed cybersecurity services for COFEPRIS-governed medical device assemblers represents the most penetrable white-space target, with Baja California facilities requiring real-time sterilization monitoring compliance. Target state-level digital infrastructure tenders in Puebla and Guanajuato through channel partnerships with existing Secretariat of Economy program administrators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fiber-coaxial broadband specialists serving residential and SME segments in secondary cities. Five-to-ten year viability hinges on successful copper-to-fiber transition execution and cloud service bundling penetration. Monitor Federal Telecommunications Institute auction schedules as inflection indicator for infrastructure valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Region Establishment | Oracle's localized operations address data residency requirements for Querétaro automotive assemblers. |
| Spectrum License Acquisition | Mid-band frequency securing enables Monterrey manufacturing campuses to bypass public network congestion. |
| Edge Computing Deployment | Miniaturized server installation supports sub-10-millisecond quality control in Aguascalientes automotive supply chains. |
| Managed Services Unbundling | Operational expenditure models attract capital-constrained textile manufacturers in León seeking procurement flexibility. |
| Cybersecurity Platform Integration | AI-driven threat detection addresses COFEPRIS mandates for Baja California medical device sterilization monitoring. |
Study Parameters
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings across the Mexico ICT landscape. Conversations with CTOs at automotive assemblers, IT procurement officers in federal agencies, platform engineers at hyperscale operators, and channel partners in Guadalajara technology clusters inform demand-side segmentation. Secondary sources include Federal Telecommunications Institute licensing records, Secretariat of Finance procurement disclosures, COFEPRIS certification databases, and carrier capex reports. Bottom-up installation tracking and top-down economic sizing provide triangulation checks.
Sensitivity analysis around spectrum auction timing and nearshoring manufacturing flow projections shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, compliance complexity level, and regional infrastructure maturity. CAGRs derive from installed base migration curves and greenfield adoption rates. Forecast inputs incorporate Federal Telecommunications Institute licensing pipeline visibility and Secretariat of Economy incentive program allocation schedules.
Underlying assumptions cover stable federal digitalization mandate continuity, with deviation risk concentrated in copper-to-fiber transition capital availability and COFEPRIS cross-border data handling rule changes. Revision becomes warranted when nearshoring manufacturing commitments cross threshold shifts or spectrum auction schedules experience regulatory delay.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Indonesia Enterprise Mobility Management Market
Digital Solutions
Webrtc Market
Digital Solutions
Container Orchestration Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Cloud Monetization Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Europe Online Dating Services Market
Digital Solutions
Barcode Software Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Global Process Orchestration Market