
 Philippines Data Center Networking Market | 2026-2036
Philippines Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Data Center Networking Market Insights
Modular switch-to-software bundling is rebalancing procurement patterns across Philippine data center builds. Cisco Systems leverages its integrated silicon-to-software stack to anchor enterprise campus-to-cloud migrations. Juniper Networks competes through intent-based automation tailored for service provider edge deployments. Arista Networks specializes in low-latency leaf-spine fabrics for hyperscale customers operating in the Clark Freeport Zone.
Philippines data center networking encompasses the switching, routing, and interconnect fabric that moves traffic between compute, storage, and external networks within climate-controlled facilities, typically operating at 40G to 400G port speeds with redundant power and sub-5-microsecond latency targets. Its primary purpose is to sustain application availability and data sovereignty for enterprises and cloud operators serving the Philippine archipelago. Ethernet switching leads product type revenue due to universal compatibility with hyperscale topologies, while InfiniBand captures the fastest expansion as GPU clusters for AI training proliferate in Batangas and Pampanga. Cloud-based deployment models are gaining share fastest among fintech entrants seeking elastic capacity without capex commitments.
The Department of Information and Communications Technology (DICT) enforces data localization provisions under the National Cybersecurity Plan, compelling foreign cloud operators to maintain certified domestic network infrastructure. The National Privacy Commission mandates breach-notification timelines that drive investment in redundant switching fabrics with real-time telemetry. The Bureau of Product Standards implements BIS-aligned electrical safety certifications for networking equipment deployed in tropical-humidity environments. Stakeholders must monitor DICT's evolving critical information infrastructure designation list, as reclassification would trigger mandatory on-premises routing for designated sectors.
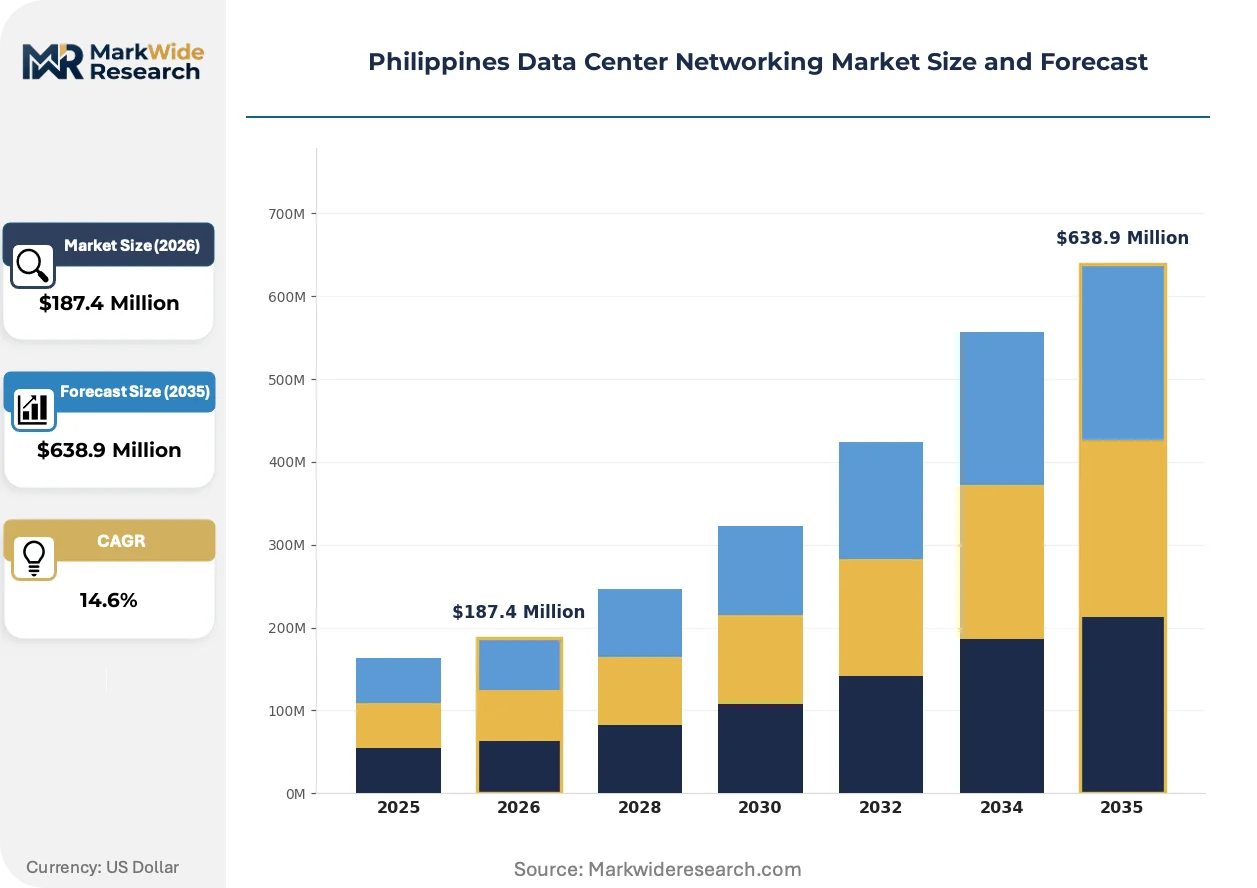
Market Dynamics
Hyperscale clustering around submarine cable landing stations in Clark and Cavite is compressing procurement cycles and forcing switch vendors to pre-certify equipment for tropical-humidity deployment before bidding.
Growth Catalysts
- Digital Banking Mandates:Financial services firms are expanding colocation footprints to satisfy real-time transaction processing requirements and consumer-facing application uptime guarantees.
- DICT Cybersecurity Frameworks:The Department of Information and Communications Technology's tightening compliance requirements compel infrastructure operators to invest in redundant switching fabrics with embedded telemetry.
- GPU Cluster Proliferation:AI training workloads in Batangas and Pampanga are accelerating InfiniBand adoption for east-west traffic between compute nodes.
Market Restraints
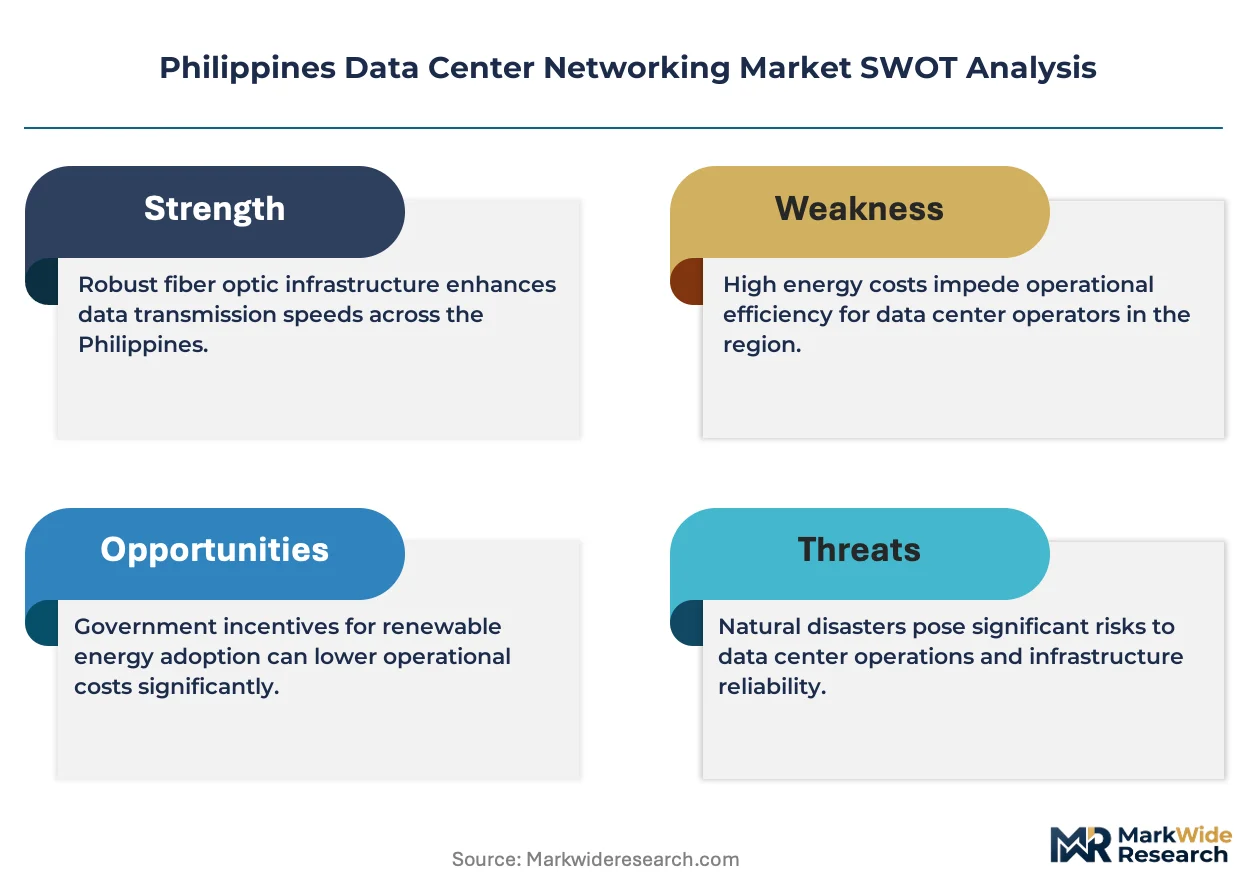
- Submarine Cable Concentration:Dependence on limited landing station corridors creates single-point-of-failure risk for network backhaul in the Clark Freeport Zone.
- BIS-Aligned Certification Delays:The Bureau of Product Standards' electrical safety testing for tropical environments extends equipment approval timelines by four to eight months.
- Copper and Silicon Supply Volatility:Switching fabric component costs fluctuate with foundry capacity allocation decisions in East Asian semiconductor manufacturing hubs.
Strategic Opportunities
- Mindanao Submarine Cable Expansion:Secondary landing stations in Davao and Cagayan de Oro offer greenfield build opportunities outside Metro Manila's congested power grid.
- Fintech Elastic Capacity Models:Cloud-based deployment configurations allow entrants to scale networking resources without committing to three-year hardware depreciation cycles.
- Data Localization Enforcement:The National Cybersecurity Plan's domestic infrastructure requirements create captive demand for certified on-premises routing among foreign cloud operators.
Industry Challenges
- Intent-Based Automation Talent Scarcity:Network engineering teams lack proficiency in API-driven fabric management and telemetry-driven troubleshooting workflows.
- Legacy Campus Integration Friction:Enterprises migrating to leaf-spine architectures face protocol translation complexity with existing three-tier hierarchical switching deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Data Center Networking Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Load Balancers, NICs Deployment Model: On-Premises, Colocation, Hybrid, Cloud-based End User: Financial Services, Retail, IT & Telecommunications, Government Technology: Ethernet, Fiber Channel, InfiniBand, MPLS |
| Companies Covered | Cisco Systems, Juniper Networks, Huawei Technologies, VMware, Arista Networks, Hewlett Packard Enterprise, IBM, Schneider Electric, NVIDIA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Data Center Networking Market Trends and Innovations
Silicon-to-software integration is collapsing traditional procurement boundaries between hardware vendors and network operating system providers across Philippine data center builds.
SmartNICs and DPUs are unifying compute offload, security processing, and storage virtualization onto single-chip platforms. Hyperscale operators in the Clark corridor are deploying these at 25G and 100G densities to free CPU cycles for revenue-generating workloads. This convergence is unifying server and network procurement decisions under single infrastructure teams rather than siloed purchasing committees.
The National Privacy Commission's breach-notification mandates are compressing incident-response windows to seventy-two hours. Data center operators must deploy real-time flow telemetry and automated segmentation to satisfy audit requirements. Financial services colocation tenants bear the highest compliance burden and are pre-qualifying vendors based on native integration with SIEM platforms.
Consumption-based networking contracts are displacing traditional capital purchase models among fintech entrants. These arrangements transfer refresh risk to vendors while granting buyers elastic port capacity. Metro Manila's enterprise segment shows the fastest uptake, with contracts indexed to monthly peak throughput rather than provisioned port counts.
Philippines Data Center Networking Market Segmentation
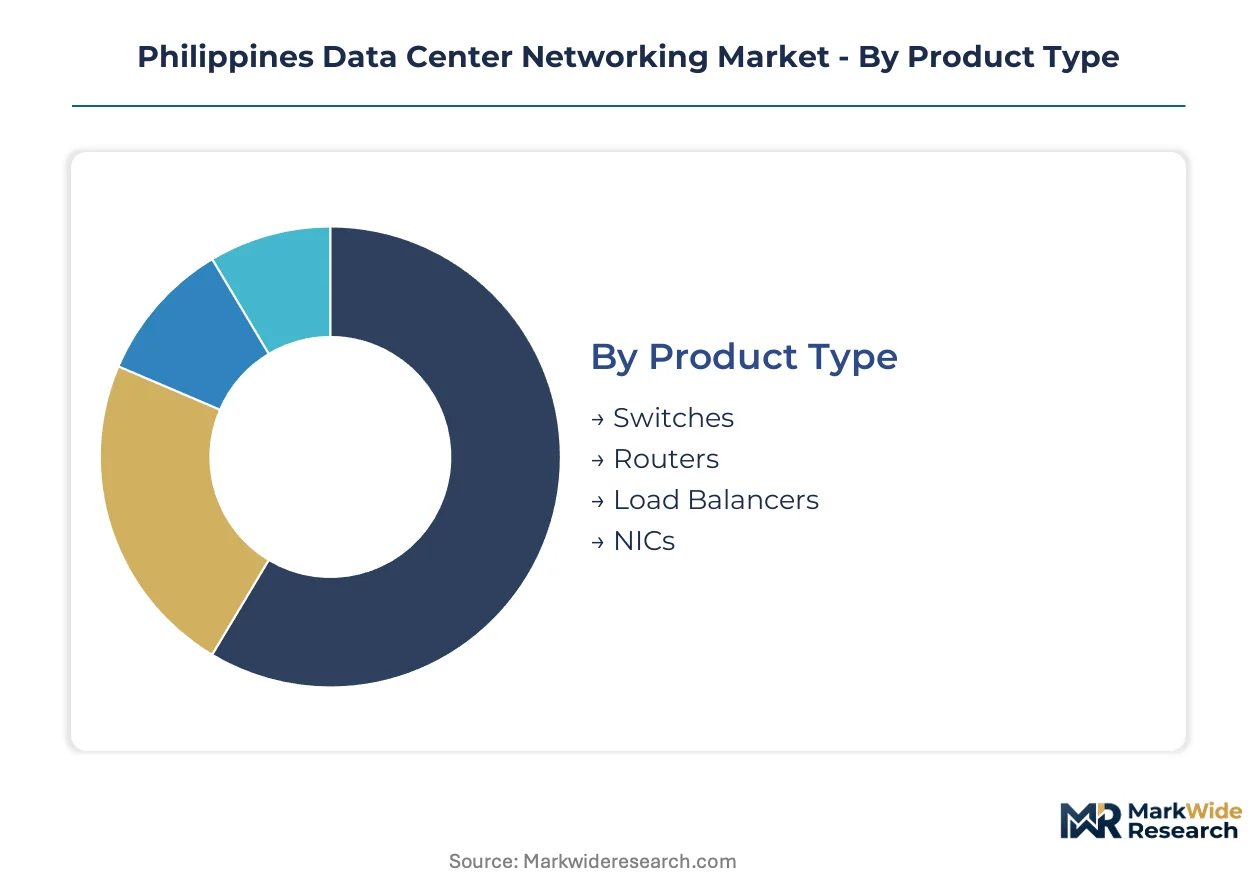
Philippine data center networking procurement splits sharply between hyperscale operators demanding 400G leaf-spine fabrics and enterprise tenants prioritizing certified interoperability with legacy campus infrastructure. Segment boundaries are blurring as SmartNICs collapse switching decisions into server procurement cycles.
Product Type:
Ethernet switching commands volume leadership while specialized interconnect technologies capture premium expansion in GPU-dense deployments.
- Switches:Leaf-spine architectures dominate hyperscale builds in Clark and Cavite, with 100G to 400G port densities standard for east-west traffic between compute racks. Financial services colocation tenants in Metro Manila prioritize redundant switching fabrics with embedded telemetry to satisfy National Privacy Commission breach-notification mandates.
- Routers:Border and core routing infrastructure handles north-south traffic aggregation at submarine cable landing stations, where DICT cybersecurity frameworks mandate domestic traffic inspection capabilities. Operators face extended Bureau of Product Standards certification timelines for tropical-humidity deployment.
- Load Balancers:Application delivery controllers distribute traffic across distributed microservices architectures in fintech and e-commerce deployments.
- NICs:SmartNICs and DPUs are unifying compute offload with network virtualization, collapsing server and network procurement decisions into single infrastructure teams.
Today's leader: Switches. Tomorrow's challenger: NICs.
Deployment Model:
Capital commitment tolerance varies dramatically between established enterprises depreciating owned assets and fintech entrants seeking consumption-based elasticity.
- On-Premises:Foreign cloud operators maintain certified domestic routing infrastructure to satisfy DICT data localization provisions under the National Cybersecurity Plan. These deployments require three-year depreciation cycles and dedicated facilities engineering teams.
- Colocation:Financial services firms are expanding footprints in Clark Freeport Zone facilities to meet digital banking mandates for real-time transaction processing. Tenants procure cross-connects and inter-rack switching while outsourcing power and cooling redundancy.
- Hybrid:Enterprises bridge owned campus switching with cloud burst capacity for seasonal demand spikes in retail and logistics applications.
- Cloud-based:Elastic networking contracts indexed to monthly peak throughput are gaining share fastest among fintech entrants avoiding hardware depreciation commitments.
Established infrastructure: On-Premises and Colocation. Fastest climb: Cloud-based.
End User:
Compliance burden intensity separates segments, with regulated industries funding redundant fabric investments that latency-sensitive applications demand.
- Financial Services:Digital banking mandates compel real-time transaction processing infrastructure with sub-5-microsecond latency targets. Colocation tenants pre-qualify vendors based on native SIEM integration to satisfy National Privacy Commission audit requirements.
- IT & Telecommunications:Service providers deploy intent-based automation at network edges, though talent scarcity in API-driven fabric management constrains rollout velocity. Edge deployments concentrate in Cavite corridor facilities adjacent to submarine cable landing stations.
- Retail:E-commerce platforms prioritize elastic capacity for promotional traffic spikes, favoring consumption-based networking contracts over capital purchases.
- Government:Critical information infrastructure designation under DICT frameworks triggers mandatory on-premises routing for designated sectors.
Current spend concentration: Financial Services. Steepest expansion trajectory: IT & Telecommunications.
Technology:
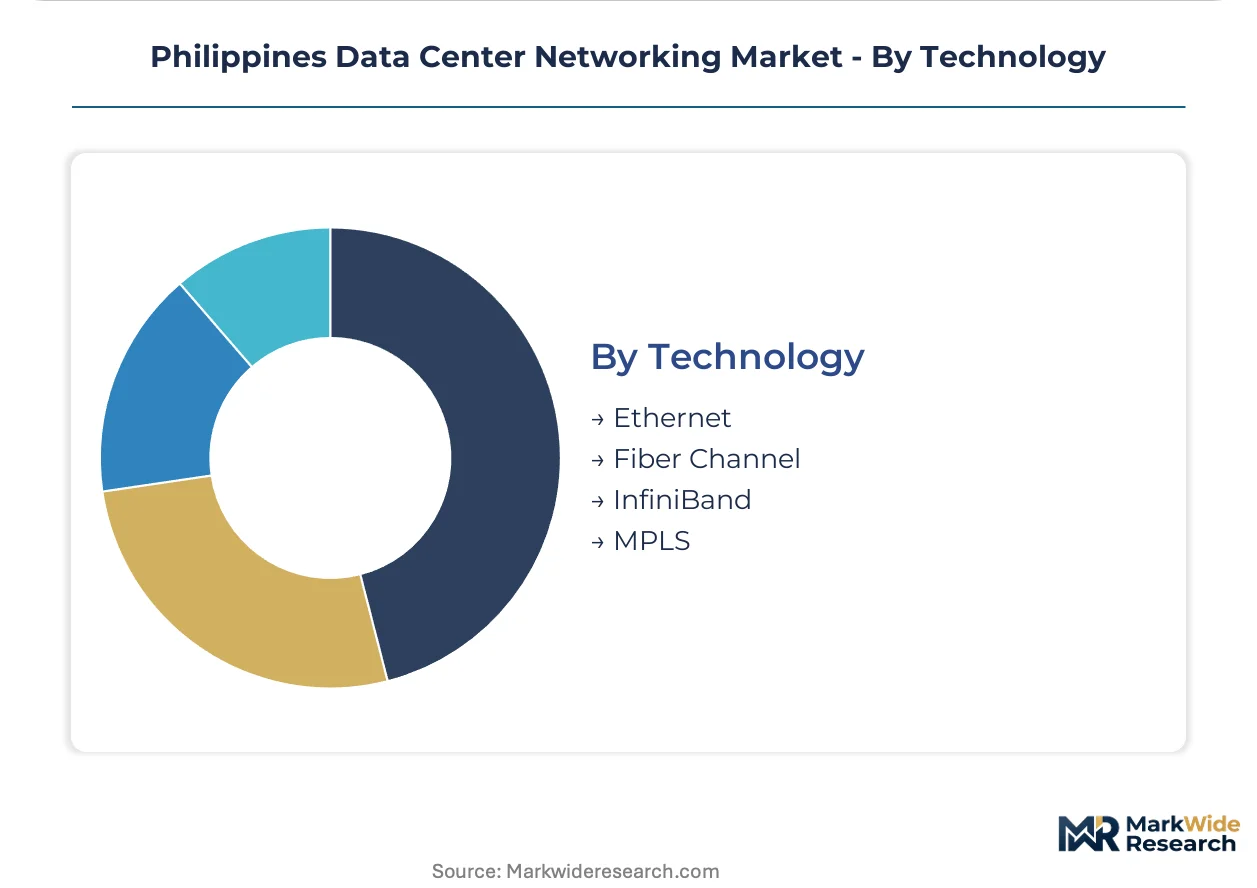
Interconnect protocols stratify by workload type, with general-purpose traffic and high-performance computing demanding fundamentally different fabric designs.
- Ethernet:Universal compatibility with hyperscale topologies drives volume leadership, with 25G server access and 100G/400G spine interconnects standard in Clark corridor builds. Equipment must pre-certify for tropical-humidity deployment before vendor bidding.
- InfiniBand:GPU clusters for AI training in Batangas and Pampanga are accelerating adoption for east-west traffic between compute nodes, gaining share fastest among interconnect technologies. Low-latency RDMA capabilities support distributed training workloads.
- Fiber Channel:Storage area networking persists in legacy enterprise deployments migrating from three-tier hierarchical switching architectures.
- MPLS:Service provider backbones maintain traffic engineering for multi-tenant colocation environments with guaranteed SLA tiers.
Dominant installed base: Ethernet. Emerging disruptor: InfiniBand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center networking infrastructure in the Philippines traces its modern lineage to submarine cable investments beginning in the early 2000s, with facilities clustering around landing stations to minimize latency and backhaul costs.
Metro Manila
Financial services firms drive demand for redundant switching fabrics with sub-5-microsecond latency targets to satisfy digital banking mandates. The National Privacy Commission enforces breach-notification timelines that compel real-time telemetry deployment. Hyperscale builds concentrate in the Clark Freeport Zone and Cavite corridor adjacent to submarine cable landing stations.
Central Luzon
GPU clusters for AI training in Pampanga accelerate InfiniBand adoption for east-west traffic between compute nodes. DICT cybersecurity frameworks mandate domestic traffic inspection capabilities at border routing infrastructure. The Clark corridor hosts pre-certified equipment deployments for tropical-humidity environments.
Calabarzon
Batangas facilities serve latency-sensitive workloads requiring proximity to submarine cable terminations without Metro Manila power grid congestion. Bureau of Product Standards certification delays extend equipment approval timelines by four to eight months for tropical-environment deployment. Industrial parks in Laguna and Cavite attract colocation tenants seeking geographic diversity.
Mindanao
Secondary submarine cable landing stations in Davao and Cagayan de Oro offer greenfield build opportunities outside Luzon's congested infrastructure. The DICT National Cybersecurity Plan's data localization provisions create captive demand for certified domestic routing. Power availability and lower land costs attract operators seeking expansion capacity.
Visayas
Cebu serves as a regional interconnection hub for submarine cables linking Luzon and Mindanao. Service providers deploy intent-based automation at network edges, though talent scarcity constrains rollout velocity. The island geography necessitates redundant switching fabrics to maintain connectivity during cable maintenance windows.
Philippines Data Center Networking Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integrated silicon-to-software stacks versus standalone hardware procurement. The vendor base stratifies between full-stack infrastructure providers, specialized switching fabric vendors, and component suppliers addressing discrete network layers. Three archetypes dominate: integrated platform vendors bundling silicon through software, automation specialists targeting service provider edge deployments, and low-latency fabric providers for hyperscale AI clusters. Competitive moves center on pre-certification for tropical-humidity deployment and modular consumption-based contract structures.
Within the integrated platform tier, Cisco Systems and Juniper Networks exemplify full-stack positioning through silicon-to-software bundling. Arista Networks occupies a specialist position in low-latency leaf-spine architectures. Huawei Technologies represents the vertically integrated alternative with captive component supply. These three anchors illustrate how procurement patterns bifurcate between bundled platform commitments and best-of-breed fabric specialization.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks |
| Huawei Technologies |
| VMware |
| Arista Networks |
| Hewlett Packard Enterprise |
| IBM |
| Schneider Electric |
| NVIDIA |
| Others |
Pricing and Supply Chain Analysis
SmartNIC integration into server procurement cycles is collapsing traditional switching cost structures while concentrating bargaining power among hyperscale buyers in the Clark corridor. This silicon convergence simultaneously compresses hardware margins and rewards vendors with captive software stacks.
Pricing Analysis
Consumption-based networking contracts indexed to monthly peak throughput dominate fintech procurement, displacing capital purchase models. Three-tier pricing structure across premium, standard, and economy levels separates DICT-certified equipment from pre-certified tropical-humidity gear and commodity campus switching. Price differentiation rests on certification grade and embedded telemetry capabilities. Margins are tightening due to foundry capacity allocation volatility in East Asian semiconductor hubs. Retail and logistics segments show highest price sensitivity; financial services colocation tenants accept premium positioning for SIEM-native integration.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators mandate multi-supplier qualification for 400G leaf-spine fabrics, fragmenting vendor concentration. Component supply draws from Taiwan, South Korea, and USA for advanced switching silicon; copper interconnects and power supplies source from China and Vietnam. Raw material dependencies include 7nm/5nm foundry wafers, high-speed optical transceivers, and tropical-grade conformal coatings. Single-source vulnerability persists for merchant silicon from TSMC-class foundries. Distribution runs through direct vendor relationships with hyperscale infrastructure teams and systems integrators serving enterprise colocation tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines data center networking market compounds steadily as DICT localization mandates create structural demand for certified domestic infrastructure regardless of macro cycles.
For Market Incumbents: Hedge against SmartNIC-driven procurement consolidation by deepening software subscription attach rates and pre-certifying equipment portfolios for Bureau of Product Standards tropical-humidity testing. Defensive moves include captive supply agreements with Taiwanese foundries and telemetry integration partnerships with SIEM vendors serving financial services tenants. Certification investment represents the priority lever against emerging automation specialists. For New Entrants and Emerging Players: Cloud-based consumption models offer the most penetrable route for fintech entrants seeking elastic capacity without depreciation commitments. White-space targets include Mindanao secondary landing stations in Davao and Cagayan de Oro, where greenfield builds escape Metro Manila power grid constraints. Intent-based automation talent scarcity creates entry opportunity for API-native vendors. Go-to-market positioning should emphasize consumption-based contracts with monthly throughput indexing. For Investors and Strategic Acquirers: Roll-up economics work for regional colocation operators because DICT cybersecurity frameworks fragment infrastructure ownership across mandatory on-premises and certified colocation tiers. Long-term viability centers on facilities with submarine cable adjacency and pre-certified tropical deployment capabilities. Acquisition target archetype: mid-scale Clark corridor operators with 100G-ready interconnection and DICT compliance infrastructure. The signal to watch is Bureau of Product Standards certification queue length as indicator of vendor competitive position.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Investment | Bureau of Product Standards tropical-humidity approval compresses vendor bidding cycles by four to eight months. |
| SIEM Platform Integration | Native telemetry export satisfies National Privacy Commission breach-notification mandates for financial services tenants. |
| Consumption-Based Contracting | Monthly peak throughput indexing transfers refresh risk to vendors while capturing fintech elasticity demand. |
| Mindanao Geographic Expansion | Secondary submarine cable landing stations in Davao offer power-cost advantages outside Luzon's congested grid. |
| SmartNIC-DPU Convergence | Single-chip compute offload unifies server and network procurement decisions under hyperscale infrastructure teams. |
Research Methodology
Direct dialogue with data center facility engineers, network architects at hyperscale operators, procurement leads at financial services colocation tenants, and DICT compliance officers grounded qualitative findings. Secondary validation drew from DICT National Cybersecurity Plan documentation, Bureau of Product Standards certification records, submarine cable landing station operator disclosures, and hyperscaler capex filings. Bottom-up and top-down triangulation cross-checked port shipment estimates against facility power allocation permits.
Bottom-up modeling segmented by product type, deployment model, end user, and technology across the analysis window. Segmentation dimensions included switching fabric speed tier, DICT compliance status, and geographic cluster proximity to submarine cable terminations. CAGRs were derived from facility pipeline tracking and equipment procurement cycle analysis. Forecast inputs incorporated GPU cluster deployment timelines in Batangas and Pampanga, plus fintech licensing velocity under digital banking mandates.
The model assumes a particular technology adoption path; alternative pathways for InfiniBand versus Ethernet in AI training clusters would alter the outlook. Forecasts reflect assumptions regarding DICT critical infrastructure designation expansion and Bureau of Product Standards certification timeline stability. Deviation in foundry capacity allocation or submarine cable landing station permitting would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
United States Data Center Networking Market