
 Mobile Data Market | 2026-2036
Mobile Data Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Data Market Intelligence
Enterprise buyer concentration is decoupling from traditional consumer-centric revenue models as multinational corporations negotiate direct private 5G contracts with carriers. AT&T leverages its fiber backhaul integration to anchor large-scale enterprise deployments across North American manufacturing corridors. Reliance Jio Infocomm Limited dominates India's price-sensitive mass market through its proprietary 4G infrastructure while extending into enterprise IoT verticals.
Mobile data encompasses wireless information transmission across cellular architectures operating from 600 MHz to 39 GHz spectrum bands, utilizing packet-switched core networks to deliver IP-based services to endpoint devices. Its primary commercial purpose is enabling real-time connectivity for applications ranging from streaming media to industrial automation control systems. The 5G service type segment captures the dominant share of carrier capital expenditure as enterprises demand ultra-reliable low-latency connectivity for autonomous systems and remote operations. IoT devices represent the fastest-expanding device type category, with agricultural sensors and fleet management units driving volume growth in emerging economies where smartphone penetration has plateaued.
The Federal Communications Commission in the United States and the Telecom Regulatory Authority of India both enforce spectrum allocation frameworks that directly determine which carriers can deploy next-generation services and at what cost basis. The European Union's GDPR and emerging AI Act create compliance layers for how mobile data flows are processed, stored, and monetized across carrier networks and third-party application ecosystems. Stakeholders must monitor how national security reviews of foreign network equipment reshape supplier eligibility and deployment timelines across major markets.
Market Dynamics
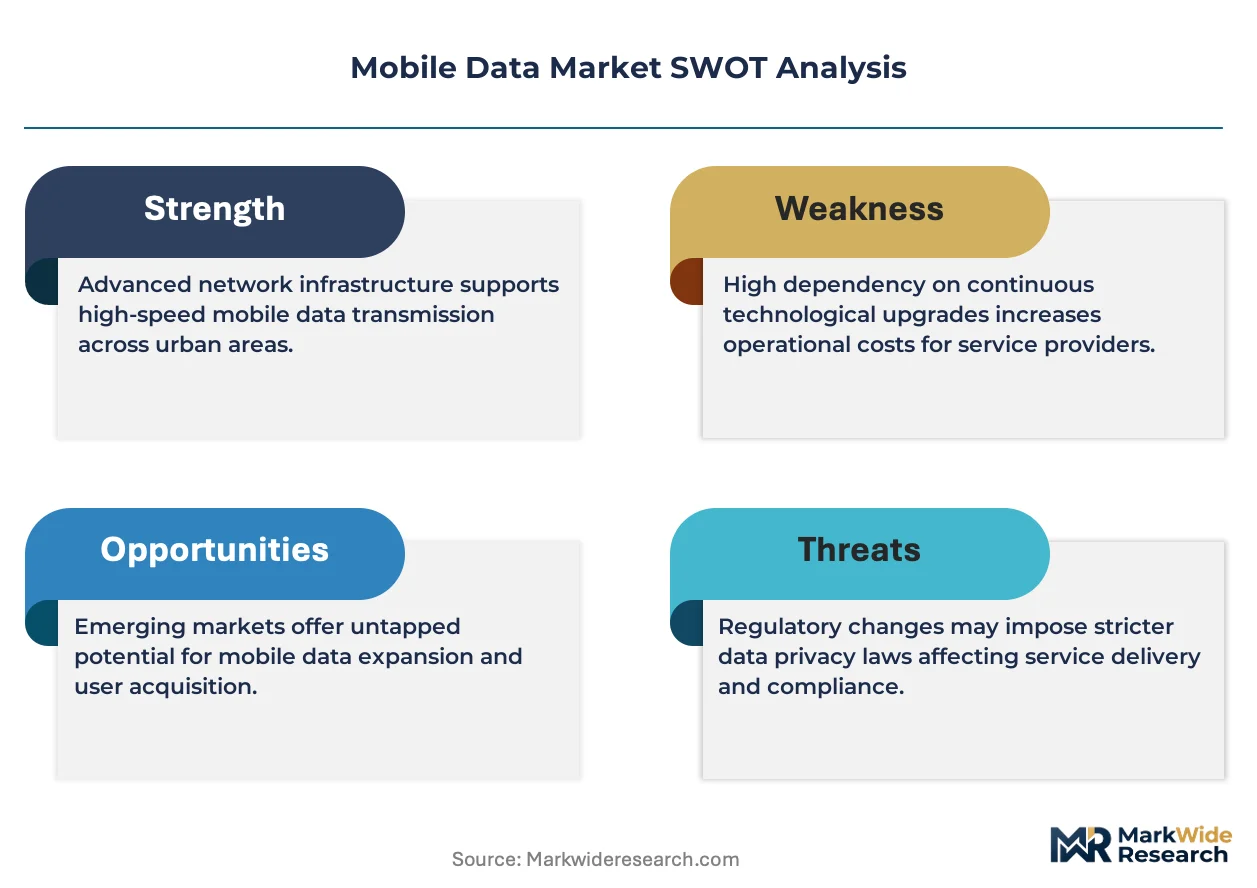
Enterprise demand for deterministic latency is compressing carrier infrastructure refresh cycles while fragmenting procurement authority between CIOs and operational technology managers.
Growth Catalysts
- Private 5G spectrum frameworks:Germany's BNetzA and the FCC in the United States have opened localized licensing regimes that let manufacturers bypass public network congestion for industrial automation.
- Cloud-native core architectures:Containerized packet cores reduce deployment timelines from months to weeks, letting carriers provision network slices for enterprise IoT verticals on demand.
- India:TRAI's zero-touch provisioning mandates and Reliance Jio's fiber backhaul density have compressed rural connectivity costs below viable thresholds for agricultural sensor networks.
Market Restraints
- Semiconductor supply concentration:Advanced baseband processor fabrication depends on a single geography for leading-edge nodes, creating equipment delivery uncertainty.
- Site acquisition friction:Municipal zoning boards and aviation authorities impose multi-year delays on millimeter-wave small cell densification in urban corridors.
- Energy cost volatility:Radio access network power consumption scales linearly with traffic load, exposing carriers to input cost swings that tariff structures cannot immediately pass through.
Strategic Opportunities
- Brazil:ANATEL's delayed but advancing 5G standalone auction creates first-mover positioning for infrastructure vendors willing to localize manufacturing under the country's telecom incentive framework.
- Network-as-a-service models:Hyperscalers are embedding cellular connectivity into cloud marketplaces, letting enterprises procure private mobile infrastructure through existing IT procurement channels.
- AI-driven radio resource management:Converging machine learning inference at the edge with real-time spectrum sensing is opening sub-millisecond optimization loops that static policies cannot achieve.
Industry Challenges
- RF engineering talent scarcity:The shift to massive MIMO and beamforming architectures has outpaced university programs producing antenna design specialists.
- Multi-vendor interoperability certification:Open RAN disaggregation promises supplier diversity but extends integration testing timelines as carriers validate disaggregated component combinations.
- Legacy billing system migration:Usage-based pricing for network slices requires real-time charging platforms that many carriers have deferred modernizing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Data Market |
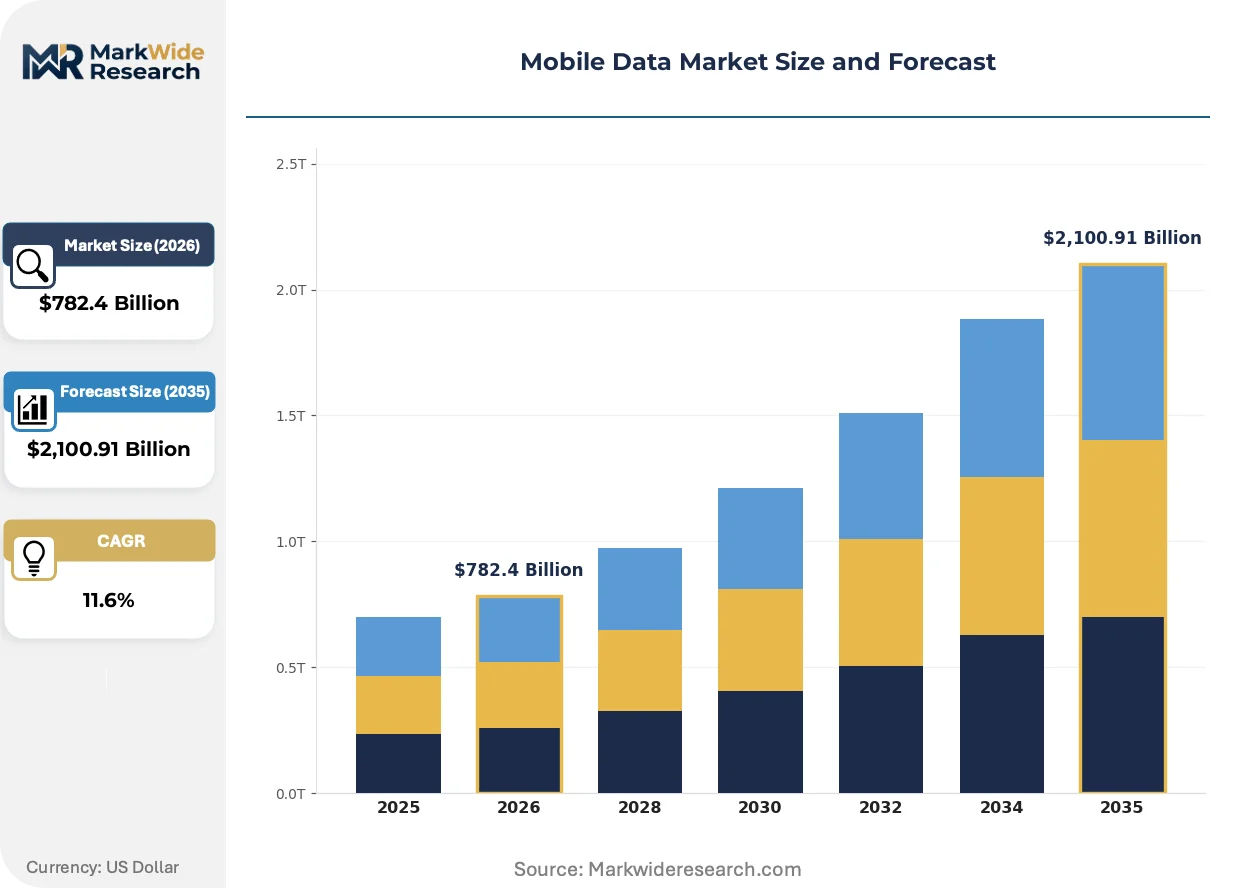
| Market Size in 2026 | $782.4 Billion |
| Market Size in 2035 | $2,100.91 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
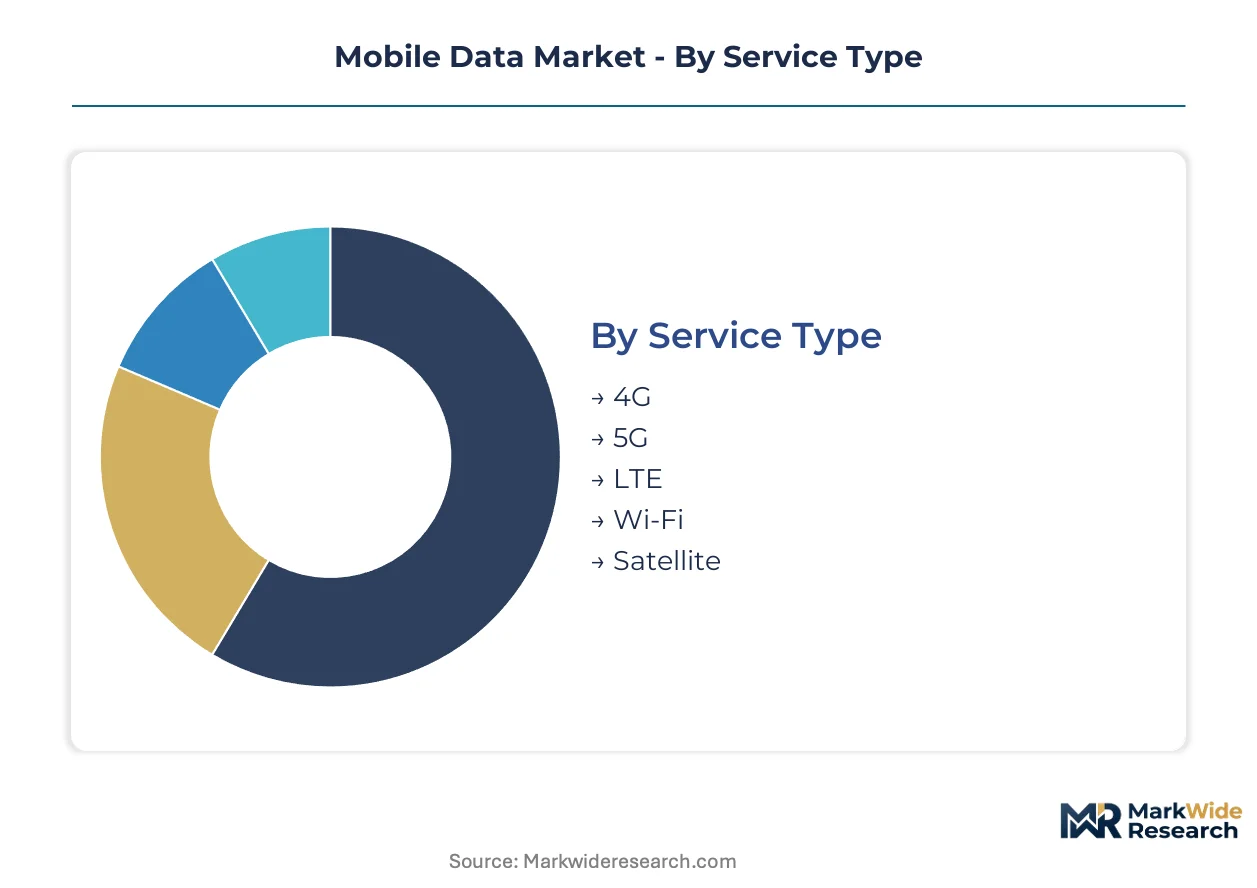
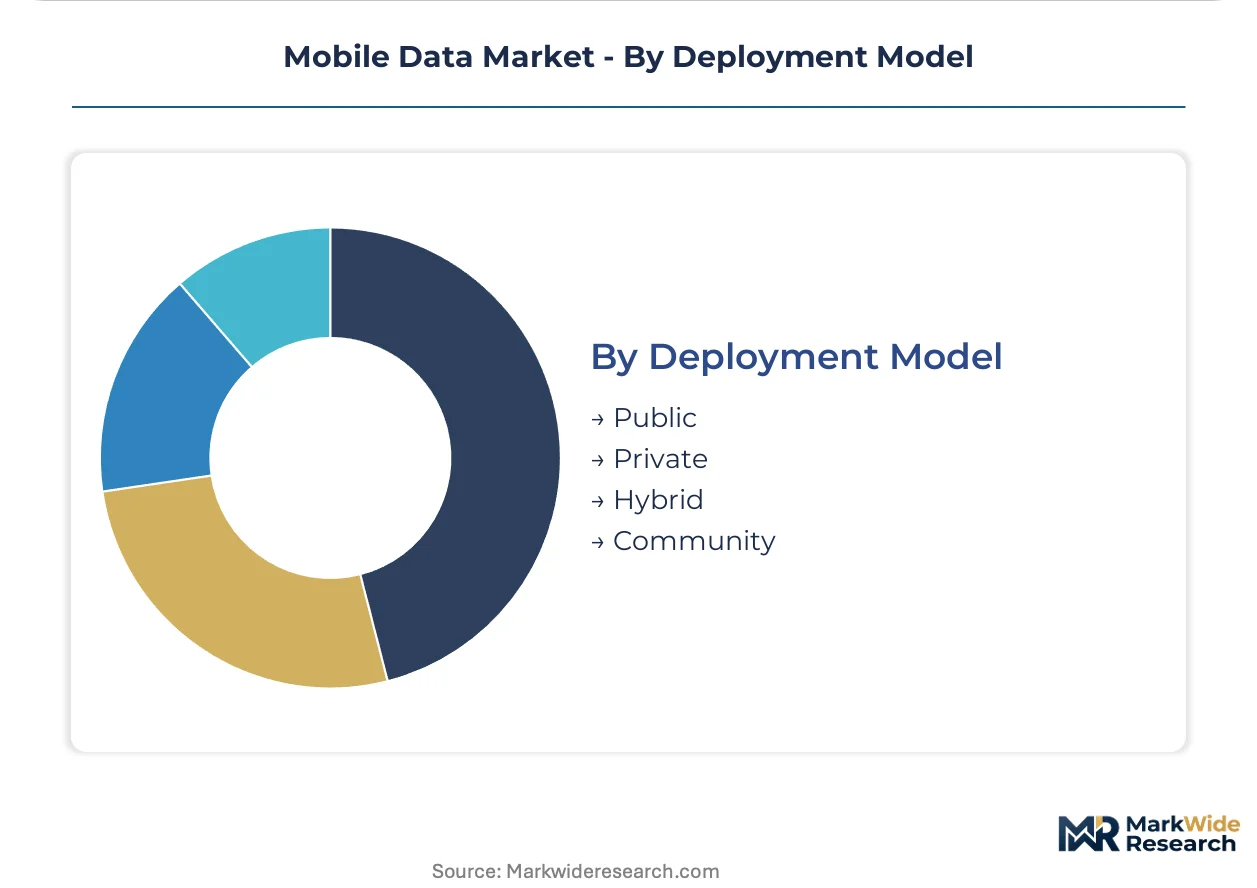
| Segmentation | Service Type: 4G, 5G, LTE, Wi-Fi, Satellite End User: Consumers, Enterprises, Government, Educational Institutions Device Type: Smartphones, Tablets, Laptops, IoT Devices Deployment Model: Public, Private, Hybrid, Community |
| Companies Covered | China Mobile Communications Corporation, AT&T Inc., Verizon Communications Inc., China Telecom Corp., Ltd., Reliance Jio Infocomm Limited, Deutsche Telekom AG, Vodafone Group Plc, Nippon Telegraph and Telephone Corporation, T-Mobile US Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Data Market Strategic Shifts & Innovations
Convergence between connectivity and compute layers is dissolving traditional boundaries between telecom infrastructure and cloud service delivery, forcing architectural decisions that will determine carrier relevance.
Standalone 5G core networks with cloud-native function decomposition are unifying control plane and user plane scaling. Manufacturing facilities in the German Ruhr and automotive corridors outside Stuttgart are deploying these architectures to guarantee sub-10 millisecond latency for robotic coordination. The structural consequence is compressing the addressable market for traditional network equipment vendors who cannot match software iteration velocity.
The European Union's AI Act imposes risk-classification obligations on mobile networks processing automated decision-making traffic. Carriers must now document algorithmic transparency for network optimization routines affecting safety-critical applications. Medical device manufacturers in Ireland and industrial automation suppliers in the Netherlands are demanding contractual indemnification clauses that shift compliance liability upstream.
Enterprise buyers are consolidating mobile connectivity procurement under existing cloud service contracts rather than negotiating separate carrier agreements. Manufacturing and logistics verticals in the United States Midwest are purchasing private 5G as a bundled infrastructure-as-a-service line item through AWS, Azure, and Google Cloud marketplaces. This channel migration is compressing carrier direct sales organizations while expanding hyperscaler influence over network architecture specifications.
Mobile Data Market Segmentation
Carrier investment priorities diverge sharply across service tiers and deployment models, with regulatory frameworks dictating which segments justify capital allocation. Enterprise procurement patterns now favor deterministic performance guarantees over consumer-grade throughput metrics.
Service Type:
5G deployments require FCC Part 27 licensing in the United States, 3.5 GHz CBRS General Authorized Access for private networks, and national spectrum harmonization under EU Radio Spectrum Policy Group guidelines. 4G and LTE segments operate under grandfathered allocations with lighter compliance burdens.
- 5G:Ultra-reliable low-latency connectivity utilizing sub-6 GHz and millimeter-wave spectrum bands. Manufacturing facilities in Germany's Ruhr region and automotive corridors outside Stuttgart deploy these architectures for robotic coordination requiring sub-10 millisecond latency guarantees.
- 4G:Packet-switched LTE-Advanced networks delivering 100+ Mbps peak rates through carrier aggregation. Reliance Jio's proprietary infrastructure in India anchors mass-market connectivity where fiber backhaul density has compressed rural deployment costs below viable thresholds for agricultural monitoring.
- LTE:Evolved packet core networks providing fallback capacity and machine-type communication compatibility.
- Wi-Fi:Unlicensed 2.4 GHz and 5 GHz spectrum for indoor offload and enterprise local area networking.
- Satellite:Geostationary and low-earth-orbit constellations extending coverage to maritime and remote terrestrial zones.
4G sits at the top of the volume ranking, with 5G climbing the fastest as enterprise deterministic latency requirements displace legacy provisioning models.
End User:
Enterprise and government segments command premium pricing through dedicated network slices, while consumer volumes drive infrastructure amortization across shared radio access networks.
- Enterprises:Multinational corporations negotiate direct private 5G contracts bypassing public network congestion. AT&T leverages fiber backhaul integration to anchor large-scale deployments across North American manufacturing corridors where operational technology managers now share procurement authority with CIOs.
- Consumers:Individual subscribers purchasing connectivity through retail channels with usage-based or unlimited tariff structures. India's price-sensitive mass market concentrates demand through Reliance Jio's aggressive pricing, triggering nationwide digital transformation in tier-2 and tier-3 cities.
- Government:National security and public safety networks requiring encrypted priority access during emergency conditions.
- Educational Institutions:Campus-wide connectivity provisioning for hybrid learning environments and research collaboration platforms.
Consumers generate the highest absolute traffic volumes, though enterprises exhibit the steepest expansion trajectory as cloud-native core architectures compress deployment timelines.
Device Type:
Smartphone certification through FCC OET and EU RED conformity assessment represents the baseline compliance threshold, while IoT devices face additional cybersecurity labeling requirements under emerging national frameworks.
- IoT Devices:Agricultural sensors and fleet management units operating on narrowband-IoT and LTE-M protocols. Emerging economies deploy these at volume where smartphone penetration has plateaued, with TRAI's zero-touch provisioning mandates in India enabling automated rural connectivity activation.
- Smartphones:Handheld endpoints consuming streaming media, cloud applications, and real-time communications services. 5G-capable models now dominate replacement cycles in the United States, Germany, and South Korea as carriers sunset legacy network generations.
- Tablets:Larger-format mobile computing devices for field workforce productivity and entertainment consumption.
- Laptops:Cellular-enabled portable computers supporting untethered enterprise productivity and remote collaboration.
Smartphones retain the dominant installed base position, with IoT devices gaining share fastest as industrial automation and precision agriculture applications proliferate.
Deployment Model:
Private deployments require localized spectrum licensing under Germany's BNetzA framework or FCC Part 96 CBRS rules, while public networks operate under national carrier concessions with universal service obligations.
- Private:Localized 5G networks dedicated to single-tenant industrial or campus environments. Manufacturing facilities purchase these through AWS, Azure, and Google Cloud marketplaces as bundled infrastructure-as-a-service line items, compressing carrier direct sales organizations while expanding hyperscaler architectural influence.
- Public:Shared commercial infrastructure serving heterogeneous subscriber bases with standardized service level agreements. Municipal zoning boards and aviation authorities impose multi-year delays on millimeter-wave small cell densification, constraining capacity expansion in urban corridors.
- Hybrid:Architectures combining private edge computing with public network backhaul for cost-optimized coverage.
- Community:Cooperative ownership models for rural and underserved area connectivity provisioning.
Public infrastructure accounts for the overwhelming majority of connected devices, yet private networks demonstrate the most rapid adoption curve as enterprises seek deterministic latency guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridors drive private 5G adoption at triple the pace of Brazil's emerging auction markets, while India's rural digital transformation compresses connectivity costs below thresholds seen elsewhere.
United States
Manufacturing facilities across Michigan and Ohio demand deterministic latency for robotic coordination, while logistics hubs in the Midwest consolidate procurement under cloud marketplace contracts. The FCC's Part 27 licensing and CBRS General Authorized Access frameworks enable localized spectrum deployment. AT&T anchors large-scale enterprise deployments across these corridors through fiber backhaul integration.
Germany
Automotive suppliers and steel producers in the Ruhr region require sub-10 millisecond latency guarantees for production line synchronization. BNetzA's localized licensing regime lets manufacturers bypass public network congestion through private spectrum allocation. Stuttgart's automotive corridor exemplifies this deployment model, with suppliers purchasing network slices as infrastructure-as-a-service.
India
Agricultural sensor networks and tier-2 city digital services expand addressable markets where smartphone penetration has plateaued. TRAI enforces zero-touch provisioning mandates that automate rural connectivity activation. Reliance Jio's proprietary infrastructure and fiber backhaul density in Maharashtra and Gujarat compress deployment economics below viable thresholds for precision farming applications.
China
Industrial IoT verticals and smart manufacturing clusters drive spectrum utilization across sub-6 GHz allocations. MIIT coordinates national spectrum harmonization under standards that prioritize equipment from domestic vendors. The Yangtze River Delta manufacturing belt concentrates private network deployments for semiconductor fabrication and automotive assembly.
Brazil
Infrastructure vendors target first-mover positioning ahead of ANATEL's advancing 5G standalone auction timeline. The country's telecom incentive framework mandates localized manufacturing commitments for spectrum access. São Paulo's industrial suburbs and Rio de Janeiro's port logistics zones represent initial deployment candidates for private network pilots.
Mobile Data Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across infrastructure deployment, spectrum licensing, and enterprise service provisioning. Tier-1 carriers with integrated fiber and wireless assets anchor large-scale contracts, while regional specialists capture price-sensitive mass markets through proprietary infrastructure builds. Strategic moves concentrate on cloud-native core partnerships and hyperscaler marketplace integration, with secondary emphasis on private spectrum acquisition.
Within the integrated infrastructure tier, China Mobile Communications Corporation and Verizon Communications Inc. occupy positions spanning consumer and enterprise segments. Deutsche Telekom AG exemplifies the European carrier archetype balancing public network obligations with private 5G specialization. AT&T Inc. and Reliance Jio Infocomm Limited represent contrasting geographic anchors, with the former leveraging North American fiber density and the latter compressing emerging market economics through vertical infrastructure control.
| Leading Market Players |
|---|
| China Mobile Communications Corporation |
| AT&T Inc. |
| Verizon Communications Inc. |
| China Telecom Corp., Ltd. |
| Reliance Jio Infocomm Limited |
| Deutsche Telekom AG |
| Vodafone Group Plc |
| Nippon Telegraph and Telephone Corporation |
| T-Mobile US Inc. |
| Others |
Cost & Logistics Intelligence
Enterprise-consumer bifurcation in connectivity provisioning creates divergent margin structures across carrier portfolios. Premium private 5G contracts for manufacturing automation command pricing multiples over mass-market consumer tariffs, while supply chain configurations split between hyperscaler-integrated cloud cores and proprietary radio access network builds.
Pricing Analysis
Capacity additions in India are reshaping price floors for emerging market connectivity as Reliance Jio's fiber backhaul density compresses rural deployment economics. Three-tier pricing structure across premium enterprise slices, standard consumer unlimited plans, and economy feature-phone tiers anchors carrier revenue models. Cost compression in consumer segments intensifies because spectrum auction debt service demands volume scaling. Government and enterprise buyers exhibit lowest price sensitivity due to deterministic latency requirements, while agricultural IoT deployments in tier-2 Indian cities show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced baseband processor fabrication at leading-edge nodes. Radio access network equipment draws from China, Finland, and Sweden for antenna systems and packet core software. Tariff exposure on semiconductor components creates equipment delivery uncertainty for millimeter-wave small cell densification. Distribution runs through carrier direct sales organizations for enterprise contracts and retail channel partners for consumer subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where enterprise demand for sub-10 millisecond latency guarantees is displacing consumer throughput metrics as the primary value driver.
For Market Incumbents: To counter hyperscaler marketplace encroachment, anchor fiber backhaul integration in North American manufacturing corridors and accelerate cloud-native core certification for EU AI Act compliance. Prioritize real-time charging platform modernization to capture usage-based network slice revenue.
For New Entrants and Emerging Players: Hyperscaler channel partnerships offer the most penetrable entry vector for private 5G provisioning in German automotive corridors and Brazilian industrial suburbs awaiting ANATEL standalone auction completion. Target agricultural sensor network deployments in Indian states where TRAI zero-touch provisioning mandates have automated rural activation workflows.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional carriers possessing localized spectrum holdings and fiber backhaul density in underserved manufacturing belts. Five-to-ten year viability hinges on successful enterprise slice monetization rather than consumer ARPU recovery. Monitor FCC Part 96 CBRS license transfer volumes as inflection indicator for private network adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Migration | Containerized packet cores reduce German automotive supplier deployment timelines from months to weeks. |
| Private Spectrum Acquisition | FCC Part 96 CBRS licenses enable Michigan manufacturers to bypass public network congestion. |
| Hyperscaler Marketplace Integration | AWS and Azure channels compress carrier direct sales cycles for Midwest logistics hub contracts. |
| AI-Driven Radio Resource Management | Machine learning inference at the edge opens sub-millisecond optimization loops for robotic coordination. |
| Backward Integration into Fiber Backhaul | Captive fiber density in Maharashtra anchors Reliance Jio's agricultural sensor network economics. |
Research Approach
Multiple input streams — carrier capex disclosures, regulatory filing databases, and equipment vendor order backlogs — were reconciled across primary interviews with network planning executives, enterprise CIOs, and spectrum auction specialists. Secondary validation drew from FCC licensing records, TRAI consultation papers, BNetzA frequency allocation tables, and 3GPP standardization timelines. Bottom-up subscriber and traffic projections were triangulated against top-down carrier revenue forecasts.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation modeled by service type, deployment model, end-user vertical, and device category. CAGRs were derived from logistic diffusion curves fitted to 5G population coverage and enterprise adoption S-curves. Spectrum auction schedules and hyperscaler marketplace partnership announcements served as industry-specific forecast inputs.
Revisions become necessary when semiconductor supply constraints extend equipment delivery timelines or when national security reviews disqualify network equipment suppliers. Forecasts reflect documented assumptions about spectrum allocation timelines and enterprise procurement channel migration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Nigeria Data Center Networking Market