
 Managed DNS Services Market | 2026-2036
Managed DNS Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed DNS Services Market Intelligence
Market Context
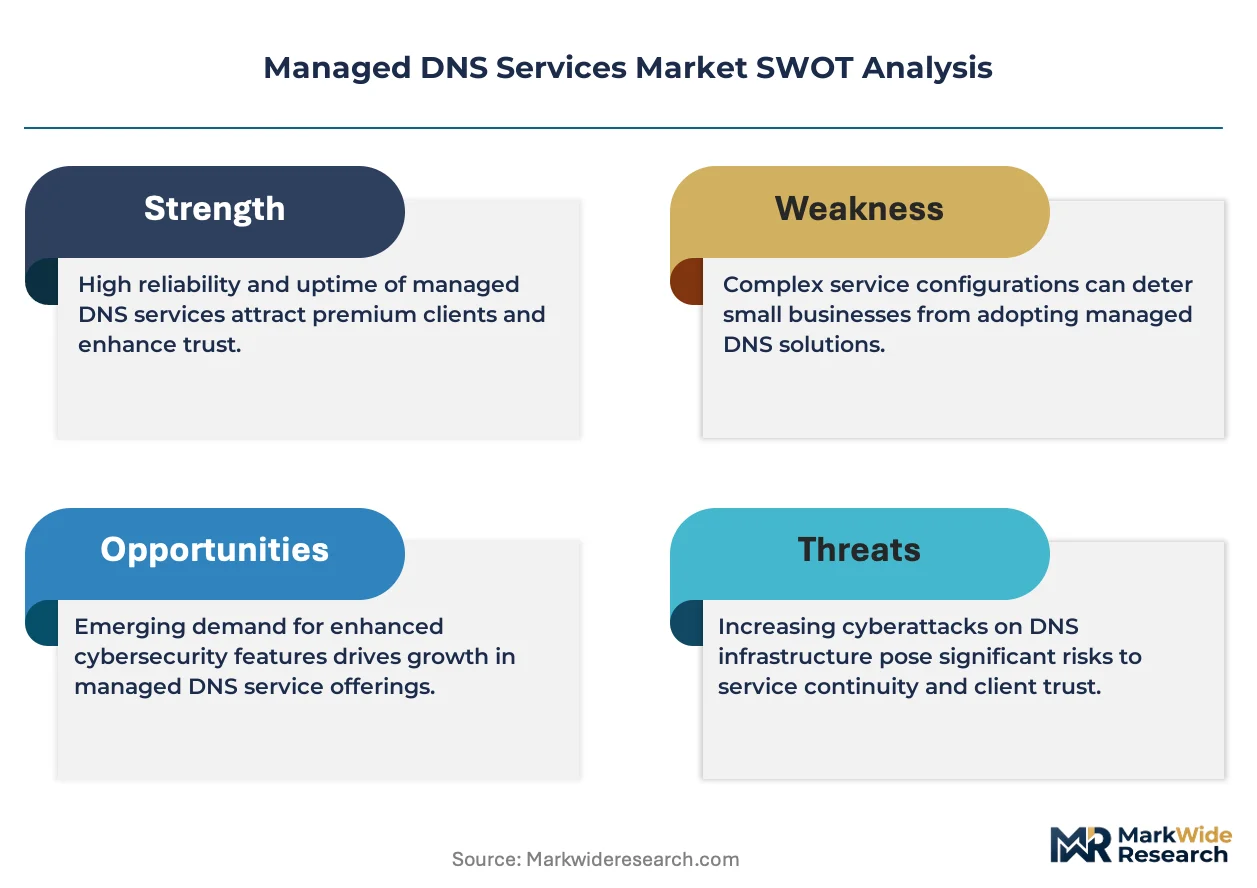
IPv6 address space is realigning how DNS providers architect resolution infrastructure for next-generation connectivity. Cloudflare DNS leverages anycast routing density to sustain sub-millisecond response times across its edge footprint. Google Cloud DNS anchors enterprise trust through deep integration with its broader cloud identity stack. IBM NS1 Connect differentiates via traffic steering intelligence that competes on application-layer granularity rather than raw query volume.
Technical Definition and Segment Structure
Managed DNS services are externally hosted domain name resolution platforms that translate human-readable hostnames into IP addresses using distributed server networks operating at the application layer of internet infrastructure, typically guaranteeing availability through redundant anycast topologies and automated failover protocols. Authoritative DNS commands the largest revenue share as enterprises delegate primary zone management to specialists rather than maintaining in-house BIND or PowerDNS implementations. Cloud-based deployment absorbs the fastest growth trajectory as DevOps teams embed DNS provisioning into infrastructure-as-code pipelines. DDoS protection use cases concentrate margin pools because mitigation capabilities command premium pricing above baseline resolution contracts.
Regulatory Environment and Outlook
FCC net neutrality rulings in the United States shape how DNS providers prioritize traffic and disclose routing policies to enterprise customers. GDPR and the EU AI Act impose data residency and algorithmic transparency obligations on European DNS operations handling personally identifiable query logs. NIS2 Directive mandates incident reporting timelines that force telecommunication providers and ISPs to reassess vendor resilience certifications. Stakeholders must monitor how fragmented national cybersecurity frameworks alter vendor qualification criteria before committing to multi-year infrastructure contracts.
Market Dynamics
Cloud-native application architectures are forcing enterprises to externalize DNS resolution from on-premise BIND deployments to distributed anycast networks that guarantee sub-second failover during regional outages.
Growth Catalysts
- EU NIS2 Directive:Incident reporting mandates compel German and French telecommunications operators to upgrade vendor resilience certifications, accelerating replacement cycles for legacy in-house DNS infrastructure.
- Financial services:Real-time payment networks in Frankfurt and London require traffic steering intelligence that routes queries around degraded paths without application-layer interruption.
- Edge computing density:Kubernetes clusters deployed at 5G base stations in Seoul and Tokyo generate localized resolution demands that recursive DNS caches cannot satisfy.
Market Restraints
- Input cost volatility:Anycast peering agreements with tier-1 transit providers in Amsterdam and Ashburn expose managed DNS operators to bandwidth pricing swings that compress margin on flat-rate enterprise contracts.
- Supply concentration:Root server mirror deployments cluster in Northern Virginia and Frankfurt, creating single-point-of-failure exposure for providers dependent on these facilities.
- Regulatory friction:GDPR data residency requirements prevent European enterprises from delegating zone management to providers with query logging infrastructure in US jurisdictions.
Strategic Opportunities
- Underpenetrated geography:Brazilian fintechs in São Paulo lack access to traffic steering granularity available in North American markets, creating whitespace for latency-optimized authoritative DNS.
- Technology convergence:Integration of DNS resolution telemetry with SIEM platforms enables security teams in Singapore to correlate query anomalies with lateral movement detection.
- Regulatory tailwind:India's CERT-In directive mandating DNSSEC deployment for critical infrastructure creates mandatory upgrade cycles that favor managed service providers over self-managed alternatives.
Industry Challenges
- Skill scarcity:Enterprise network engineers with expertise in both DNSSEC key rotation and cloud API orchestration command premium compensation that inflates internal platform build costs.
- Integration complexity:Hybrid cloud environments in Melbourne and Sydney require synchronization between on-premise Active Directory zones and cloud-native DNS records that automation tools handle inconsistently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed DNS Services Market |
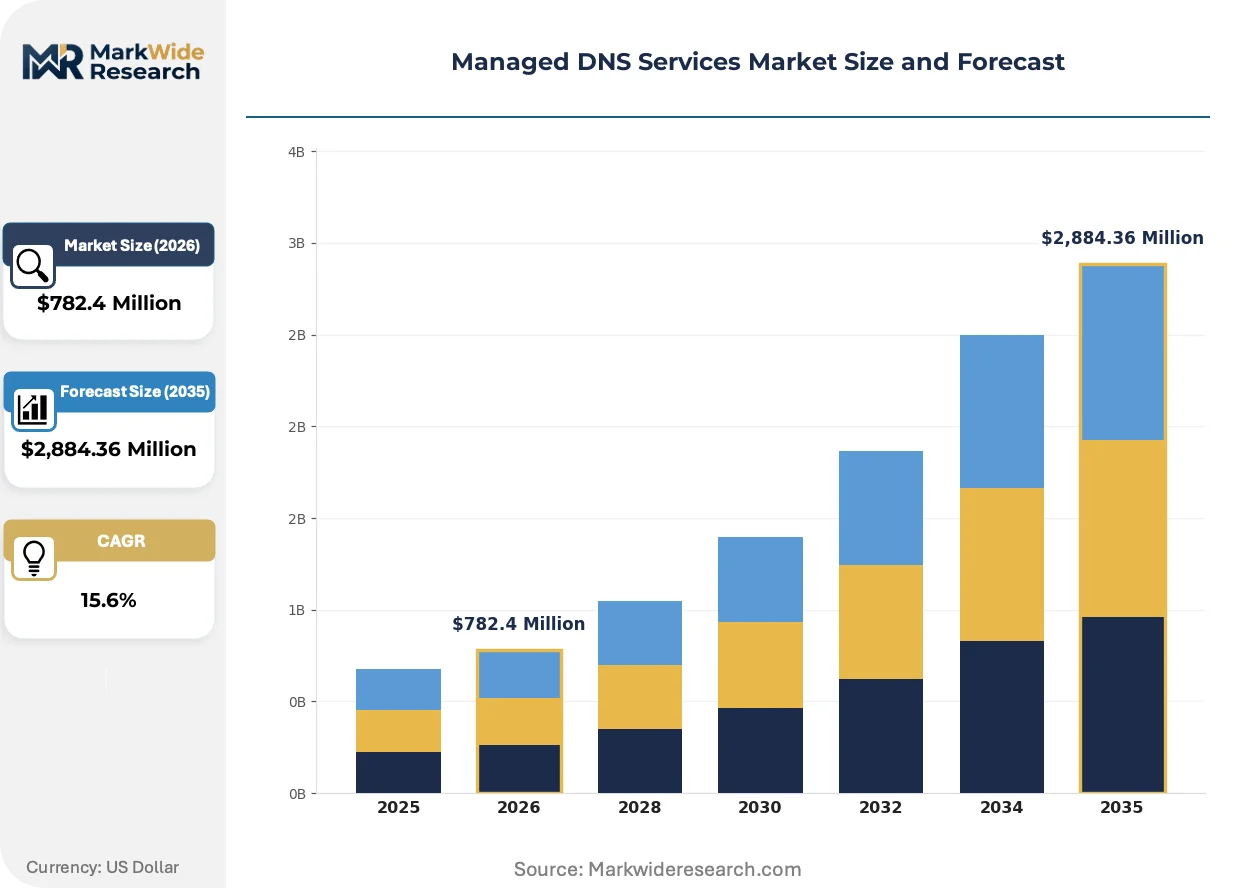
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $2,884.36 Million |
| CAGR (2026 – 2036) | 15.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Authoritative DNS, Recursive DNS, Forwarding DNS, Reverse DNS, Dynamic DNS, Secondary DNS Deployment Mode: Cloud-Based, Hybrid, On-Premises, Edge Computing Use Case: Website Acceleration, DDoS Protection, Traffic Load Balancing, Security Enhancements, Failover Management, Global Traffic Management End User Type: Telecommunication Providers, Internet Service Providers, Content Delivery Networks, Managed Service Providers, Enterprise Networks, Data Centers |
| Companies Covered | Namecheap, Vercara UltraDNS, Cloudflare DNS, Azure DNS, IBM NS1 Connect, DNS Made Easy, GoDaddy, Google Cloud DNS, ClouDNS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed DNS Services Market Strategic Shifts & Innovations
Traffic steering intelligence is migrating from simple geographic proximity rules to application-layer health checks that reroute queries based on real-time server performance metrics.
DNS-over-HTTPS (DoH) is electrifying privacy-sensitive enterprise segments by encrypting resolution requests at the transport layer. Healthcare systems in Boston and Chicago are mandating DoH compliance for all endpoint DNS traffic to prevent ISP-level query inspection. This encryption shift is compressing the addressable market for traditional recursive resolver vendors that lack TLS termination capabilities at scale.
The EU AI Act imposes algorithmic transparency obligations on DNS providers operating machine-learning-based anomaly detection systems. French and German regulators now require documentation of training data provenance for models that flag DDoS patterns. European managed DNS vendors are responding by segregating query logging infrastructure to EU-only regions and publishing model cards for traffic classification systems.
Consumption patterns among DevOps teams are favoring API-first provisioning over portal-based zone management. Platform engineering groups in Tel Aviv and Bangalore are embedding DNS record creation directly into Terraform pipelines, displacing manual change requests that previously routed through network operations centers. This self-service model is most visible in technology verticals where infrastructure-as-code maturity exceeds financial services by approximately eighteen months.
Managed DNS Services Market Segmentation
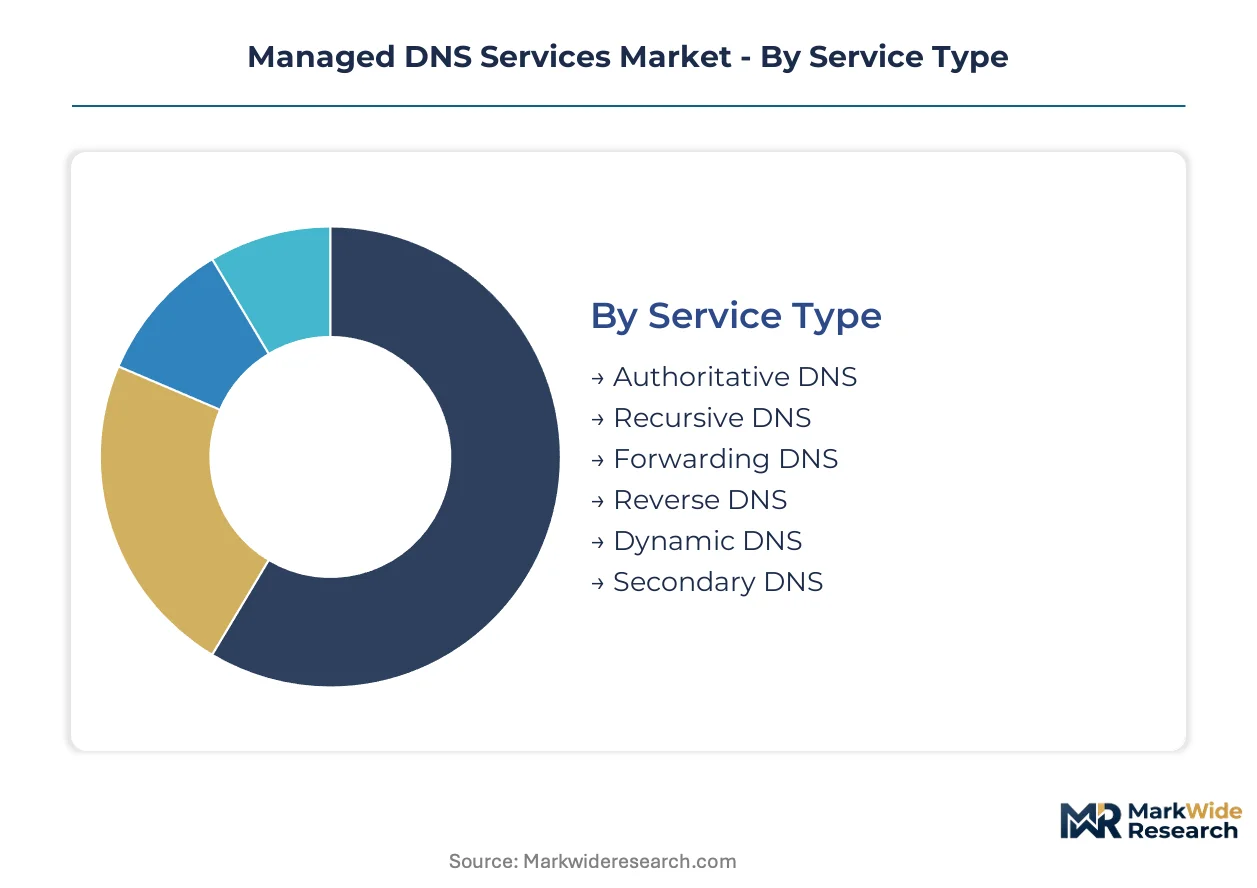
Managed DNS services fragment across multiple dimensions that determine architectural complexity, pricing models, and vendor selection criteria. Each segmentation axis reveals distinct commercial dynamics: service type dictates infrastructure investment requirements, deployment mode shapes operational control trade-offs, use case determines premium pricing eligibility, and end user type governs procurement sophistication and contract scale.
Service Type:
Customization intensity varies dramatically across this spectrum—from commoditized recursive resolution to highly tailored authoritative zone configurations requiring dedicated engineering support.
- Authoritative DNS:Primary zone hosting that responds definitively for domain ownership records, requiring redundant anycast topologies and automated failover protocols. Frankfurt financial services and London payment networks delegate critical zone management here to guarantee sub-second propagation during infrastructure failures. Leading the category by volume: Authoritative DNS. Growing fastest: Dynamic DNS.
- Recursive DNS:Caching resolver infrastructure that traverses the DNS hierarchy on behalf of endpoints, optimizing through localized edge deployment. Seoul and Tokyo 5G base station clusters generate concentrated demand that recursive caches at the edge struggle to satisfy.
- Forwarding DNS:Intermediate resolver configuration that delegates upstream resolution to designated upstream servers, common in segmented enterprise networks with compliance filtering requirements.
- Reverse DNS:PTR record management mapping IP addresses to hostnames, essential for email deliverability verification and security logging correlation in Singapore SIEM integrations.
- Dynamic DNS:Real-time record updates for hosts with non-static IP assignments, expanding most quickly among IoT device fleets and residential broadband applications where fixed addressing is cost-prohibitive.
- Secondary DNS:Slave zone replication providing redundancy against primary server failure, mandated by India's CERT-In directive for critical infrastructure operators requiring DNSSEC-backed resilience.
Volume concentration sits with authoritative services; steepest expansion trajectory belongs to dynamic resolution for ephemeral infrastructure.
Deployment Mode:
Control retention versus operational offload defines procurement decisions across this matrix, with cost tier and compliance posture as primary selectors.
- Cloud-Based:Fully externalized resolution infrastructure provisioned through API-driven platforms, embedding directly into Terraform pipelines. Tel Aviv and Bangalore platform engineering teams favor this mode for infrastructure-as-code maturity eighteen months ahead of financial services benchmarks.
- Hybrid:Split resolution architecture synchronizing on-premise Active Directory zones with cloud-native record management, prevalent in Melbourne and Sydney enterprises where legacy identity systems persist alongside Kubernetes adoption.
- On-Premises:Self-managed BIND or PowerDNS implementations retained for air-gapped environments or regulatory data residency mandates, contracting as DevOps externalization accelerates.
- Edge Computing:Micro-deployed resolution nodes co-located with 5G infrastructure and industrial IoT gateways, gaining share fastest as latency requirements harden for autonomous systems and real-time control loops.
Cloud-based deployment commands dominant share; edge computing deployment shows the sharpest volume acceleration.
Use Case:
Application criticality and risk exposure determine margin capture, with security-adjacent use cases sustaining premium pricing above baseline resolution contracts.
- DDoS Protection:Mitigation-integrated resolution absorbing volumetric attacks through anycast dispersion and traffic scrubbing, commanding the highest price premiums in the category. Healthcare systems in Boston and Chicago mandate this capability alongside DoH encryption for endpoint protection.
- Traffic Load Balancing:Application-layer health check integration rerouting queries based on real-time server performance rather than simple geographic proximity, essential for Frankfurt-London real-time payment network resilience.
- Website Acceleration:Geo-proximity resolution minimizing latency for content delivery, standard offering with thinning differentiation as edge caching matures.
- Security Enhancements:DNSSEC validation, threat intelligence filtering, and query logging for forensics, expanding with EU AI Act algorithmic transparency requirements for anomaly detection systems.
- Failover Management:Automated record manipulation during regional outages, a baseline expectation increasingly subsumed into broader traffic steering intelligence.
- Global Traffic Management:Multi-region application steering across cloud provider footprints, correlating with enterprise multi-cloud adoption patterns in São Paulo fintech clusters seeking North American-equivalent granularity.
DDoS protection generates the highest margin pool; traffic load balancing demonstrates the strongest growth momentum.
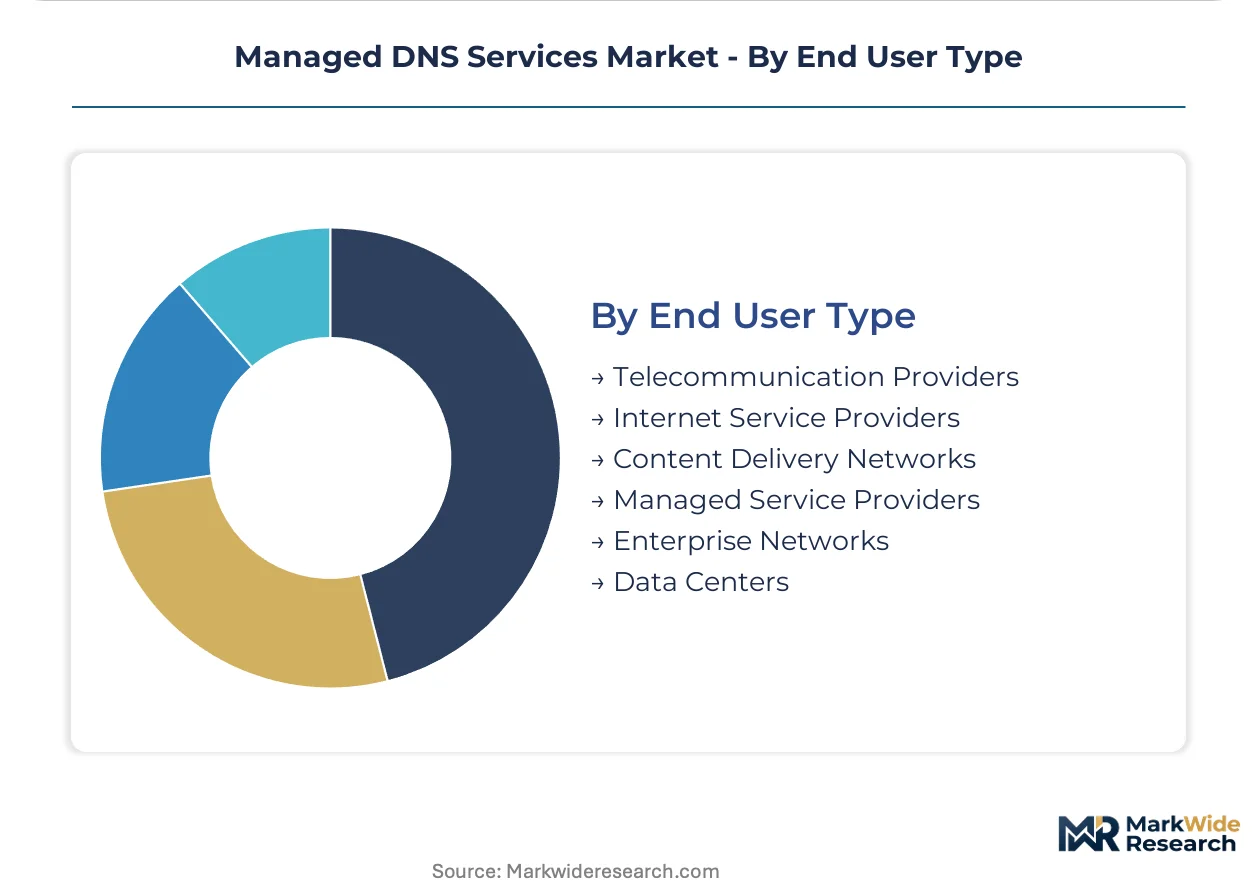
End User Type:
Procurement sophistication and contract scale diverge sharply, from transactional volume-based pricing for carriers to consultative enterprise engagements.
- Telecommunication Providers:German and French operators upgrading vendor resilience certifications under NIS2 Directive incident reporting mandates, driving replacement cycles for legacy infrastructure.
- Internet Service Providers:Consumer-facing resolution at massive query scale, with GDPR data residency requirements preventing delegation to US-jurisdiction logging infrastructure.
- Content Delivery Networks:Resolution performance directly impacting edge cache hit ratios, requiring sub-millisecond anycast density comparable to Cloudflare's routing footprint.
- Managed Service Providers:Multi-tenant zone management platforms white-labeling DNS capabilities to downstream clients, consolidating procurement for mid-market enterprises.
- Enterprise Networks:Hybrid cloud environments demanding synchronization between on-premise directories and cloud-native records, facing skill scarcity for DNSSEC key rotation and cloud API orchestration expertise.
- Data Centers:Colocation facilities offering resolution as infrastructure utility, with supply concentration risk from root server mirror clustering in Northern Virginia and Frankfurt.
Telecommunication providers represent the largest contract value segment; managed service providers are scaling fastest through multi-tenant aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German enterprises generate the most acute demand concentration as financial services operators modernize core network architectures ahead of compliance deadlines. The EU AI Act and NIS2 Directive are tightening digital infrastructure accountability across member states. Cloud-native enterprises across financial services are accelerating adoption of managed DNS platforms to ensure application uptime and traffic resilience.
Germany
Frankfurt financial services and payment networks require traffic steering intelligence that routes queries around degraded paths without interruption. The EU NIS2 Directive mandates incident reporting timelines that force telecommunications providers to reassess vendor resilience certifications. Bavaria and North Rhine-Westphalia host the densest concentration of enterprises upgrading legacy in-house DNS infrastructure.
United States
Boston and Chicago healthcare systems mandate DNS-over-HTTPS compliance for endpoint protection against ISP-level query inspection. FCC net neutrality rulings shape how providers prioritize traffic and disclose routing policies to enterprise customers. Northern Virginia clusters root server mirror deployments that create single-point-of-failure exposure for dependent providers.
France
French telecommunications operators face EU NIS2 Directive mandates compelling vendor resilience certification upgrades. The EU AI Act imposes algorithmic transparency obligations on machine-learning-based anomaly detection systems. Paris and Île-de-France regulators now require documentation of training data provenance for DDoS pattern classification models.
India
CERT-In directives mandate DNSSEC deployment for critical infrastructure, creating mandatory upgrade cycles favoring managed service providers. Bangalore platform engineering teams embed DNS record creation into Terraform pipelines, displacing manual network operations center workflows. Mumbai and Delhi-NCR enterprises exhibit infrastructure-as-code maturity gaps behind technology verticals.
Brazil
São Paulo fintechs lack access to traffic steering granularity available in North American markets, creating whitespace for latency-optimized authoritative DNS. GDPR data residency requirements prevent delegation to US-jurisdiction logging infrastructure for European-facing operations. Local demand concentrates among mid-market enterprises seeking multi-region application steering across cloud provider footprints.
Managed DNS Services Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors integrate resolution telemetry with adjacent security platforms. The vendor base organizes around three archetypes: hyperscale cloud platforms with identity stack integration, specialized traffic steering providers competing on application-layer granularity, and domain registrars bundling resolution with registration services. Competitive intensity concentrates on API-first provisioning capabilities and edge anycast density. M&A activity and technology licensing agreements represent the primary expansion vectors.
Within the traffic steering specialization tier, IBM NS1 Connect and Vercara UltraDNS occupy positions emphasizing application-layer intelligence over raw query volume. Among hyperscale-integrated platforms, Cloudflare DNS and Google Cloud DNS anchor competitive positioning through anycast routing density and cloud identity ecosystem integration. The registrar-anchored segment includes Namecheap and GoDaddy, representing bundled service models that compete on customer acquisition efficiency rather than technical differentiation.
| Leading Market Players |
|---|
| Namecheap |
| Vercara UltraDNS |
| Cloudflare DNS |
| Azure DNS |
| IBM NS1 Connect |
| DNS Made Easy |
| GoDaddy |
| Google Cloud DNS |
| ClouDNS |
| Others |
Cost & Logistics Intelligence
Engineers fluent in DNSSEC key rotation and cloud API orchestration cluster in Frankfurt and Bangalore, creating labor-cost differentials that widen pricing-tier spreads between premium managed DNS contracts and commodity resolution services. DevOps teams in Tel Aviv embed DNS provisioning into Terraform pipelines eighteen months ahead of financial services benchmarks, compressing margins on portal-based zone management while amplifying premiums for API-first infrastructure.
Pricing Analysis
Volume concentrates in flat-rate recursive resolution contracts while margin pools in DDoS-integrated authoritative services with traffic steering intelligence. Three-tier pricing structure across premium, standard, and economy levels separates anycast density guarantees from basic failover capabilities, with certification under EU NIS2 Directive incident reporting mandates commanding tier-one positioning. Cost compression in standard-tier bandwidth contracts stems from anycast peering agreement volatility with tier-1 transit providers in Amsterdam and Ashburn. Telecommunication providers in Germany exhibit highest price sensitivity due to mandated vendor resilience certification upgrades, while Frankfurt financial services accept premium positioning for sub-second failover guarantees.
Supply Chain Analysis
India's CERT-In directive mandating DNSSEC deployment for critical infrastructure operators is reshaping sourcing toward domestic managed service providers with localized query logging infrastructure. Core supply concentration rests on tier-1 transit peering agreements in Northern Virginia, Frankfurt, and Amsterdam, with root server mirror deployments clustering in the first two locations. Raw material dependencies include anycast routing hardware, TLS termination capacity for DoH encryption, and machine-learning training data for anomaly detection systems. Single-point-of-failure exposure from root server mirror concentration in Northern Virginia and Frankfurt presents structural supply risk. Distribution runs through direct enterprise sales for large contracts and managed service provider white-label aggregation for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed DNS services are consolidating around API-first provisioning capabilities and edge anycast density, with EU regulatory mandates forcing weaker portal-based providers toward acquisition or exit. NIS2 Directive incident reporting timelines and EU AI Act algorithmic transparency obligations are accelerating replacement cycles for vendors lacking compliance documentation.
For Market Incumbents: To counter hyperscale cloud platforms integrating resolution with identity stacks, deepen traffic steering intelligence differentiation through application-layer health check granularity rather than raw query volume competition. Acquire specialized DNSSEC automation tooling to address skill scarcity inflating enterprise internal build costs, while expanding EU-only query logging regions to satisfy GDPR data residency requirements blocking US-jurisdiction delegation. For New Entrants and Emerging Players: São Paulo fintechs lacking North American-equivalent traffic steering granularity represent the most penetrable buyer archetype for latency-optimized authoritative DNS. Target Brazilian mid-market enterprises seeking multi-region application steering across cloud provider footprints, with go-to-market anchored through local managed service provider partnerships rather than direct enterprise sales investment. For Investors and Strategic Acquirers: The window for entry favors traffic steering specialists with application-layer intelligence and established EU compliance infrastructure over pure-play recursive resolver vendors. Long-term viability centers on API-first provisioning capabilities embedded in DevOps infrastructure-as-code pipelines. Watch for EU AI Act model card publication requirements as inflection indicator separating compliant vendors from forced-exit candidates.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Terraform pipeline embedding displaces manual network operations center workflows in Bangalore platform engineering teams. |
| EU Compliance Infrastructure Expansion | Segregated query logging regions satisfy GDPR data residency requirements blocking US-jurisdiction delegation for French ISPs. |
| Traffic Steering Intelligence Acquisition | Application-layer health check granularity commands premium pricing above geographic proximity-based resolution in Frankfurt payment networks. |
| DNSSEC Automation Capability Buildout | Automated key rotation addresses skill scarcity inflating enterprise internal platform build costs across hybrid cloud environments. |
| Edge Computing Resolution Deployment | Micro-deployed nodes at Seoul and Tokyo 5G base stations satisfy localized resolution demands that recursive caches cannot meet. |
Research Approach
Independent corroboration across network operations executives, DevOps platform engineers, regulatory compliance officers, and telecommunications procurement leads underwrites the qualitative findings in this analysis. Primary interviews with CTOs at Frankfurt financial services firms and Bangalore technology enterprises combined with secondary validation from FCC net neutrality filings, EU NIS2 Directive implementation guidance, and CERT-In directive documentation. Bottom-up triangulation across infrastructure-as-code adoption patterns and top-down reconciliation against anycast routing density disclosures anchored segmentation modeling.
Comparable-period anchoring to historical DNS infrastructure replacement cycles and DevOps maturity benchmarks structured the forecast window across the analysis window. Segmentation dimensions modeled include service type, deployment mode, use case, and end user type, with infrastructure-as-code maturity gaps between technology verticals and financial services as an industry-specific dimension. CAGRs derived from replacement cycle acceleration under EU regulatory mandates and edge computing density expansion patterns. Forecast inputs incorporated anycast peering agreement pricing volatility and DNSSEC deployment mandate compliance timelines.
Revisions become necessary when EU member state cybersecurity framework fragmentation alters vendor qualification criteria, or when DoH encryption adoption compresses addressable markets for traditional recursive resolver vendors faster than projected. Forecasts reflect documented assumptions regarding DevOps pipeline embedding rates and regulatory compliance deadline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Internet Protocol Version 6 (IPv6) Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
South Korea Data Center Server Market