
 South Africa Automotive Electric Actuators Market | 2026-2036
South Africa Automotive Electric Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Electric Actuators Market Analytics
The capital-intensity divergence between integrated manufacturers and component assemblers is redrawing competitive boundaries in South Africa's electric actuator supply base. Robert Bosch GmbH leverages its in-house semiconductor and motor manufacturing to sustain margin control across brake and steering actuator lines. Johnson Electric anchors its position through specialized micro-motor expertise for door mechanism applications, while Continental AG competes via broad electromechanical portfolios serving OEMs and Tier-1 suppliers directly.
Automotive electric actuators are electromechanical devices that convert electrical energy into precise mechanical motion, typically achieving positional accuracy within fractions of a millimeter through brushless DC motors, lead screws, or piezoelectric stacks, and serve primarily to automate vehicle subsystems that previously relied on hydraulic or manual control. Rotary actuators dominate power steering applications where torque density requirements remain highest, while smart actuators integrating position sensors and CAN bus communication represent the fastest-expanding technology tier as vehicle architectures shift toward domain-controlled electronics. Electromechanical technology leads volume shipments across OEM channels, whereas piezoelectric variants occupy niche precision roles in advanced brake systems where response latency thresholds measure in single-digit milliseconds.
The National Regulator for Compulsory Specifications enforces SABS automotive standards that mandate electromagnetic compatibility and environmental sealing grades for all actuator assemblies sold into South African vehicle production, while the Department of Trade, Industry and Competition administers local content requirements under the Automotive Production and Development Programme that shape supplier qualification and sourcing geography. The South African Bureau of Standards additionally tests durability cycles under thermal and dust exposure profiles reflective of regional operating conditions. Stakeholders must monitor how evolving EU-export alignment through the SADC-EU Economic Partnership Agreement recalibrates certification burdens for actuator manufacturers serving dual domestic and European OEM supply chains.
Market Dynamics
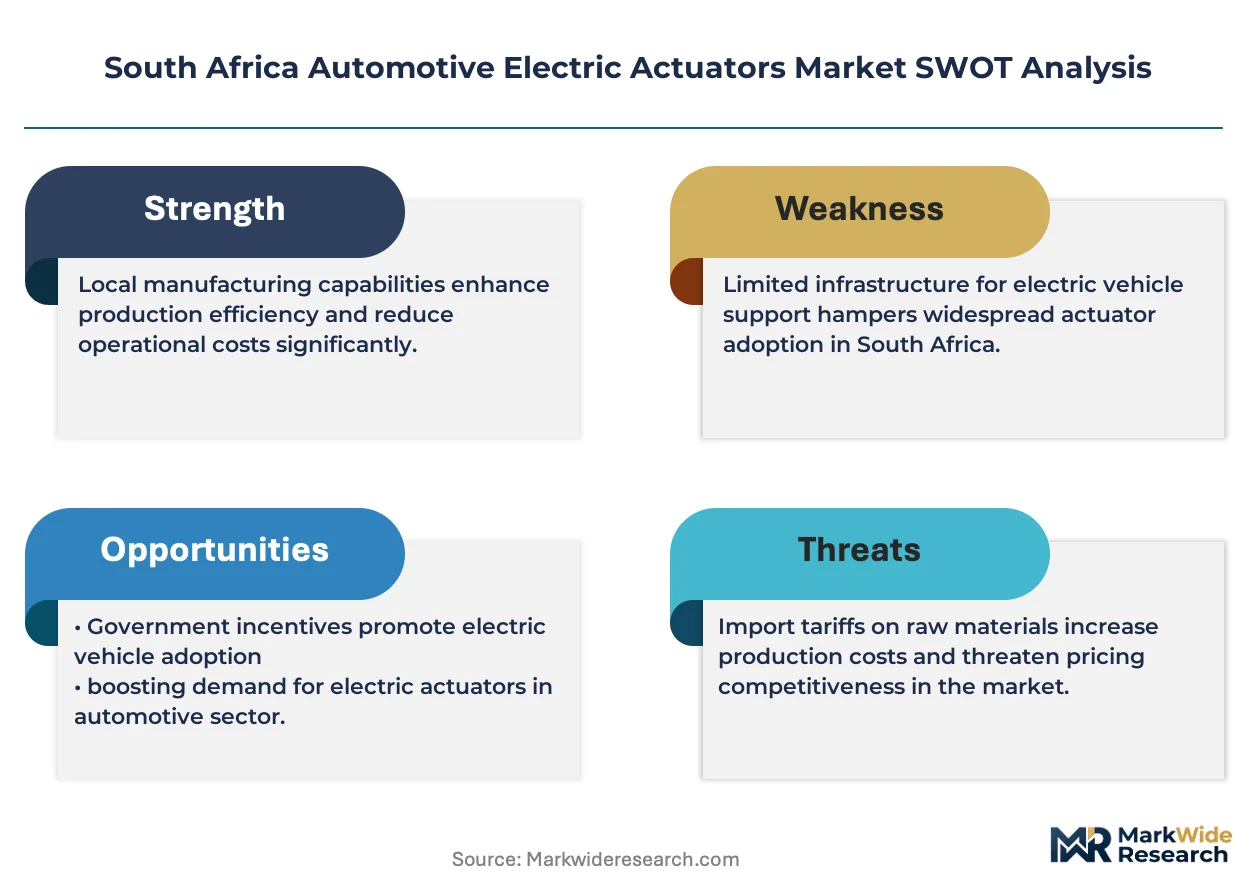
Domain-controlled vehicle architectures are compressing actuator supplier margins by forcing electromechanical component makers to absorb integration costs previously borne by Tier-1 system integrators. South Africa's Automotive Production and Development Programme local content thresholds compound this pressure by mandating domestic value-add percentages that many imported motor and sensor subassemblies fail to satisfy.
Growth Catalysts
- African Continental Free Trade Area tariff elimination:Duty-free access to 54-country consumer base incentivizes Gauteng and Eastern Cape assembly plants to scale actuator-intensive model lines for regional export.
- Brushless DC motor efficiency mandates:South African Bureau of Standards thermal cycling requirements for powertrain electrification components are accelerating replacement of hydraulic steering assist with electromechanical alternatives.
- Gqeberha supplier clustering:Dense concentration of Volkswagen and Isuzu assembly operations creates localized demand density that justifies dedicated actuator warehousing and technical service infrastructure.
Market Restraints
- Rare earth magnet import dependency:Neodymium and dysprosium supply chains concentrated in Chinese processing facilities expose South African actuator assemblers to price volatility and export quota disruptions.
- SABS electromagnetic compatibility certification backlog:Testing queue lengths at the South African Bureau of Standards delay product launch timelines by four to eight months for new electromechanical actuator designs.
- Hydraulic brake system residual preference:Commercial vehicle fleet operators maintain installed base of pneumatic and hydraulic actuation for heavy-duty applications, slowing electromechanical penetration in the truck and bus segment.
Strategic Opportunities
- Aftermarket smart actuator retrofit kits:CAN bus-enabled position sensors bundled with installation hardware address aging vehicle parc in KwaZulu-Natal and Western Cape logistics corridors.
- Renewable energy equipment cross-application:Precision linear actuation expertise developed for throttle and transmission applications transfers to solar tracker and wind turbine pitch control systems.
- Automotive Production and Development Programme Phase 2 incentives:Enhanced production allowances for black-owned component manufacturers create qualification pathways for emerging electromechanical suppliers.
Industry Challenges
- Embedded software validation competency gaps:Functional safety certification to ISO 26262 ASIL-D standards requires firmware engineering capabilities scarce in South Africa's technical labor pool.
- Dual domestic-EU supply chain reconciliation:Simultaneous compliance with SABS regional testing protocols and UNECE E-mark homologation demands duplicate documentation and engineering validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Electric Actuators Market |
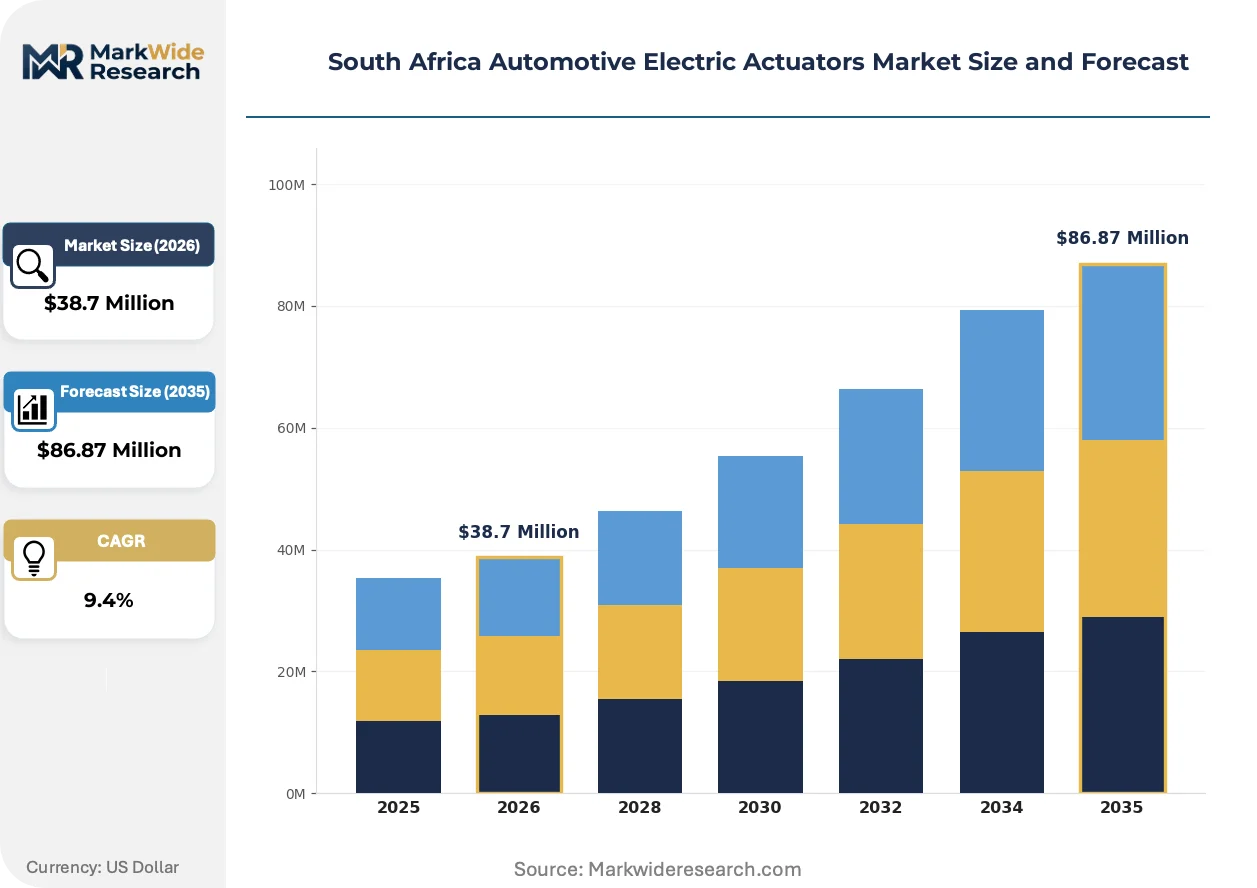
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $86.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Actuators, Linear Actuators, Motorized Actuators, Smart Actuators End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers Technology: Electromechanical, Pneumatic, Hydraulic, Piezoelectric Application: Power Steering, Brake Systems, HVAC Systems, Door Mechanisms |
| Companies Covered | Robert Bosch GmbH, Mitsubishi Electric Corporation, Denso Corporation, Hella KGaA Hueck & Co, Johnson Electric, Nidec Corporation, Continental AG, Magneti Marelli S P A, Hitachi Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Electric Actuators Market Evolving Landscape
Electromechanical actuation is displacing legacy hydraulic and pneumatic control systems across vehicle subsystems where energy efficiency and precision positioning outweigh first-cost considerations. South African OEM procurement patterns reflect this transition through revised supplier technical specifications and consolidated actuator family sourcing.
Multi-layer ceramic capacitor integration within smart actuator housings is miniaturizing power electronics packaging for door latch and mirror adjustment applications. Tier-1 suppliers serving the Eastern Cape assembly belt are adopting these compact motor driver configurations to reduce wiring harness complexity. The technology is miniaturizing control module footprints by forty percent while maintaining SABS vibration resistance grades.
The South African Bureau of Standards alignment with UNECE WP.29 cybersecurity regulations is mandating over-the-air update capabilities for all networked actuator assemblies from 2026. This forces domestic suppliers to embed secure boot architectures and encrypted CAN bus communication stacks previously absent in mechanical-only product lines. Brake and steering actuator categories face the steepest compliance cost escalation given their safety-critical classification.
Fleet operators in Gauteng's commercial vehicle corridor are unbundling actuator maintenance from traditional dealer service contracts and contracting directly with component remanufacturers. This channel disintermediation compresses OEM parts revenue while expanding independent aftermarket share. The pattern is most visible in long-haul trucking applications where downtime costs dominate procurement decisions.
South Africa Automotive Electric Actuators Market Segmentation
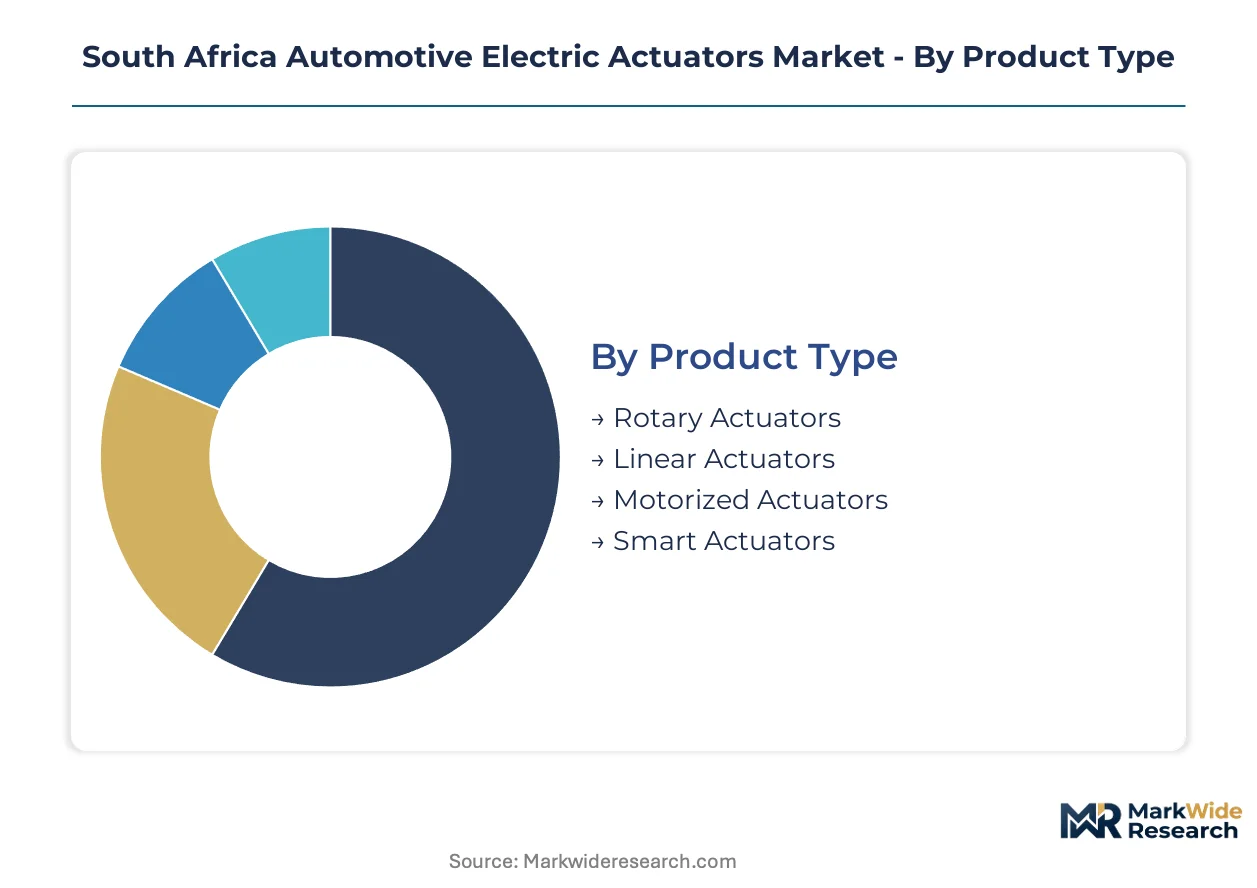
Segmentation in South Africa's automotive electric actuator market reveals how procurement authority, technology maturity, and application criticality reshape supplier priorities across Gauteng's component belt and the Eastern Cape assembly corridor.
Product Type:
Rotary actuators dominate export-bound production from Gqeberha, while smart variants serve domestic OEMs migrating to domain-controlled architectures.
- Rotary Actuators:Brushless DC motor assemblies deliver torque density exceeding 15 Nm/kg for steering column integration. Volkswagen and Isuzu plants in the Eastern Cape anchor procurement volume for medium-duty truck and passenger car lines. SABS thermal cycling certification adds four-month lead times to qualification cycles.
- Smart Actuators:CAN bus-enabled position feedback modules with embedded motor drivers support over-the-air update mandates. Gauteng-based OEM technical centers specify these for brake-by-wire and steer-by-wire prototypes targeting African Continental Free Trade Area export markets.
- Linear Actuators:Lead screw and ball screw mechanisms convert rotational to translational motion for throttle and transmission applications.
- Motorized Actuators:Integrated motor-gearbox assemblies serve door latch and seat adjustment functions with reduced wiring complexity.
Rotary actuators hold the largest share; momentum sits with smart actuators.
End User:
Cost tier stratification separates integrated OEM procurement from fragmented aftermarket channels.
- OEMs:Ford and Toyota South Africa issue consolidated actuator family specifications spanning steering, brake, and HVAC subsystems. Direct sourcing compresses Tier-1 margins while demanding ISO 26262 ASIL-D functional safety documentation.
- Tier-1 Suppliers:Continental and Bosch divisions serve as system integrators, embedding actuators into mechatronic modules for OEM delivery. Their technical service infrastructure concentrates in Rosslyn and Gqeberha supplier parks.
- Vehicle Assemblers:Complete knock-down operations in Durban and Port Elizabeth integrate actuators into semi-knocked-down kits for regional re-export.
- Aftermarket Suppliers:Independent distributors in Johannesburg and Cape Town stock replacement actuators for aging vehicle parc maintenance.
OEMs command the highest volume; aftermarket suppliers are expanding most quickly.
Technology:
Application maturity determines where electromechanical displacement lags behind legacy alternatives.
- Electromechanical:Brushless DC motor systems with integrated position sensing displace hydraulic power steering across light vehicle segments. South African Bureau of Standards efficiency mandates accelerate adoption in Gauteng-produced models.
- Piezoelectric:Ceramic stack actuators achieve sub-millisecond response for anti-lock brake system modulation. Precision requirements limit deployment to premium vehicle platforms assembled in Gqeberha.
- Hydraulic:Piston-driven actuation persists in commercial vehicle brake systems where fleet operators prioritize repair familiarity over efficiency gains.
- Pneumatic:Compressed air systems retain installed base in heavy-duty truck suspension and door applications.
Electromechanical technology leads volume; piezoelectric variants show the steepest expansion trajectory.
Application:
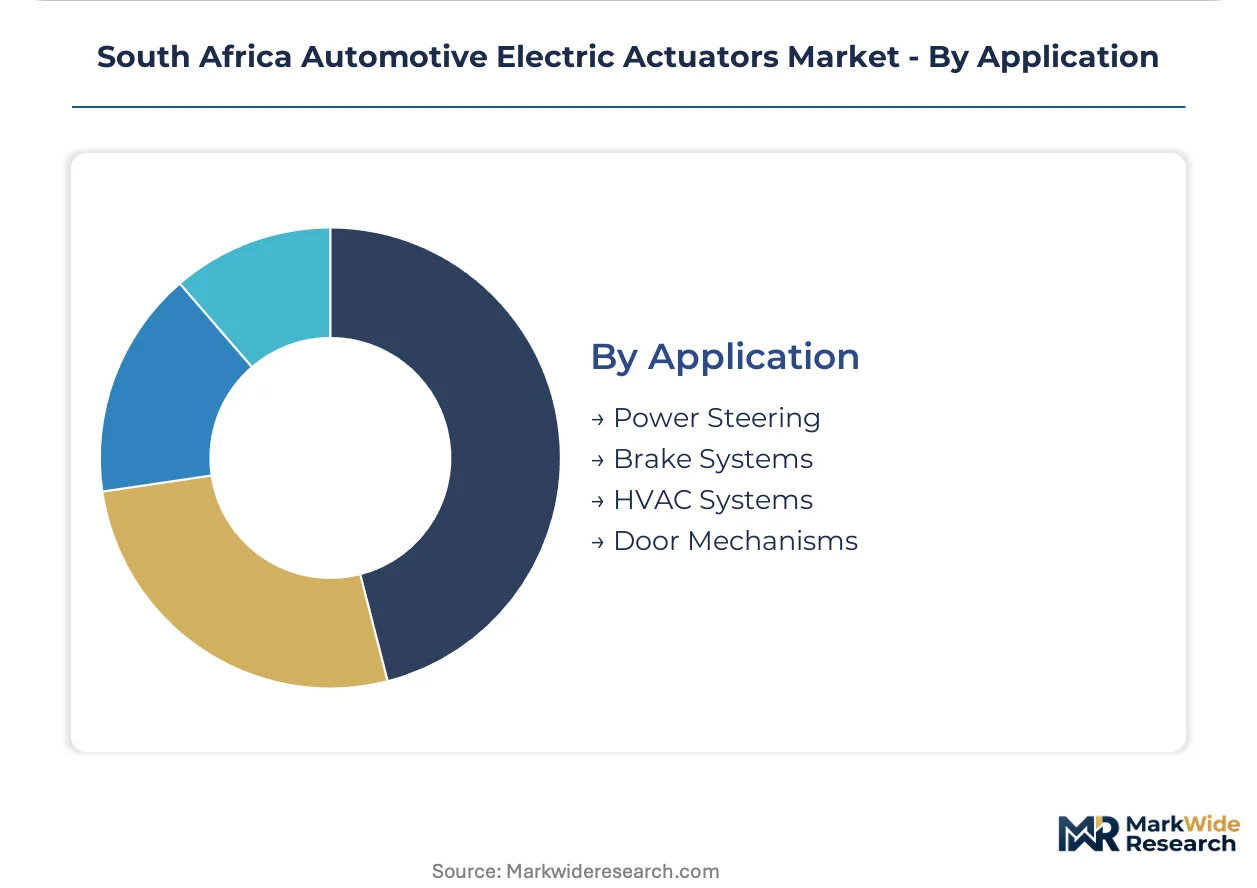
Supply concentration in brake and steering segments contrasts with fragmented HVAC and door mechanism sourcing.
- Power Steering:Electric power steering racks with torque-assist motors replace hydraulic pumps in new vehicle platforms. Eastern Cape assembly plants specify these for models targeting AfCFTA duty-free export.
- Brake Systems:Electromechanical brake boosters and caliper actuators integrate with regenerative braking in hybrid architectures. SABS electromagnetic compatibility testing creates bottlenecks for new supplier qualification.
- HVAC Systems:Blend door and recirculation actuators regulate cabin airflow with stepper motor precision.
- Door Mechanisms:Central locking and power window actuators serve high-volume replacement demand in KwaZulu-Natal logistics corridors.
Brake systems capture the highest unit value; door mechanisms gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gauteng's manufacturing corridor while the Eastern Cape assembly belt absorbs margin compression from AfCFTA export obligations. The National Regulator for Compulsory Specifications enforces divergent certification burdens across South Africa's nine provinces. Regional supplier qualification timelines stretch longest in coastal zones distant from SABS testing facilities.
Gauteng
Ford and Toyota South Africa issue consolidated actuator specifications from technical centers in Pretoria and Johannesburg. The Automotive Production and Development Programme mandates local content thresholds that reshape supplier geography across the province. Rosslyn supplier parks host Continental and Bosch technical service infrastructure serving brake and steering actuator lines.
Eastern Cape
Volkswagen and Isuzu assembly operations in Gqeberha generate concentrated demand for rotary actuators in medium-duty truck and passenger car platforms. SABS thermal cycling certification adds four-month lead times to qualification cycles for export-bound production. The Coega Industrial Development Zone attracts actuator warehousing investment serving AfCFTA duty-free distribution.
KwaZulu-Natal
Durban complete knock-down operations integrate actuators into semi-knocked-down kits for regional re-export to SADC markets. Fleet operators in Richards Bay logistics corridors unbundle actuator maintenance from dealer contracts. Independent distributors stock replacement actuators for aging vehicle parc in heavy-duty trucking applications.
Western Cape
Cape Town aftermarket suppliers serve replacement demand from aging vehicle fleets in wine region logistics corridors. The province lacks OEM assembly presence, concentrating procurement authority in independent distribution channels. Technical labor pools for ISO 26262 firmware validation remain shallower than in Gauteng or the Eastern Cape.
South Africa Automotive Electric Actuators Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South Africa's electric actuator supply base. Integrated manufacturers with in-house semiconductor and motor production sustain margin control, while component assemblers absorb integration costs previously borne by Tier-1 system integrators. The market structure tiers into three strategic archetypes: vertically integrated multinationals, specialized micro-motor experts, and emerging black-owned component manufacturers. Dominant competitive moves include portfolio diversification into renewable energy cross-applications and capacity expansion into supplier parks adjacent to Eastern Cape assembly plants.
Within the integrated multinational tier, Robert Bosch GmbH and Continental AG anchor positions through broad electromechanical portfolios and captive technical service infrastructure. Johnson Electric occupies a specialized position exemplifying micro-motor expertise for door mechanism applications. Nidec Corporation and Denso Corporation represent Japanese-origin manufacturers with scale-driven positioning in brushless DC motor assemblies. Mitsubishi Electric Corporation sits within the premium-tier vector serving domain-controlled architecture prototypes.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| Hella KGaA Hueck & Co |
| Johnson Electric |
| Nidec Corporation |
| Continental AG |
| Magneti Marelli S P A |
| Hitachi Ltd |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Eastern Cape assembly plants and Tier-1 actuator suppliers lock in rare earth magnet supply access while capping price volatility exposure for brake and steering component families. These contractual structures bind Volkswagen and Isuzu procurement teams to fixed-volume commitments that trade margin flexibility for supply security under AfCFTA export obligations.
Pricing Analysis
Configured-to-order pricing commands a 15-25% premium over standard actuator catalog pricing for smart variants with embedded CAN bus modules and over-the-air update capability. The dominant pricing structure runs through tiered contract frameworks separating premium ASIL-D certified brake actuators from standard door mechanism units and economy-grade HVAC blend door motors. Cost compression in the economy tier is intensifying because Chinese motor imports undercut local assembly on first-cost metrics. Fleet operators in KwaZulu-Natal logistics corridors exhibit the highest price sensitivity, while OEM technical centers in Gauteng prioritize certification grade over unit cost.
Supply Chain Analysis
Rare earth magnet processing concentrated in Chinese refining facilities creates a single-source vulnerability that South African actuator assemblers cannot bypass without prohibitive capital investment. The supply chain draws from China for neodymium-dysprosium alloys, Japan for precision motor laminations, and Germany for semiconductor-integrated motor drivers. Tariff exposure runs through SADC-EU Economic Partnership Agreement alignment requirements that force duplicate component sourcing for dual-certification products. Distribution runs through supplier parks adjacent to Rosslyn and Gqeberha assembly corridors, with aftermarket channels fragmenting across Johannesburg and Cape Town independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's automotive electric actuator market is recovering from cyclical compression as OEMs restock electromechanical inventory ahead of AfCFTA tariff elimination deadlines. The cyclical driver is production schedule normalization at Eastern Cape assembly plants following supply chain destocking.
For Market Incumbents: Secure backward integration into motor lamination and semiconductor sourcing to defend margin structure against Chinese import price pressure. Incumbents should expand technical service infrastructure in Coega Industrial Development Zone to capture aftermarket disintermediation revenue from fleet operators unbundling maintenance contracts. The priority lever is ISO 26262 firmware validation capability acquisition to meet domain-controlled architecture procurement specifications. For New Entrants and Emerging Players: Anchor in aftermarket smart actuator retrofit kits for aging vehicle parc in Western Cape wine region logistics corridors, where independent distribution channels lack technical service depth. The most penetrable segment is CAN bus-enabled position sensor bundles for brake and steering system upgrades. A direct contracting model with commercial fleet operators bypasses dealer service network gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among component remanufacturers serving long-haul trucking applications with actuator refurbishment contracts. Long-term viability over a 5-10 year window favors acquisition targets with renewable energy cross-application capability in solar tracker and wind turbine pitch control systems. The signal to watch is SABS electromagnetic compatibility certification queue length reduction as an indicator of new supplier qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated actuator family specifications from Ford and Toyota South Africa compress supplier engineering overhead. |
| Rare Earth Supply Agreement | Long-term magnet sourcing contracts with Chinese processors hedge against export quota disruptions. |
| Software-Defined Vehicle Investment | Embedded secure boot architectures meet UNECE WP.29 cybersecurity mandates for networked brake actuators. |
| Geographic Manufacturing Footprint | Supplier park proximity to Gqeberha assembly plants reduces logistics cost for AfCFTA-bound production. |
| Charging Infrastructure Partnership | Electromechanical actuator expertise transfers to electric vehicle charging station positioning systems. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and SABS certification officials and refined through secondary validation against vehicle production databases, IHS Markit registration data, customs import records, and Automotive Production and Development Programme compliance filings. Bottom-up actuator shipment estimates by application and technology tier were triangulated with top-down OEM production schedule analysis across the analysis window.
Variance decomposition separated volume drivers from price-mix effects across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from modeled shipment trajectories and average selling price evolution, with specific inputs including SABS thermal cycling certification timelines and AfCFTA tariff phase-out schedules.
Underlying assumptions cover OEM production schedule stability and rare earth magnet import quota continuity, with deviation risk concentrated in SABS electromagnetic compatibility testing backlog duration and EU-export alignment recalibration. Practitioners should keep alternative scenarios live as cybersecurity regulation implementation timelines and black-owned supplier incentive program criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market