
 Automotive LED Market | 2026-2036
Automotive LED Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive LED Market Analysis
Multi-source procurement for LED chip supply is shifting toward captive wafer production among tier-one lighting suppliers. OSRAM GmbH leverages in-house epitaxy capacity to secure gallium nitride supply chains. Nichia Corporation sustains dominance in phosphor-converted white LED architectures. Koito Manufacturing Co., Ltd. anchors its position through integrated module assembly from chip to headlamp housing.
Automotive LED refers to semiconductor-based solid-state lighting devices engineered from indium gallium nitride or aluminum gallium indium phosphide compounds, emitting photons through electroluminescence with luminous efficacy exceeding 150 lumens per watt, designed primarily for exterior illumination and interior ambient lighting in motor vehicles. Headlight assemblies command the largest value pool due to complexity in adaptive driving beam modules and thermal management requirements. COB technology leads unit shipments in daytime running light applications where compact form factors dominate. SMD packages compete aggressively in taillight segments where cost-per-lumen sensitivity shapes supplier selection.
Europe's ECE R48 regulation and the US NHTSA Federal Motor Vehicle Safety Standard 108 govern photometric performance and glare limits, compelling suppliers to invest in matrix beam software and sensor fusion. Japan's METI energy efficiency directives push OEMs toward lower-power LED architectures in domestic vehicle platforms. Stakeholders must monitor divergence between UN-ECE automated driving harmonization and US state-level headlight autonomy rules.
Market Dynamics
Matrix beam software and thermal management complexity are compressing supplier margins while forcing tier-one lighting manufacturers to internalize gallium nitride epitaxy capacity.
Growth Catalysts
- ECE R48 tightening:Europe's updated photometric performance requirements mandate adaptive driving beam systems in premium vehicle platforms, accelerating module complexity upgrades.
- Indium gallium nitride efficiency gains:Luminous efficacy thresholds exceeding 150 lumens per watt enable lower-power architectures that satisfy Japan's METI energy efficiency directives.
- Stuttgart-Munich corridor concentration:Germany's automotive manufacturing cluster generates concentrated demand for headlight assembly integration from chip to housing.
Market Restraints
- Gallium nitride wafer supply concentration:Epitaxial substrate production clusters among limited merchant suppliers, creating vulnerability for non-captive lighting module manufacturers.
- Aluminum gallium indium phosphide thermal limitations:Red-amber LED compounds face efficacy degradation at elevated junction temperatures, constraining taillight design flexibility.
- NHTSA-US state divergence:Automated driving harmonization gaps between Federal Motor Vehicle Safety Standard 108 and emerging state-level headlight autonomy rules create compliance fragmentation.
Strategic Opportunities
- COB daytime running light expansion:Compact chip-on-board form factors penetrate mid-volume vehicle platforms where cost-per-lumen sensitivity previously blocked LED adoption.
- Sensor fusion convergence:Integration of matrix beam software with camera and radar systems creates white space for lighting suppliers possessing embedded systems capability.
- US IRA clean vehicle incentives:Domestic content requirements for federal tax credits favor North American LED module assembly investment.
Industry Challenges
- Phosphor-converted white LED IP complexity:Nichia Corporation's patent estate around yttrium aluminum garnet architectures forces licensing negotiations or design-arounds for new entrants.
- Adaptive driving beam calibration timeline:OEM validation cycles for software-defined headlight patterns extend 18-24 months, compressing supplier revenue recognition windows.
- Legacy halogen housing retrofits:Thermal management requirements for high-power LED modules conflict with existing headlamp geometries, demanding costly tooling redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive LED Market |
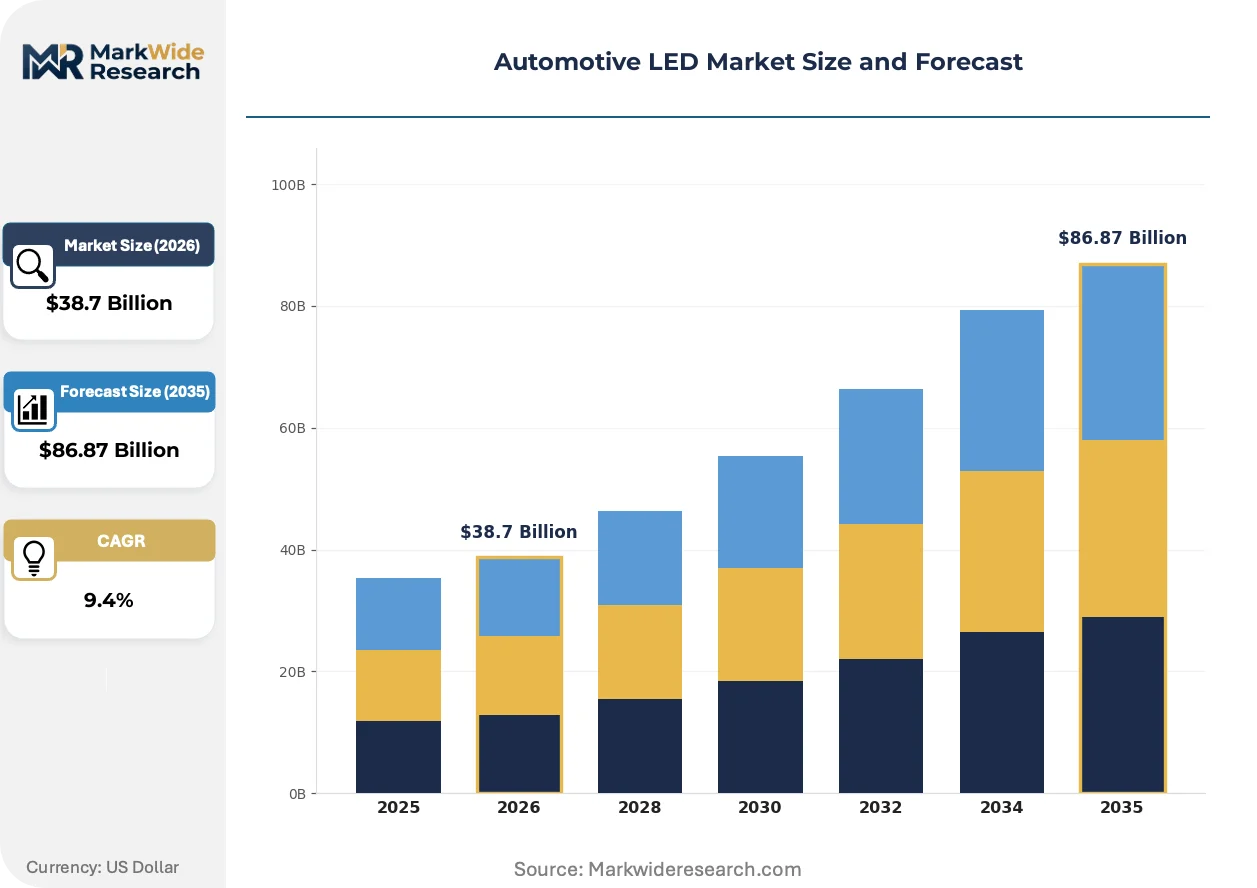
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Daytime Running Lights, Fog Lights Technology: COB, SMD, Halogen Replacement, Laser LED End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks |
| Companies Covered | Koito Manufacturing Co., Ltd., HELLA GmbH & Co. KGaA, Valeo SA, Marelli Holdings Co., Ltd., Stanley Electric Co., Ltd., Nichia Corporation, OSRAM GmbH, Hyundai Mobis Co., Ltd., ZKW Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive LED Market Emerging Trajectories
Digital light processing and solid-state thermal management are converging to redefine exterior illumination architecture, shifting competitive advantage toward software-integrated module suppliers.
Micro-LED pixel arrays are automating adaptive beam pattern generation through real-time traffic object detection and glare-free zone sculpting. Premium passenger vehicle manufacturers in Germany and Japan are adopting these systems at model-refresh cadences of 24-36 months. The technology is automating the displacement of mechanical shutter mechanisms with solid-state electronic control, compressing component count and assembly labor content.
REACH substance restrictions on cadmium-containing quantum dots are compelling phosphor suppliers to accelerate silicon carbide and nitride alternative development. The industrial consequence is a qualification bottleneck for next-generation high-color-rendering interior ambient lighting. European OEMs face the most compressed reformulation timelines as 2026 restriction dates approach.
Direct OEM procurement of LED chips is fragmenting traditional tier-one lighting supplier relationships as vehicle electrification platforms demand customized spectral outputs. Battery electric vehicle programs specify amber-dominated cabin lighting to reduce circadian disruption during nighttime charging. This pattern is most visible in Scandinavian markets where winter darkness extends operational lighting hours.
Automotive LED Market Segmentation
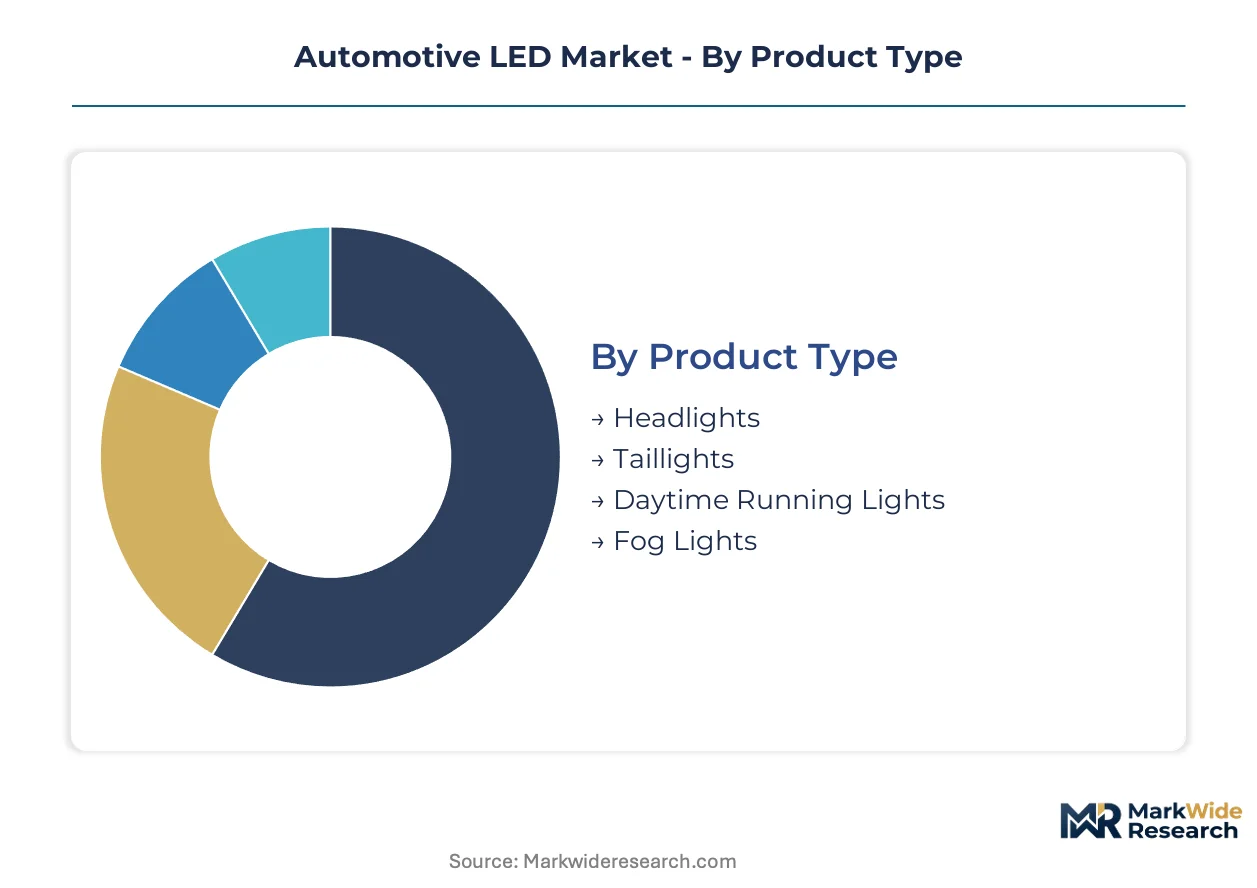
Automotive LED segmentation reflects divergent upgrade cycles across exterior illumination modules. Vehicle electrification compresses replacement timelines for headlight assemblies while extending durability expectations for interior ambient systems.
Product Type:
Upgrade cycles vary sharply across exterior lighting positions, with forward illumination demanding the most frequent technology refreshes due to regulatory and safety performance evolution.
- Headlights:Adaptive driving beam modules integrate matrix LED arrays with thermal management substrates. Stuttgart and Munich corridor OEMs specify these for premium platform refreshes, driven by ECE R48 tightening on photometric performance.
- Taillights:Red-amber LED compounds face aluminum gallium indium phosphide thermal limitations at elevated junction temperatures. Japan's METI efficiency directives push lower-power architectures here, constraining design flexibility for sequential turn indicators.
- Daytime Running Lights:COB form factors penetrate mid-volume platforms.
- Fog Lights:Compact SMD packages dominate cost-sensitive segments.
Headlights sit at the top of the volume ranking, with daytime running lights climbing the fastest.
Technology:
Cost tiers separate technologies by manufacturing complexity and intellectual property intensity, with premium positions commanding captive supply chain investments.
- COB:Chip-on-board architectures eliminate individual LED packaging, reducing thermal interface layers. Daytime running light applications in Germany's automotive cluster favor these compact form factors where space constraints dominate module design.
- SMD:Surface-mount device packages compete aggressively on cost-per-lumen metrics. Taillight segments favor these where phosphor-converted white LED licensing from Nichia Corporation shapes supplier selection.
- Halogen Replacement:Retrofit modules address legacy housing thermal conflicts.
- Laser LED:High-beam augmentation systems target premium long-range illumination.
COB claims the largest installed base, while laser LED gains share fastest among emerging architectures.
End User:
Customer type determines procurement concentration, with direct OEM relationships fragmenting traditional tier-one supplier channels.
- OEMs:Direct LED chip procurement is accelerating as battery electric vehicle programs specify customized spectral outputs. Scandinavian OEMs demand amber-dominated cabin lighting to reduce circadian disruption during winter charging cycles.
- Aftermarket Providers:Retrofit kit distributors face REACH substance restriction deadlines on cadmium-containing quantum dots.
- Dealerships:Authorized service networks handle warranty-period replacements.
- Vehicle Assemblers:Contract manufacturers integrate lighting at final assembly stages.
OEMs dominate procurement value, with aftermarket providers expanding most quickly in regulatory retrofit zones.
Application:
Application segmentation tracks vehicle platform electrification rates, with commercial electrification lagging passenger adoption by multiple product cycles.
- Passenger Vehicles:Premium manufacturers deploy micro-LED pixel arrays for adaptive beam pattern generation. Germany and Japan OEMs adopt these at 24-36 month refresh cadences, displacing mechanical shutter mechanisms with solid-state electronic control.
- Commercial Vehicles:Heavy-duty duty cycles prioritize durability over adaptive features. Long-haul operators in North America resist complexity that extends service intervals.
- Two-Wheelers:Compact COB modules address severe space constraints.
- Heavy-Duty Trucks:Thermal management requirements favor conservative LED architectures.
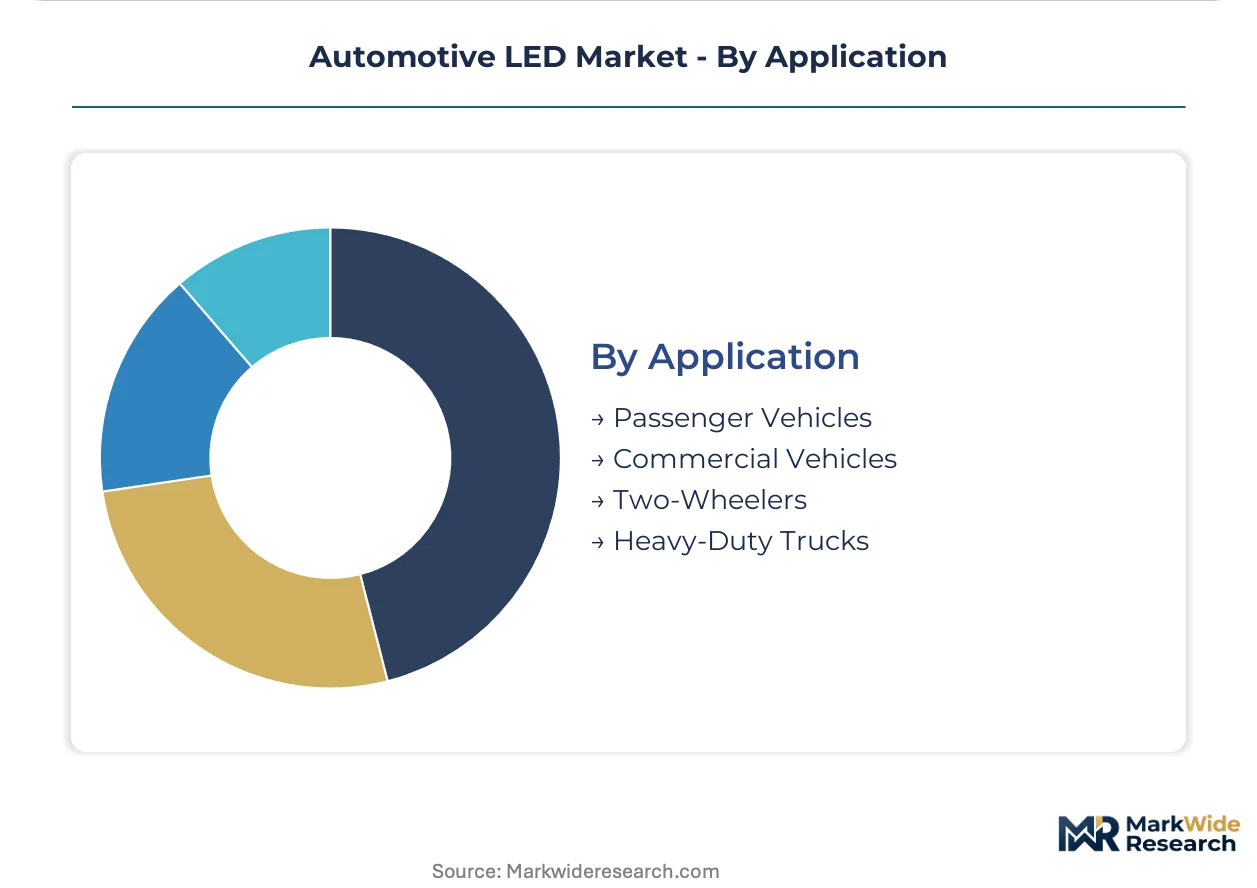
Passenger vehicles anchor volume leadership, with two-wheelers showing the steepest expansion trajectory in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping LED module assembly location decisions as compliance-cost differentials between jurisdictions widen. Tier-one suppliers migrate final-stage production toward markets offering clean-vehicle incentive stacking or streamlined type-approval pathways.
United States
NHTSA Federal Motor Vehicle Safety Standard 108 governs photometric performance and glare limits for headlight assemblies. The Inflation Reduction Act clean vehicle tax credits create domestic content requirements favoring North American LED module assembly investment. Michigan and Ohio automotive corridors concentrate headlamp housing integration for Detroit Three electrification platforms.
Germany
ECE R48 tightening mandates adaptive driving beam systems in premium vehicle platforms, accelerating module complexity upgrades. The KBA type-approval authority enforces stringent photometric validation protocols for matrix beam software. Stuttgart and Munich manufacturing clusters generate concentrated demand for chip-to-housing headlight assembly integration.
Japan
METI energy efficiency directives push OEMs toward lower-power LED architectures in domestic vehicle platforms. The PMDA does not regulate automotive lighting directly, but JIS standards align with UN-ECE harmonization frameworks. Nagoya and Tokyo metropolitan manufacturing zones anchor tier-one supplier module design centers.
China
MIIT new energy vehicle mandates accelerate LED adoption across battery electric platforms requiring customized spectral outputs. GB standards for automotive lighting equipment are converging toward UN-ECE technical prescriptions. Yangtze River Delta and Pearl River Delta industrial clusters concentrate chip packaging and module assembly capacity.
South Korea
MFDS pharmaceutical regulations do not extend to automotive components, but KOSHA industrial safety standards shape manufacturing facility certification. The Seoul Capital Area anchors domestic OEM procurement concentration for Hyundai-Kia electrification programs. Busan-Ulsan manufacturing belt supplies export-oriented LED module assembly for Southeast Asian vehicle markets.
Automotive LED Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor fusion and software-defined lighting architectures. The supplier base concentrates among lighting module specialists with captive gallium nitride epitaxy capacity and diversified electronics conglomerates with automotive tier-one relationships. Three archetypes dominate: integrated chip-to-module manufacturers, software-embedded system suppliers, and scale-focused packaging houses. Competitive moves center on backward integration into wafer production and strategic partnerships for matrix beam algorithm development.
Among Japan-based manufacturers, Koito Manufacturing Co., Ltd., Stanley Electric Co., Ltd., and Nichia Corporation exemplify the integrated archetype combining epitaxy capacity with module assembly expertise. German GmbH-structured entities including HELLA GmbH & Co. KGaA, OSRAM GmbH, and ZKW Group GmbH occupy positions emphasizing ECE regulatory compliance and premium OEM relationships. These groupings represent divergent strategic postures on captive supply chain control versus collaborative sensor fusion development.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| Valeo SA |
| Marelli Holdings Co., Ltd. |
| Stanley Electric Co., Ltd. |
| Nichia Corporation |
| OSRAM GmbH |
| Hyundai Mobis Co., Ltd. |
| ZKW Group GmbH |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap lighting specialists in Germany and Japan anchor pricing discipline through captive gallium nitride epitaxy capacity, insulating module margins from merchant wafer volatility while concentrating procurement leverage among Stuttgart-Munich corridor OEMs.
Pricing Analysis
Distributor margin compression in aftermarket channels intensifies as direct OEM procurement of LED chips fragments traditional tier-one relationships. Three-tier pricing structure across premium adaptive beam modules, standard COB daytime running lights, and economy SMD taillight packages separates certification-grade ECE R48 compliance from basic photometric performance. Cost compression in mid-volume platforms accelerates as COB form factors penetrate segments previously blocked by cost-per-lumen sensitivity. Aftermarket providers exhibit highest price sensitivity due to REACH substance restriction compliance costs, while premium OEMs prioritize matrix beam software integration over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from tier-one lighting manufacturers mandate multi-supplier qualification for gallium nitride wafers across Taiwan, Germany, and South Korea. Epitaxial substrate production draws from indium gallium nitride compounds, aluminum gallium indium phosphide red-amber architectures, and phosphor-converted white LED phosphors. Single-source vulnerability concentrates around Nichia Corporation's yttrium aluminum garnet patent estate. Distribution runs through integrated chip-to-module manufacturers, software-embedded system suppliers, and scale-focused packaging houses serving regional automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive LED demand compounds steadily as vehicle electrification mandates compress replacement timelines for headlight assemblies across battery electric platforms.
For Market Incumbents: Anchor defensive positioning through backward integration into gallium nitride epitaxy capacity, mirroring OSRAM GmbH's in-house wafer production model. Deepen module assembly expertise from chip to headlamp housing to resist direct OEM chip procurement fragmentation. Prioritize matrix beam software calibration capabilities as OEM validation cycles extend supplier revenue recognition windows.
For New Entrants and Emerging Players: NHTSA Federal Motor Vehicle Safety Standard 108 divergence from emerging US state-level headlight autonomy rules opens a window for compliance-specialist module suppliers. Target mid-volume daytime running light platforms where COB form factor penetration lags in North American markets. Pursue sensor fusion partnerships with camera and radar system developers as adaptive beam integration creates white space.
For Investors and Strategic Acquirers: Valuations sit cheapest among scale-focused packaging houses lacking captive epitaxy capacity but possessing established tier-one automotive relationships. Long-term viability rests on software-defined lighting architectures displacing mechanical shutter mechanisms. Monitor US IRA clean vehicle incentive domestic content requirements as inflection indicator for North American assembly investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Epitaxy Capacity Expansion | Captive wafer production insulates OSRAM GmbH and Koito Manufacturing from merchant supply volatility. |
| Matrix Beam Software Integration | Sensor fusion convergence with camera systems creates embedded systems capability differentiation. |
| COB Daytime Running Light Platform Penetration | Compact form factors unlock mid-volume vehicle segments previously blocked by cost sensitivity. |
| North American Module Assembly Investment | US IRA domestic content requirements favor Michigan and Ohio corridor production localization. |
| Phosphor Alternative Development | Silicon carbide and nitride reformulations address REACH cadmium quantum dot restriction deadlines. |
Methodological Framework
Multiple input streams — primary interviews with tier-one supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, ECE R48 regulatory filings, and IHS Markit registration data; and customs records on gallium nitride wafer trade flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from trend extrapolation of technology adoption curves and regulatory compliance timelines, incorporating METI efficiency directive implementation pace and ECE R48 tightening schedules as automotive-specific forecast inputs.
Revisions become necessary when gallium nitride wafer supply concentration shifts, NHTSA automated driving harmonization accelerates, or REACH substance restriction deadlines compress. Deviation in OEM direct chip procurement patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
E-Bike Lights Market