
 Calcium Tartrate Market | 2026-2036
Calcium Tartrate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Tartrate Market Analysis
Specialized chemists with tartaric acid derivative expertise is unwinding production bottlenecks across Mediterranean and Asian manufacturing zones. Alvinesa Natural Ingredients leverages vertical integration from grape pomace sourcing to refined calcium tartrate output. REVICO France anchors its position through deep ties to Languedoc-Roussillon wine cooperatives. Grap'Sud dominates crystallization technology for high-purity food grade variants.
Calcium tartrate is the calcium salt of tartaric acid (C4H4O6Ca), typically precipitated from wine lees or mother liquors and refined to purities exceeding 99 percent for pharmaceutical and food applications. The compound functions primarily as an acidulant, stabilizer, and calcium fortifier across processed food systems and tablet formulations. Food grade powder occupies the largest volume share, while pharmaceutical grade crystals command premium positioning due to stringent USP-NF monograph compliance. Direct sales channels sustain margin pools for industrial grade buyers, though online retail is gaining share among small-scale cosmetics formulators seeking granular minimum order quantities.
REACH registration requirements under ECHA govern tartaric acid derivative placement across EU member states, while FDA food additive regulations under 21 CFR 184.1077 shape import eligibility for non-US producers. China's SAMR national food safety standards and GB specifications for food-grade chemicals create parallel compliance tracks for Asia-Pacific market access. Stakeholders must monitor evolving purity thresholds across pharmaceutical compendia and assess backward integration into vineyard waste streams before committing capital to new calcium tartrate refining capacity.
Market Dynamics
Winemaking waste valorization is restructuring calcium tartrate feedstock economics, as Mediterranean cooperatives monetize pomace streams previously treated as disposal costs. This supply-side reconfiguration is compressing raw material spreads and forcing refiners to secure long-term grape lees contracts.
Growth Catalysts
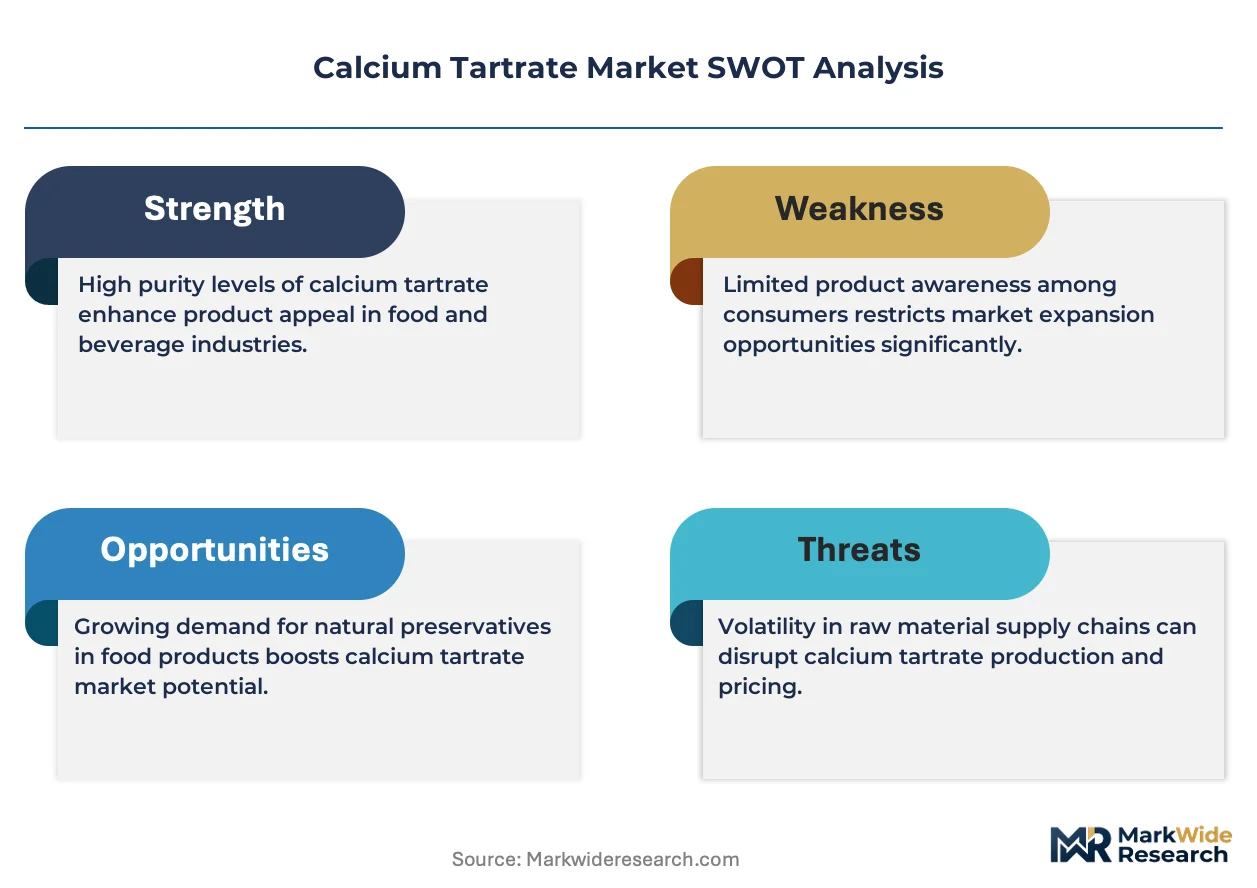
- REACH registration thresholds:ECHA's tightened purity documentation for tartaric acid derivatives is filtering out unqualified suppliers and consolidating demand around certified EU refiners.
- Clean-label bakery leavening:Formulators in Germany and France are substituting synthetic acidulants with calcium tartrate to meet retailer clean-label mandates.
- Pharmaceutical excipient certification:USP-NF monograph compliance is opening tablet formulation contracts to calcium tartrate producers meeting US FDA 21 CFR 184.1077 standards.
Market Restraints
- Grape harvest volatility:Climate-induced yield fluctuations in Languedoc-Roussillon and La Rioja create feedstock quantity uncertainty for seasonal precipitation-dependent recovery.
- High-purity crystallization capex:Pharmaceutical-grade production requires GMP-compliant isolation equipment that smaller Mediterranean processors cannot finance.
- Citric acid substitution:Lower-cost acidulants from corn fermentation are displacing calcium tartrate in non-premium food applications where mineral fortification is not required.
Strategic Opportunities
- China's food safety upgrade:SAMR's GB standard harmonization is creating entry windows for foreign producers meeting dual USP-China specifications.
- Cosmetic grade microencapsulation:Beauty formulators in South Korea are adopting calcium tartrate as a pH buffer in sensitive-skin product lines.
- Vineyard waste-to-chemicals policy:EU Green Deal circular economy funding is subsidizing pomace processing infrastructure in Italy and Spain.
Industry Challenges
- Tartaric acid derivative chemist scarcity:Specialized crystallization expertise is concentrated among retiring technicians in France's wine chemistry institutes.
- Multi-jurisdiction certification timelines:Simultaneous USP-NF, REACH, and SAMR dossier preparation extends product launch cycles by eighteen to twenty-four months.
- Legacy batch reactor integration:Continuous crystallization systems face retrofit friction at established Mediterranean facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Tartrate Market |
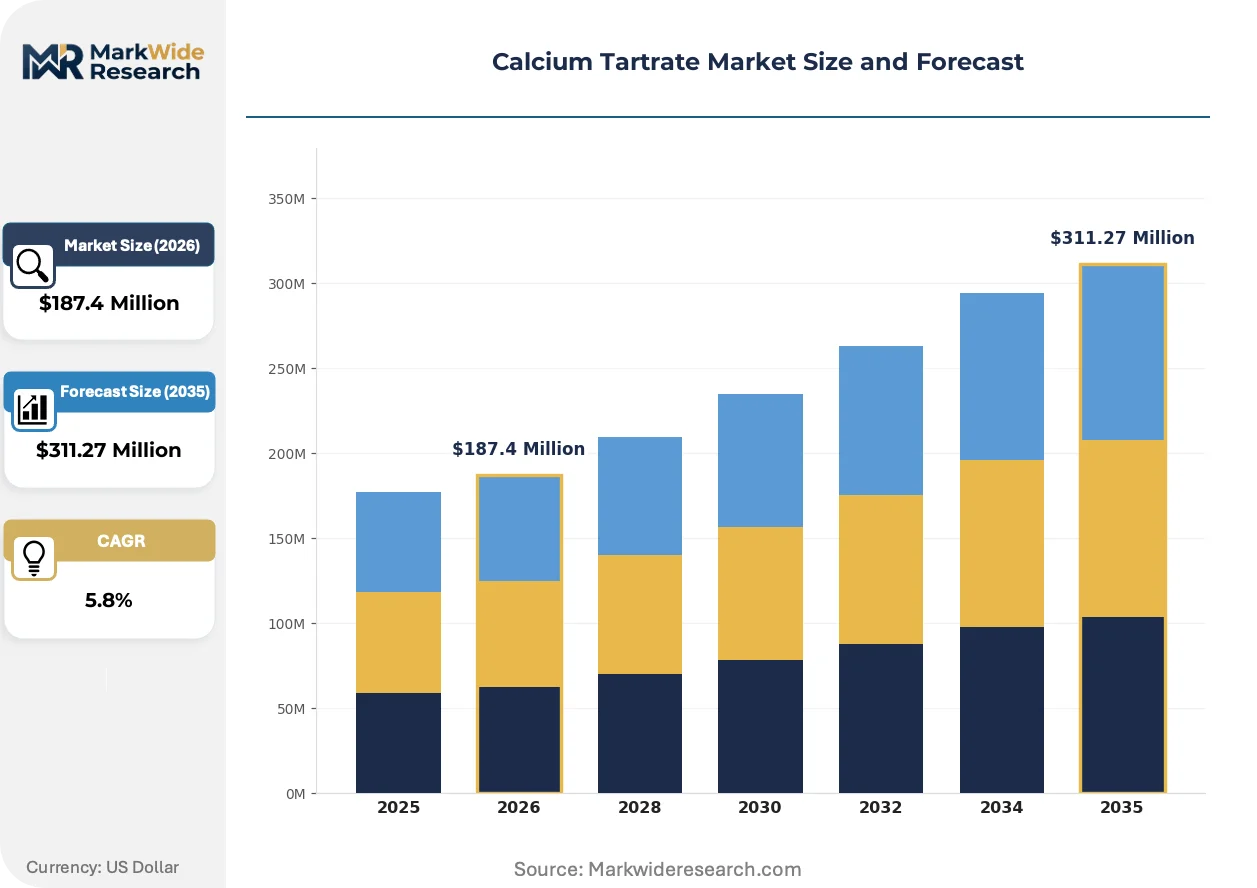
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade End Use: Food & Beverage, Pharmaceuticals, Agriculture, Cosmetics Sales Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Form: Powder, Granules, Crystals, Liquid |
| Companies Covered | Alvinesa Natural Ingredients, REVICO France, Grap'Sud, Brenn O Kem, Derivados Vinicos, Caviro Group, American Tartaric Products, Tarcol, Ninghai Organic Chemical Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Tartrate Market Emerging Trajectories
Membrane filtration and continuous crystallization technologies are displacing conventional batch recovery methods, enabling real-time purity adjustment and reducing solvent waste volumes. These process innovations are compressing unit economics for food-grade production while raising barriers for artisanal competitors.
Electrodialysis-based tartaric acid recovery is decomposing the traditional lees-drying and acid-dissolution sequence into a single-stage operation. Spanish refiners near Valencia are piloting these systems for 40% energy reduction. The technology is compressing capital payback periods and enabling smaller-scale distributed processing near vineyard clusters.
REACH's 2023 update to Annex XVII restrictions on residual solvents is forcing crystallization solvent substitution across EU production sites. Refiners are switching from methanol to ethanol-water mixtures, increasing energy consumption but securing market access. Food-grade exporters to Germany face the most stringent documentation requirements.
Buyer consolidation among European bakery ingredient distributors is shifting procurement toward annual framework contracts with volume guarantees. Small cosmetics formulators are migrating to specialized chemical e-procurement platforms for sub-tonne orders. This channel bifurcation is most visible in France, where direct mill relationships coexist with digital spot purchasing.
Calcium Tartrate Market Segmentation
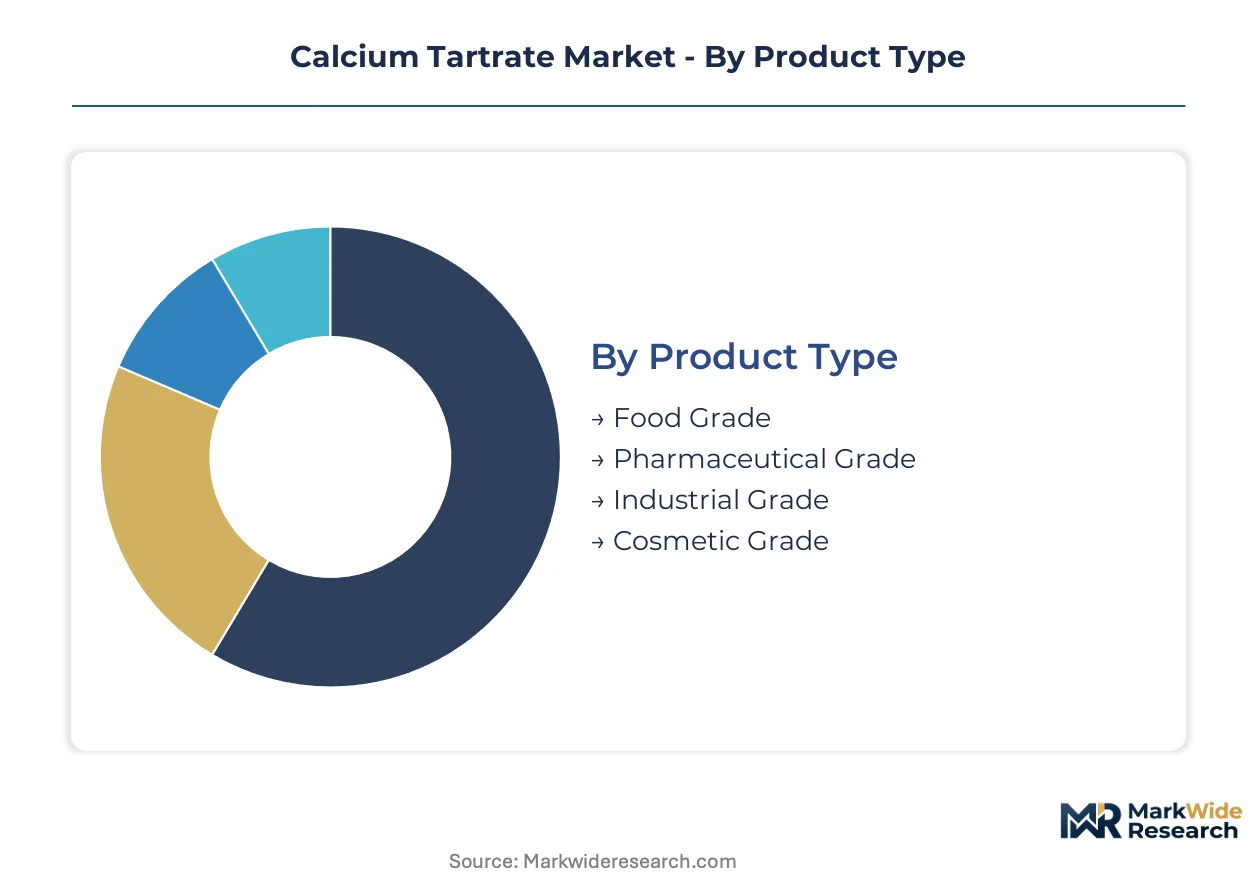
Calcium tartrate's value chain fragments sharply across purity grades and regulatory jurisdictions, with margin capture diverging between commodity food acidulants and certified pharmaceutical excipients. Understanding segment-level economics reveals where capital deployment yields sustainable returns versus commodity trap exposure.
Product Type:
Margin pools concentrate in pharmaceutical-grade certification, where USP-NF compliance commands pricing multiples over food-grade alternatives. Industrial and cosmetic grades operate on thinner spreads dependent on volume throughput.
- Food Grade:Refined to purities exceeding 99 percent for bakery leavening and acidulant applications. German clean-label formulators and French industrial bakers drive procurement concentration as retailers mandate synthetic acidulant replacement.
- Pharmaceutical Grade:Crystalline material meeting USP-NF monograph standards for tablet binder and calcium fortifier roles. China's expanding generic pharmaceutical sector and India's contract manufacturing organizations are absorbing certified output fastest.
- Industrial Grade:Lower-purity variants for metal finishing and chemical synthesis feedstocks. Spanish refiners near Valencia distribute through bulk chemical distributors to European industrial processors.
- Cosmetic Grade:Microencapsulated forms for pH buffering in sensitive-skin formulations. South Korean beauty laboratories and Italian natural cosmetics manufacturers specify this grade for premium positioning.
The dominant share belongs to Food Grade, while Pharmaceutical Grade is closing the gap fastest.
End Use:
Application economics split between high-volume food processing and precision pharmaceutical formulation, with agricultural and cosmetic uses emerging as specialized niches.
- Food & Beverage:Acidulant, stabilizer, and calcium fortifier functions across bakery, confectionery, and beverage systems. REACH-compliant EU processors and SAMR-registered Chinese food manufacturers concentrate procurement.
- Pharmaceuticals:Tablet excipient and controlled-release matrix applications requiring batch-level documentation. FDA 21 CFR 184.1077 compliance opens access to US generic drug manufacturers.
- Agriculture:Soil amendment and animal feed additive applications. Italian organic farming cooperatives and Spanish citrus growers specify calcium tartrate for certified organic production systems.
- Cosmetics:pH adjustment and preservative synergy in natural personal care. French green beauty formulators and German dermocosmetic brands drive specification.
Food & Beverage commands volume leadership, though Pharmaceuticals delivers the steepest expansion trajectory.
Sales Channel:
Channel economics reflect buyer scale fragmentation, with direct relationships sustaining industrial margins and digital platforms capturing small-lot cosmetics demand.
- Direct Sales:Annual framework contracts with volume guarantees dominate industrial and pharmaceutical procurement. Mediterranean refiners maintain mill-direct relationships with German bakery ingredient distributors.
- Online Retail:Specialized chemical e-procurement platforms serve sub-tonne cosmetics formulators. French small-scale manufacturers increasingly source through digital spot purchasing.
- Specialty Stores:Regional chemical distributors stock food-grade material for mid-scale European processors.
- Supermarkets:Minimal penetration; limited to consumer-facing calcium supplement formulations in select markets.
Direct Sales retains the largest share, while Online Retail is expanding most quickly among non-industrial buyers.
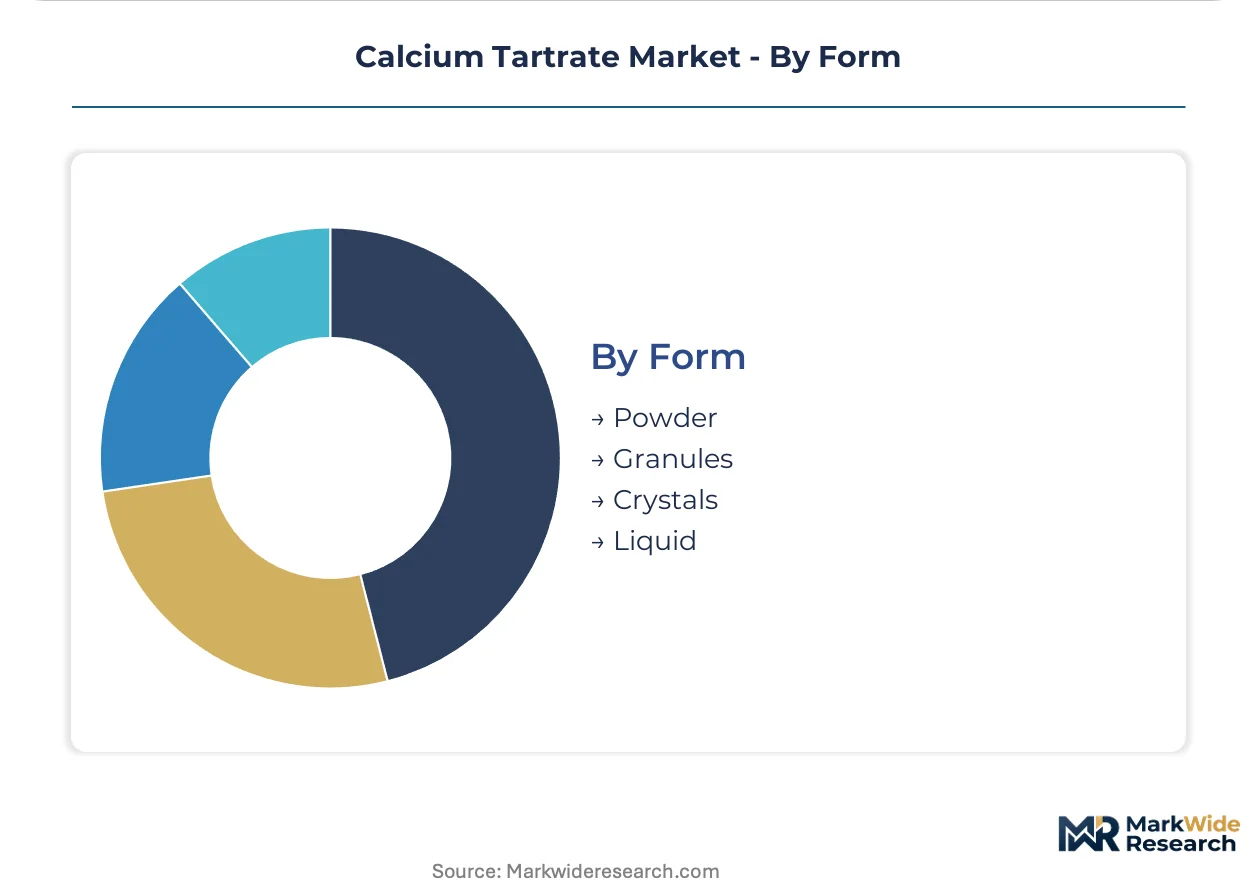
Form:
Physical form selection tracks end-use processing requirements, with powder dominating high-volume food applications and crystals commanding pharmaceutical premiums.
- Powder:Fine-ground material for dry blending in bakery premixes and instant beverage formulations. Chinese food processors and German industrial bakers specify this form for handling efficiency.
- Crystals:High-purity crystalline material for pharmaceutical tableting and controlled dissolution. USP-NF certification requirements restrict supply to GMP-compliant refiners.
- Granules:Intermediate particle size for agricultural spreading and slow-release applications. Spanish citrus cooperatives specify granules for soil amendment programs.
- Liquid:Aqueous solutions for cosmetic formulation and specialized industrial processes. Limited commercial penetration outside South Korean beauty manufacturing.
Powder holds the dominant position, though Crystals delivers the strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH registration requirements anchor European demand for certified calcium tartrate, while China's SAMR standards and the US FDA's 21 CFR framework shape parallel compliance tracks across major consumption zones.
Germany
Pharmaceutical excipient demand from Baden-Württemberg's generic drug manufacturers and clean-label bakery leavening specifications from industrial bakers drive procurement concentration. The country's national pharmaceutical regulator enforces USP-NF monograph alignment for tablet binder applications. Mannheim's chemical processing corridor hosts refiners supplying both food-grade acidulants and certified pharmaceutical crystals.
China
Expanding food processing capacity in Shandong Province and pharmaceutical contract manufacturing growth in Jiangsu Province absorb certified calcium tartrate output. SAMR's GB standard harmonization for food-grade chemicals creates dual-compliance entry requirements for foreign producers. The Yangtze River Delta cluster concentrates powder processing for instant beverage and bakery premix applications.
United States
FDA 21 CFR 184.1077 compliance opens import eligibility for tartaric acid derivatives in fortified food systems and pharmaceutical formulations. The agency's food additive standards shape purity benchmarks for tablet excipient contracts with generic drug manufacturers. New Jersey's pharmaceutical corridor and California's natural cosmetics formulators represent distinct demand nodes.
France
Languedoc-Roussillon wine cooperatives supply grape lees feedstock to refiners serving bakery ingredient distributors and pharmaceutical excipient buyers. ANSM's pharmaceutical manufacturing standards intersect with ECHA REACH documentation for tartaric acid derivative placement. The Bordeaux-Toulouse axis anchors pomace processing infrastructure subsidized under EU Green Deal circular economy funding.
Spain
Valencia's refiners pilot electrodialysis-based recovery systems for energy-efficient tartaric acid extraction from wine lees. The country's national food safety authority enforces EU regulatory alignment for food-grade chemical exports. La Rioja's vineyard clusters and Catalonia's cooperatives monetize pomace streams previously treated as disposal costs.
Calcium Tartrate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the calcium tartrate value chain. The market structure concentrates around Mediterranean wine-chemistry refiners with captive pomace access and Asian chemical processors with scale-driven powder production. Three archetypes dominate: vertically integrated vineyard-linked refiners, independent tartaric acid derivative specialists, and diversified food-ingredient distributors. Competitive moves center on long-term grape lees contracting and GMP-compliant crystallization capacity expansion.
Among vineyard-integrated refiners, Alvinesa Natural Ingredients and REVICO France exemplify the backward-integrated archetype controlling feedstock from grape pomace sourcing through refined output. Grap'Sud occupies a position representing crystallization technology specialization for high-purity food grade variants. These three anchors illustrate how Mediterranean wine-chemistry expertise translates into differentiated positioning against cost-focused Asian competitors.
| Leading Market Players |
|---|
| Alvinesa Natural Ingredients |
| REVICO France |
| Grap'Sud |
| Brenn O Kem |
| Derivados Vinicos |
| Caviro Group |
| American Tartaric Products |
| Tarcol |
| Ninghai Organic Chemical Factory |
| Others |
Supply Flow & Price Mechanics
Long-term grape lees offtake contracts tie Mediterranean refiners to Languedoc-Roussillon and La Rioja cooperatives, locking in feedstock access while anchoring price visibility against harvest volatility. This structure shields certified producers from spot market swings but compresses margins when citric acid substitutes erode acidulant pricing power.
Pricing Analysis
Pharmaceutical-grade crystals from GMP-compliant Spanish and French refiners command substantial premiums over Chinese powder exports into German bakery chains. Pricing stratifies across USP-NF certified, food-grade compliant, and industrial-grade tiers, with purity documentation serving as the primary differentiation driver. Cost compression in food-grade powder runs through corn-fermented citric acid substitution, where mineral fortification is dispensable. Small cosmetics formulators sourcing through digital platforms exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize batch certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of dried wine lees prevails among Valencia and Bordeaux refiners to buffer climate-induced harvest gaps, contrasting with just-in-tartaric-acid delivery norms in Chinese powder processing. Supply concentrates in Spain, France, and Italy for refined output, drawing from grape pomace, crystallization solvents, and energy inputs. Single-source vulnerability haunts pharmaceutical-grade buyers dependent on GMP-certified Mediterranean crystallizers. Distribution runs through bulk chemical distributors for industrial accounts and direct mill relationships for German bakery ingredient consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium tartrate sits in early-cycle expansion as clean-label bakery reformulation and pharmaceutical excipient certification open parallel demand corridors. Penetration remains shallow in South Korean cosmetics and Chinese SAMR-registered food processing, creating runway before commoditization pressures intensify.
For Market Incumbents: Shield margin pools by securing decade-long grape lees contracts with Languedoc-Roussillon cooperatives before EU Green Deal subsidies attract new pomace processors. Invest in continuous crystallization retrofit at Valencia facilities to defend against electrodialysis-enabled entrants with lower energy footprints. Citric acid displacement in non-fortified applications demands certification moats around USP-NF and REACH dossiers. For New Entrants and Emerging Players: Differentiate on dual USP-China specification compliance to penetrate Jiangsu Province pharmaceutical contract manufacturing, where incumbent Mediterranean suppliers face SAMR registration delays. Target South Korean cosmetic grade microencapsulation as the most penetrable niche, leveraging pH-buffer positioning in sensitive-skin lines. Deploy specialized chemical e-procurement platform partnerships to reach sub-tonne French cosmetics formulators without distributor margin stacking. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated vineyard-linked refiners with captive pomace access and existing REACH registration, not standalone crystallization specialists exposed to feedstock cost spikes. Five-to-ten year viability hinges on circular economy policy durability and pharmaceutical excipient certification consolidation. Watch for electrodialysis technology maturation as inflection signal—cost parity below batch crystallization would restructure competitive economics toward distributed processing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vineyard Waste Streams | Captive pomace supply from La Rioja cooperatives secures feedstock cost visibility against climate volatility. |
| GMP-Compliant Crystallization Capacity Expansion | USP-NF certification opens tablet excipient contracts with Baden-Württemberg generic drug manufacturers. |
| Electrodialysis Technology Pilot | Valencia refiners achieving 40% energy reduction compress capital payback and enable distributed processing. |
| Dual USP-SAMR Dossier Investment | Simultaneous FDA and China registration accelerates entry into Jiangsu Province pharmaceutical corridors. |
| Long-Term Supply Agreement with Bakery Distributors | Annual framework contracts with German industrial bakers lock volume against citric acid substitution. |
Methodological Framework
Operator-level perspectives from tartaric acid derivative chemists, wine cooperative procurement managers, pharmaceutical excipient quality directors, and bakery ingredient category buyers anchored the qualitative base. These primary interviews combined with secondary validation from ECHA REACH registration databases, FDA 21 CFR 184.1077 guidance documents, SAMR GB standard filings, and EU Green Deal circular economy funding disclosures. Bottom-up segmentation modeling and top-down trade flow analysis triangulated volume estimates across purity grades and end-use applications.
Sensitivity analysis tested forecast robustness against grape harvest volatility scenarios, citric acid substitution elasticity, and pharmaceutical certification timeline delays. The analytical framework disaggregated demand across food-grade powder, pharmaceutical-grade crystals, industrial-grade bulk, and cosmetic-grade microencapsulated forms, further split by bakery leavening, tablet excipient, metal finishing, and pH buffering end uses. CAGRs derived from segment-level growth rate blending weighted by current volume shares, with electrodialysis adoption curves and SAMR harmonization schedules as key industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU circular economy subsidy flows or abrupt REACH purity threshold tightening would require recalibration. Forecasts embed assumptions around climate-induced harvest variability in Mediterranean wine regions and corn-fermented acidulant pricing stability. Revision becomes warranted when electrodialysis capital costs cross below batch crystallization retrofit economics or when Chinese pharmaceutical contract manufacturing absorption rates decelerate sharply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Guanylic Acid Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Europe Feed Additives Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Micronized Powder Market
Additives
Impact Modifier Market
Additives
Refinery Fuel Additives Market
Additives
Sorbitan Tristearate Market
Additives
Potassium Nitrate Market
Additives
Chitosan Powder Market
Additives
Fuel Additives Market
Additives
Additives for Metalworking Fluids Market
Additives
Sodium Potassium Tartrate Market
Additives
Chemical Silage Additives Market
Additives
Low VOC Coating Additives Market
Additives
Inorganic Rheology Modifiers Market