
 Global Acidulants Market | 2026-2036
Global Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acidulants Market Foresight
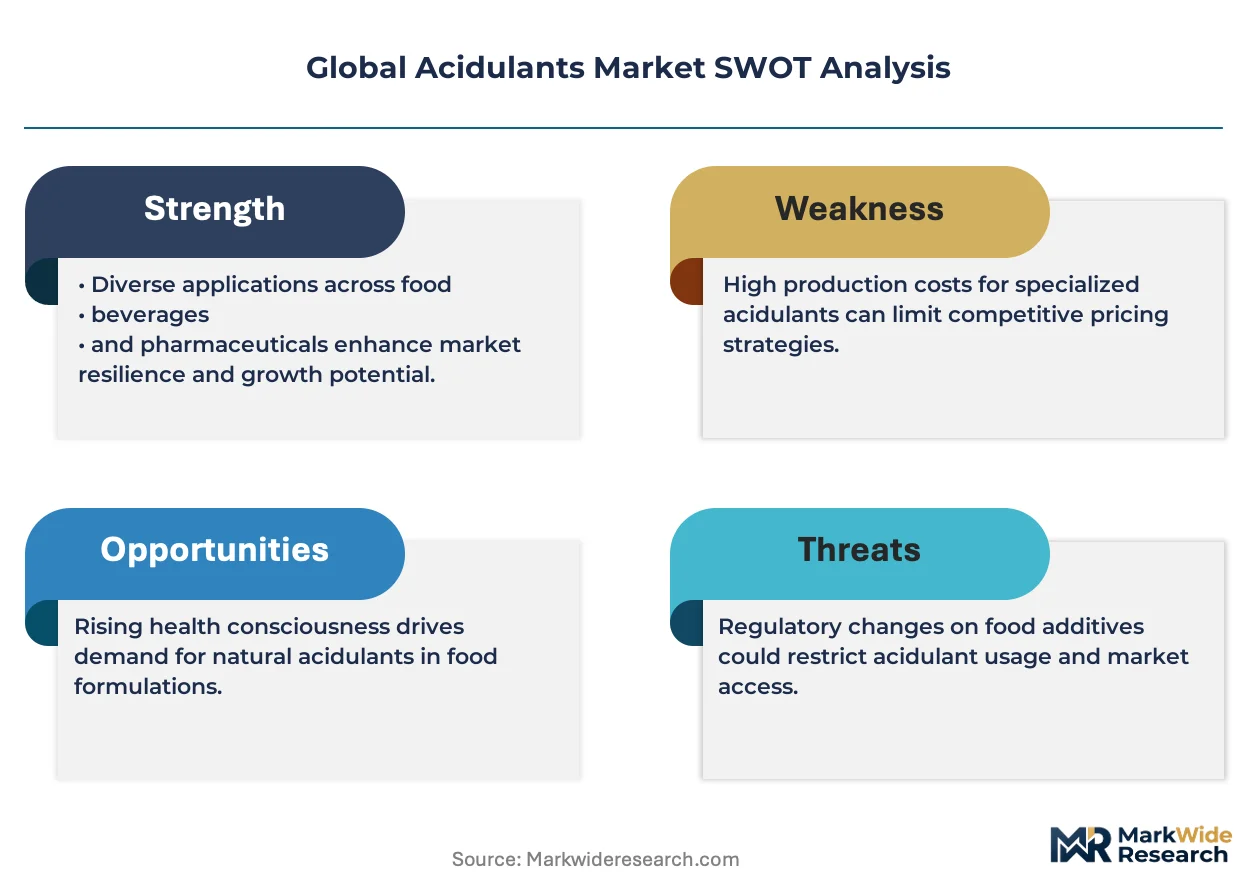
China is narrowing its citric acid supply gap through fermentation capacity additions in Shandong and Jiangsu provinces. Cargill Incorporated leverages corn-based feedstock integration to sustain cost leadership in lactic acid production. Jungbunzlauer Suisse AG anchors European pharmaceutical-grade acidulant supply through Swiss manufacturing precision. Tate & Lyle competes in malic acid specialization for beverage applications across North American and Asian markets.
Acidulants comprise organic and inorganic compounds—citric, lactic, phosphoric, and malic acids—that lower pH, enhance flavor profiles, and extend shelf stability in processed goods. Industrial production relies primarily on microbial fermentation of carbohydrate substrates, with downstream purification achieving food-grade, pharmaceutical-grade, or technical-grade specifications. Citric acid dominates volume demand as the workhorse acidulant across food and beverage applications, while lactic acid captures accelerating growth from clean-label positioning and biodegradable polymer feedstock demand. Phosphoric acid retains entrenched use in cola-type beverages though faces substitution pressure from health-conscious reformulations. Malic acid occupies a premium niche in confectionery and sports drinks where tartness modulation commands higher formulation value.
FDA food additive regulations and EPA environmental compliance govern US acidulant manufacturing discharge and purity thresholds, while REACH and EU Green Deal frameworks in Europe mandate carbon footprint transparency and sustainable sourcing verification for imported acidulants. EFSA purity standards for food-grade acids create technical barriers that favor established producers with analytical certification capabilities. Stakeholders must monitor fermentation feedstock cost volatility and regional carbon border adjustment mechanisms that could restructure competitive cost positions between Asian and Western supply bases.
Market Dynamics
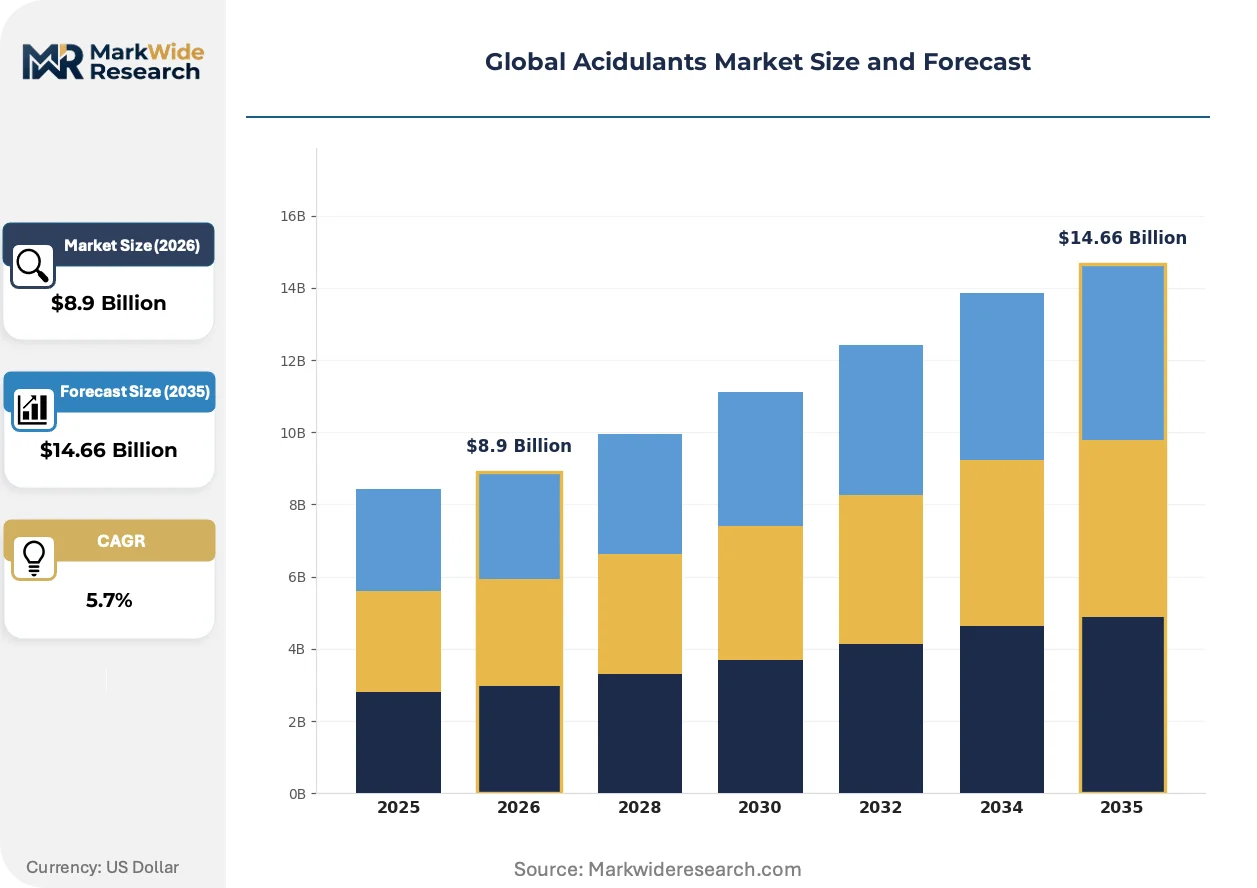
Fermentation capacity concentration in Shandong and Jiangsu provinces is tightening citric acid supply chains while REACH compliance costs in Europe filter procurement decisions toward certified producers with analytical capabilities.
Growth Catalysts
- EU Green Deal carbon footprint mandates:Importers face disclosure requirements that favor low-carbon fermentation operations, redirecting procurement toward facilities with renewable energy integration.
- Clean-label beverage reformulation:Manufacturers replace phosphoric acid with citric and malic alternatives in sports drinks and functional waters, expanding acidulant volume per SKU.
- India's food processing cluster expansion:Domestic acidulant consumption rises as export-oriented units in Maharashtra and Gujarat scale sauce and pickle production for Middle Eastern markets.
Market Restraints
- Corn feedstock price volatility:Lactic acid production margins compress when carbohydrate substrate costs spike, particularly affecting US Midwest fermentation facilities.
- Chinese citric acid supply concentration:Over half of global fermentation capacity sits in two coastal provinces, creating single-point vulnerability to environmental enforcement shutdowns.
- Phosphoric acid health substitution:Cola manufacturers face consumer pressure to reduce phosphate content, eroding the acid's entrenched position in carbonated beverages.
Strategic Opportunities
- Brazilian bio-based polymer feedstock demand:Lactic acid suppliers can redirect pharmaceutical-grade output toward polylactic acid precursors serving packaging converters.
- Direct-to-brewery malic acid distribution:Craft beverage producers in Australia and New Zealand seek tartness modulation bypassing traditional ingredient distributors.
- Japan's METI bioplastics roadmap:Government procurement preferences for biodegradable materials create acidulant demand for polymer-grade lactic acid specifications.
Industry Challenges
- Pharmaceutical-grade certification timelines:EFSA and FDA analytical validation protocols extend product qualification cycles by 18-24 months for new fermentation entrants.
- Fermentation specialist talent scarcity:Industrial microbiology expertise concentrates at established producers, constraining capacity expansion at second-tier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acidulants Market |
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.66 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Phosphoric Acid, Malic Acid Application: Food & Beverages, Pharmaceuticals, Cosmetics, Cleaning Agents End User: Food Manufacturers, Beverage Producers, Cosmetic Companies, Pharmaceutical Firms Form: Powder, Liquid, Granular, Paste |
| Companies Covered | Jungbunzlauer Suisse AG, Cargill Incorporated, Archer Daniels Midland Company, Corbion, Tate & Lyle, Brenntag North America, Univar Solutions LLC, ADM, Bartek Ingredients Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acidulants Market Shifts & Advancements
Digital process control systems are penetrating fermentation operations while regulatory disclosure requirements tighten and procurement patterns fragment across direct and channel relationships.
Continuous fermentation monitoring using inline spectroscopy is digitizing pH and biomass tracking in citric acid bioreactors. Large-scale Chinese producers in Shandong deploy these systems to maintain batch consistency under stricter SAMR environmental audits. Real-time data streams compress deviation response times from hours to minutes, reducing off-spec product volumes.
REACH substance registration deadlines for imported acidulants are forcing EU distributors to verify supply chain carbon intensity documentation. ECHA compliance costs now filter procurement toward producers with ISO 14064 greenhouse gas verification. German and Dutch beverage formulators increasingly demand batch-level traceability certificates from Asian suppliers.
Ingredient co-manufacturing agreements are fragmenting traditional distributor relationships in North American beverage markets. Mid-sized craft producers in Colorado and Oregon contract directly with Jungbunzlauer's North American logistics arm for malic acid deliveries. This channel compression eliminates margin layers but requires buyers to manage inventory and certification documentation internally.
Global Acidulants Market Segmentation
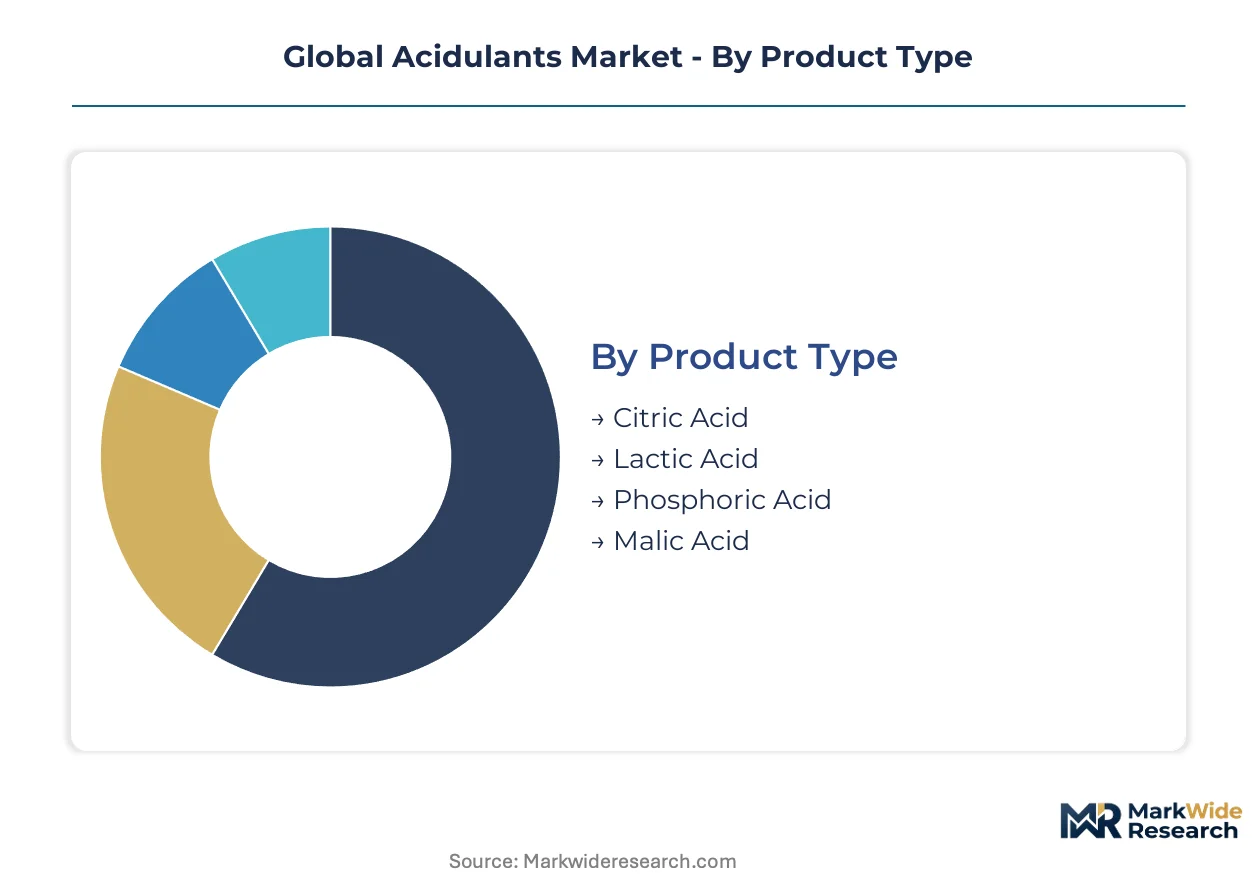
Acidulant procurement decisions cascade through multiple classification layers, from molecular specification to physical state, each filtering supplier eligibility and formulation compatibility. Manufacturers navigate these intersecting categories to match purity grades with end-use regulatory requirements while optimizing handling economics.
Product Type:
Mature commodity acids dominate volume flows while specialty fermentation derivatives capture reformulation premiums.
- Citric Acid:Fermentation-derived tricarboxylic acid from Aspergillus niger carbohydrate conversion. Beverage producers across China and India scale procurement for clean-label cola alternatives as phosphoric acid faces health-driven substitution.
- Lactic Acid:Bacterial fermentation product with dual food-grade and polymer-grade specifications. Brazilian packaging converters and Japanese bioplastics manufacturers under METI procurement guidelines drive polymer precursor demand.
- Phosphoric Acid:Inorganic acid from phosphate rock processing retains entrenched use in legacy cola formulations despite consumer pressure.
- Malic Acid:Dicarboxylic acid from petrochemical or fermentation routes commands tartness modulation premiums in confectionery.
Citric acid retains volume leadership; lactic acid holds the steepest expansion curve.
Application:
Formulation intensity varies sharply across end-use sectors, with beverage applications consuming highest acidulant volumes per unit output.
- Food & Beverages:pH reduction and flavor enhancement in processed sauces, pickles, and carbonated drinks. Maharashtra and Gujarat food processing clusters scale consumption for Middle Eastern export markets.
- Pharmaceuticals:Buffering agents and excipients requiring EMA and FDA validated purity certification. Swissmedic-registered facilities anchor European pharmaceutical-grade supply.
- Cosmetics:pH adjustment in personal care formulations with mild acid preferences.
- Cleaning Agents:Descaling and chelating functions in industrial and household formulations.
Food and beverage applications anchor demand tonnage; pharmaceutical specifications yield the highest margin realization.
End User:
Procurement sophistication diverges between multinational formulators with in-house certification teams and mid-tier buyers relying on distributor documentation.
- Food Manufacturers:Sauce and condiment producers in Shandong province integrate directly with regional citric acid fermentation facilities.
- Beverage Producers:Craft operators in Colorado and Oregon contract malic acid through direct logistics arrangements bypassing traditional channels.
- Cosmetic Companies:Formulators seeking mild acid profiles for sensitive skin positioning.
- Pharmaceutical Firms:EMA and FDA compliance mandates filter supplier selection toward ISO 14064-verified fermentation operations.
Beverage producers drive spot market volatility; pharmaceutical firms impose the longest qualification timelines.
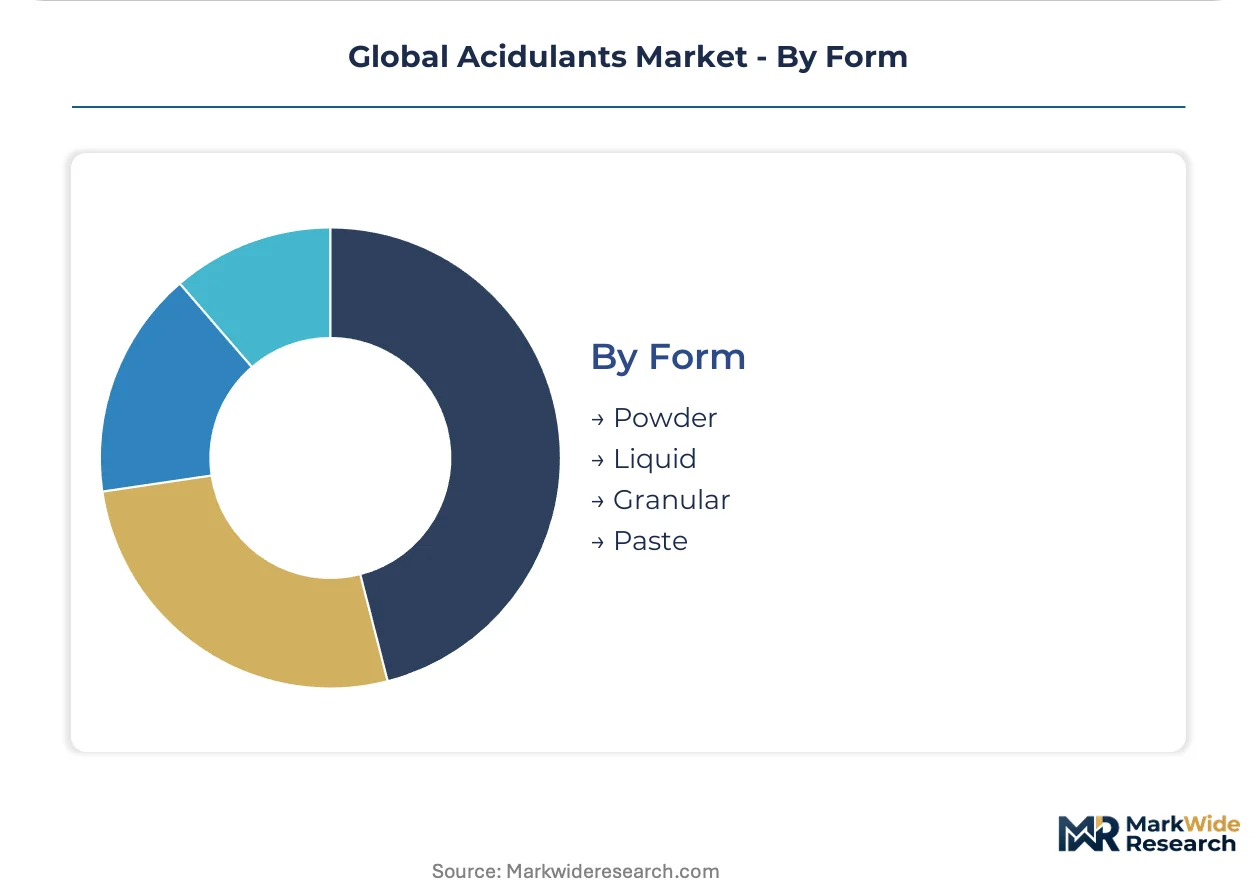
Form:
Physical state determines logistics economics and dissolution kinetics in continuous manufacturing environments.
- Powder:Spray-dried crystalline material with extended shelf stability. Bulk handling systems at large-scale beverage bottlers favor powder for automated dosing.
- Liquid:Aqueous solutions eliminating dissolution steps. Australian and New Zealand craft breweries source liquid malic acid for direct tank addition.
- Granular:Free-flowing particles reducing dust exposure in manual handling operations.
- Paste:High-concentration semisolid for specialized confectionery applications.
Powder commands the broadest installed base; liquid formats gain share in continuous processing lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes acidulants predominantly for beverage manufacturing, while India channels demand toward processed food exports, and Germany anchors pharmaceutical-grade specifications. This consumption-mix differential shapes procurement standards, regulatory compliance burdens, and supplier certification requirements across major demand centers.
China
Shandong and Jiangsu provinces host over half of global citric acid fermentation capacity, with SAMR environmental audits tightening discharge standards. The dual carbon goals framework pressures coastal facilities to integrate renewable energy or face production curtailments. Regional food manufacturers in Qingdao and Yantai scale direct procurement from neighboring fermentation plants.
United States
Midwest corn belt proximity sustains lactic acid feedstock economics for fermentation facilities serving beverage reformulation demand. FDA food additive regulations and EPA discharge permits govern purity thresholds and environmental compliance. Colorado and Oregon craft beverage clusters source malic acid through direct logistics arrangements bypassing traditional distribution channels.
India
Maharashtra and Gujarat food processing clusters expand acidulant consumption for sauce and pickle production targeting Middle Eastern export markets. FSSAI purity standards and DGFT export documentation requirements filter supplier eligibility toward certified operations. Domestic fermentation capacity additions in Gujarat aim to reduce import dependence for citric acid specifications.
Germany
REACH substance registration and ECHA carbon intensity disclosure requirements redirect procurement toward ISO 14064-verified fermentation operations. The EU Green Deal mandates favor low-carbon acidulant imports, elevating compliance costs for uncertified suppliers. Beverage formulators in Bavaria and North Rhine-Westphalia demand batch-level traceability certificates from Asian suppliers.
Brazil
Packaging converters in São Paulo and Rio Grande do Sul drive polymer-grade lactic acid demand for polylactic acid precursor applications. ANVISA pharmaceutical-grade specifications and national bioplastics incentives under the national bioeconomy framework shape import qualification timelines. Regional sugarcane ethanol infrastructure offers carbohydrate feedstock alternatives to corn-based fermentation inputs.
Global Acidulants Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where analytical certification capabilities anchor premium positioning while feedstock integration secures cost leadership. The vendor base separates into fermentation specialists with pharmaceutical-grade validation, diversified agricultural processors with captive carbohydrate supplies, and regional distributors with logistics reach. Strategic moves concentrate on backward integration into feedstock cultivation and direct-to-manufacturer channel compression.
Within the fermentation specialist tier, Jungbunzlauer Suisse AG occupies a position exemplifying Swiss precision in pharmaceutical-grade acidulant supply, while Cargill Incorporated represents the agricultural processor archetype with corn-based feedstock integration sustaining lactic acid cost structures. Tate & Lyle sits within the specialty acidulant segment, anchoring malic acid positioning for beverage applications. These three entities collectively illustrate the competitive vectors of certification depth, feedstock control, and formulation specialization that define market positioning.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Corbion |
| Tate & Lyle |
| Brenntag North America |
| Univar Solutions LLC |
| ADM |
| Bartek Ingredients Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on Shandong and Jiangsu fermentation clusters determines both the spread between pharmaceutical-grade premiums and economy-grade spot pricing and the three-tier distribution architecture spanning certified direct contracts, regional distributors, and spot market brokers. Corn feedstock volatility in the US Midwest and EU carbon border adjustment exposure for Asian imports compress margins at standard-grade tiers while reinforcing premium capture at validated facilities.
Pricing Analysis
Chinese-origin citric acid trades at substantial discounts to Swiss and German pharmaceutical-grade equivalents, with spreads widening under REACH compliance documentation burdens. Pricing stratifies across premium, standard, and economy tiers based on EMA/FDA validation status and ISO 14064 carbon verification. Cost compression in standard-grade lactic acid is intensifying because of corn price spikes and renewable energy transition costs. Beverage manufacturers exhibit highest price sensitivity, while pharmaceutical firms absorb premiums for analytical certification.
Supply Chain Analysis
REACH substance registration deadlines function as de facto export controls, filtering acidulant flows toward ECHA-pre-registered producers with established Only Representative structures. Manufacturing concentrates in China, the United States, and Germany, with raw material dependencies on corn carbohydrate feedstocks, phosphate rock processing, and petrochemical-derived precursors. Single-source vulnerability from Shandong environmental enforcement actions threatens global citric acid availability. Distribution runs through certified importer-distributors for EU pharmaceutical accounts and direct logistics arrangements for North American beverage clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service offerings for carbon footprint documentation and batch-level traceability are expanding faster than commodity acidulant volumes, creating attach-rate opportunities for analytical laboratories and compliance consultancies.
For Market Incumbents: Entrench pharmaceutical-grade positioning through Swissmedic and FDA validation investments, while securing captive corn supply contracts in the US Midwest to buffer lactic acid margin compression. Expand fermentation capacity in Gujarat to offset Shandong concentration risk and capture India's export-oriented food processing demand. For New Entrants and Emerging Players: Polymer-grade lactic acid specifications for Brazilian packaging converters and Japanese bioplastics manufacturers under METI procurement guidelines represent the most penetrable entry points. Direct-to-brewery malic acid distribution in Australia and New Zealand bypasses entrenched distributor relationships. Lead with carbon-negative fermentation positioning validated through ISO 14064 verification. For Investors and Strategic Acquirers: EU Green Deal carbon intensity disclosure mandates reshape the acquisition landscape toward ISO 14064-verified fermentation assets with existing Only Representative registrations. Long-term viability hinges on feedstock flexibility and regulatory certification depth rather than scale alone. Monitor SAMR environmental enforcement intensity in Shandong as the critical supply disruption signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Feedstock Cultivation | Cargill's captive carbohydrate supply secures lactic acid cost leadership against spot market volatility. |
| Pharmaceutical-Grade Certification Investment | Jungbunzlauer's Swissmedic-registered facilities command 40-60% price premiums over standard-grade competitors. |
| Direct-to-Manufacturer Channel Compression | Colorado craft breweries contracting malic acid directly eliminates distributor margin layers. |
| Renewable Energy Fermentation Integration | Shandong facilities integrating solar and biogas reduce EU carbon border adjustment exposure. |
| Polymer-Grade Lactic Acid Capacity Expansion | Brazilian PLA precursor demand from São Paulo packaging converters redirects pharmaceutical-grade output. |
Research Methodology
The analysis maps citric acid, lactic acid, phosphoric acid, and malic acid sub-sectors, each validated through fermentation plant managers, beverage procurement leads, pharmaceutical regulatory affairs directors, and distribution channel partners. Primary interviews with Shandong facility operators and Bavarian formulators combined with secondary validation from SAMR discharge records, ECHA registration databases, FSSAI purity standards, and SEC 10-K filings. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Assumptions held corn feedstock pricing and EU carbon border adjustment implementation timelines fixed across the analysis window, while fermentation yield improvements and clean-label substitution rates varied. Segmentation dimensions modeled include acidulant molecular type, purity grade tier, physical form, end-use application, and regional production hub. CAGRs derived from weighted average of historical capacity expansion trajectories and projected reformulation intensity in beverage applications.
Practitioners should monitor SAMR environmental enforcement patterns and EU carbon border adjustment mechanism final rules for early signals of supply constraint or cost structure shift. Forecasts reflect these documented assumptions; material shifts in Chinese environmental policy stringency or REACH substance registration deadlines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Inhibited Propylene Glycol Market
Additives
Marine Fuel Additives Market
Additives
Silage Additives Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Silicone Additives Market
Additives
Global Packaging Additives Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Defoaming Coating Additives Market
Additives
Sorbitan Esters Market
Additives
Enzyme Stabilizer Market
Additives
Liquid Silage Additive Market
Additives
Gasoline Additives Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Liquid Thickeners Market
Additives
Global Slip Additives Market
Additives
Green Chelates/Natural Chelating Agents Market