
 Global Slip Additives Market | 2026-2036
Global Slip Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Slip Additives Market Outlook
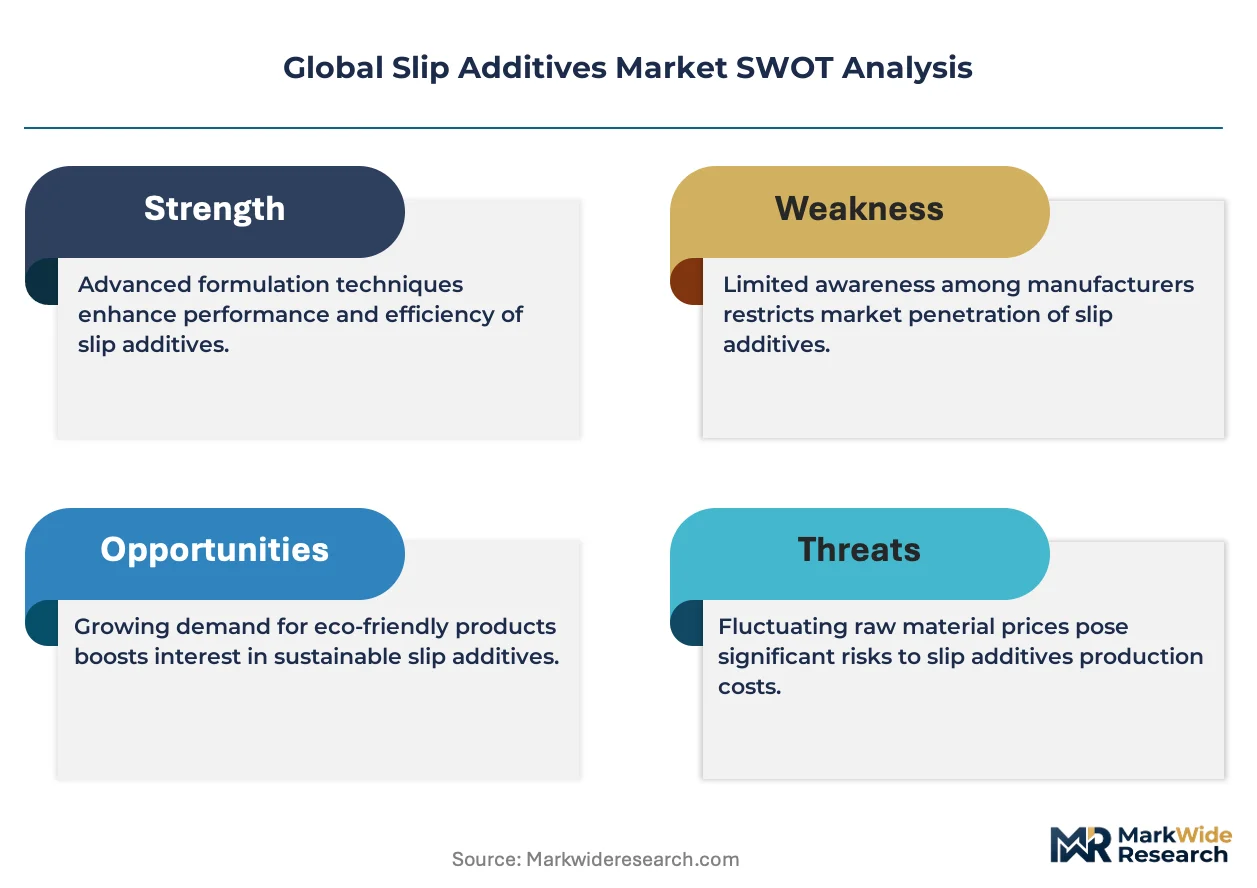
The gap between premium high-performance slip additives and commodity fatty amide grades is expanding as film converters demand lower coefficient-of-friction specifications for high-speed packaging lines. Croda International Inc. leverages its oleochemical feedstock control to sustain margin pools in amide chemistry. BASF SE anchors its position through backward integration into polymer-compatible wax synthesis. Evonik Industries AG differentiates via specialized silicone-modified additives for electronics-grade films.
Slip additives are surface-active compounds, typically fatty acid amides or synthetic waxes, that migrate to polymer interfaces to reduce static and kinetic friction coefficients below 0.2 in processed films and coatings. Manufacturers disperse these agents at 0.1-2.0 weight percent during extrusion to enable machinability in automated packaging and printing operations. The packaging application segment leads volume consumption due to the ubiquity of flexible food and consumer goods wrapping, while water-based technology is gaining fastest as converters eliminate solvent emissions to comply with tightening volatile organic compound limits. Polypropylene resin compatibility commands premium pricing because slip agent selection must match polymer crystallinity and processing temperatures.
REACH registration requirements in Europe and FDA food-contact substance notifications in the United States impose migration limits and toxicological documentation burdens that filter out smaller additive suppliers. China's GB standards for food packaging materials and Japan's JIS specifications for plastic films add further compliance layers for exporters. Stakeholders must monitor regulatory divergence between jurisdictions where migration test protocols and approved substance lists diverge, forcing dual formulation strategies or regional product variants.
Market Dynamics
Flexible packaging converters in Vietnam and Indonesia are accelerating amide-based slip agent procurement to match high-speed line specifications, while REACH and FDA purity mandates filter supplier pools across all export corridors.
Growth Catalysts
- REACH migration thresholds:ECHA's tightening purity requirements for migratory chemistries are consolidating demand toward certified amide suppliers capable of toxicological documentation.
- High-speed packaging automation:Film converters deploying automated filling lines demand coefficient-of-friction specifications below 0.2, pulling premium additive grades.
- Southeast Asia capacity expansion:Vietnam and Indonesia are adding flexible packaging conversion lines faster than regional additive supply, creating import pull.
Market Restraints
- Oleochemical feedstock volatility:Erucamide and oleamide prices track rapeseed and soybean oil futures, compressing margin predictability for amide producers.
- Supplier concentration in EU amide synthesis:Three integrated oleochemical players control majority European fatty amide output, creating single-source risk.
- Silicone additive substitution:Electronics-grade film producers are testing polydimethylsiloxane alternatives for ultra-low friction requirements.
Strategic Opportunities
- India's food packaging modernization:FSSAI is tightening food-contact material rules, creating certified additive demand as domestic converters upgrade.
- Water-based coating conversion:Solvent emission regulations are pushing ink and coating formulators toward water-based systems compatible with migratory slip agents.
- Polypropylene recycling integration:Mechanical recycling streams require slip agent reformulation to manage mixed-polymer friction profiles in reprocessed film.
Industry Challenges
- Migration testing protocol divergence:EU, US, and Chinese food-contact test methods produce conflicting results for the same additive-polymer combination, forcing dual formulation development.
- Extrusion dispersion uniformity:Masterbatch producers struggle to maintain 0.1-2.0 weight percent distribution consistency across high-throughput lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Slip Additives Market |
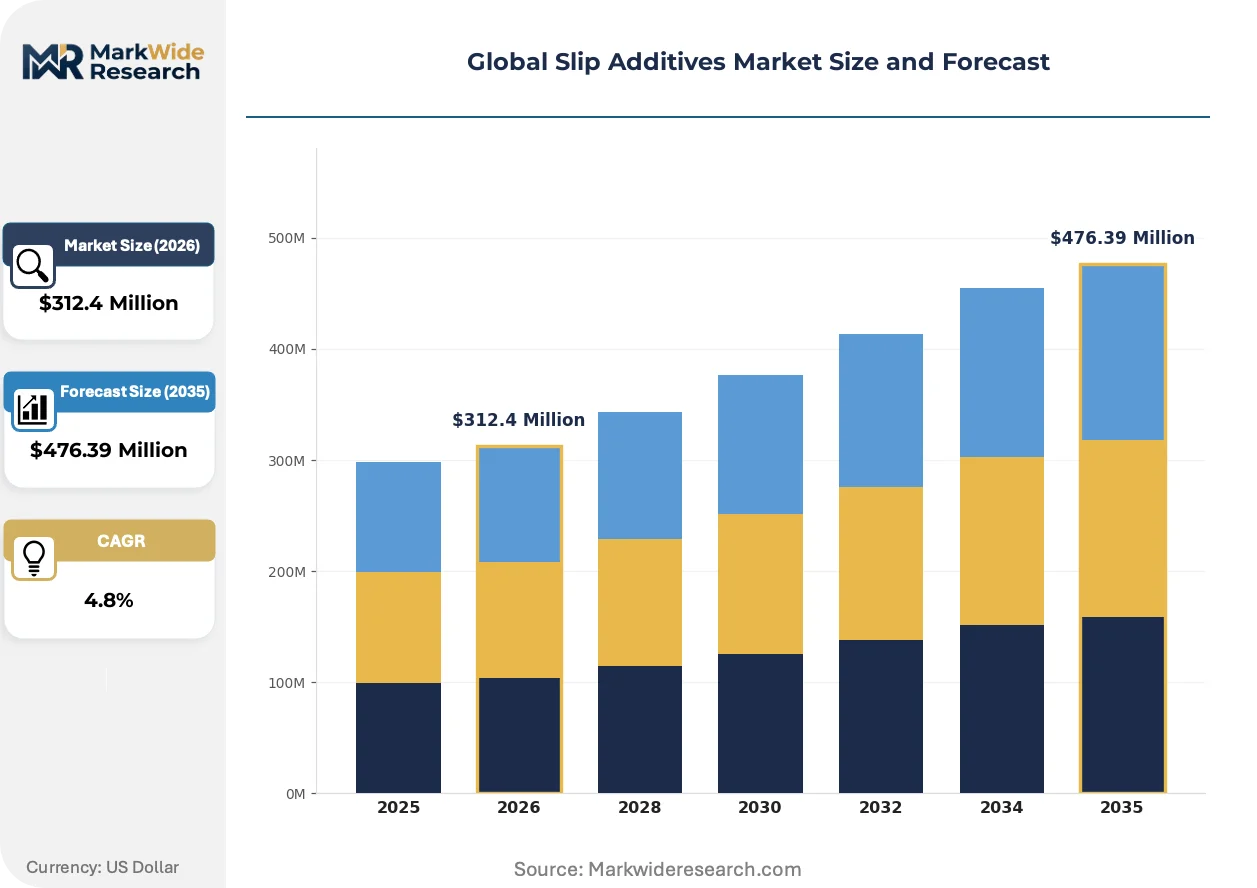
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Amides, Waxes Application: Packaging, Coatings, Plastic Films, Adhesives End Use Industry: Food & Beverage, Personal Care, Electronics, Automotive Technology: Conventional, Water-Based, Solvent-Based, High-Performance |
| Companies Covered | Fine Organics, Croda International Inc., PMC Biogenix, Honeywell International Inc., Lubrizol Corporation, BASF SE, Emery Oleochemicals, Evonik Industries AG, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Slip Additives Market Strategic Shifts
Slip additive formulation is pivoting from commodity fatty amide grades toward polymer-specific architectures, with regulatory compliance and processing compatibility now co-equal design constraints.
Bio-based erucamide from non-GMO rapeseed feedstock is integrating into European packaging supply chains as brand owners face CSRD Scope 3 reporting pressure. Major flexible film converters in Germany and the Netherlands specify certified sustainable content in procurement tenders. The technology is integrating carbon accounting into additive selection criteria alongside performance metrics.
REACH registration requirements for polymer additives are expanding substance documentation burdens beyond basic fatty amides into specialized wax and silicone-modified chemistries. ECHA's 2024 updated guidance on nanomaterial classification captures certain surface-modified additives. Electronics-grade film exporters to the EU are reformulating to pre-register alternative chemistries ahead of sunset date pressure.
Film converters are consolidating additive procurement through integrated masterbatch suppliers rather than direct chemical sourcing. Large packaging groups in Indonesia and Thailand now specify finished masterbatch with pre-dispersed slip agents, compressing the independent additive distribution channel. This concentration is most visible in Southeast Asia where converter scale has reached threshold volumes for direct compounder relationships.
Global Slip Additives Market Segmentation
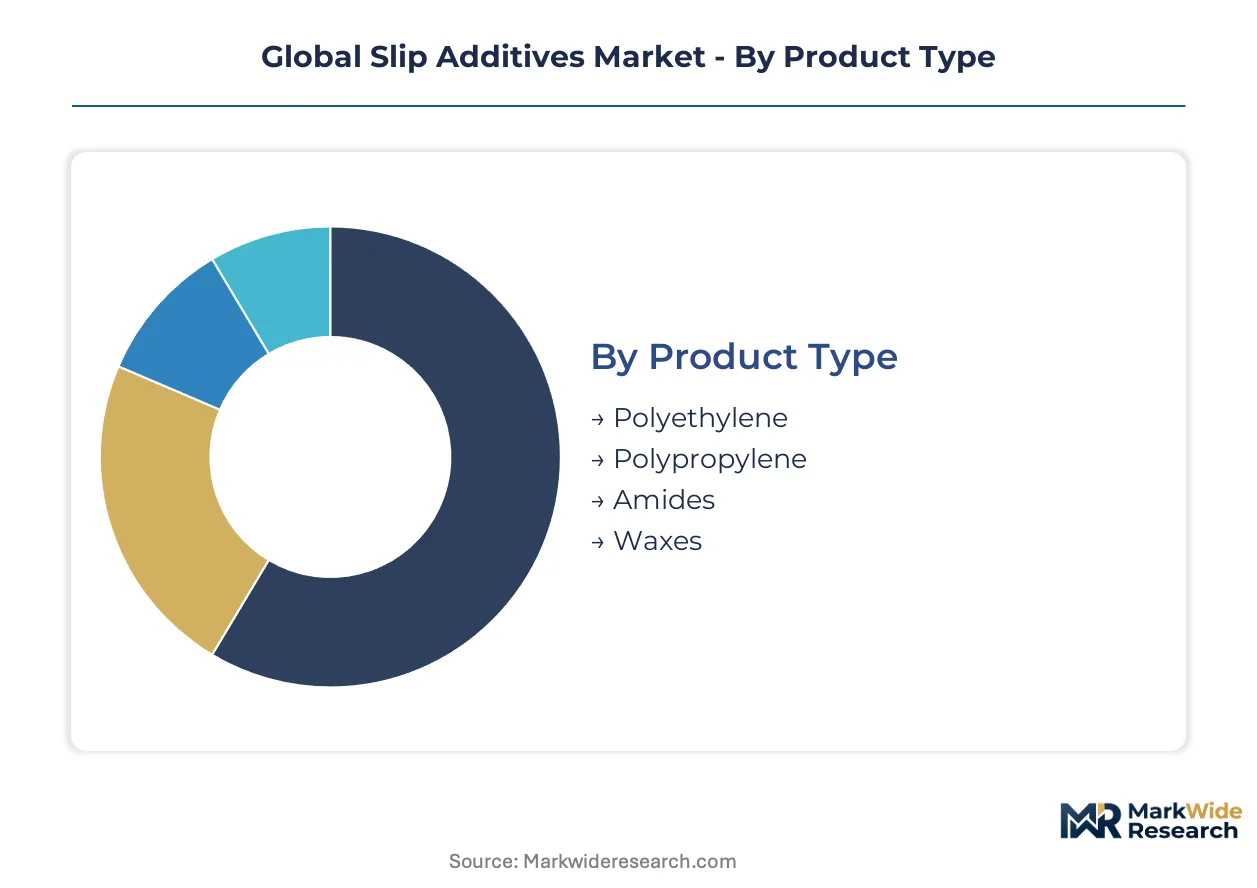
Slip additive selection pivots on polymer compatibility, regulatory migration limits, and processing temperature windows. Segment boundaries blur as suppliers engineer hybrid chemistries spanning multiple categories to capture converter consolidation.
Product Type:
Polypropylene-compatible additives command premium pricing against polyethylene grades due to crystallinity-matching complexity and higher thermal stability requirements.
- Polyethylene:Linear low-density polyethylene film extrusion consumes the largest additive volumes globally, with converters in Vietnam and Indonesia driving procurement acceleration for high-speed packaging lines. Migration thresholds under REACH and FDA rules filter supplier pools toward certified amide producers capable of toxicological documentation.
- Polypropylene:Isotactic polypropylene demands slip agents with melting points above 140°C to prevent volatilization during biaxial orientation, creating formulation barriers that sustain margin premiums. Electronics-grade film producers in Japan and Germany specify these grades for ultra-low coefficient-of-friction requirements.
- Amides:Erucamide and oleamide dominate flexible food packaging, tracking rapeseed and soybean oil futures for feedstock cost volatility.
- Waxes:Synthetic and natural waxes serve coating applications requiring non-migratory surface modification.
Today's leader: Polyethylene. Tomorrow's challenger: Polypropylene.
Application:
Packaging film lines absorb additive volumes at scale, while coating formulators shift procurement toward water-compatible grades under solvent emission constraints.
- Packaging:Flexible food and consumer goods wrapping generates the dominant share of slip additive consumption, with Southeast Asian converters scaling amide purchases to match shelf-life extension targets. Automated filling lines demand coefficient-of-friction specifications below 0.2, pulling premium additive grades from certified suppliers.
- Coatings:Water-based coating conversion is expanding most quickly as ink and coating formulators eliminate solvent emissions to comply with tightening volatile organic compound limits in the EU and US.
- Plastic Films:Electronics-grade films require specialized silicone-modified additives for ultra-low friction requirements in display and semiconductor packaging.
- Adhesives:Pressure-sensitive adhesive tapes utilize slip agents to control unwind force and lamination behavior.
Packaging holds volume dominance. Coatings present the steepest expansion trajectory.
End Use Industry:
Food-contact regulations concentrate procurement toward migration-tested suppliers, while electronics-grade specifications reward performance over cost.
- Food & Beverage:Shelf-life extension targets in Southeast Asia and India's FSSAI tightening drive certified additive demand as domestic converters upgrade food-contact material compliance.
- Personal Care:Flexible wrapping for cosmetics and hygiene products requires odor-neutral slip agents with low extractables profiles.
- Electronics:Display films and semiconductor packaging specify silicone-modified additives for coefficient-of-friction control below 0.15.
- Automotive:Interior trim films and protective coatings utilize wax-based slip agents for UV stability and durability.
Food & Beverage anchors procurement volumes. Electronics commands the highest specification premiums.
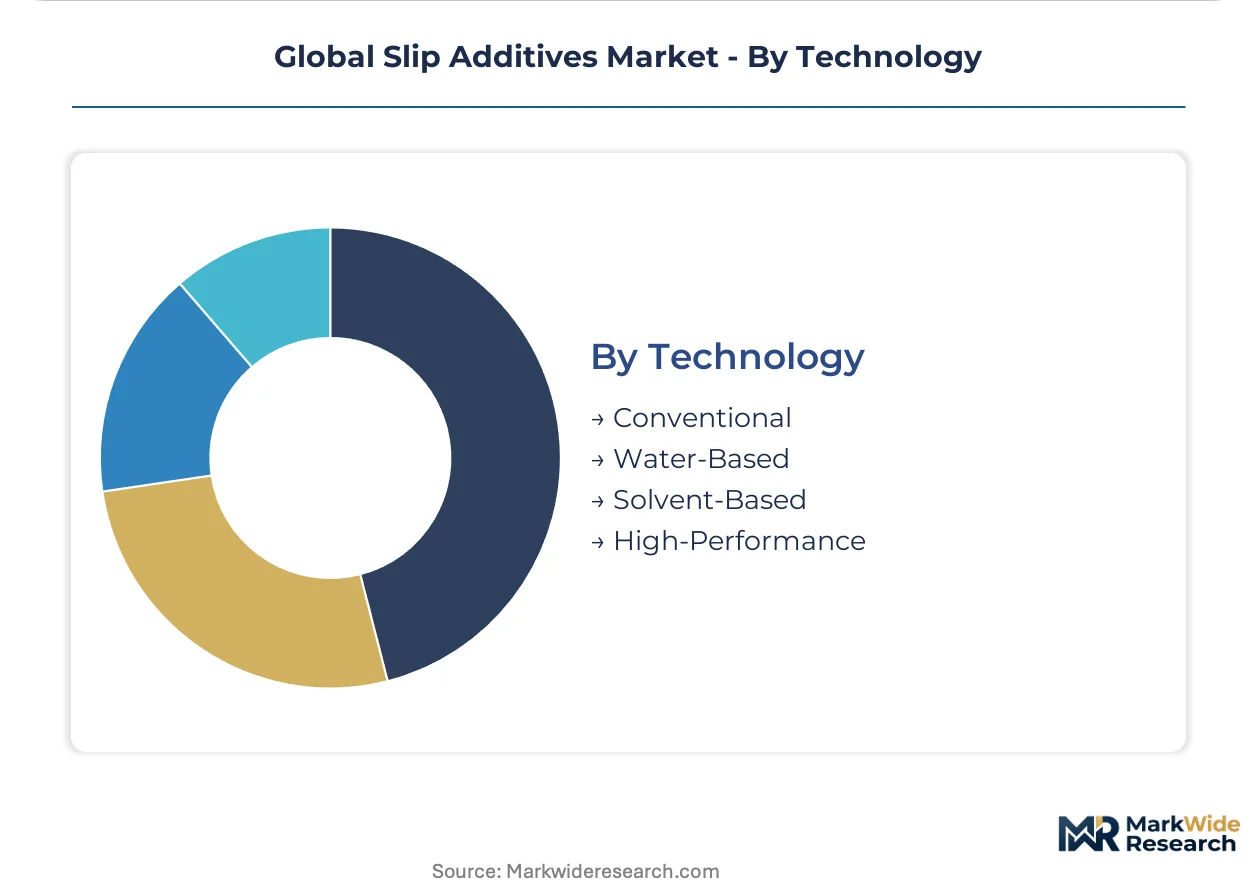
Technology:
Conventional fatty amide chemistry faces displacement pressure from water-based and high-performance architectures as regulatory and processing demands diverge.
- Conventional:Standard fatty acid amide formulations serve commodity film extrusion where cost minimization outweighs performance optimization.
- Water-Based:Solvent emission regulations across Europe and North America push ink and coating formulators toward water-based systems compatible with migratory slip agents.
- Solvent-Based:Niche industrial coatings and specialty adhesives retain solvent-carrier systems where drying speed and substrate adhesion are critical.
- High-Performance:Polymer-specific architectures with tailored molecular weights and surface activity command premium positioning for electronics and medical packaging applications.
Conventional technology retains volume leadership. Water-Based systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemists and polymer engineers cluster around major flexible packaging conversion hubs, with talent pools densest in Germany, the United States, and Vietnam where high-speed line specifications demand precise additive formulation expertise.
United States
Food packaging film converters in the Midwest and Southeast are scaling amide-based slip agent procurement to meet automated filling line specifications below 0.2 coefficient-of-friction. FDA food-contact substance notifications impose migration limits and toxicological documentation burdens that filter supplier pools toward certified producers. The Chicago and Atlanta metropolitan areas concentrate flexible packaging conversion capacity where domestic converters upgrade compliance systems.
Germany
Electronics-grade film producers in Bavaria and Baden-Württemberg specify silicone-modified additives for ultra-low friction requirements in display and semiconductor packaging. ECHA's REACH registration requirements expand substance documentation burdens beyond basic fatty amides into specialized wax chemistries. The Rhine-Main and Stuttgart industrial corridors anchor European amide synthesis where three integrated oleochemical players control majority output.
Vietnam
Flexible packaging converters in Ho Chi Minh City and the surrounding industrial zones are accelerating amide-based slip agent procurement faster than regional additive supply, creating import pull. The country's national food safety authority is tightening food-contact material rules in alignment with export market requirements. The southern provinces around Bình Dương and Đồng Nai concentrate new conversion line installations where converter scale has reached threshold volumes for direct compounder relationships.
China
GB standards for food packaging materials add compliance layers for domestic producers and exporters alike, with migration test protocols diverging from EU and US methods. The Yangtze River Delta and Pearl River Delta clusters host the largest concentrations of flexible film extrusion capacity. Shanghai and Shenzhen-based converters are consolidating additive procurement through integrated masterbatch suppliers rather than direct chemical sourcing.
Indonesia
Large packaging groups in Jakarta and Surabaya now specify finished masterbatch with pre-dispersed slip agents, compressing the independent additive distribution channel. The country's national standards body is harmonizing food-contact regulations with ASEAN frameworks to facilitate regional trade. The Java corridor concentrates fastest-growing flexible packaging conversion capacity where shelf-life extension targets drive certified additive demand.
Global Slip Additives Market Competitive Environment
Top-tier vendors anchor integrated oleochemical and petrochemical supply chains, while mid-scale specialists occupy polymer-specific formulation niches. The market structure tilts toward consolidation in European amide synthesis where feedstock control determines margin sustainability. Three strategic archetypes dominate: integrated oleochemical producers with captive fatty acid supply, diversified chemical conglomerates with polymer science platforms, and specialized additive houses with regulatory certification depth. Capacity expansion and backward integration into wax synthesis represent the dominant competitive moves.
Among European-integrated specialists, BASF SE and Evonik Industries AG exemplify divergent strategic positioning within the premium additive tier. Croda International Inc. occupies a position representing the oleochemical feedstock control archetype. These three entities anchor the competitive landscape through distinct chemistry platforms rather than overlapping product portfolios, with each representing a viable path to margin defense amid regulatory tightening and feedstock volatility.
| Leading Market Players |
|---|
| Fine Organics |
| Croda International Inc. |
| PMC Biogenix |
| Honeywell International Inc. |
| Lubrizol Corporation |
| BASF SE |
| Emery Oleochemicals |
| Evonik Industries AG |
| Lonza Group |
| Others |
Value Chain & Pricing Dynamics
Specialized chemists and polymer engineers cluster in Germany's Rhine-Main corridor and Vietnam's southern industrial zones, with labor-cost differentials of roughly three-to-one widening spreads between premium certified grades and commodity amide formulations. This workforce geography concentrates formulation expertise in high-regulation jurisdictions while volume production migrates toward lower-cost conversion hubs, creating tiered pricing that reflects certification burden rather than raw material cost alone.
Pricing Analysis
Bundled masterbatch supply commands premium positioning against unbundled additive procurement, with integrated compounders capturing margin through dispersion technology and regulatory documentation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-notified amides for food contact from REACH-registered industrial grades and uncertified commodity erucamide. Cost compression in economy tiers is intensifying because Indonesian and Vietnamese converters are consolidating procurement through direct compounder relationships. Small and mid-scale film producers remain most price-sensitive, while electronics-grade buyers prioritize coefficient-of-friction performance over unit cost.
Supply Chain Analysis
Erucamide and oleamide supply rests on European oleochemical producers with captive rapeseed and soybean oil processing, drawing from agricultural feedstocks in Germany, the Netherlands, and Malaysia. Specialty wax inputs feed from petrochemical complexes in the United States and South Korea, while silicone-modified additives source from Japanese and German precision chemical houses. Single-source vulnerability concentrates in European amide synthesis where three integrated players control majority output. Distribution runs through masterbatch compounders in Southeast Asia who pre-disperse additives for direct converter delivery, compressing independent chemical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-regulated European formulation expertise and Southeast Asian conversion scale, with regulatory compliance costs in Germany and the Netherlands running substantially above FSSAI-aligned requirements in India and Vietnam.
For Market Incumbents: Cement feedstock security through backward integration into oleochemical processing or long-term offtake agreements with rapeseed and soybean oil processors. Lock in converter relationships via certified masterbatch supply with embedded regulatory documentation, defending against silicone additive substitution in electronics-grade applications by investing in polymer-specific amide architectures with sub-0.15 coefficient-of-friction performance. For New Entrants and Emerging Players: E-commerce-enabled technical sales platforms offer low-friction entry into fragmented Southeast Asian converter bases, particularly in Vietnam's Bình Dương and Đồng Nai provinces where procurement consolidation has not yet reached threshold scale. Target water-based coating formulators in Europe and North America with amide grades engineered for VOC-compliant ink systems, leveraging regulatory pressure as the go-to-market wedge. For Investors and Strategic Acquirers: Integrated packaging conglomerates are the most active acquirer in this space, seeking captive additive supply to secure margin pools and formulation control. Over a multi-year horizon, targets with REACH registration depth and Southeast Asian distribution infrastructure offer defensive positioning against feedstock volatility. Watch for divergence between EU and Chinese migration test protocols as the signal triggering dual-formulation capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstock | Croda International Inc. and European peers defend margin pools against rapeseed oil volatility through captive supply. |
| Masterbatch Supply Consolidation | Indonesian and Thai packaging groups compress independent distribution by specifying pre-dispersed additive systems. |
| REACH Registration Investment | ECHA documentation burdens filter supplier pools toward certified producers capable of toxicological data packages. |
| Water-Based Coating Grade Development | EU and US VOC regulations pull formulation investment toward migratory amides compatible with aqueous ink systems. |
| Polypropylene Recycling Integration | Mechanical reprocessing streams require reformulated slip agents managing mixed-polymer friction in circular film applications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer engineers at flexible packaging converters, procurement leads at masterbatch compounders, regulatory affairs managers at additive suppliers, and plant managers at oleochemical processing facilities with secondary validation through ECHA registration databases, FDA food-contact substance notifications, customs and trade flow data, and SEC filings from listed chemical conglomerates. Bottom-up demand modeling from end-use application volumes and top-down supply analysis from production capacity declarations were triangulated to converge on market estimates.
Segment-weighting approaches applied differential growth assumptions across polymer compatibility tiers, regulatory certification levels, and regional conversion capacity expansion rates. The analytical framework modeled polyethylene versus polypropylene additive demand, packaging versus coatings application splits, and conventional versus water-based technology migration throughout the forecast period. CAGRs derived from historical elasticity relationships between flexible packaging output and slip additive consumption intensity, with cross-referencing to rapeseed and soybean oil price trajectories as feedstock cost proxies.
The model assumes a particular technology adoption path; alternative pathways for silicone-modified additive substitution in electronics-grade films would alter the outlook for premium amide demand. Forecasts reflect assumptions about REACH registration timeline adherence, Southeast Asian conversion capacity buildout rates, and oleochemical feedstock price stability. Divergence in EU-US-China migration test protocols, feedstock volatility spikes, and converter consolidation beyond threshold scale represent triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Carboxylic Acids Based Esters Market
Additives
Carboxymethyl Cellulose Market
Additives
Green Polymer Additive Market
Additives
Asia Pacific Silage Additives Market
Additives
Texture Modifier Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Global Pearlizing Agent Market
Additives
Sodium Metabisulfite Market
Additives
Cetane Improver Additives Market
Additives
Anti-Slip Additives Market
Additives
Triazine UV Absorber Market
Additives
Drilling Fluid Additives Market
Additives
Sodium Citrate Dihydrate Market
Additives
Sodium Caprylate Market
Additives
Germany Sodium Reduction Ingredient Market