
 US Cheese Market | 2026-2036
US Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
US Cheese Market Intelligence
Asset-light dairy processing contracts and third-party cheese aging facilities is reconfiguring competitive entry barriers for mid-tier brands. Kraft Heinz Company leverages its retail shelf space dominance to sustain branded cheese margins across conventional channels. Saputo Inc. anchors its position through backward integration into fluid milk supply across the Upper Midwest. Dairy Farmers of America competes via cooperative scale, controlling raw milk sourcing for private-label programs.
Cheese comprises milk proteins coagulated through enzymatic or acid-based processes, with moisture content, fat-in-dry-matter ratios, and aging duration defining commercial grades for melting, shredding, or table use. Cheddar occupies the largest production volume position, while Mozzarella captures expanding food service demand driven by pizza chain expansion. Grated and shredded packaging formats command premium unit economics due to labor-cost savings for institutional buyers. The manufacturing end-user segment sources commodity blocks for further processing into prepared foods.
The USDA's Agricultural Marketing Service grading standards and the FDA's Current Good Manufacturing Practices shape product specifications and interstate commerce eligibility. Wisconsin's state dairy plant inspection program and California's Department of Food and Agriculture dairy safety rules add compliance layers for processors operating across state lines. Stakeholders must monitor how proposed federal dairy pricing reforms and state-level environmental regulations on methane emissions from large herd operations reshape cost structures and sourcing geography.
Market Dynamics
Restaurant chains are accelerating cheese-intensive menu expansion while the FDA's updated Pasteurized Milk Ordinance tightens processing compliance, creating a structural squeeze between demand pull and regulatory friction.
Growth Catalysts
- Quick-service pizza expansion:National chains are adding cheese-forward limited-time offerings, driving institutional mozzarella procurement volumes.
- USDA grading standardization:Uniform quality benchmarks enable interstate commerce fluidity for specialty aged varieties.
- Wisconsin-California processing clusters:Geographic concentration of fluid milk supply and aging infrastructure reduces inbound logistics costs for commodity block production.
Market Restraints
- Fluid milk input cost volatility:Federal milk marketing order pricing fluctuations compress margin predictability for cheddar processors.
- Herd supply concentration:Large-scale dairy operations in the Upper Midwest create sourcing vulnerability during regional climate events.
- Plant-based substitution:Oat and almond-derived alternatives capture lactose-intolerant and flexitarian consumer segments in coastal urban markets.
Strategic Opportunities
- Third-party aging facility networks:Asset-light contract models lower capital barriers for artisanal brand entry into premium segments.
- Grated and shredded format premiumization:Labor-cost savings for institutional buyers support unit economics expansion in food service channels.
- California methane regulation incentives:State environmental credit programs reward processors sourcing from verified lower-emission herd operations.
Industry Challenges
- Cross-state compliance complexity:Wisconsin's dairy plant inspection program and California's Department of Food and Agriculture rules create overlapping audit burdens for multi-facility operators.
- Specialized affineur skill scarcity:Traditional aging expertise required for premium grade certification faces generational transfer gaps.
- Legacy equipment retrofit costs:FDA Current Good Manufacturing Practices upgrades demand capital deployment for mid-tier processors with dated infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cheese Market |
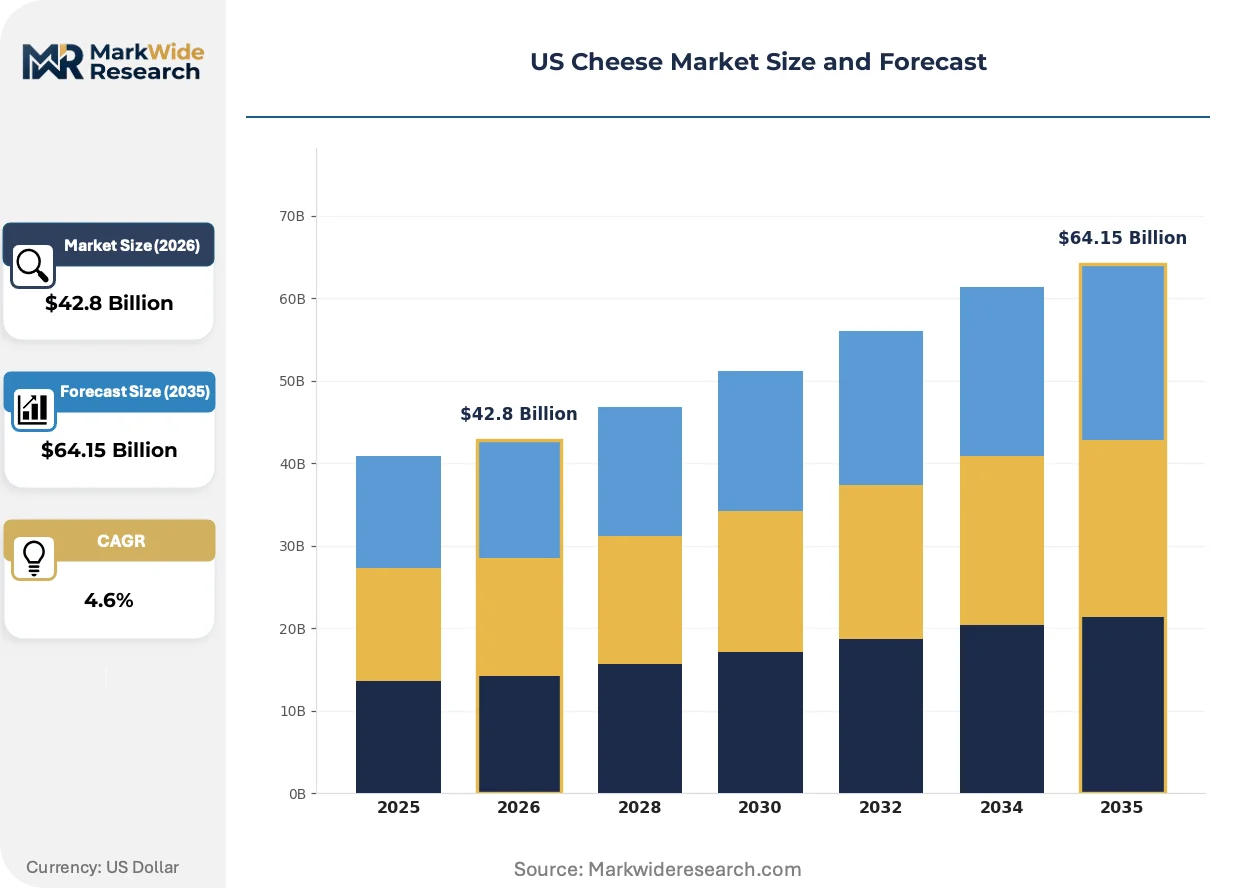
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Parmesan, Feta Packaging Type: Block, Slice, Grated, Shredded End User: Food Service, Retail, Manufacturing, Catering Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Fonterra Co-operative Group Limited, FrieslandCampina, Kraft Heinz Company, Bel Group, Lactalis Group, Saputo Inc., Arla Foods, Groupe Savencia, Dairy Farmers of America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cheese Market Strategic Shifts & Innovations
Enzymatic and fermentation technologies are converging with precision supply chain tools to reshape how cheese grades are standardized, aged, and distributed across fragmented buyer segments.
Precision fermentation-derived casein and whey proteins are hybridizing with traditional enzymatic coagulation methods in pilot-scale facilities. Specialty cheese makers in Vermont and Oregon are testing these inputs for texture replication in aged varieties. This hybridization is compressing the traditional 12-24 month aging timeline for certain flavor profiles while challenging Protected Designation of Origin frameworks.
The FDA's updated labeling standards for plant-based dairy alternatives are tightening disclosure requirements on nutritional equivalence claims. Processors must now substantiate protein quality comparisons against dairy reference standards. Natural cheese manufacturers in Wisconsin are leveraging this regulatory friction to differentiate commodity blocks in retail channels.
Food service distributors are consolidating procurement through direct-to-processor contracts, bypassing traditional dairy cooperatives for volume mozzarella commitments. Pizza chain operators are negotiating specification-grade agreements with California processors for consistent melt performance. This concentration is most visible in the Southeast, where rapid chain expansion outpaces local aging infrastructure development.
US Cheese Market Segmentation
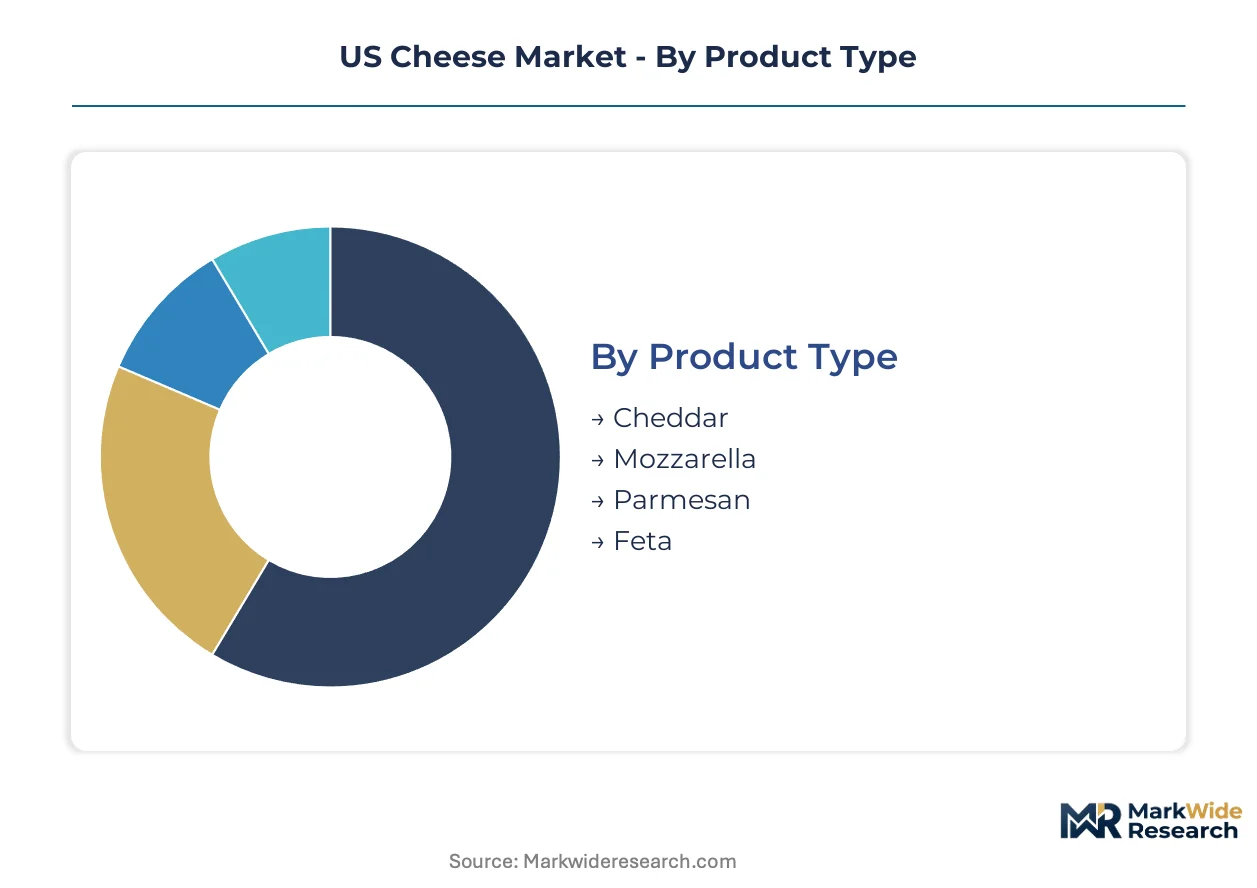
Cheese segmentation in the US market determines everything from aging infrastructure investment to cold-chain logistics configuration. Product type dictates coagulation chemistry and moisture targets, while packaging format shapes margin capture through labor-cost positioning for institutional buyers.
Product Type:
After-sales service intensity varies sharply across cheese types, with aged varieties demanding affineur monitoring and defect management that commodity fresh cheeses do not require.
- Cheddar:Firm-textured cheese with moisture content below 39% and fat-in-dry-matter minimums driving sharpness grading from mild to extra-sharp. Wisconsin and Vermont processors dominate aged production, though California fluid milk cost advantages are compressing block pricing for commodity grades used in prepared foods manufacturing.
- Mozzarella:Pasta filata variety with stretch-curd manufacturing and rapid moisture release specifications optimized for melt performance. Quick-service pizza chains in the Southeast and Texas are driving specification-grade procurement directly from California processors, bypassing traditional cooperative channels.
- Parmesan:Grana-style hard cheese requiring 10-24 month aging with granular texture and low moisture for grating applications.
- Feta:Brined fresh cheese with crumb texture and 55-60% moisture content, primarily serving Mediterranean restaurant segments and specialty retail.
Cheddar holds the largest share; momentum sits with Mozzarella.
Packaging Type:
Cost tier stratification runs deepest here, with labor-saving formats commanding 40-60% unit premiums over commodity blocks while requiring entirely different cutting and gas-flush equipment.
- Block:Standard 40-pound commodity format for food service redistribution and manufacturing input, with USDA grading stamps enabling interstate commerce fluidity. Upper Midwest dairy cooperatives anchor national supply, though inbound logistics from Wisconsin to Southeast distributors create working capital inefficiencies.
- Grated:Precision-cut particles with anti-caking agents and modified atmosphere packaging for extended shelf stability. Institutional buyers in healthcare and education sectors prioritize this format for kitchen labor reduction, supporting premium unit economics despite higher packaging costs.
- Slice:Individually wrapped or stacked configurations for sandwich preparation in quick-service and retail deli applications.
- Shredded:Ribbon-cut format with cellulose coating for pizza topping and casserole manufacturing.
Block captures the highest volume; grated and shredded are climbing the fastest.
End User:
Application requirements fragment sharply across these buyer types, with melt-performance specifications, lot-traceability demands, and payment terms varying by an order of magnitude.
- Food Service:Restaurants, pizza chains, and institutional kitchens sourcing specification-grade mozzarella and cheddar with consistent melt profiles. National pizza operators are consolidating procurement through direct California processor contracts, eroding traditional cooperative intermediation.
- Retail:Supermarket deli counters and packaged cheese aisles where branded block and shredded formats compete on shelf placement and promotional frequency.
- Manufacturing:Prepared food processors converting commodity cheese blocks into frozen entrees, sauces, and snack coatings.
- Catering:Event and contract food service with volatile volume requirements and limited cold-storage infrastructure.
Food Service holds the largest share; momentum sits with Manufacturing.
Distribution Channel:
Customer type determines service intensity, with wholesale buyers demanding technical specification support that convenience store operators do not require.
- Supermarkets:Dominant retail channel with category management negotiations, promotional slotting fees, and temperature-controlled display case requirements. Kraft Heinz and Saputo leverage branded portfolio breadth to secure end-cap positioning and multi-SKU facings.
- Wholesale:Food service distributors and redistribution centers supplying restaurants and institutions with 40-pound blocks and institutional packs. Consolidation among broadline distributors is compressing supplier margins while demanding lot-traceability documentation.
- Online:Direct-to-consumer and specialty cheese e-commerce with cold-chain shipping requirements and subscription model experimentation.
- Convenience Stores:Grab-and-go string cheese and single-serve snacks with limited refrigeration space and high turnover velocity requirements.
Supermarkets hold the largest share; online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service distributors and quick-service chains concentrate procurement in states with fluid milk surplus and aging infrastructure. Wisconsin and California anchor national supply, though Southeast demand growth outpaces local processing capacity.
Wisconsin
Dairy Farmers of America and independent cooperatives source fluid milk from 6,000-plus dairy farms for cheddar and specialty aged production. The state's dairy plant inspection program adds compliance layers for interstate shippers. Green Bay and La Crosse processing clusters supply commodity blocks to Southeast redistributors.
California
Central Valley herd operations feed mozzarella and Monterey Jack production for pizza chain contracts. The Department of Food and Agriculture dairy safety rules overlap with federal standards, creating dual audit requirements. Tulare and Merced counties concentrate fluid milk supply for direct food service procurement.
Texas
Rapid quick-service expansion in Dallas-Fort Worth and Houston drives specification-grade mozzarella demand. The state health department adopts FDA Pasteurized Milk Ordinance standards with additional temperature-logging mandates. Amarillo and Lubbock emerging as inbound redistribution hubs for Upper Midwest supply.
New York
Specialty and artisanal cheese makers in the Hudson Valley and Finger Lakes serve high-end retail and direct-to-restaurant channels. State agriculture department grading programs parallel USDA standards for intrastate commerce. Syracuse and Rochester host aging facilities for European-style varieties.
Idaho
Magic Valley dairy operations supply whey processing and commodity cheddar for manufacturing end users. State environmental quality regulations on dairy waste management shape herd expansion economics. Twin Falls anchors processing capacity for export-oriented production.
US Cheese Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered pricing bands. Consolidation among broadline distributors compresses supplier margins while demanding lot-traceability documentation. Three archetypes dominate: cooperative-scale raw milk controllers, branded retail shelf-space holders, and asset-light artisanal specialists. M&A activity targets aging infrastructure and direct-to-food-service contract portfolios.
Among cooperative-structured suppliers, Dairy Farmers of America and Fonterra Co-operative Group Limited exemplify scale-driven raw milk aggregation. Kraft Heinz Company and Saputo Inc. occupy positions as branded portfolio anchors with retail channel dominance. Within the specialty tier, Bel Group and Lactalis Group represent European-origin diversification into US premium segments.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| FrieslandCampina |
| Kraft Heinz Company |
| Bel Group |
| Lactalis Group |
| Saputo Inc. |
| Arla Foods |
| Groupe Savencia |
| Dairy Farmers of America |
| Others |
Cost & Logistics Intelligence
Federal milk marketing order pricing volatility determines both cheddar block spreads and processor location decisions across the Upper Midwest and California. This input cost uncertainty compresses margin predictability for commodity grades while amplifying premiums for aged specialty varieties with affineur-certified provenance.
Pricing Analysis
Cost-plus contracts indexed to Class III milk futures dominate mozzarella procurement for quick-service pizza chains. Three-tier pricing structure across premium, standard, and economy levels separates aged Wisconsin cheddar from commodity California blocks and private-label manufacturing inputs. Pricing pressure stems from fluid milk cost volatility under federal marketing orders. Food service distributors show highest price sensitivity; specialty affineur-certified brands command inelastic demand.
Supply Chain Analysis
Fluid milk supply concentrates in Wisconsin, California, and Idaho where dairy processing clusters anchor national production. Raw material dependencies include Class III milk, rennet and microbial enzymes, and modified atmosphere packaging films. Single-source vulnerability emerges from Upper Midwest herd concentration during regional climate events. Distribution runs through cooperative-controlled redistribution centers to broadline food service distributors and retail consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US cheese market sits in a cyclical recovery phase driven by quick-service restaurant expansion and normalized post-pandemic food service demand. Federal dairy pricing reform debates and state methane regulations add structural uncertainty to margin trajectories.
For Market Incumbents: Pre-empt cooperative disintermediation by securing direct-to-chain mozzarella contracts with Southeast pizza operators. Expand backward integration into fluid milk supply across California's Central Valley to offset federal pricing volatility. Invest in third-party aging facility networks to capture artisanal brand premiums without capital-heavy infrastructure.
For New Entrants and Emerging Players: Southeast redistribution hub underpenetration offers white-space entry for specification-grade mozzarella processors serving Texas and Florida quick-service expansion. Target direct procurement relationships with pizza chains bypassing Dairy Farmers of America cooperative channels. Launch with grated and shredded format premiumization emphasizing kitchen labor-cost savings for institutional buyers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light aging infrastructure platforms over capital-intensive fluid milk processing. Long-term viability hinges on direct food service contract portfolios and state environmental credit qualification. Acquisition targets should show verified lower-emission herd sourcing relationships. Watch California methane regulation incentive expansion as inflection signal for geographic sourcing advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Chain Contracting | Bypasses Dairy Farmers of America cooperative intermediation for pizza chain volume commitments. |
| Third-Party Aging Facility Network | Lowers capital barriers for artisanal brand entry into premium cheddar and specialty segments. |
| Backward Integration into Fluid Milk | Saputo and Kraft Heinz anchor margin control through captive Upper Midwest milk supply. |
| Grated and Shredded Format Expansion | Captures 40-60% unit premiums from healthcare and education institutional buyers. |
| California Methrogen Credit Qualification | State environmental incentives reward processors sourcing from verified lower-emission herd operations. |
Research Approach
Desk research of USDA Agricultural Marketing Service pricing data, FDA regulatory filings, and state dairy inspection records preceded structured interviews with cheese processing plant managers, food service procurement directors at broadline distributors, cooperative supply planners, and retail category buyers. Secondary validation drew from Wisconsin Department of Agriculture trade statistics, California Department of Food and Agriculture safety reports, and SEC 10-K disclosures from publicly traded dairy processors. Bottom-up volume modeling and top-down value reconciliation ensured triangulation across data sources.
Assumptions held federal milk marketing order pricing mechanisms and FDA Pasteurized Milk Ordinance compliance standards fixed across the analysis window, while varying quick-service restaurant expansion rates and plant-based substitution penetration. Segmentation modeling incorporated product type, packaging format, end-user application, and distribution channel dimensions. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections, with fluid milk supply forecasts and food service channel growth rates as primary inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cooperative-scale suppliers or rapid plant-based technology breakthroughs would shift outcomes. Cross-checking against USDA National Agricultural Statistics Service herd count data and restaurant industry same-store sales benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low-Calorie Butter Market
Dairy Products
Goat Milk Products Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Cheddar Cheese Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Dairy Protein Market
Dairy Products
Ricotta Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Japan Dairy Market
Dairy Products
Fermented Milk Products Market
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Ghee Market