
 Ethane Market | 2026-2036
Ethane Market Size, Share, and Industry Trends Forecast 2026-2036
Ethane Market Analysis
Petrochemical buyers are redrawing procurement patterns as plastics manufacturers displace naphtha with ethane feedstock. Chevron Phillips Chemical leverages its Gulf Coast pipeline network to sustain cost-advantaged supply chains. ExxonMobil Chemical anchors its Baytown complex with integrated ethane-to-polyethylene production. Saudi Aramco competes through its Jubail Industrial City operations, positioning its SABIC affiliate for Asian export markets.
Ethane is a two-carbon alkane (C₂H₆) typically recovered from natural gas processing and refinery off-gas streams, with purity grades ranging from 95% to 99% for petrochemical use; its primary purpose is steam-cracking into ethylene, the foundational monomer for polyethylene and ethylene oxide derivatives. Liquid ethane dominates volume flows through dedicated pipelines and cryogenic transport, while gaseous ethane serves regional fuel blending markets with thinner margins. Ethylene as a derived product category captures the largest value pool, though chemical intermediates applications in solvents and refrigerants are expanding fastest among downstream segments.
The US EPA enforces methane and volatile organic compound limits at ethane fractionation facilities, while OSHA mandates process safety management for high-pressure handling systems; these frameworks elevate capital costs for new crackers but reinforce incumbent advantages at permitted sites. In Europe, ECHA's REACH requirements govern ethane import registrations and chemical safety documentation. Stakeholders must monitor feedstock cost spreads between ethane and naphtha as the decisive variable for cracker economics and regional investment allocation.
Market Dynamics
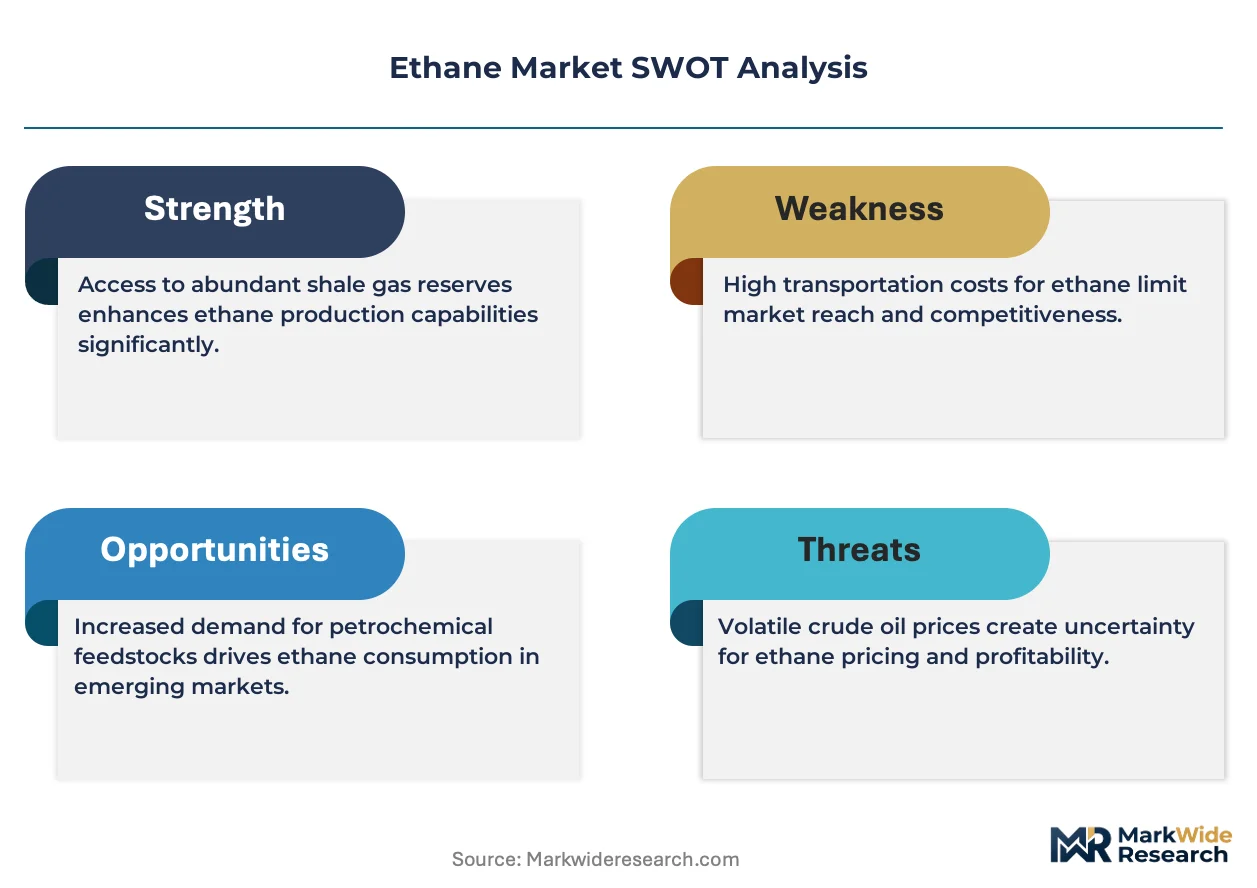
Feedstock cost spreads between ethane and naphtha now dictate cracker economics and regional investment flows, with US Gulf Coast producers capturing structural margin advantages from shale-derived supply.
Growth Catalysts
- Polyethylene demand expansion:Packaging and construction sectors in Asia-Pacific drive ethylene consumption, pulling ethane through dedicated cracking capacity expansions.
- US EPA emission standards:Clean Air Act compliance at fractionation facilities reinforces incumbent advantages at permitted Gulf Coast sites while elevating barriers for greenfield entrants.
- Shale-derived feedstock abundance:Associated gas liquids from Permian and Appalachian basins sustain cost-advantaged ethane supply chains for domestic petrochemical producers.
Market Restraints
- Feedstock price volatility:Natural gas liquid fractionation spreads fluctuate with crude oil benchmarks, compressing cracker margins when naphtha-ethane differentials narrow.
- Pipeline infrastructure concentration:Midstream capacity constraints between Appalachian production and Gulf Coast demand centers create bottleneck risks during peak withdrawal seasons.
- Propylene co-production shortfall:Ethane cracking yields minimal propylene byproduct, forcing polypropylene producers to source alternative feedstocks.
Strategic Opportunities
- European cracker feedstock switching:Rotterdam and Antwerp petrochemical complexes present conversion potential from naphtha to imported US ethane as ETS carbon costs rise.
- Chemical recycling integration:Pyrolysis-derived synthetic naphtha-ethane blends offer circular feedstock pathways for polyethylene producers seeking Scope 3 reductions.
- India's petrochemical buildout:Reliance Industries and Indian Oil Corporation are expanding cracking capacity at Jamnagar and Paradip to capture domestic polymer demand growth.
Industry Challenges
- Cryogenic handling expertise scarcity:Specialized technicians for minus-100-degree Celsius transport and storage systems command premium wages across Gulf Coast and Middle Eastern hubs.
- Fractionation train commissioning delays:Multi-year construction timelines for debottlenecking projects expose capital commitments to feedstock price cycle reversals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethane Market |
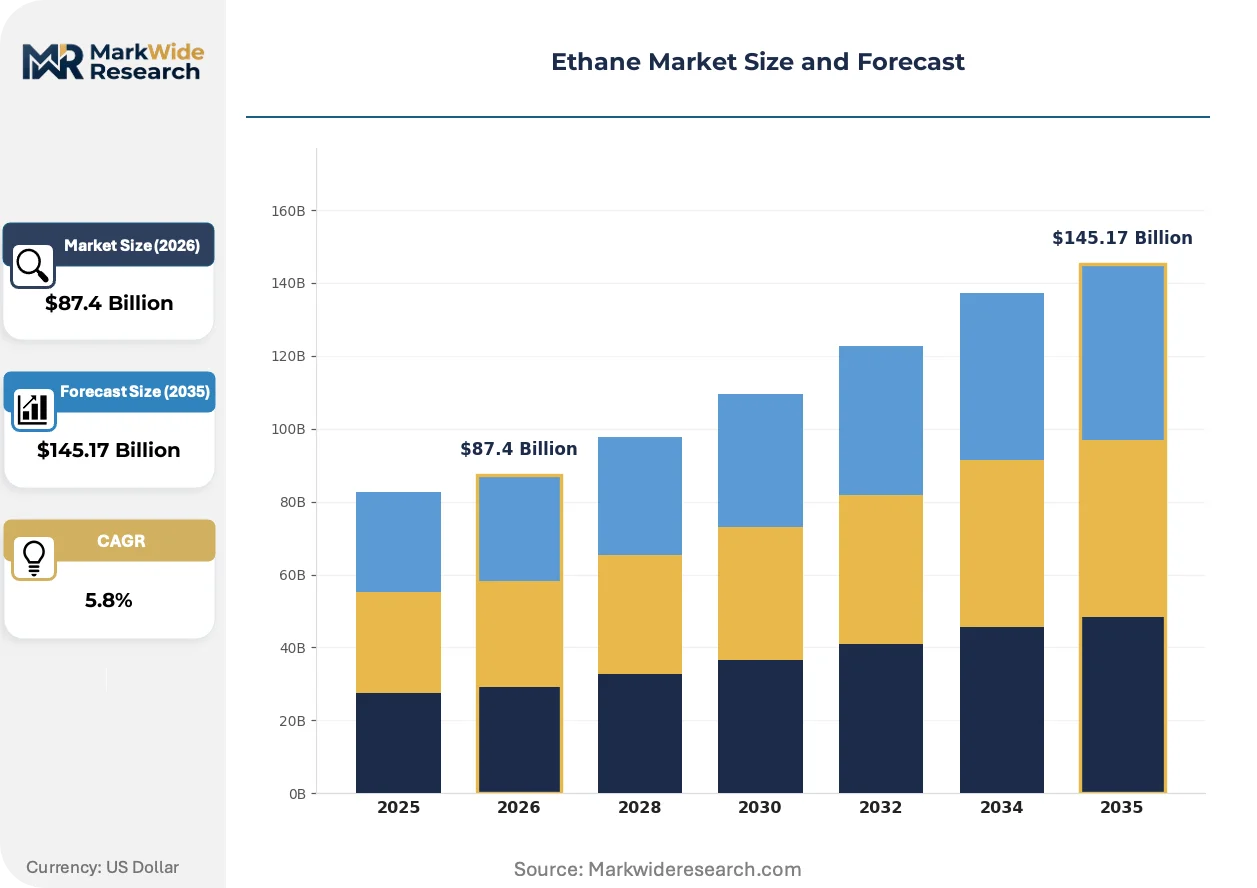
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Ethane, Gaseous Ethane, Ethanolamine, Ethylene End User: Petrochemical Industry, Fuel Industry, Plastics Manufacturing, Chemical Synthesis Application: Ethylene Production, Refrigerants, Solvents, Chemical Intermediates Distribution Channel: Direct Sales, Retail Distribution, Online Sales, Third-Party Distributors |
| Companies Covered | Chevron Phillips Chemical, Reliance Industries, ExxonMobil Chemical, Saudi Aramco, BASF SE, Royal Dutch Shell, Sinopec, INEOS, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethane Market Emerging Trajectories
Process intensification and modular cracking architectures are compressing capital requirements for ethylene production, while regulatory carbon accounting reshapes feedstock sourcing decisions across integrated petrochemical complexes.
Electric cracking furnace technology is miniaturizing thermal energy inputs for ethylene production by replacing conventional fired heaters with resistive heating elements. BASF and Sabic pilot installations in Ludwigshafen and Jubail demonstrate 90% carbon emission reductions versus steam methane reforming. This technology is miniaturizing the scale at which competitive ethylene production becomes viable, enabling stranded gas monetization in remote locations previously uneconomical for world-scale crackers.
The EU F-Gas Regulation phase-down mandates refrigerant transitions in cold chain logistics handling cryogenic ethane transport. Industrial gas carriers operating Rotterdam-to-Singapore routes now retrofit vessels with CO2 cascade systems to maintain minus-104-degree cargo temperatures. Chemical tanker operators face compliance cost pressures that advantage integrated producers with captive marine fleets over merchant shipping dependent players.
Spot market indexing now governs term contract negotiations between Appalachian producers and Gulf Coast crackers, displacing traditional oil-linked pricing mechanisms. Midstream marketers at Marcus Hook and Mont Belvieu storage hubs offer daily price discovery platforms that compress procurement cycles from quarterly to weekly intervals. This behavioral shift concentrates price risk management capabilities among sophisticated trading desks while squeezing margin buffers for smaller crackers lacking in-house commodity expertise.
Ethane Market Segmentation
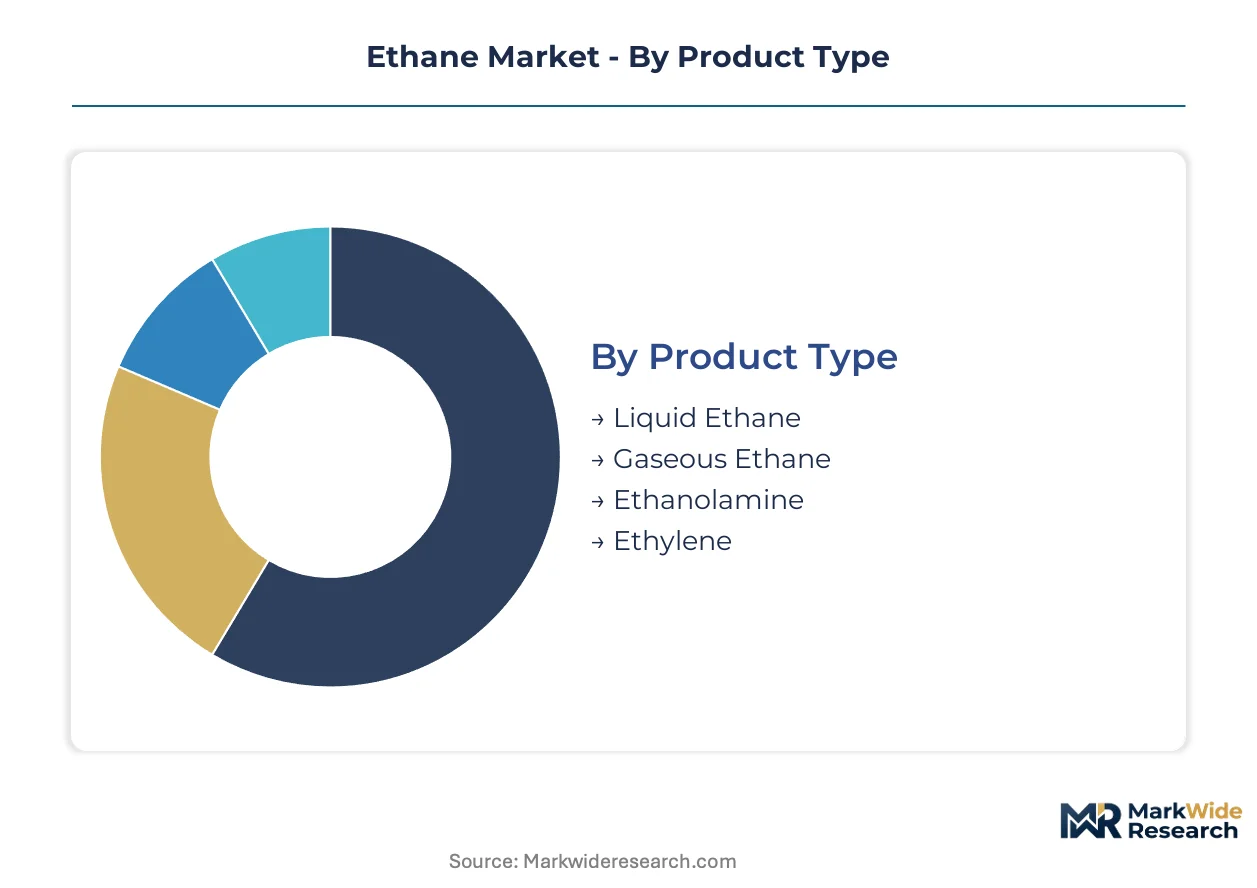
Ethane market segmentation reveals how feedstock form, end-use application, and channel structure determine margin capture and competitive vulnerability. Producers must align product specifications with cracker requirements and regional infrastructure constraints.
Product Type:
Substitution pressure from naphtha and propane alternatives weighs most heavily on lower-purity grades where specification flexibility allows feedstock switching.
- Liquid Ethane:Cryogenic liquid form at minus-89 degrees Celsius enables dense-volume transport through dedicated pipeline networks and marine vessels. Gulf Coast petrochemical complexes in Texas and Louisiana concentrate demand for this specification due to integrated storage and fractionation infrastructure.
- Gaseous Ethane:Vapor-phase product serves regional fuel blending markets and small-scale industrial heating applications with minimal processing requirements. Appalachian basin production supplies nearby power generation and industrial thermal users through local distribution networks.
- Ethanolamine:Derivative compound produced via ethylene oxide reaction finds application in gas sweetening and surfactant manufacturing.
- Ethylene:Cracked output from ethane steam cracking constitutes the dominant value-capture point in the value chain.
Liquid ethane anchors the volume base while ethylene gains share at the steepest rate as integrated producers deepen downstream integration.
End User:
Cost tier differentiation separates capital-intensive integrated crackers from price-sensitive fuel blenders.
- Petrochemical Industry:Steam cracker operators consume specification-grade ethane to produce ethylene monomer for polyethylene polymerization. US Gulf Coast facilities in Baytown and Port Arthur leverage shale-proximity for structurally advantaged feedstock costs.
- Plastics Manufacturing:Polyethylene resin producers source ethane-derived ethylene for film, packaging, and durable goods applications. Asian converters in South Korea and Thailand pull material through long-term offtake contracts indexed to regional naphtha benchmarks.
- Fuel Industry:Power generators and industrial boilers utilize ethane as clean-burning gaseous fuel with lower carbon intensity than coal or residual oil.
- Chemical Synthesis:Specialty chemical producers employ ethane as feedstock for halogenated intermediates and solvent manufacturing.
Petrochemical industry demand dominates absolute volumes while plastics manufacturing expands most quickly as packaging consumption rises in emerging economies.
Application:
Supply concentration in ethylene production creates margin pressure on peripheral applications with thinner value capture.
- Ethylene Production:Steam cracking at 800-900 degrees Celsius yields ethylene with co-product hydrogen and methane. Mont Belvieu pricing hubs in Texas and Conway in Kansas anchor North American contract negotiations for this application.
- Chemical Intermediates:Ethane chlorination and nitration routes produce solvents, refrigerants, and pharmaceutical precursors. European chemical clusters in Rotterdam and Antwerp process imported material for this higher-margin segment.
- Refrigerants:Halogenated ethane derivatives serve industrial cooling systems and cold chain logistics.
- Solvents:Degreasing and extraction applications utilize ethane-based formulations in metal finishing and electronics cleaning.
Ethylene production commands the volume base while chemical intermediates climbs the fastest as specialty applications diversify revenue streams.
Distribution Channel:
Customer type stratification separates large-volume direct procurement from fragmented retail and digital channels.
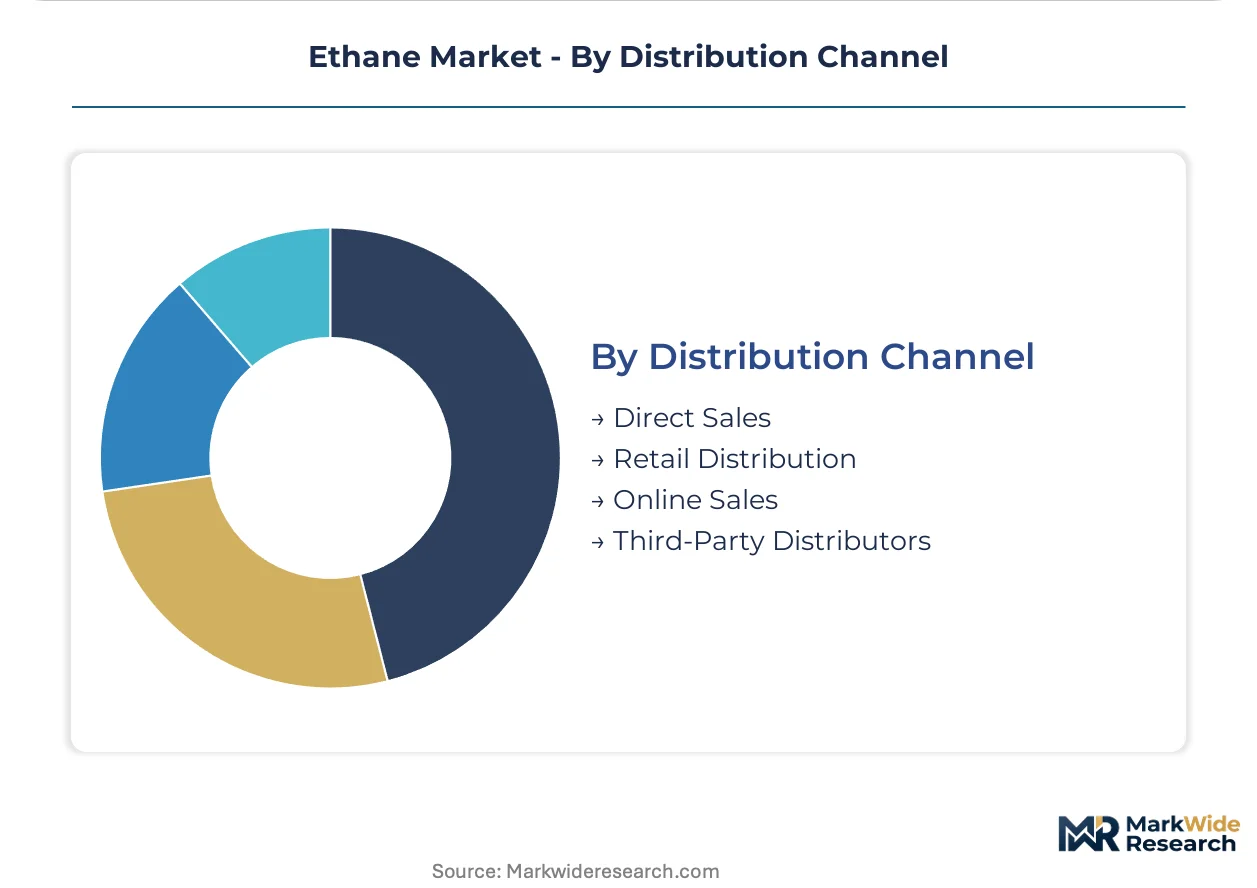
- Direct Sales:Pipeline-connected crackers negotiate long-term supply agreements with integrated midstream operators. Enterprise Products Partners and Energy Transfer execute term contracts with Chevron Phillips Chemical and ExxonMobil through dedicated infrastructure.
- Third-Party Distributors:Independent marketers aggregate smaller volumes for regional industrial users lacking pipeline access. Marcus Hook export terminal operators in Pennsylvania serve this channel for international shipments.
- Retail Distribution:Local gas suppliers deliver cylinder and small-tank quantities to commercial heating customers.
- Online Sales:Digital platforms facilitate spot market transactions and price discovery for non-contract volumes.
Direct sales anchors the volume base while third-party distributors gain share at the steepest rate as export markets expand and infrastructure access fragments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Enterprise Products Partners pipeline network linking Mont Belvieu to Appalachia underwrites United States dominance in ethane trade flows. This infrastructure backbone enables cost-advantaged feedstock delivery to Gulf Coast crackers while supporting export terminal operations at Marcus Hook.
United States
Permian and Appalachian shale basins supply abundant associated gas liquids to domestic crackers. EPA Clean Air Act enforcement at fractionation facilities elevates compliance costs for new entrants. Baytown and Port Arthur petrochemical complexes anchor integrated ethane-to-polyethylene production along the Texas Gulf Coast.
China
State-backed petrochemical expansions at Ningbo and Dalian drive ethylene capacity additions. MIIT industrial policy prioritizes feedstock diversification away from naphtha dependence. Sinopec operates integrated refining-petrochemical complexes across the Yangtze River Delta with expanding ethane import terminal capacity.
Saudi Arabia
SABIC affiliate operations at Jubail Industrial City target Asian polyethylene export markets. SFDA chemical safety frameworks govern import handling protocols for cryogenic feedstock. Ras Al-Khair industrial zone concentrates new cracker investments with access to Red Sea shipping lanes.
Germany
BASF Ludwigshafen complex pilots electric cracking furnace technology for emission reductions. ECHA REACH registration requirements structure import documentation for non-EU ethane suppliers. Antwerp-Rotterdam-Rhine chemical corridor processes imported material for specialty chemical intermediates production.
India
Reliance Industries Jamnagar refinery-petrochemical integration captures domestic polymer demand growth. Petroleum and Natural Gas Regulatory Board pipeline safety mandates govern high-pressure ethane transport systems. Paradip and Hazira industrial corridors attract greenfield cracker investments with coastal import access.
Ethane Market Vendor Landscape
Listed petrochemical majors compete with state-backed national oil companies across capital deployment intensity and feedstock integration depth. The vendor structure concentrates around integrated energy conglomerates with captive upstream supply and specialized chemical producers reliant on merchant feedstock purchases. Three archetypes dominate: Gulf Coast shale-advantaged crackers, Middle Eastern export-oriented producers, and Asian demand-anchored integrated complexes. Capacity expansion and backward integration into fractionation infrastructure constitute the primary competitive vectors reshaping participant positioning.
Among North American integrated operators, Chevron Phillips Chemical and ExxonMobil Chemical exemplify pipeline-connected Gulf Coast producers with structural feedstock cost advantages. Saudi Aramco occupies a position as the state-backed archetype leveraging Jubail Industrial City infrastructure for Asian market access. These three entities represent distinct geographic-strategic combinations: US shale proximity, Middle Eastern export orientation, and integrated refining-petrochemical scale.
| Leading Market Players |
|---|
| Chevron Phillips Chemical |
| Reliance Industries |
| ExxonMobil Chemical |
| Saudi Aramco |
| BASF SE |
| Royal Dutch Shell |
| Sinopec |
| INEOS |
| Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Ethane displacing naphtha as the dominant cracker feedstock redraws supply geography toward US shale basins while collapsing the historical oil-linked pricing premium that European and Asian crackers once commanded. This substitution dynamic concentrates pricing power with Gulf Coast pipeline-connected producers and forces merchant buyers into volatile spot-indexed procurement cycles.
Pricing Analysis
Volume-discount tiering separates pipeline-connected Gulf Coast crackers from smaller regional buyers lacking dedicated infrastructure access. Spot market indexing at Mont Belvieu and Marcus Hook compresses contract negotiation cycles from quarterly to weekly intervals, squeezing margin buffers for non-integrated processors. Price differentiation rests on purity grade and storage terminal proximity, with 95% specification material trading at structural discounts to 99% cracker-grade product. Smaller fuel-blending offtakers exhibit acute price sensitivity, while integrated polyethylene producers absorb feedstock volatility through downstream margin capture.
Supply Chain Analysis
Cryogenic inventory management demands specialized handling infrastructure with lead times stretching across multi-year fractionation train construction timelines. Supply concentrates in the United States, Saudi Arabia, and China, with Permian and Appalachian basins feeding Gulf Coast demand centers through Enterprise Products Partners pipeline networks. Raw material dependencies center on associated gas liquids from shale formations, fractionation capacity, and marine vessel availability for export routes. Single-source vulnerability runs through the Mont Belvieu pricing hub, where contract settlements for North American volumes anchor global benchmarks. Distribution runs through dedicated pipeline networks for domestic crackers and cryogenic marine vessels for Asian and European import terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethane market is entering a cyclical recovery phase as polyethylene demand rebounds from inventory destocking and US Gulf Coast feedstock costs reset lower against naphtha alternatives.
For Market Incumbents: Secure backward integration into Appalachian fractionation infrastructure to defend against midstream bottlenecks during peak withdrawal seasons. Lock in long-term offtake agreements with NGL producers before spot market indexing erodes term contract premiums. Prioritize cryogenic handling certification investments to sustain operational continuity as OSHA process safety enforcement intensifies at Gulf Coast facilities. For New Entrants and Emerging Players: Lead with modular cracking architectures targeting stranded gas monetization in remote locations previously uneconomical for world-scale facilities. India's Jamnagar and Paradip corridors present the most penetrable geography, with Reliance Industries and Indian Oil Corporation expanding capacity ahead of domestic polymer demand growth. Position around electric cracking furnace technology to differentiate on Scope 3 emission reductions for European polyethylene buyers facing ETS carbon cost escalation. For Investors and Strategic Acquirers: EPA methane emission standard tightening reshapes the acquisition landscape by elevating compliance costs for greenfield entrants and reinforcing incumbent advantages at permitted Gulf Coast sites. Target midstream operators with captive storage and pipeline networks linking production basins to demand centers. Watch for ethane-naphtha spread compression as the inflection indicator signaling cracker margin pressure and potential capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fractionation | Enterprise Products Partners pipeline control secures feedstock access against Appalachian supply bottlenecks. |
| Electric Cracking Furnace Deployment | BASF Ludwigshafen pilots demonstrate 90% emission reductions for European regulatory compliance positioning. |
| Long-term Supply Agreement | Chevron Phillips Chemical term contracts at Mont Belvieu lock in cost advantages against spot market volatility. |
| Export Terminal Capacity Expansion | Marcus Hook marine loading infrastructure captures Asian polyethylene demand growth through cryogenic vessel charters. |
| Joint Venture in Import-dependent Markets | Sinopec Ningbo partnerships secure US ethane supply chains for Chinese cracker feedstock diversification. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with petrochemical procurement leads, plant managers at Gulf Coast crackers, midstream infrastructure operators, and marine logistics coordinators contributing operational data. Secondary validation drew from EIA hydrocarbon statistics, FERC pipeline filings, SEC 10-K disclosures from integrated petrochemical majors, and customs trade records for cryogenic ethane shipments. Bottom-up capacity utilization data triangulated against top-down ethylene production estimates to anchor volume forecasts.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning purity grade tier, end-use industry concentration, distribution channel structure, and regional production hub configuration. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity buildout schedules. Forecast inputs incorporated ethane-naphtha spread differentials, polyethylene resin price trajectories, and shale gas liquids production forecasts from Permian and Appalachian basins.
The analysis sits within stated boundaries; outcomes outside sustained shale production growth, stable marine transport rates, or continued polyethylene demand expansion would require recalibration. Forecasts reflect documented assumptions around cracker commissioning timelines and fractionation capacity additions. Commodity price volatility, regulatory emission standard shifts, and alternative feedstock cost movements represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Methyl Formate Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Dibutyl Ether Market
Solvents
Chloroacetonitrile Market
Solvents
Aromatic Solvents Market
Solvents
Sugar Dissolvers Market
Solvents
Methyl Acetate Market
Solvents
Xylene Market
Solvents
Saudi Arabia Methanol Market
Solvents
Organic Solvents Market
Solvents
Global Solvent Dyes Market
Solvents
Global Solvents Market
Solvents
Phenol Derivatives Market
Solvents
Oxygenated Solvents Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Nitroglycerin Market