
 Fluid Neutralizing Market | 2026-2036
Fluid Neutralizing Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Neutralizing Market Analytics
Oil & Gas is rebalancing toward environmental services as the dominant end-use vertical for fluid neutralizing systems. Halliburton leverages its drilling chemicals heritage to anchor supply relationships across North American shale basins. Schlumberger Limited competes through integrated wellbore chemistry portfolios that bundle neutralizers with completion fluids. BASF SE differentiates via specialty chemical R&D intensity in pH control technologies.
Fluid neutralizing encompasses chemical agents and systems designed to adjust pH levels of industrial liquids, typically operating across a functional range of pH 4–10 using mineral bases, organic buffers, or synthetic alkalis to achieve regulatory discharge compliance or process stability. Acid neutralizers dominate volume demand in wastewater treatment applications where sulfuric and hydrochloric acid residues require systematic correction. pH adjusters represent the fastest-expanding product category as pharmaceutical manufacturing and precision chemical synthesis impose tighter process control tolerances. Buffer solutions command premium positioning in bioprocessing and analytical laboratory end uses where stability within ±0.1 pH units determines batch validity.
EPA effluent limitation guidelines under the Clean Water Act mandate neutralization prior to industrial discharge, directly conditioning product specifications and treatment system design across US manufacturing facilities. REACH registration requirements and ECHA substance evaluation protocols in Europe restrict certain alkaline compounds, forcing reformulation toward biodegradable alternatives. China's MEE wastewater discharge standards for heavy industrial zones impose comparable neutralization obligations. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance cost asymmetries that distort competitive positioning.
Market Dynamics
EPA effluent limitation guidelines under the Clean Water Act are compressing discharge timelines for US industrial facilities, forcing accelerated capital deployment into automated neutralization systems that can achieve real-time pH compliance before wastewater reaches municipal treatment networks.
Growth Catalysts
- Tightening Effluent Standards:China's MEE wastewater discharge standards for heavy industrial zones mandate neutralization prior to release, compelling steel and chemical plants to upgrade aging batch-treatment infrastructure.
- Shale Basin Expansion:Produced water volumes from Permian and Bakken formations require systematic pH correction before deep-well injection or surface discharge, sustaining demand for mobile neutralization units.
- Bioprocessing Scale-Up:Cell culture media preparation in pharmaceutical manufacturing demands buffer solutions with ±0.1 pH stability, driving premium-grade product consumption.
Market Restraints
- Raw Material Concentration:Caustic soda supply concentrates in Gulf Coast chlor-alkali complexes, exposing neutralizer formulators to hurricane-related production disruptions and price volatility.
- REACH Substitution Pressures:ECHA substance evaluation protocols restrict certain alkaline compounds, forcing European manufacturers toward biodegradable alternatives with higher unit costs and shorter shelf lives.
- Legacy Infrastructure Lock-In:US municipal wastewater utilities operate neutralization systems with 20-30 year asset lives, slowing replacement cycles despite efficiency gaps with modern membrane-integrated designs.
Strategic Opportunities
- Modular System Deployment:Containerized neutralization skids enable rapid installation at remote mining and oilfield sites, bypassing permanent infrastructure constraints in Peru and Chilean copper belts.
- Carbon Capture Integration:Alkaline neutralizing agents can double as CO2 capture media in cement and power plant flue gas treatment, opening dual-revenue product positioning.
- Precision Agriculture Runoff:Buffer solutions for hydroponic nutrient management represent an underpenetrated channel as controlled-environment farming expands in the Netherlands and Spain.
Industry Challenges
- Specialized Technician Scarcity:Automated neutralization systems require operators trained in both chemical handling and PLC programming, a skill combination concentrated in Gulf Coast and Rhine-Ruhr industrial corridors.
- Multi-Jurisdiction Certification Burden:Products sold across US, EU, and Chinese markets must satisfy divergent EPA, REACH, and GB standard testing protocols, extending commercialization timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Neutralizing Market |
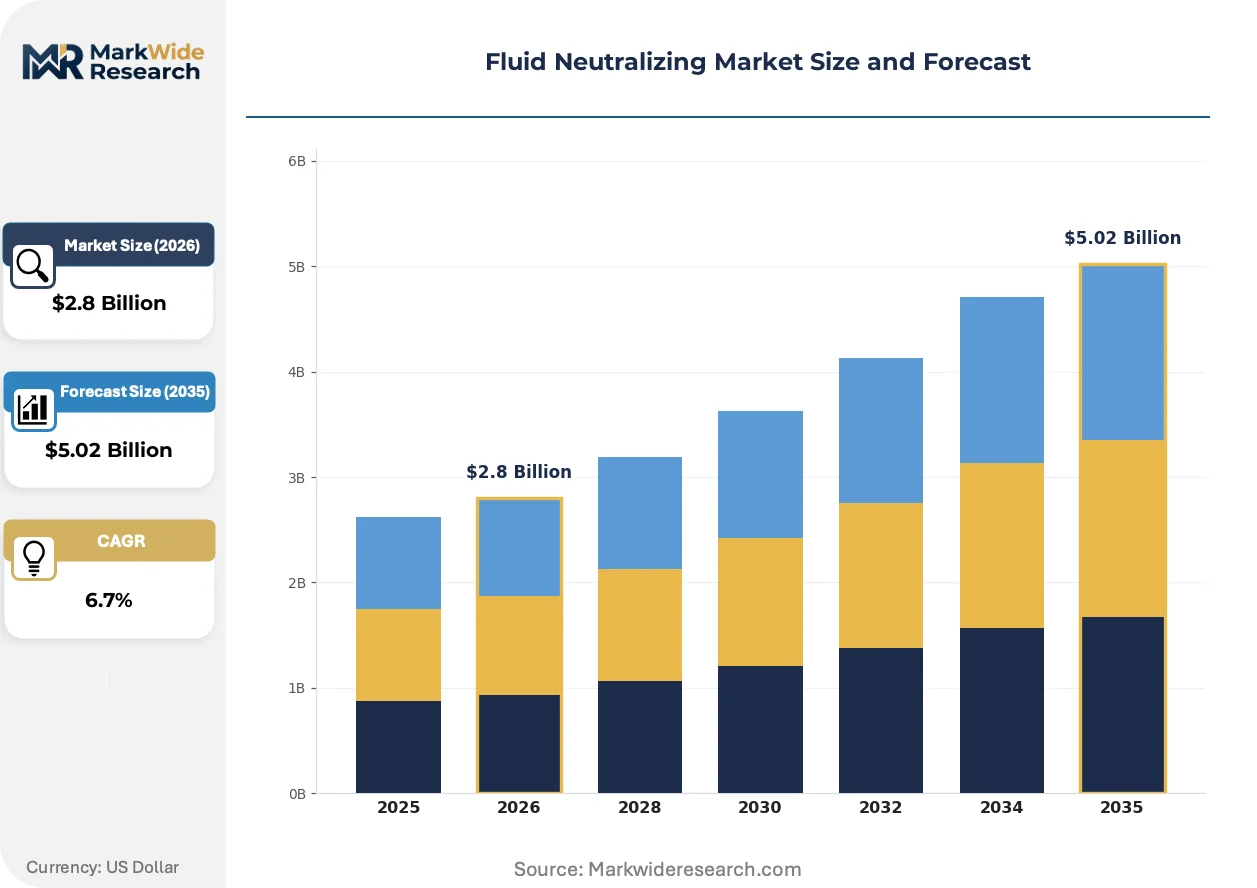
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid Neutralizers, Base Neutralizers, Buffer Solutions, pH Adjusters Application: Wastewater Treatment, Soil Stabilization, Industrial Processes, Chemical Manufacturing End User: Environmental Services, Agriculture, Pharmaceuticals, Oil & Gas Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Halliburton, Schlumberger Limited, BASF SE, Clariant, Solvay, Newpark Resources Inc., Nouryon, Global Drilling Fluids and Chemicals Limited, Kemira OYJ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Neutralizing Market Evolving Landscape
Real-time sensor integration and predictive control algorithms are transforming fluid neutralizing from batch-based compliance into continuous process optimization, compressing response times from hours to minutes.
Membrane electrolysis for on-site alkali generation is electrifying pH adjustment economics by eliminating bulk chemical transport and storage liabilities. Food and beverage processors in California and Germany are piloting these systems to reduce supply chain exposure. The technology is compressing operating margins for traditional caustic soda distributors while enabling facility-level chemical independence.
REACH registration requirements and ECHA substance evaluation protocols are forcing systematic reformulation of alkaline neutralizers toward biodegradable alternatives. European formulators are substituting mineral bases with organic buffer systems derived from agricultural waste streams. Pharmaceutical and cosmetics manufacturers face the steepest compliance costs, driving consolidation among specialty chemical suppliers with dedicated regulatory affairs capabilities.
Specification-driven procurement now dominates large industrial accounts, with engineering firms embedding neutralization performance guarantees into turnkey wastewater treatment contracts. Equipment vendors are absorbing chemical supply obligations previously held by separate distributors. This consolidation is most visible in German automotive manufacturing clusters, where integrated service contracts now cover both capital equipment and decade-long chemical provisioning.
Fluid Neutralizing Market Segmentation
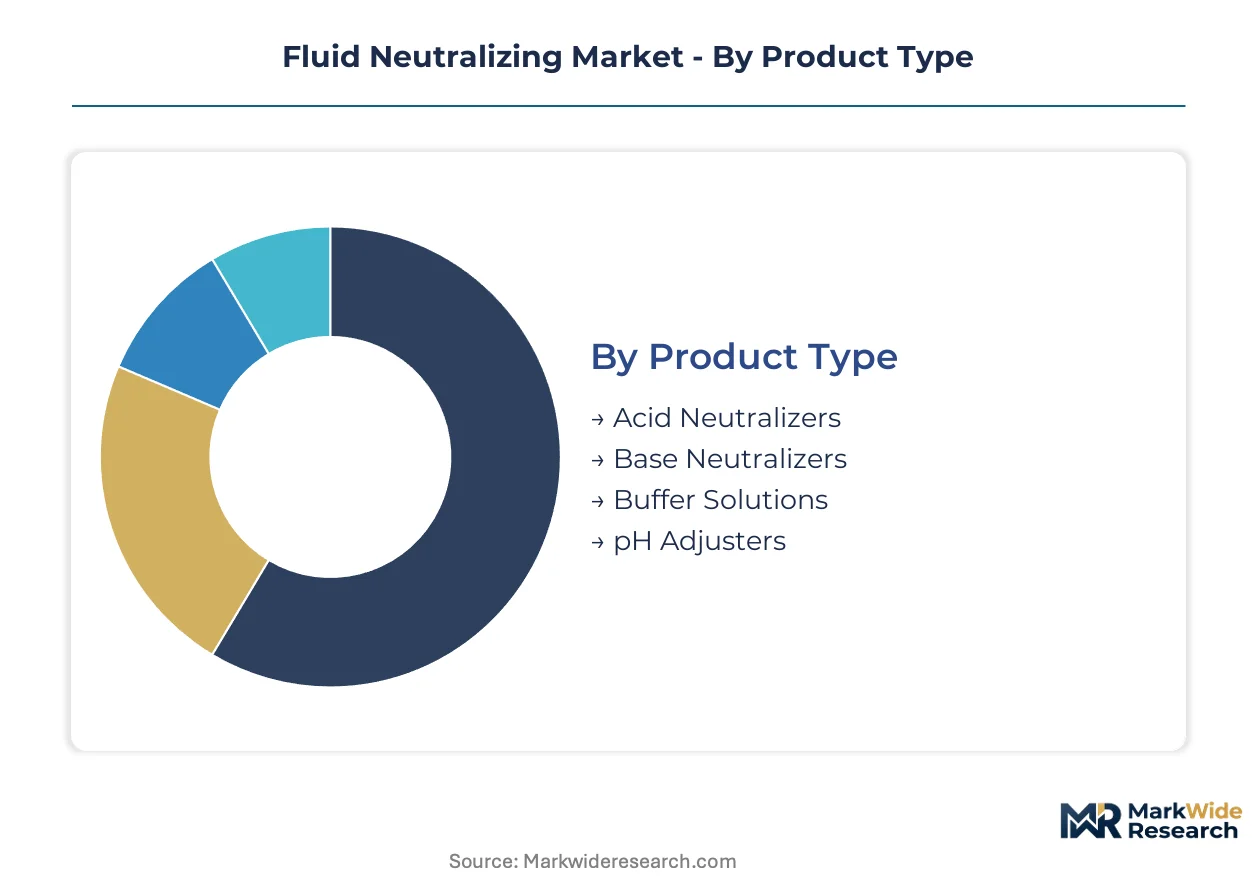
Product architecture in fluid neutralizing spans standalone chemical agents and integrated system-in-package designs. Procurement patterns diverge sharply between facilities buying bulk commodity neutralizers and those specifying precision buffer systems for validated processes.
Product Type:
Standalone acid and base neutralizers dominate bulk procurement for wastewater compliance, while buffer solutions and precision pH adjusters embed into validated manufacturing workflows requiring documented stability.
- Acid Neutralizers:Mineral bases including calcium carbonate and magnesium hydroxide neutralize sulfuric and hydrochloric acid residues from metal finishing and chemical synthesis. Steel mills in Germany's Ruhr region deploy automated lime slurry systems to meet ECHA discharge protocols. Demand concentrates where EPA effluent guidelines mandate real-time pH correction before municipal sewer release.
- Buffer Solutions:Organic and inorganic buffer systems maintain ±0.1 pH stability across bioprocessing and analytical applications. Pharmaceutical manufacturers in Switzerland and Massachusetts specify these for cell culture media preparation where batch validity depends on precise ionic equilibrium. Premium positioning reflects qualification documentation and supply chain traceability requirements.
- Base Neutralizers:Sulfuric acid and carbon dioxide-based systems correct alkaline wastewater from textile dyeing and pulp processing.
- pH Adjusters:Concentrated mineral acids and alkalis enable rapid pH correction in continuous-flow industrial processes.
Acid neutralizers lead volumes today; buffer solutions are gaining share fastest.
Application:
Cost tier stratification separates high-volume wastewater treatment from precision chemical manufacturing applications demanding validated process control.
- Wastewater Treatment:Municipal and industrial facilities neutralize acidic or alkaline effluent prior to discharge. China's MEE standards for heavy industrial zones compel steel and petrochemical plants to upgrade batch-treatment infrastructure. Membrane-integrated neutralization systems command 3-4x capital cost premiums over conventional designs.
- Chemical Manufacturing:Precision pH control determines yield and impurity profiles in pharmaceutical and specialty chemical synthesis. FDA process validation requirements drive specification-driven procurement with documented performance guarantees. Contract manufacturers in Ireland and Singapore absorb chemical supply obligations previously held by separate distributors.
- Soil Stabilization:Lime and cement-based neutralizers treat acidic soils for construction and agricultural remediation.
- Industrial Processes:Metal finishing, electronics fabrication, and food processing require intermittent pH correction for bath maintenance.
Wastewater treatment commands the largest installed base; chemical manufacturing shows the steepest expansion trajectory.
End User:
Customer type determines procurement modality, with environmental services firms specifying integrated service contracts and pharmaceutical manufacturers enforcing supplier qualification protocols.
- Environmental Services:Specialty contractors design, build, and operate neutralization systems under long-term service agreements. Engineering firms in Texas and Alberta embed performance guarantees into turnkey wastewater contracts, absorbing decade-long chemical provisioning obligations. Consolidation is compressing margins for standalone chemical distributors.
- Oil & Gas:Produced water from Permian and Bakken shale formations requires systematic pH correction before deep-well injection or surface discharge. Mobile neutralization units serve remote drilling sites where permanent infrastructure is uneconomic. Halliburton and Schlumberger leverage drilling chemicals heritage to anchor supply relationships.
- Agriculture:Controlled-environment farming in the Netherlands and Spain drives demand for hydroponic nutrient buffer solutions.
- Pharmaceuticals:Cell culture and fermentation processes demand validated buffer systems with documented stability.
Environmental services leads contract value; oil and gas is expanding most quickly.
Distribution Channel:
Supply concentration shapes channel strategy, with caustic soda distributors defending position through logistics integration and specialty formulators building direct technical sales capabilities.
- Direct Sales:Specialty chemical suppliers maintain technical field teams for pharmaceutical and bioprocessing accounts requiring application support. BASF SE and regional European formulators invest in regulatory affairs capabilities to navigate REACH substitution pressures. Direct relationships enable specification lock-in through validated supply agreements.
- Distributors:Regional chemical distributors serve mid-sized industrial accounts with commodity neutralizers and standard buffer formulations. Gulf Coast chlor-alkali complexes supply caustic soda through established distribution networks exposed to hurricane-related disruption risks.
- Wholesale:Bulk procurement aggregators serve municipal utilities with standardized product specifications.
- Online Retail:Laboratory-scale buffer solutions and analytical reagents move through specialized scientific supply platforms.
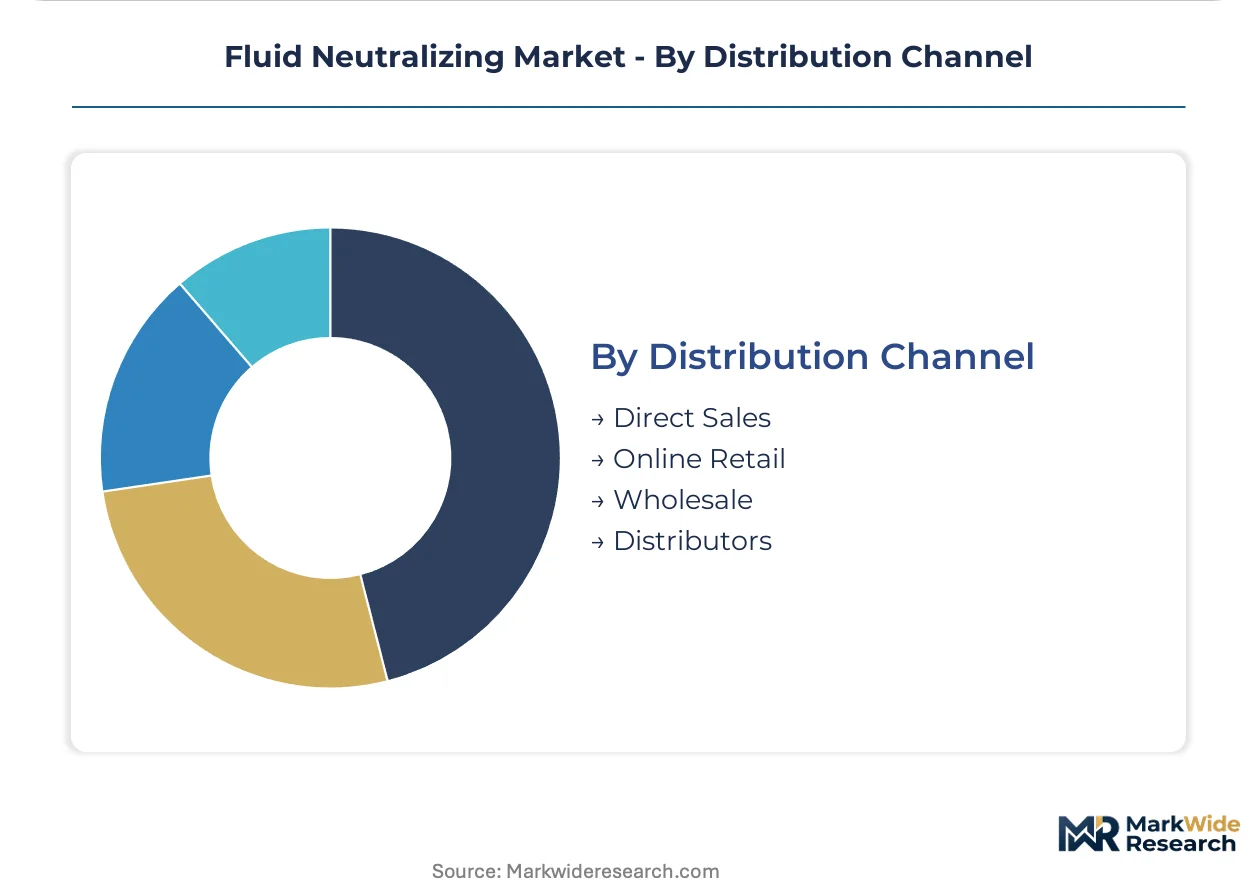
Direct sales captures the highest margin segment; distributor relationships still move the largest tonnage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors fluid neutralizing demand through German steel and chemical clusters upgrading legacy wastewater infrastructure under tightening ECHA discharge protocols.
United States
Permian Basin shale operators deploy mobile neutralization units for produced water management before deep-well injection. EPA effluent limitation guidelines under the Clean Water Act mandate real-time pH correction at Texas and Louisiana refineries. Gulf Coast chlor-alkali complexes supply caustic soda to formulators serving the Houston Ship Channel petrochemical corridor.
Germany
Automotive manufacturing clusters in Bavaria and Baden-Württemberg specify integrated service contracts covering both neutralization equipment and decade-long chemical provisioning. REACH registration requirements force systematic reformulation toward biodegradable alkaline alternatives. Engineering firms in North Rhine-Westphalia embed performance guarantees into turnkey wastewater treatment contracts for Ruhr steel mills.
China
MEE wastewater discharge standards for heavy industrial zones compel Yangtze River Delta steel and petrochemical plants to upgrade batch-treatment infrastructure. Dual carbon goals accelerate adoption of membrane-integrated neutralization designs with 3-4x capital premiums over conventional systems. Sichuan-Chongqing chemical synthesis hubs drive precision pH adjuster consumption for pharmaceutical intermediates.
Switzerland
Pharmaceutical manufacturers in Basel specify validated buffer systems with documented stability for cell culture media preparation. Swissmedic quality requirements and EMA alignment impose qualification documentation burdens that lock in premium-grade suppliers. Precision chemical synthesis clusters around Lake Geneva absorb chemical supply obligations previously held by separate distributors.
India
CDSCO-regulated contract manufacturers in Maharashtra and Gujarat enforce supplier qualification protocols for pharmaceutical buffer procurement. Central Pollution Control Board mandates for effluent treatment plant upgrades drive municipal and industrial neutralization system deployment. Andhra Pradesh bulk drug parks attract integrated service providers bundling equipment and chemical provisioning.
Fluid Neutralizing Market Competitive Landscape
Integrated service contracting dominates the current landscape as engineering firms absorb chemical supply obligations previously held by separate distributors. The vendor base stratifies between multinational chemical conglomerates with regulatory affairs capabilities and regional formulators serving commodity wastewater applications. Three archetypes prevail: drilling-fluids heritage players leveraging oilfield relationships, specialty chemical R&D houses differentiating through pH control innovation, and environmental services contractors bundling equipment with long-term chemical provisioning. Geographic expansion and strategic partnerships represent the dominant competitive vectors as players seek to bypass multi-jurisdiction certification burdens.
Within the oilfield-services tier, Halliburton and Schlumberger Limited exemplify drilling-chemicals heritage players anchoring supply relationships across North American shale basins through integrated wellbore chemistry portfolios. BASF SE occupies a position among specialty chemical R&D houses, representing the archetype of formulators investing in regulatory affairs capabilities to navigate REACH substitution pressures and specification-driven procurement from pharmaceutical manufacturers. These three companies illustrate how competitive positioning increasingly depends on validated supply agreements rather than standalone product differentiation.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger Limited |
| BASF SE |
| Clariant |
| Solvay |
| Newpark Resources Inc. |
| Nouryon |
| Global Drilling Fluids and Chemicals Limited |
| Kemira OYJ |
| Others |
Value Network & Pricing Analysis
Backward integration into caustic soda production anchors both supply security and pricing power for Gulf Coast formulators serving the Houston Ship Channel petrochemical corridor. This captive supply structure insulates integrated players from hurricane-related production disruptions while compressing margins for distributors dependent on spot market procurement.
Pricing Analysis
Caustic soda feedstock volatility passes through directly to neutralizer pricing, with Gulf Coast chlor-alkali complex outages triggering immediate surcharges across commodity acid neutralizer tiers. Three-tier pricing structure across premium, standard, and economy levels separates validated buffer systems for pharmaceutical manufacturing from bulk lime slurry for steel mill wastewater compliance. Cost compression in standard-grade mineral bases is intensifying because REACH-mandated reformulation toward biodegradable alternatives raises unit production costs. Municipal wastewater utilities exhibit highest price sensitivity due to fixed-rate service contracts, while pharmaceutical manufacturers absorb premium pricing for documented stability guarantees.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for specialty buffer solutions requiring temperature-controlled logistics. Manufacturing concentrates in the United States, Germany, and China, with caustic soda feedstock drawn from Gulf Coast chlor-alkali complexes and mineral bases sourced from Midwestern limestone quarries and Ruhr industrial corridor processing facilities. Single-source vulnerability concentrates in caustic soda supply from hurricane-exposed Gulf Coast production sites. Distribution runs through integrated service contractors bundling chemical provisioning with equipment deployment, displacing standalone distributor relationships in German automotive and Texas oilfield accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
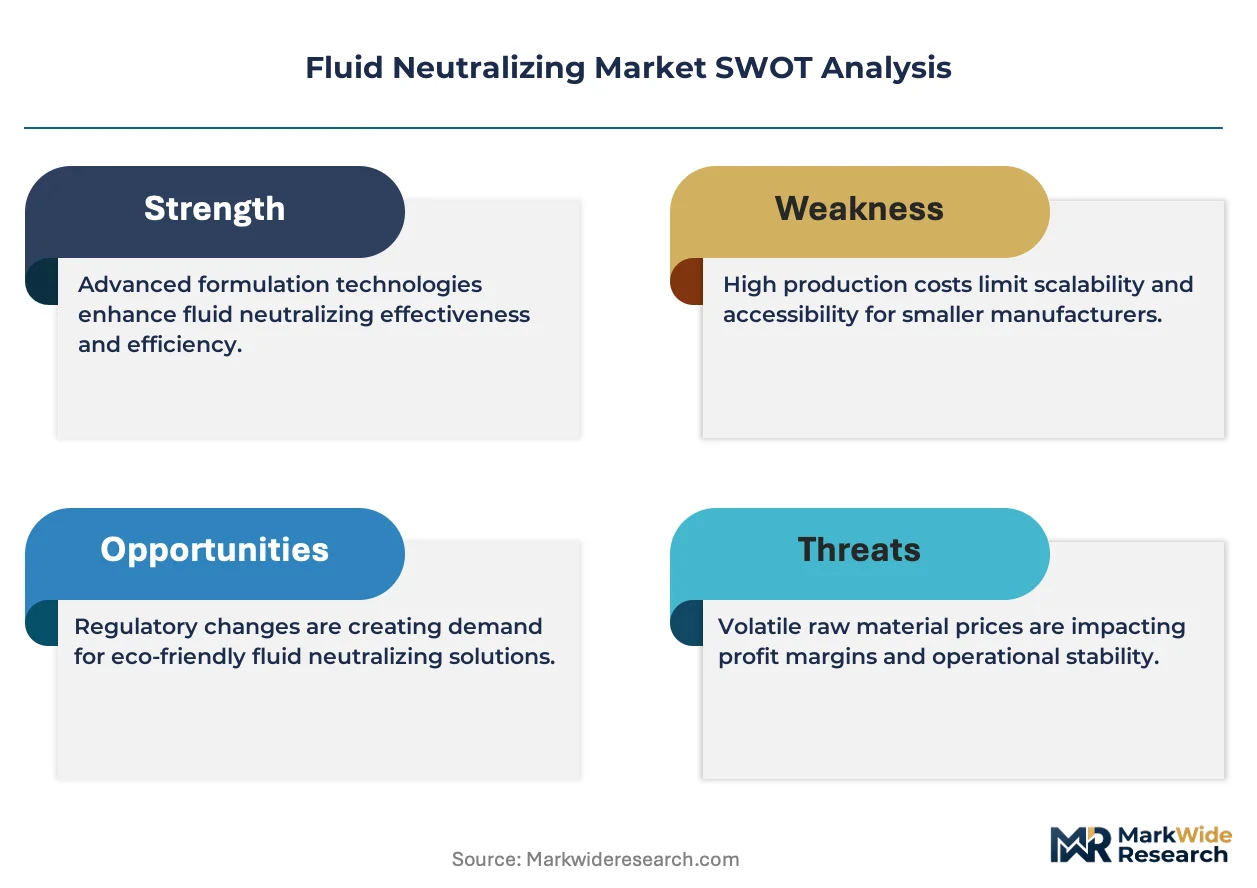
REACH substitution pressures in Europe versus EPA discharge timeline compression in the United States create a geographic-arbitrage window for formulators with dual-jurisdiction regulatory capabilities. Divergent compliance cost structures favor players who can manufacture biodegradable alternatives for ECHA markets while maintaining mineral base production for US industrial accounts.
For Market Incumbents: Extend validated supply agreements with pharmaceutical manufacturers to decade-long chemical provisioning contracts that lock out specialty chemical competitors. Deepen captive caustic soda supply through offtake arrangements with Gulf Coast chlor-alkali producers before hurricane season disruption risks materialize. Absorb mobile neutralization unit operators in Permian and Bakken shale basins to defend against oilfield-services competitors leveraging drilling chemicals heritage. For New Entrants and Emerging Players: Begin with precision agriculture buffer solutions for hydroponic nutrient management in Dutch and Spanish controlled-environment farming clusters, the most penetrable white-space channel lacking established chemical supplier relationships. Target containerized neutralization skid deployment for remote Chilean and Peruvian copper belt mining sites where permanent infrastructure constraints exclude integrated service incumbents. Pursue direct technical sales capabilities rather than distributor relationships to capture specification-driven procurement from mid-sized pharmaceutical contract manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with dedicated regulatory affairs capabilities because REACH registration requirements and ECHA substance evaluation protocols create compliance barriers that favor consolidated specialty chemical houses over fragmented commodity producers. Five-to-ten year viability hinges on biodegradable alternative formulation expertise displacing mineral base incumbents. Target acquisition archetype: European formulators with validated supply agreements in Swiss and German pharmaceutical manufacturing clusters. Watch for inflection where membrane electrolysis on-site alkali generation achieves cost parity with bulk chemical transport in California and German food processing pilot installations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caustic Soda Supply | Gulf Coast captive production insulates Halliburton and Schlumberger from hurricane-related feedstock disruption risks. |
| Biodegradable Alternative Formulation | BASF SE's REACH-compliant organic buffer systems command premium positioning in ECHA-regulated European pharmaceutical accounts. |
| Containerized Neutralization Skid Deployment | Mobile units bypass permanent infrastructure constraints in Chilean copper belt mining operations lacking municipal sewer access. |
| Integrated Service Contract Expansion | Texas engineering firms embedding performance guarantees absorb decade-long chemical provisioning obligations from standalone distributors. |
| Membrane Electrolysis Pilot Scaling | On-site alkali generation in California food processing reduces supply chain exposure to caustic soda price volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at wastewater treatment facilities, procurement leads at downstream oilfield operators, distribution channel partners in industrial chemical networks, and technical R&D directors at specialty formulators with secondary validation through EPA effluent limitation guideline filings, ECHA substance evaluation protocols, MEE wastewater discharge standard documentation, and customs trade data on caustic soda and mineral base imports. Bottom-up facility-level capacity assessments and top-down regional demand aggregation provided triangulation.
Segment-weighting approaches distributed total market value across acid neutralizers, buffer solutions, base neutralizers, and pH adjusters by product type; wastewater treatment, chemical manufacturing, soil stabilization, and industrial processes by application; and environmental services, oil and gas, agriculture, and pharmaceuticals by end user. CAGRs derived from regression analysis against industrial production indices, regulatory implementation timelines, and capital expenditure patterns across the projection horizon. Forecast inputs included shale basin produced water volume projections and pharmaceutical manufacturing capacity expansion schedules.
Caveats apply where REACH substitution acceleration, hurricane-related Gulf Coast production disruptions, or membrane electrolysis cost breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions on regulatory implementation pacing and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Hydrogen Cyanamide Market
Solvents
Chloroacetonitrile Market
Solvents
Isopropylamine Market
Solvents
Dibutyl Ether Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
Solvent Green 7 Market
Solvents
Global Glycidol Market
Solvents
Butyl Glycol Market
Solvents
Reactive Diluents Market
Solvents
Global Chloroform Market
Solvents
Benzylamine Market
Solvents
Piperylene Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Organic Solvents Market
Solvents
Ketone-Based Solvents Market