
 Isoamylene Market | 2026-2036
Isoamylene Market Size, Share, and Industry Trends Forecast 2026-2036
Isoamylene Market Outlook
Buyer concentration in the pharmaceutical and specialty chemical sectors is pivoting toward a smaller pool of qualified suppliers capable of meeting escalating purity thresholds. ExxonMobil Chemical Company leverages its integrated C5 stream infrastructure to secure feedstock cost advantages across multiple geographies. Evonik Industries AG differentiates through R&D intensity in high-purity isoamylene derivatives for polymer applications. BASF anchors European supply with backward integration into steam cracker operations and captive hydrogenation capacity.
Isoamylene is a branched C5 olefin, specifically 2-methyl-2-butene and 2-methyl-1-butene, typically produced via C5 fraction separation from steam cracking or fluid catalytic cracking operations, with commercial grades ranging from 65% to 99% purity depending on end-use requirements. Its primary industrial purpose centers on serving as a chemical intermediate for antioxidants, flavor and fragrance precursors, and specialty polymer modifiers where controlled reactivity matters. Pure Isoamylene commands premium positioning in pharmaceutical and electronics-grade applications where residual diene content must stay below 50 ppm. Chemical Intermediates represents the deepest margin pool, though Fuel Additives retains volume leadership through refinery integration. Polymer Production is gaining traction as metallocene catalyst systems expand compatibility with highly branched comonomers.
EPA fuel additive regulations and REACH substance restrictions in Europe are tightening allowable impurity profiles, forcing reformulation of legacy isoamylene-derived products and accelerating qualification timelines for new suppliers. China's SAMR national standards for chemical intermediates and Japan's METI chemical management framework add compliance layers for cross-border trade. Stakeholders must monitor regulatory divergence between jurisdictions, as diverging purity specifications threaten to fragment product grades and complicate inventory management across regional supply networks.
Market Dynamics
Specialty chemical manufacturers are consolidating procurement around qualified suppliers capable of meeting escalating purity thresholds for pharmaceutical and electronics-grade applications, reshaping competitive positioning through qualification barriers rather than price alone.
Growth Catalysts
- REACH substance restrictions:Tightening allowable impurity profiles in Europe is accelerating supplier qualification timelines and creating preference for established high-purity producers.
- Metallocene catalyst systems:Expanding compatibility with highly branched comonomers is expanding addressable demand in advanced polymer modification applications.
- Shandong chemical parks:Integrated aromatics capacity and downstream derivative projects are drawing volume toward captive consumption within China's domestic supply chain.
Market Restraints
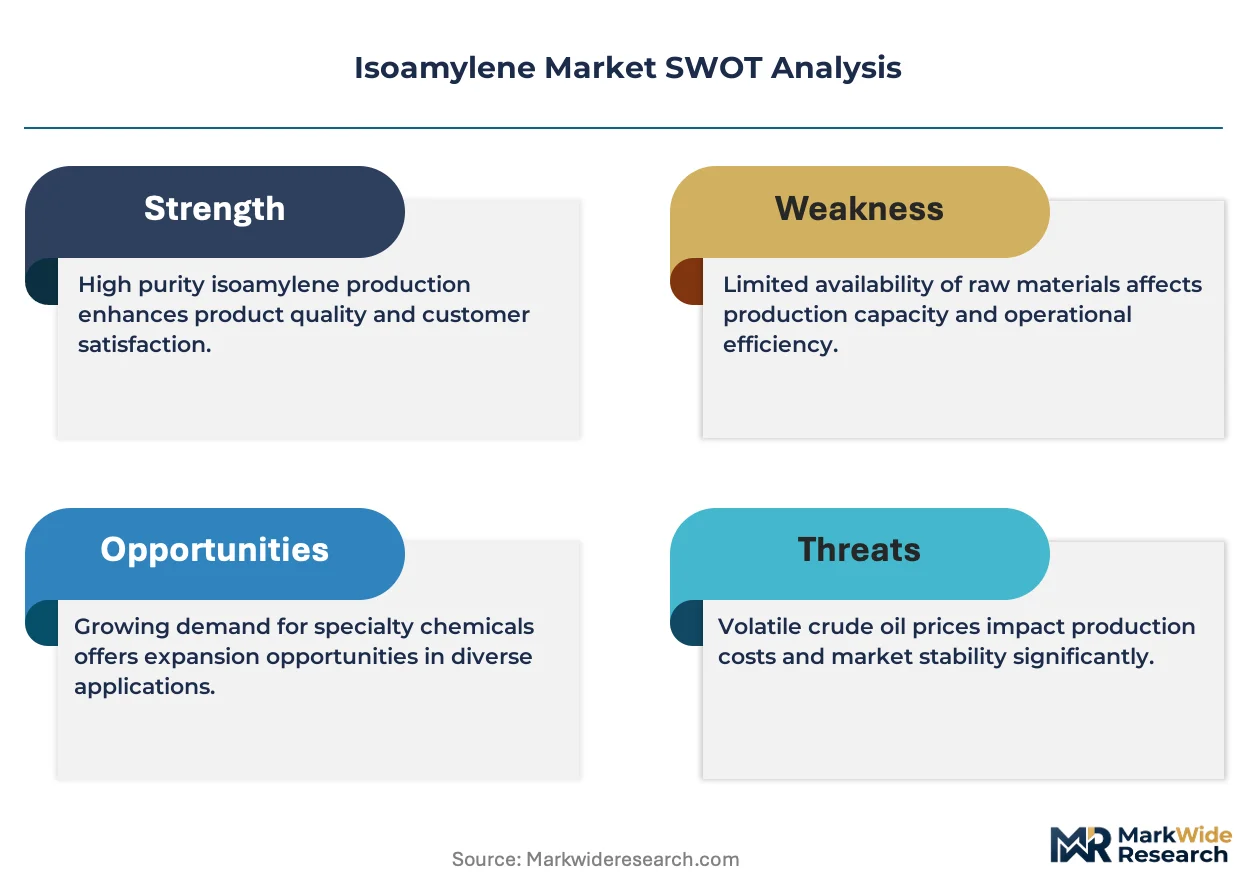
- C5 feedstock volatility:Steam cracker operating rates and fluid catalytic cracking yields fluctuate with refinery economics, compressing margin predictability for non-integrated producers.
- SAMR national standards:China's evolving chemical intermediate specifications create compliance friction for cross-border trade and inventory stratification.
- Alternative antioxidants:Hindered phenolic and phosphite chemistries compete in polymer stabilization applications where isoamylene-derived intermediates historically dominated.
Strategic Opportunities
- Electronics-grade purification:Residual diene content below 50 ppm unlocks semiconductor and display material applications with pricing power decoupled from commodity chemical benchmarks.
- EPA fuel additive reformulation:Evolving standards for refinery-derived additives create technical service relationships with integrated producers seeking compliant intermediate supply.
- Flavor and fragrance precursors:Natural-identical terpene synthesis applications in Japan and Switzerland offer premium positioning outside commodity polymer channels.
Industry Challenges
- Chromatographic separation expertise:High-purity production requires specialized analytical chemists and process engineers in short supply across the specialty chemical sector.
- Multi-jurisdiction qualification:Divergent purity specifications between EPA, REACH, and SAMR frameworks fragment product grades and complicate inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoamylene Market |
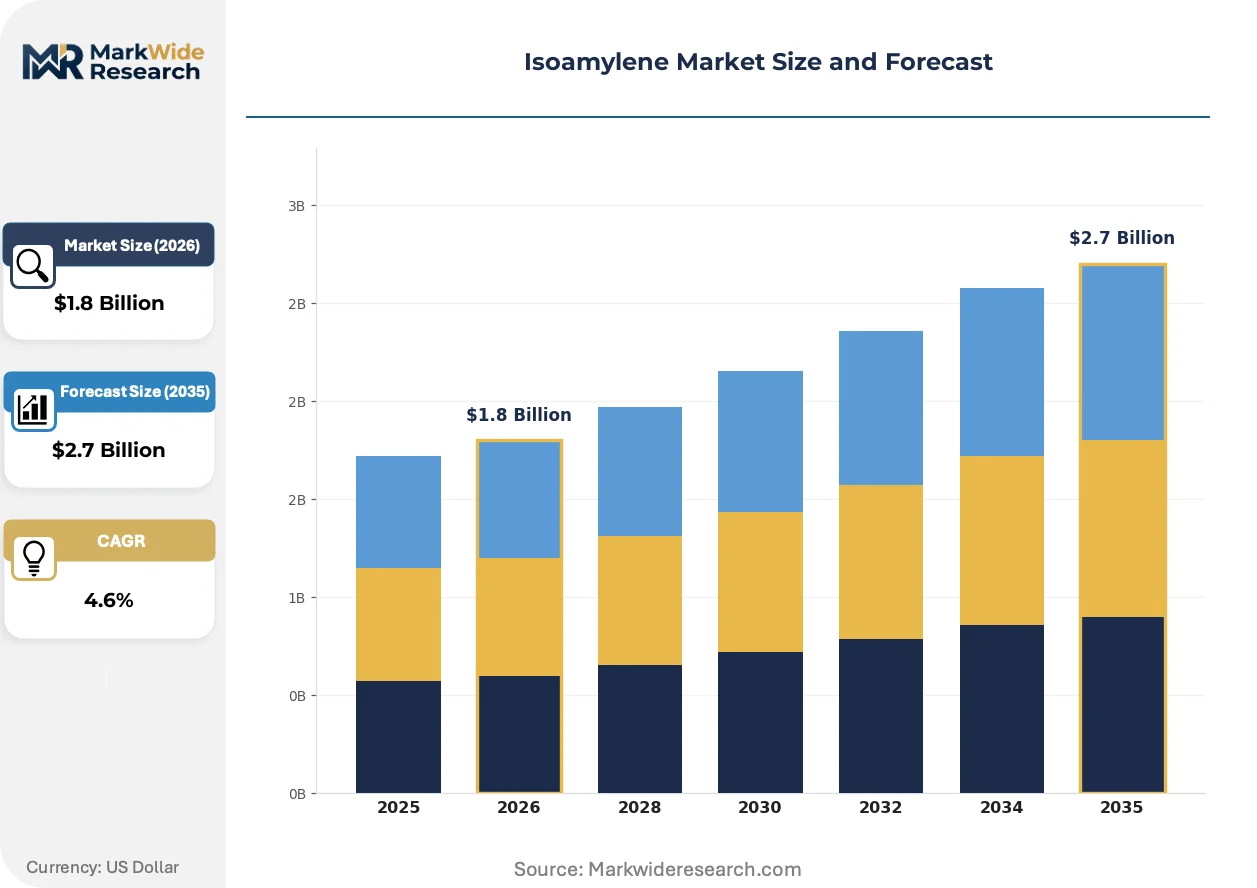
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Isoamylene, Isoamylene Blends, Derivatives, Others Application: Fuel Additives, Chemical Intermediates, Polymer Production, Solvent End User: Chemical Manufacturers, Oil Refineries, Material Suppliers, Pharmaceutical Companies Distribution Channel: Direct Sales, Distributors, Online Retail, Exporters |
| Companies Covered | ExxonMobil Chemical Company, Evonik Industries AG, BASF, Nippon Shokubai Co., Ltd., Sasol Limited, Chevron Phillips Chemical Company, Arkema S.A., Shandong Yuhuang Chemical, INEOS Group Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoamylene Market Strategic Shifts
Process intensification and analytical advancement are compressing the cost-quality frontier for ultra-high-purity grades, while regulatory divergence is fragmenting product specifications across major consumption centers.
Adsorptive separation technology using modified zeolite molecular sieves is expanding into commercial isoamylene purification, enabling producers to achieve pharmaceutical-grade specifications without energy-intensive cryogenic distillation. Specialty polymer compounders in Germany and Japan are adopting these grades for metallocene-catalyzed elastomers. The technology is expanding into mid-scale production facilities previously constrained by capital requirements for conventional separation trains.
REACH authorization procedures for diene-containing substances are tightening residual content thresholds in imported chemical intermediates, forcing reformulation of legacy antioxidant products and accelerating timeline pressures for supplier requalification. European formulators face inventory stranding risk for non-compliant material. Electronics-grade applications in the Netherlands and Ireland are responding with dedicated supply agreements specifying sub-50 ppm diene guarantees.
Specification-driven procurement now dominates pharmaceutical and agrochemical intermediate purchasing, with technical audits replacing spot-market transactions for critical raw materials. Large molecule manufacturers in Switzerland and Massachusetts are consolidating approved supplier lists to three or fewer qualified sources per region. This concentration is most visible in active pharmaceutical ingredient precursors, where batch consistency documentation requirements exceed standard commercial chemical practice.
Isoamylene Market Segmentation
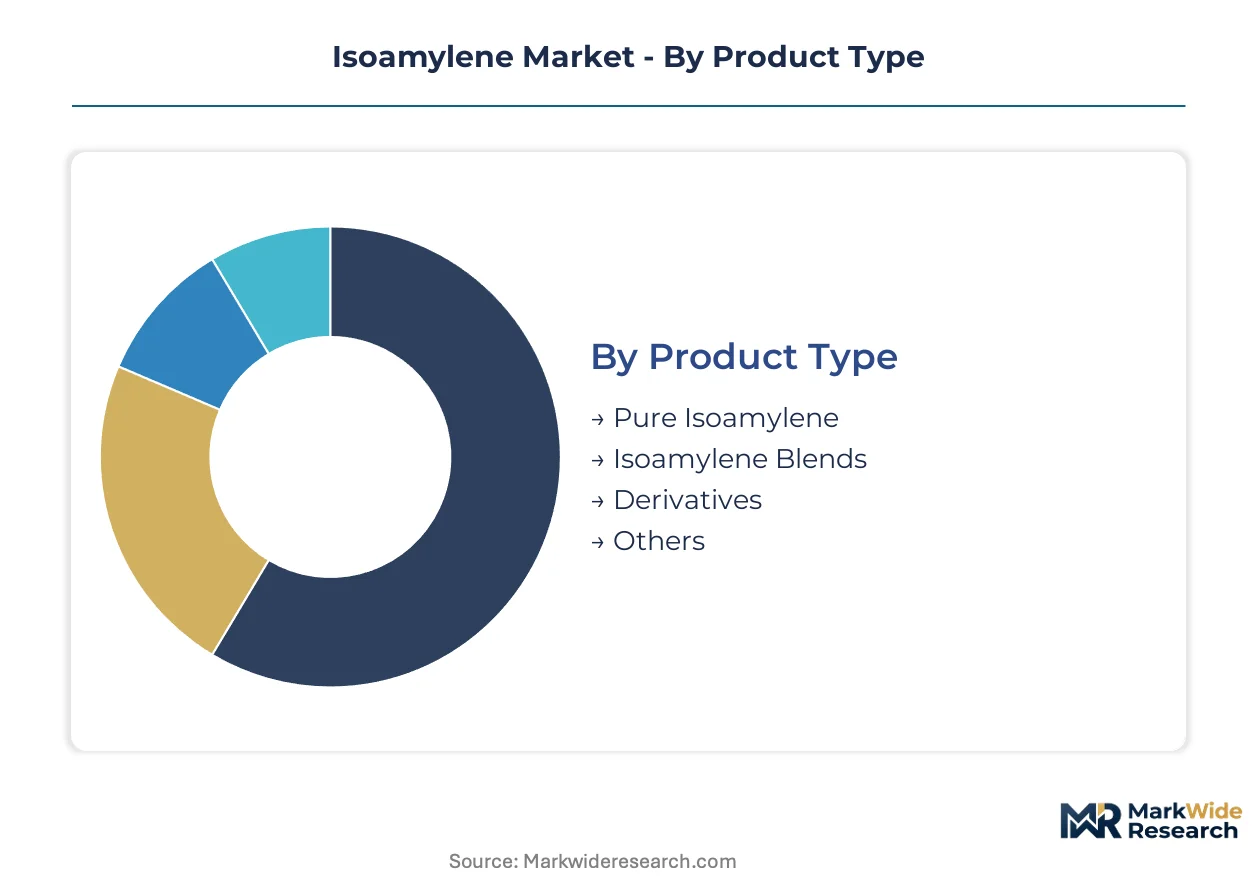
Isoamylene's value chain fragments sharply across purity grades and captive consumption models. Specification thresholds determine pricing power and supplier qualification requirements in each segment cluster.
Product Type:
Customization intensity escalates from commodity blends to pharmaceutical-grade purification, with capital requirements and analytical capabilities determining competitive entry barriers.
- Pure Isoamylene:Pharmaceutical and electronics-grade specifications demand residual diene content below 50 ppm. Swiss and Massachusetts-based active pharmaceutical ingredient manufacturers consolidate procurement around three or fewer qualified suppliers per region.
- Isoamylene Blends:Commercial grades ranging from 65% to 90% purity serve fuel additive and general chemical intermediate applications. Refinery-integrated producers in Texas and Rotterdam leverage captive C5 stream access to defend margin positions.
- Derivatives:Pre-reacted forms including antioxidant precursors and terpene intermediates for flavor applications.
- Others:Specialty grades for research quantities and custom synthesis applications.
Most installed capacity flows through Isoamylene Blends. Expansion is steepest in Pure Isoamylene.
Application:
Volume concentration diverges from value concentration, with fuel additives consuming tonnage while chemical intermediates capture margin.
- Chemical Intermediates:Antioxidant precursors, pharmaceutical building blocks, and agrochemical intermediates command premium positioning. REACH authorization procedures for diene-containing substances force reformulation of legacy products and accelerate supplier requalification timelines in Europe.
- Polymer Production:Metallocene-catalyzed elastomer applications in Germany and Japan expand compatibility with highly branched comonomers. Specialty compounders adopt adsorptive separation grades for controlled reactivity in advanced polymer modification.
- Fuel Additives:Refinery-integrated consumption dominates volume through oxygenate and octane booster formulations.
- Solvent:Niche extraction and cleaning applications in electronics manufacturing.
Volume leadership sits with Fuel Additives. Value per kilogram peaks in Chemical Intermediates.
End User:
Procurement sophistication varies from spot-market purchasing by material suppliers to multi-year technical service agreements with pharmaceutical manufacturers.
- Chemical Manufacturers:Specialty and commodity chemical producers drive specification evolution through purity thresholds and batch consistency documentation requirements exceeding standard commercial practice.
- Pharmaceutical Companies:Large molecule manufacturers in Switzerland and Massachusetts conduct technical audits replacing spot-market transactions for critical raw materials.
- Oil Refineries:Captive consumption through integrated C5 separation and downstream fuel additive production.
- Material Suppliers:Polymer compounders and additive formulators with formulation-dependent sourcing flexibility.
Contract duration extends longest with Pharmaceutical Companies. Spot-market liquidity concentrates around Material Suppliers.
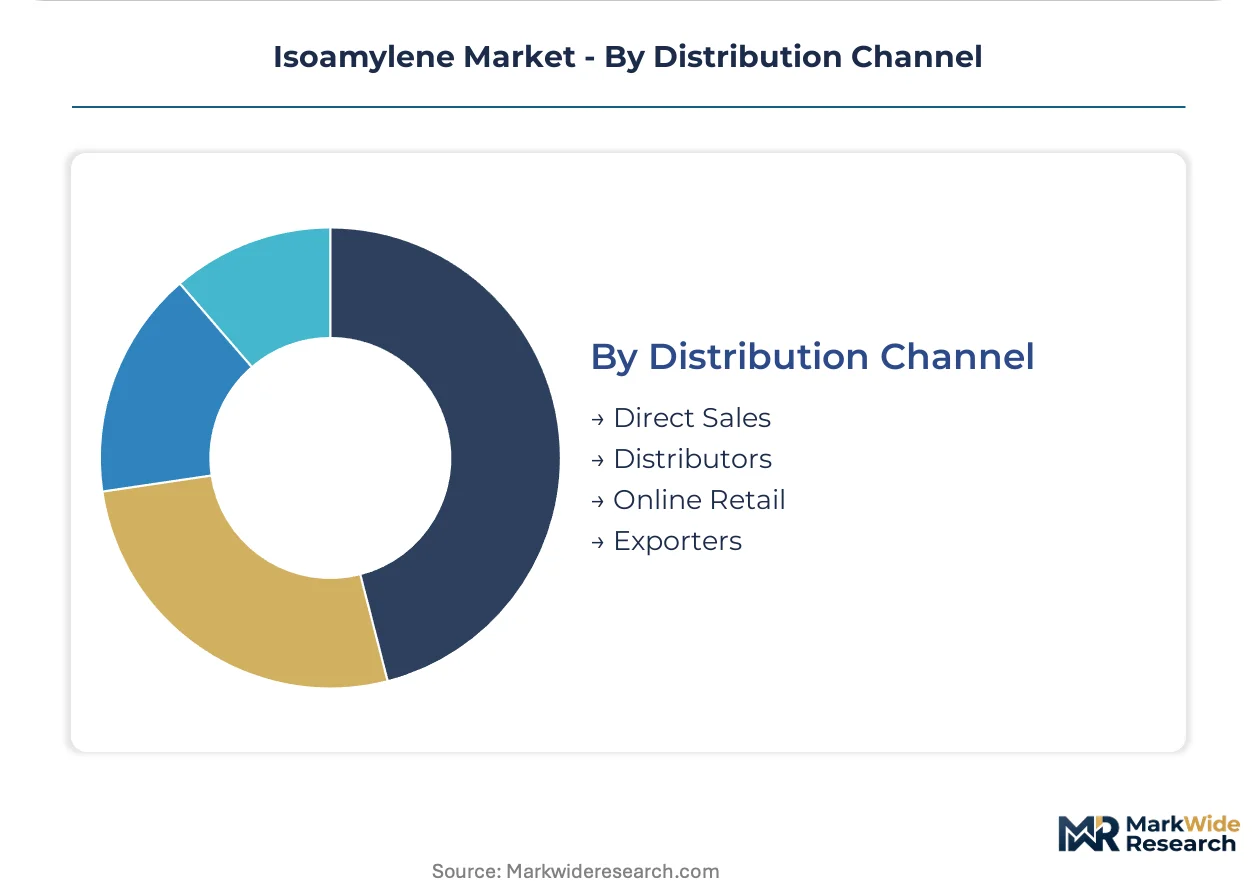
Distribution Channel:
Channel selection tracks shipment scale and technical service requirements, with qualified supplier lists restricting sourcing flexibility in high-purity segments.
- Direct Sales:Pharmaceutical and electronics-grade applications require dedicated supply agreements specifying sub-50 ppm diene guarantees. Technical service relationships dominate channel economics.
- Distributors:Mid-scale chemical manufacturers and regional compounders access inventory pooling and just-in-time delivery through specialty chemical distributors.
- Exporters:Cross-border trade to China faces SAMR national standards compliance friction and inventory stratification risks.
- Online Retail:Research quantities and small-batch custom synthesis for laboratory and pilot-scale applications.
Revenue concentration aligns with Direct Sales. Channel expansion is fastest in Distributors serving mid-scale specialty chemical manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized process engineers and analytical chemists cluster near integrated chemical parks in Shandong and Jiangsu provinces, Germany's Ruhr industrial corridor, and the US Gulf Coast petrochemical belt. This talent concentration shapes where high-purity capacity expands and where qualification timelines compress.
China
Domestic aromatics capacity and downstream derivative projects draw volume toward integrated chemical parks in Shandong and Jiangsu provinces. SAMR national standards for chemical intermediates create compliance friction for cross-border trade and inventory stratification. Shandong Yuhuang Chemical anchors regional supply with backward integration into regional C5 stream access.
Germany
Specialty polymer compounders in the Ruhr region adopt adsorptive separation grades for metallocene-catalyzed elastomers. REACH authorization procedures for diene-containing substances force reformulation of legacy antioxidant products. BASF anchors European supply with captive hydrogenation capacity at Ludwigshafen.
United States
Refinery-integrated producers in Texas leverage captive C5 stream access to defend margin positions in fuel additive applications. EPA fuel additive standards tighten allowable impurity profiles and reshape supplier qualification requirements. ExxonMobil Chemical Company secures feedstock cost advantages across multiple geographies through integrated infrastructure.
Japan
Flavor and fragrance precursor applications in natural-identical terpene synthesis command premium positioning outside commodity polymer channels. METI chemical management frameworks add compliance layers for cross-border trade. Nippon Shokubai Co., Ltd. occupies a position within the high-purity derivatives segment serving pharmaceutical and electronics-grade demand.
Switzerland
Large molecule manufacturers conduct technical audits replacing spot-market transactions for critical raw materials. Swissmedic pharmaceutical regulations exceed standard commercial chemical practice for batch consistency documentation. Active pharmaceutical ingredient precursors concentrate procurement around three or fewer qualified suppliers per region.
Isoamylene Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base separates into refinery-integrated majors, specialty chemical diversifiers, and regional pure-plays. Three archetypes dominate: C5 stream integrators leveraging feedstock access, R&D-intensive formulators of high-purity derivatives, and regional champions serving captive chemical park demand. Capacity expansion and strategic partnerships represent the dominant competitive moves reshaping supply relationships.
Among Germany-based diversified chemical producers, Evonik Industries AG exemplifies the R&D-intensive archetype developing high-purity isoamylene derivatives for polymer applications. South Africa-based Sasol Limited occupies a position within the Fischer-Tropsch and C5 chemistry specialist tier. France-based Arkema S.A. sits within the specialty materials diversifier group serving multiple industrial end-uses. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| ExxonMobil Chemical Company |
| Evonik Industries AG |
| BASF |
| Nippon Shokubai Co., Ltd. |
| Sasol Limited |
| Chevron Phillips Chemical Company |
| Arkema S.A. |
| Shandong Yuhuang Chemical |
| INEOS Group Holdings |
| Others |
Value Chain & Pricing Dynamics
C5 feedstock costs from steam cracker operations flow through three distinct pricing tiers downstream, with refinery-integrated producers in Texas and Rotterdam capturing margin advantages that non-integrated specialty chemical manufacturers cannot replicate. This input-cost hierarchy stratifies pharmaceutical-grade premiums above fuel additive baselines, while SAMR compliance friction adds landed-cost penalties for cross-border shipments into Chinese chemical parks.
Pricing Analysis
Bundled technical service agreements dominate pharmaceutical and electronics-grade procurement, while unbundled spot transactions persist for fuel additive blenders with formulation flexibility. Three-tier pricing structure across premium, standard, and economy levels tracks residual diene thresholds, with sub-50 ppm guarantees commanding substantial premiums over 65% commercial grades. Cost compression in standard-tier blends is intensifying because alternative antioxidant chemistries compete on total formulation economics. Fuel additive buyers exhibit highest price sensitivity due to refinery integration and captive supply alternatives, whereas Swiss API manufacturers show lowest sensitivity given qualification barriers and batch consistency requirements.
Supply Chain Analysis
Specialized analytical chemists and process engineers cluster in Germany's Ruhr corridor, the US Gulf Coast petrochemical belt, and Shandong province, constraining high-purity capacity expansion to these talent-dense geographies. Supply concentrates in the United States, Germany, and China, with feedstock drawn from regional steam cracker and fluid catalytic cracking operations. Raw material dependencies center on C5 fraction availability, hydrogenation catalyst supply, and adsorptive separation media. Single-source vulnerability in pharmaceutical-grade purification expertise threatens supply continuity for qualified producers. Distribution runs through direct technical service relationships for premium grades and specialty chemical distributors for mid-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities between EPA reformulation timelines and REACH authorization procedures create cost and compliance differentials for suppliers with multi-jurisdiction qualification capabilities.
For Market Incumbents: Hedge against C5 feedstock volatility through backward integration into regional steam cracker infrastructure or long-term offtake agreements with integrated refiners. Defend margin positions by accelerating electronics-grade purification investments before diene threshold tightening spreads beyond Europe. Capacity addition in Jiangsu province captures Chinese domestic demand growth while mitigating SAMR compliance friction for cross-border competitors. For New Entrants and Emerging Players: Enter via adsorptive separation technology licensing to bypass capital requirements for cryogenic distillation trains that incumbent producers already possess. White-space targets include flavor and fragrance precursor applications in Japan and Switzerland, where natural-identical terpene synthesis commands premium positioning outside commodity polymer channels. The most penetrable segment is mid-scale specialty chemical manufacturers in Europe seeking qualified alternative suppliers amid REACH-driven requalification timelines. Go-to-market angle: technical audit readiness with batch consistency documentation exceeding standard commercial practice. For Investors and Strategic Acquirers: Roll-up economics work for regional pure-play specialists with captive chemical park access because consolidation captures procurement concentration trends among pharmaceutical manufacturers limiting approved supplier lists to three or fewer qualified sources per region. Long-term viability frames around qualification barrier sustainability rather than commodity chemical cyclicality. Acquisition target archetype: R&D-intensive formulators of high-purity derivatives with existing pharmaceutical customer relationships. Signal to watch: divergence between EPA and SAMR purity specifications that fragments product grades and complicates inventory management for non-specialized producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive C5 stream access secures feedstock cost advantages against volatile refinery economics. |
| Electronics-Grade Purification Investment | Sub-50 ppm diene capability unlocks semiconductor applications with pricing power decoupled from commodity benchmarks. |
| Long-term Supply Agreement | Dedicated contracts with Swiss API manufacturers replace spot-market transactions amid qualification consolidation. |
| Joint Venture | Partnerships in Shandong chemical parks capture Chinese domestic demand growth within SAMR-compliant supply chains. |
| Green Manufacturing Transition | Adsorptive separation technology reduces energy intensity versus cryogenic distillation for pharmaceutical-grade output. |
Study Parameters
Direct dialogue with plant managers at C5 separation facilities, procurement leads at downstream polymer compounders, distribution channel partners in specialty chemicals, and technical R&D directors in adsorptive separation technology grounded qualitative findings. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical producers, and SAMR regulatory publications. Bottom-up and top-down triangulation cross-checked capacity estimates against demand aggregation across application segments.
Bottom-up modeling built from grade-specific production capacity, operating rate assumptions, and purity-tier demand curves, while top-down analysis tracked C5 derivative consumption patterns and fuel additive formulation trends across the analysis window. Segmentation dimensions included purity grade tier, end-use industry application, regional production hub clustering, and qualification status under EPA, REACH, and SAMR frameworks. CAGRs derived from regression analysis of historical price-volume relationships and forward projection of regulatory-driven specification shifts. Industry-specific forecast inputs encompassed metallocene catalyst adoption rates and pharmaceutical outsourcing trends for API precursor manufacturing.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time steam cracker operating rate disclosures introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented assumptions regarding qualification timeline compression and feedstock cost pass-through mechanisms. Material deviation in EPA fuel additive reformulation schedules or SAMR standard implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ketone-Based Solvents Market
Solvents
Mixed Xylene Market
Solvents
Aliphatic Solvents Market
Solvents
Benzene and Its Derivatives Market
Solvents
Crotonaldehyde Market
Solvents
Chloroacetonitrile Market
Solvents
Japan Acetonitrile Market
Solvents
Dimethyl Sulfoxide Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Global Nitrochlorobenzene Market
Solvents
Mineral Turpentine Market
Solvents
Benzylamine Market
Solvents
Hydrophobic Solvents Market
Solvents
Methyl Diethanolamine Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
N-Methyl Pyrrolidone Market