
 Hydrosol Market | 2026-2036
Hydrosol Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrosol Market Foresight
Multi-source botanical procurement is repositioning supply chain economics across the hydrosol sector. Givaudan leverages captive lavender and rose fields in southern France to secure aromatic raw material streams. Robertet Group anchors its competitiveness through deep backward integration into organic cultivation across multiple terroirs. Young Living competes via direct-to-practitioner channels that bypass conventional wholesale markups.
Hydrosols constitute aqueous co-products of steam distillation, typically retaining trace essential oil content between 0.02% and 0.05% along with water-soluble plant acids and flavonoids. These aromatic waters serve primarily as functional ingredients in natural cosmetics, therapeutic preparations, and clean-label food flavoring systems. Floral hydrosols, led by rose and lavender variants, occupy the dominant value share due to premium skincare positioning and established perfumery demand. The Spa & Wellness end-user channel registers the fastest structural expansion as wellness centers replace synthetic toners with plant-derived alternatives. Direct Sales distribution controls margin pools in artisanal segments where provenance storytelling commands price premiums.
REACH registration requirements in Europe mandate full toxicological dossiers for hydrosol ingredients entering cosmetic and pharmaceutical supply chains. FDA oversight of aromatherapy claims in the United States restricts therapeutic marketing language, shaping product positioning toward cosmetic and wellness framing. ISO 9235 standards for natural aromatic raw materials provide quality benchmarks that buyers increasingly embed as contractual specifications. Stakeholders must monitor evolving classification debates around hydrosol versus essential oil regulatory treatment, as jurisdictional inconsistencies create compliance fragmentation.
Market Dynamics
REACH registration dossiers and EU Green Deal compliance mandates are restructuring competitive entry barriers across the hydrosol sector, forcing smaller distillers to consolidate or exit as certification costs concentrate procurement power among integrated producers with captive organic cultivation.
Growth Catalysts
- EU Green Deal alignment:France's Grasse perfume cluster and Provence distillation corridor are capturing preferential sourcing contracts from cosmetics formulators seeking carbon-accounted supply chains.
- Steam distillation co-product valorization:Hydrosols are displacing synthetic toners in Spa & Wellness channels as wellness centers mandate plant-derived ingredient decks.
- Clean-label food flavoring systems:Beverage manufacturers in Italy and Spain are incorporating floral hydrosols into natural flavoring protocols to meet EFSA clean-label thresholds.
Market Restraints
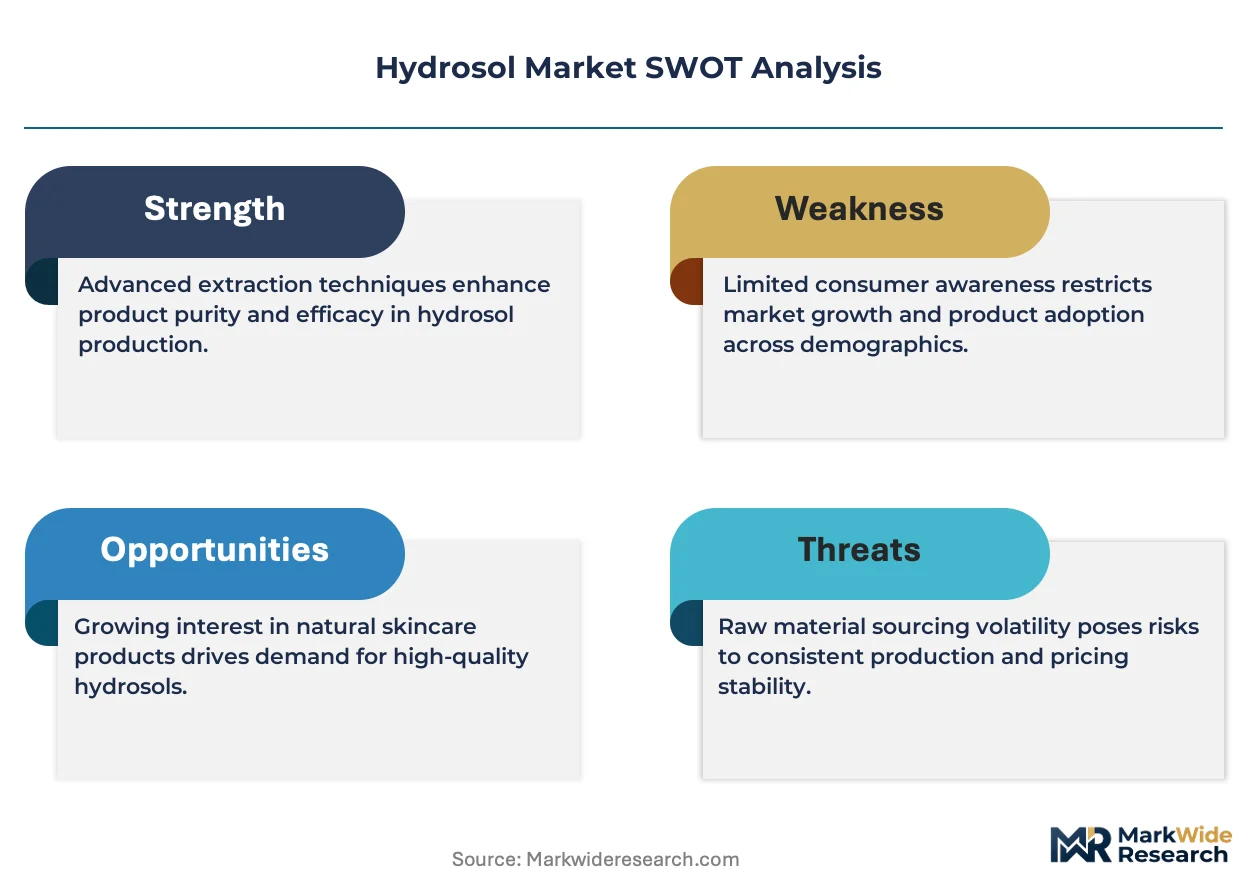
- Organic lavender input cost volatility:Climate stress across southern French growing regions is compressing margins for non-integrated distillers lacking captive field ownership.
- Supply concentration in Grasse-Provence corridor:Over-dependence on a single terroir creates geographic risk exposure for buyers without multi-source botanical procurement strategies.
- ISO 9235 certification timeline friction:Extended analytical validation periods for water-soluble plant acid content are delaying new product commercialization by 8-14 months.
Strategic Opportunities
- Balkan organic cultivation expansion:Bulgaria and Croatia are emerging as alternative lavender and rose damascena sources with lower land costs and emerging organic certification infrastructure.
- Therapeutic-grade hydrosol protocols:Integration with Ayurvedic and Traditional Chinese Medicine practitioner networks is opening direct-to-practitioner distribution channels outside conventional wholesale structures.
- CSRD-mandated supply chain disclosure:Corporate sustainability reporting requirements are creating premium pricing windows for hydrosol producers with verified carbon footprints and biodiversity-positive cultivation practices.
Industry Challenges
- Analytical chemist talent scarcity:Hydrosol-specific expertise in trace essential oil quantification and flavonoid profiling is concentrated among aging specialists in southern France without adequate succession pipelines.
- REACH dossier compilation complexity:Full toxicological documentation for water-soluble plant acids requires specialized regulatory affairs capabilities that mid-scale distillers struggle to resource internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrosol Market |
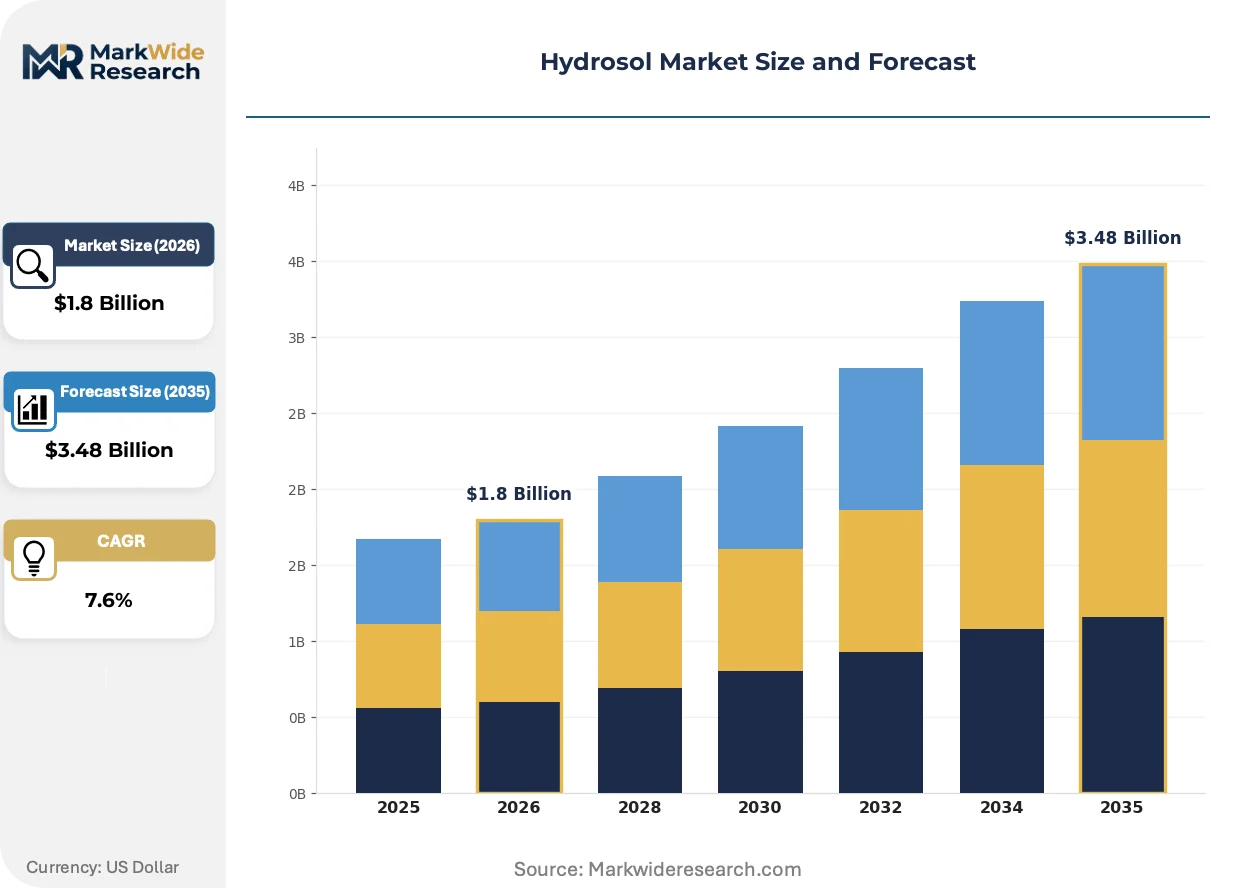
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floral, Herb, Spice, Citrus End User: Cosmetics, Food & Beverage, Pharmaceuticals, Spa & Wellness Application: Aromatherapy, Skin Care, Flavoring, Cleaning Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | DoTERRA, Sydney Essential Oil Co. Pty Limited, Givaudan, The Mountain Rose Herbs, Florihana Distillerie, Plant Therapy Essential Oils, Robertet Group, Flavex Naturextrakte GmbH, Young Living, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrosol Market Shifts & Advancements
Co-product valorization technologies and regulatory disclosure mandates are compressing traditional supply hierarchies while enabling new channel architectures that bypass conventional wholesale markups entirely.
Supercritical CO2 extraction hybridization with traditional steam distillation is unifying essential oil and hydrosol recovery rates for high-value botanicals like rose damascena. Premium skincare laboratories in Switzerland and northern Italy are adopting these integrated systems to maximize yield per hectare of organic cultivation. The technology is unifying what were previously separate capital investment decisions into single-unit operations that reduce per-liter processing costs by eliminating redundant biomass handling.
REACH Annex XVII restrictions on synthetic preservative systems in cosmetic formulations are accelerating hydrosol adoption as natural antimicrobial alternatives. ECHA's 2023-2024 guidance clarifications on hydrosol classification versus essential oil regulatory treatment have reduced compliance ambiguity for formulators. French and German cosmetics manufacturers are responding by embedding hydrosol-derived organic acids as primary preservation systems in rinse-off and leave-on products.
Practitioner-direct purchasing networks are displacing conventional distributor relationships in therapeutic and wellness segments. Aromatherapists and spa formulators in the United Kingdom and Netherlands are forming buying cooperatives that aggregate volume directly from Bulgarian and Croatian distillers. This channel compression is most visible in lavender and chamomile hydrosol categories where provenance documentation commands price premiums unavailable through wholesale intermediaries.
Hydrosol Market Segmentation
Hydrosol procurement decisions pivot on certification grade, end-use application requirements, and provenance documentation. Buyers in cosmetics and wellness channels prioritize organic certification and terroir traceability over price elasticity, creating tiered value capture across segment boundaries.
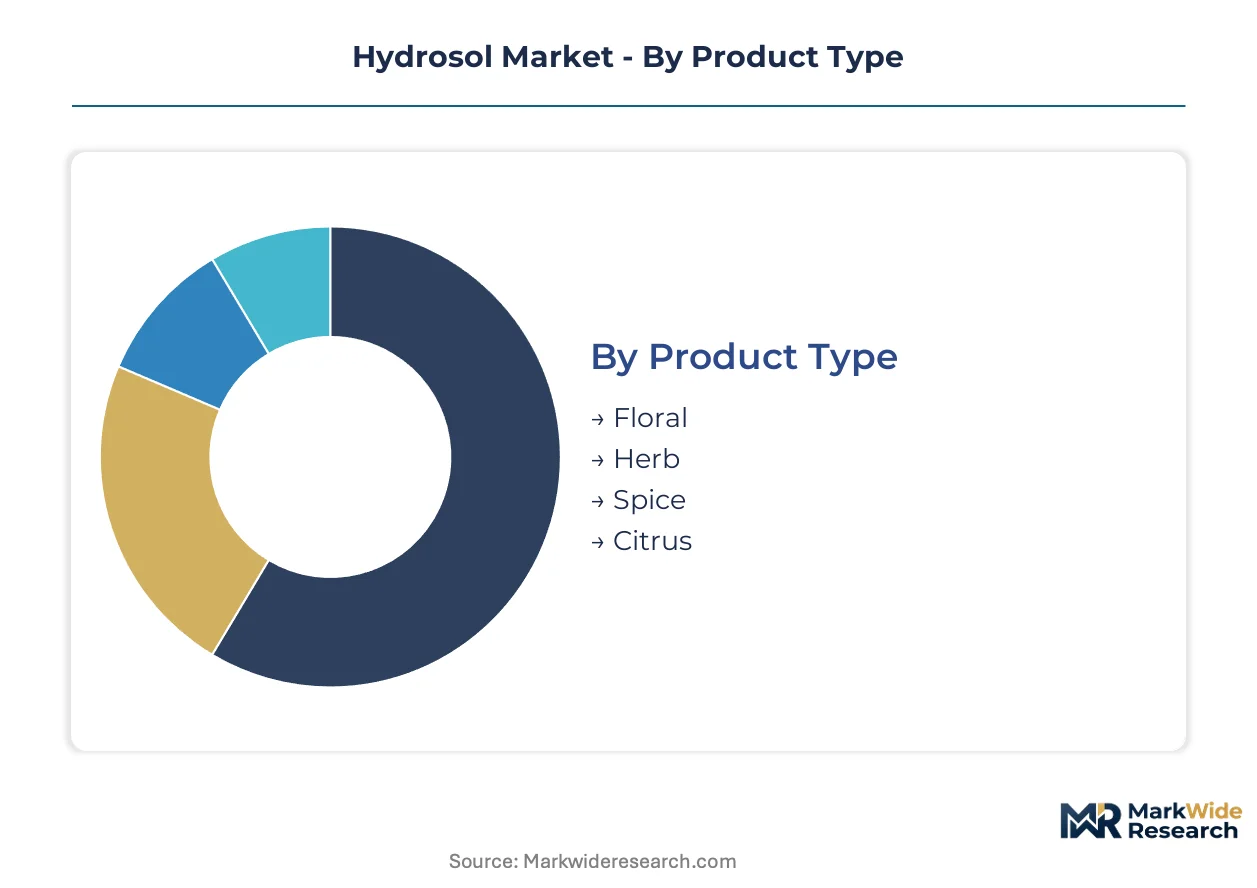
Product Type:
Formulation chemistry and aromatic intensity drive buyer selection, with skincare laboratories prioritizing specific water-soluble compound profiles for functional efficacy.
- Floral:Rose and lavender variants retain 0.02-0.05% trace essential oil content alongside water-soluble plant acids and flavonoids. Demand concentrates in France's Grasse perfume cluster where premium skincare positioning commands price premiums unavailable to commodity distillers.
- Herb:Rosemary, thyme, and sage hydrosols deliver antimicrobial organic acids suited to natural preservative systems. REACH Annex XVII restrictions on synthetic preservatives in German and French cosmetics are accelerating procurement of herb-derived alternatives for rinse-off formulations.
- Spice:Cinnamon and clove variants provide warming aromatic profiles for therapeutic applications.
- Citrus:Neroli and bergamot waters offer bright top notes for clean-label flavoring systems.
Floral hydrosols lead on scale; herb hydrosols lead on momentum as natural preservation demand accelerates.
End User:
Channel-specific regulatory requirements and formulation standards fragment demand patterns across buyer categories.
- Cosmetics:ISO 9235 compliance and ECHA registration dossiers dominate procurement specifications. French and Swiss skincare laboratories embed hydrosol-derived organic acids as primary preservation systems, displacing synthetic alternatives.
- Spa & Wellness:Wellness centers in the United Kingdom and Netherlands mandate plant-derived ingredient decks, replacing synthetic toners with traceable aromatic waters. Practitioner-direct purchasing networks are compressing conventional wholesale markups in this channel.
- Food & Beverage:Italian and Spanish beverage manufacturers incorporate floral waters into natural flavoring protocols.
- Pharmaceuticals:Full toxicological documentation requirements under REACH restrict supply to integrated producers with captive analytical capabilities.
Cosmetics commands volume concentration; Spa & Wellness exhibits the steepest expansion trajectory.
Application:
Functional performance requirements and regulatory claim boundaries shape product positioning and marketing language.
- Skin Care:Toners, mists, and hydration formulations leverage hydrosol pH compatibility and water-soluble active delivery. Bulgarian and Croatian lavender waters are gaining share in direct-to-formulator channels outside conventional distribution.
- Flavoring:EFSA clean-label thresholds in Italy and Spain drive beverage manufacturer adoption of floral hydrosols as natural flavoring carriers.
- Aromatherapy:FDA oversight in the United States restricts therapeutic marketing language, forcing cosmetic and wellness framing.
- Cleaning:Natural antimicrobial properties support surface and textile applications.
Skin Care anchors revenue scale; Flavoring gains share fastest on clean-label regulatory alignment.
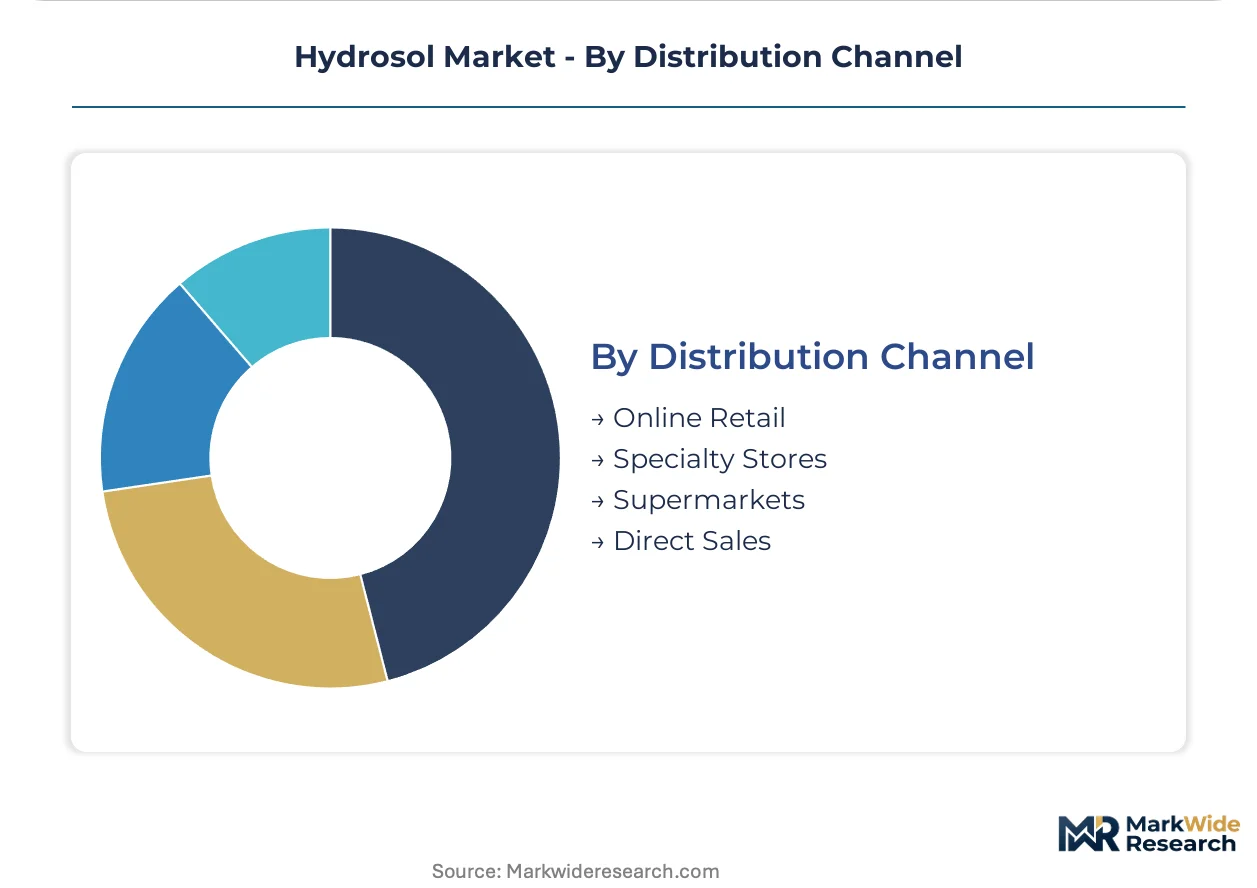
Distribution Channel:
Margin retention and provenance documentation capabilities determine channel viability for different producer scale classes.
- Direct Sales:Artisanal producers in Provence and emerging Balkan cultivation zones bypass wholesale intermediaries entirely. Provenance storytelling commands price premiums unavailable through conventional retail structures.
- Specialty Stores:Curated selection and staff expertise support premium positioning for certified organic variants.
- Online Retail:Aggregator platforms enable Bulgarian and Croatian distillers to reach United Kingdom and Netherlands practitioner networks.
- Supermarkets:Volume scale requirements favor standardized specifications over terroir differentiation.
Direct Sales leads on margin capture; Online Retail climbs the fastest as channel compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting hydrosol production toward jurisdictions with streamlined organic certification pathways and lower REACH compliance overhead. Distillers in Bulgaria and Croatia are capturing volume from French incumbents as EU Green Deal carbon-accounting requirements concentrate procurement power among multi-terroir operators.
France
Grasse perfume cluster demand and Provence distillation corridor infrastructure anchor European value capture. REACH registration dossiers for water-soluble plant acids mandate full toxicological documentation that favors integrated producers with captive analytical capabilities. Organic lavender field ownership in southern growing regions is compressing margins for non-integrated distillers lacking backward integration into cultivation.
Bulgaria
Rose damascena and lavender hydrosol output is expanding as alternative sourcing for cosmetics formulators seeking multi-terroir supply security. Emerging organic certification infrastructure under EU rural development programs is accelerating field conversion rates. The Kazanlak Valley rose-growing region is attracting direct procurement contracts from United Kingdom and Netherlands wellness cooperatives.
Croatia
Lavender cultivation in Hvar and Dalmatian coastal zones is gaining share in practitioner-direct channels bypassing conventional wholesale markups. Lower land costs relative to Provence are enabling competitive positioning for certified organic variants. Adriatic climate stability is reducing climate-stress exposure that compresses margins in southern French growing regions.
United States
FDA oversight of aromatherapy claims is restricting therapeutic marketing language and shaping product positioning toward cosmetic and wellness framing. Direct-to-practitioner networks in California and Pacific Northwest wellness markets are compressing conventional distributor relationships. USDA organic certification requirements for imported hydrosol ingredients are elevating documentation burdens for European suppliers.
Switzerland
Premium skincare laboratories in Swiss Romandie are adopting supercritical CO2 hybrid extraction systems to unify essential oil and hydrosol recovery rates. Swissmedic oversight of cosmetic ingredient safety is embedding ISO 9235 quality benchmarks as contractual specifications. Geneva and Lausanne formulation clusters are sourcing traceable aromatic waters with verified carbon footprints under CSRD-aligned procurement protocols.
Hydrosol Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue Balkan cultivation expansion and direct-to-practitioner channel compression. The vendor base stratifies across integrated fragrance houses with captive field ownership, mid-scale distillers with multi-terroir sourcing, and artisanal operators leveraging provenance storytelling. Three archetypes dominate: backward-integrated cultivation specialists, regulatory-compliance aggregators, and practitioner-network direct sellers. Capacity expansion in Bulgarian and Croatian growing zones and strategic partnerships for REACH dossier compilation represent the dominant competitive moves.
Within the integrated fragrance tier, Givaudan and Robertet Group exemplify backward-integrated operators with captive organic cultivation across multiple terroirs. Among direct-to-practitioner specialists, Young Living occupies a position representing channel compression strategies that bypass conventional wholesale markups. These three entities anchor the competitive spectrum from industrial-scale supply security to artisanal margin capture.
| Leading Market Players |
|---|
| DoTERRA |
| Sydney Essential Oil Co. Pty Limited |
| Givaudan |
| The Mountain Rose Herbs |
| Florihana Distillerie |
| Plant Therapy Essential Oils |
| Robertet Group |
| Flavex Naturextrakte GmbH |
| Young Living |
| Others |
Supply & Pricing Matrix
Supercritical CO2 hybrid extraction systems are compressing per-liter processing costs while concentrating procurement power among Swiss and northern Italian laboratories that have unified essential oil and hydrosol recovery into single-unit operations. This technology shift eliminates redundant biomass handling and rewards integrated producers with captive organic cultivation, forcing non-integrated distillers to absorb margin compression or exit.
Pricing Analysis
Direct-to-practitioner channel compression is eliminating conventional wholesale markups of 35-50% for Bulgarian and Croatian distillers selling into United Kingdom and Netherlands wellness cooperatives. Pricing stratifies across certified organic, conventional, and uncertified tiers, with organic lavender hydrosols from Provence commanding premiums that reflect terroir documentation and REACH dossier completion. Cost compression in the conventional tier is intensifying as climate stress across southern French growing regions elevates input volatility. Spa & Wellness practitioners exhibit the highest price sensitivity, while Swiss skincare laboratories demonstrate inelastic demand for carbon-accounted supply chains.
Supply Chain Analysis
Adriatic freight corridors from Croatian Dalmatian ports to Rotterdam and Hamburg are reducing logistics costs for Balkan-origin hydrosols relative to overland trucking from Provence. Supply concentration rests on France, Bulgaria, and Croatia, with raw material dependencies spanning organic lavender fields, rose damascena cultivation, and analytical chemist expertise concentrated in southern France. Single-source vulnerability to climate stress in the Grasse-Provence corridor creates geographic risk exposure for buyers lacking multi-terroir strategies. Distribution runs through practitioner-direct networks, specialty ingredient aggregators, and integrated fragrance house captive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrosol market has entered a late-cycle quality phase where procurement decisions pivot on certification completeness and carbon-accounted provenance rather than volume scale. Wellness centers and cosmetics formulators are redirecting spend toward suppliers with verified organic cultivation and REACH dossier compliance.
For Market Incumbents: Extend backward integration into Bulgarian and Croatian organic cultivation to secure multi-terroir supply security against climate stress in Provence. Acquire analytical chemist capabilities in southern France before succession gaps harden. Prioritize CSRD-mandated supply chain disclosure infrastructure to capture premium pricing windows from sustainability-reporting buyers.
For New Entrants and Emerging Players: Capture practitioner-direct channels in United Kingdom and Netherlands wellness cooperatives that aggregate volume outside conventional wholesale structures. Target the herb hydrosol segment where REACH Annex XVII restrictions on synthetic preservatives are accelerating demand for rosemary and thyme-derived antimicrobial alternatives. Lead with provenance storytelling and ISO 9235 certification to command price premiums unavailable through retail intermediaries.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale distillers with multi-terroir sourcing but incomplete REACH dossier capabilities. The long-term viability window favors integrated operators with captive field ownership and analytical infrastructure. Watch for ECHA guidance clarifications on hydrosol versus essential oil classification as the signal for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Balkan Cultivation | Secures alternative terroir supply as climate stress compresses Provence margins. |
| REACH Dossier Completion | Unlocks cosmetic and pharmaceutical supply chains requiring ECHA toxicological documentation. |
| Practitioner-Direct Channel Development | Bypasses wholesale markups in United Kingdom and Netherlands wellness networks. |
| CSRD-Aligned Carbon Accounting | Captures premium pricing from buyers with mandated supply chain disclosure requirements. |
| Supercritical CO2 Hybrid System Adoption | Unifies essential oil and hydrosol recovery to maximize yield per hectare of organic cultivation. |
Research Methodology
Bottom-up cosmetics and wellness channel modeling reconciled against top-down distillation capacity tracking forms the analytical core of this study. Primary interviews with organic cultivation managers, regulatory affairs specialists at ECHA-registered producers, procurement leads at French skincare laboratories, and aromatherapy practitioners in United Kingdom buying cooperatives were cross-validated against secondary sources including REACH registration databases, EU organic certification records, customs trade flows, and SEC filings from integrated fragrance houses. This triangulation ensures demand estimates from formulation laboratories align with supply-side field conversion rates and distillation infrastructure expansion.
Input-output matrices map organic lavender and rose damascena cultivation acreage through steam distillation and supercritical CO2 hybrid processing yields to end-use consumption across cosmetics, spa & wellness, and food & beverage channels over the projection horizon. Segmentation dimensions include product type, certification grade, end-user channel, application function, and distribution architecture. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines. Forecast inputs incorporate EU Green Deal carbon-accounting compliance timelines and ISO 9235 certification adoption rates.
Climate volatility in southern French growing regions, ECHA reclassification debates around hydrosol regulatory treatment, and analytical chemist talent scarcity are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context and supply chain exposure to these vectors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
North America Toluene Market
Solvents
Global Glycol Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
Hydrofluoroether Market
Solvents
Diethyl Ether Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Isopropylamine Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Solvent Cement Market
Solvents
Dibutyl Ether Market
Solvents
Industrial Solvents Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Fluid Neutralizing Market
Solvents
Aprotic Solvents Market