
 Ketene Market | 2026-2036
Ketene Market Size, Share, and Industry Trends Forecast 2026-2036
Ketene Market Foresight
Multi-sourced ketene procurement is repositioning supply chain resilience as a strategic priority for derivative manufacturers. DIC Corporation leverages captive pyrolysis capacity to sustain vertical control over diketene and acetoacetic ester output. Lonza Group anchors its position through pharmaceutical-grade ketene derivative specialization, while Shandong Yuhuang Chemical dominates regional feedstock supply through integrated acetic acid-to-ketene manufacturing.
Ketene is a highly reactive organic compound with the formula CH2=C=O, produced industrially through pyrolysis of acetic acid or acetone at temperatures exceeding 700°C, serving primarily as an acetylating agent and intermediate for pigments, agrochemicals, and pharmaceutical actives. Ketene derivatives command the largest value share within product type segmentation, driven by their role in beta-lactam antibiotic synthesis and cellulose ester modification. Agricultural chemicals represents the fastest-growing application segment, as pyrethroid and fungicide manufacturers expand acetoacetic ester offtake for downstream active ingredient production.
EPA oversight of ketene handling and storage under TSCA shapes facility siting and emissions controls for US producers, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for ketene derivative importers. China's MEE enforces stringent volatile organic compound discharge limits on pyrolysis operations, pushing capacity upgrades at major manufacturing clusters. Stakeholders must monitor regulatory divergence between jurisdictions to optimize multi-site production qualification and avoid market access friction.
Market Dynamics
Pyrolysis capacity concentration in Shandong province is forcing derivative manufacturers to reconfigure procurement networks around captive acetic acid supply and dual-source qualification protocols.
Growth Catalysts
- EU Green Deal compliance:REACH registration upgrades for ketene derivatives are tightening purity specifications, creating premium-grade product differentiation and margin expansion for qualified suppliers.
- Acetoacetic ester demand:Pyrethroid manufacturers in agricultural chemicals are expanding offtake volumes for downstream active ingredient synthesis in crop protection formulations.
- Shandong manufacturing clusters:Integrated acetic acid-to-ketene production hubs are achieving feedstock cost advantages that accelerate regional capacity expansion.
Market Restraints
- Acetic acid price volatility:Feedstock cost swings compress margins for non-integrated producers lacking captive acetic anhydride supply.
- Pyrolysis technology barriers:High-temperature reactor construction and safety systems require specialized engineering expertise that limits new entrant participation.
- MEE emission limits:China's volatile organic compound discharge regulations are forcing costly scrubber upgrades and operational shutdowns at legacy facilities.
Strategic Opportunities
- Pharmaceutical-grade specialization:Beta-lactam antibiotic precursor demand is creating white space for GMP-certified ketene derivative production.
- Cellulose ester modification:Pigment and coating applications are absorbing novel diketene derivative formulations with enhanced solubility profiles.
- Dual carbon policy alignment:China's national emissions targets are incentivizing pyrolysis energy efficiency retrofits that reduce carbon intensity ratings.
Industry Challenges
- Pyrolysis operator certification:Specialized high-temperature reactor handling skills are scarce, constraining workforce expansion and shift coverage.
- Multi-jurisdiction dossier compilation:REACH, TSCA, and NMPA registration requirements demand divergent toxicological study designs that extend compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ketene Market |
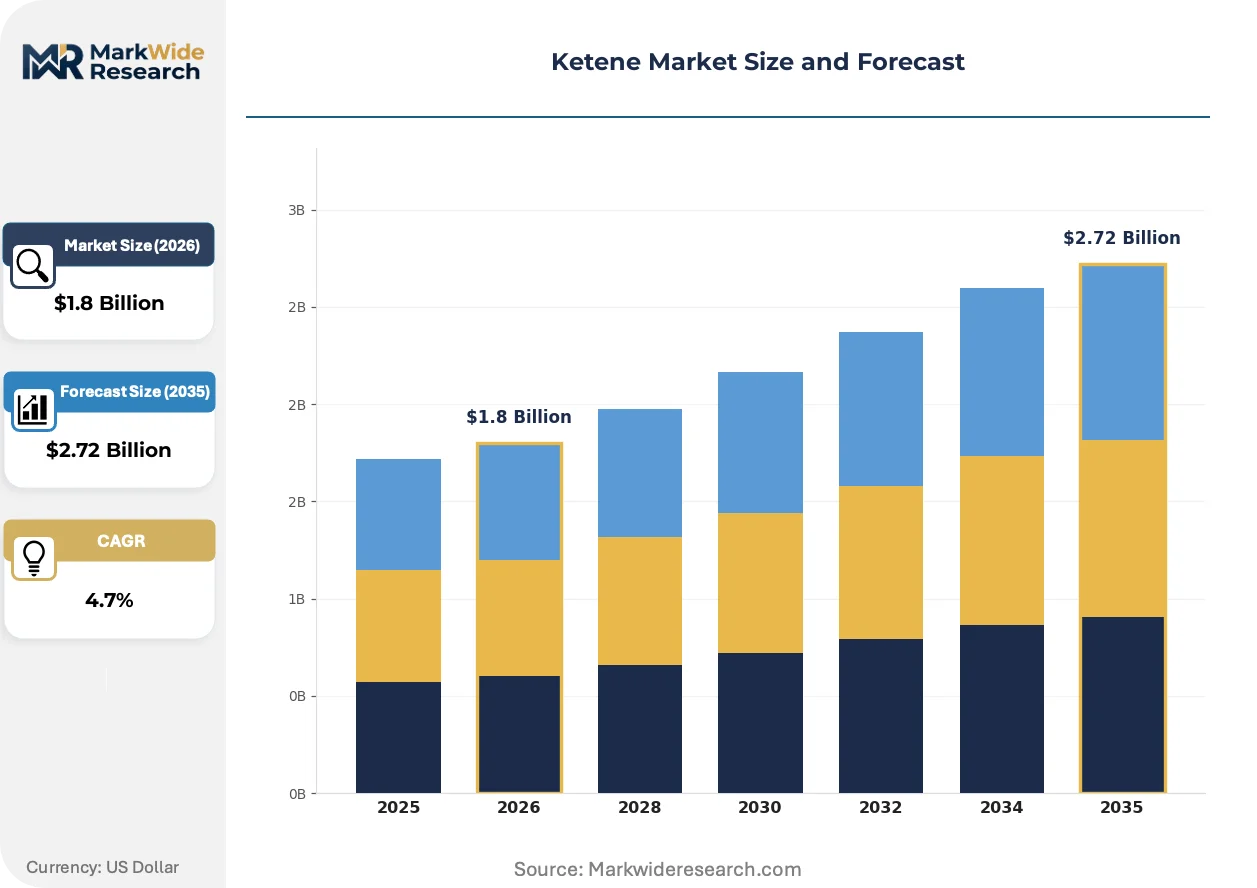
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Ketene Acetal, Ketene Dimers, Ketene Derivatives, Polymerized Ketene Application: Chemical Synthesis, Rubber Processing, Adhesives Manufacturing, Agricultural Chemicals End User: Chemical Manufacturers, Agrochemical Companies, Plastics Producers, Pharmaceuticals Technology: Pyrolysis, Chemical Vapor Deposition, Catalytic Processes, Ultrasonic Methods |
| Companies Covered | DIC Corporation, LANXESS AG, Lonza Group, Mitsui Chemicals, Inc., Shandong Yuhuang Chemical Co., Ltd, Kemira Oyj, Eastman Chemical Company, Laxmi Organic Industries, Daicel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ketene Market Shifts & Advancements
Continuous flow reactor engineering is displacing batch pyrolysis configurations across ketene manufacturing, enabling tighter temperature control and yield consistency. This equipment transition is reshaping capital deployment patterns and technical workforce requirements.
Membrane separation technology for ketene purification is converging with catalytic acetic acid cracking systems. Pharmaceutical manufacturers in Switzerland and Germany are adopting these integrated units to achieve six-nines purity grades for antibiotic intermediate production. The structural consequence is compression of traditional distillation-based supply chains and displacement of commodity-grade intermediates from high-specification applications.
REACH authorization requirements for Substances of Very High Concern are forcing ketene derivative importers to submit extended toxicological dossiers. The European Chemicals Agency is scrutinizing respiratory sensitization data more intensively, extending registration timelines by twelve to eighteen months for non-compliant dossiers. Agricultural chemical formulators are responding by pre-qualifying alternative acetylating agents and accelerating dual-registration strategies.
Long-term offtake contracting is replacing spot market purchasing among beta-lactam antibiotic manufacturers. Multi-year supply agreements with fixed volume floors and price escalation clauses are displacing quarterly tender processes. This behavioral shift is most visible in India and China, where domestic pharmaceutical producers are securing five-year supply commitments to insulate against feedstock volatility and lock in regulatory qualification status.
Ketene Market Segmentation
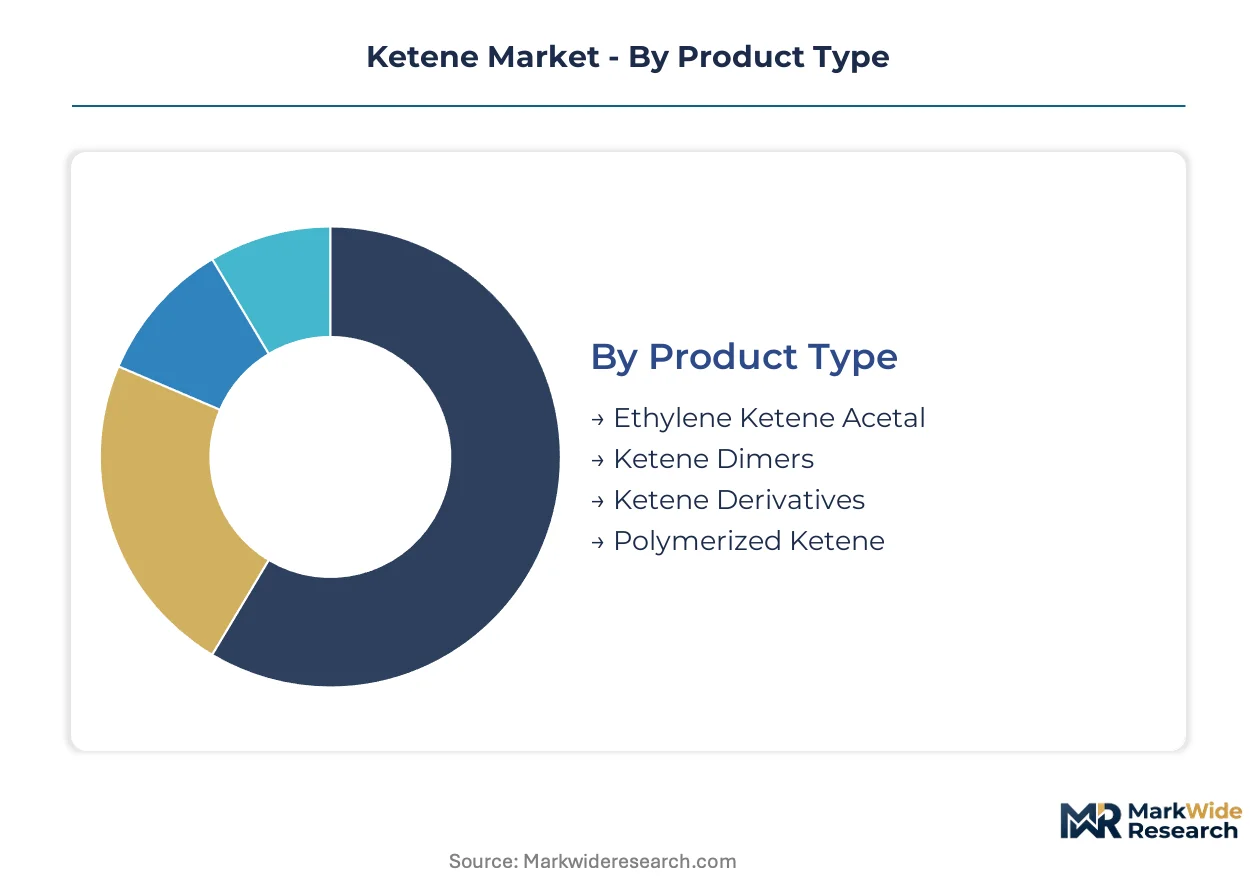
Ketene market segmentation reflects divergent technical requirements across acetylation chemistry, pharmaceutical synthesis, and crop protection applications. Buyers prioritize purity grades, reaction selectivity, and regulatory compliance depending on their downstream processing constraints.
Product Type:
Cost tier differentiation separates commodity acetylating agents from high-purity pharmaceutical intermediates.
- Ketene Derivatives:Beta-lactam antibiotic precursors and cellulose ester modifiers dominate offtake. Pharmaceutical manufacturers in Switzerland and Germany absorb six-nines purity grades for cephalosporin synthesis, while coating formulators drive diketene derivative demand for pigment dispersion.
- Ketene Dimers:Diketene and dehydroacetic acid serve as stabilized acetoacetic ester equivalents. Agrochemical formulators in Shandong province expand procurement for pyrethroid active ingredient production, constrained by REACH authorization timelines for respiratory sensitization data.
- Ethylene Ketene Acetal:Specialty acetal derivatives enable controlled-release formulations in pharmaceutical coatings.
- Polymerized Ketene:Oligomeric ketene forms find niche application in high-performance adhesive systems.
Volume sits with ketene dimers; growth tilts toward ketene derivatives.
Application:
Application selection hinges on reaction temperature tolerance and acetylation efficiency requirements.
- Agricultural Chemicals:Pyrethroid and fungicide manufacturers drive acetoacetic ester consumption. Crop protection formulators in China expand diketene derivative offtake for lambda-cyhalothrin and difenoconazole synthesis, facing MEE volatile organic compound discharge limits on pyrolysis sourcing.
- Chemical Synthesis:General acetylation processes consume ketene for anhydride production and esterification. Fine chemical producers value continuous flow reactor output for yield consistency in multi-step syntheses.
- Adhesives Manufacturing:Cellulose ester modification absorbs ketene derivatives for hot-melt adhesive viscosity control.
- Rubber Processing:Vulcanization accelerators and antidegradants incorporate ketene-derived intermediates.
Revenue concentrates in chemical synthesis; agricultural chemicals climb the fastest.
End User:
End user procurement patterns diverge between spot-market chemical traders and long-term contracted pharmaceutical buyers.
- Pharmaceuticals:Beta-lactam antibiotic manufacturers enforce GMP-certified supply chains with five-year offtake agreements. Indian and Chinese domestic producers lock in regulatory qualification status through fixed-volume contracts with price escalation clauses.
- Agrochemical Companies:Pyrethroid and fungicide formulators balance feedstock volatility against REACH-compliant derivative sourcing. EU Green Deal purity specifications tighten procurement standards for crop protection actives.
- Chemical Manufacturers:Merchant acetic anhydride and ester producers absorb commodity-grade ketene for bulk acetylation.
- Plastics Producers:Cellulose acetate and specialty polymer manufacturers source diketene derivatives for solubility enhancement.
Procurement scale favors chemical manufacturers; contract duration extends furthest in pharmaceuticals.
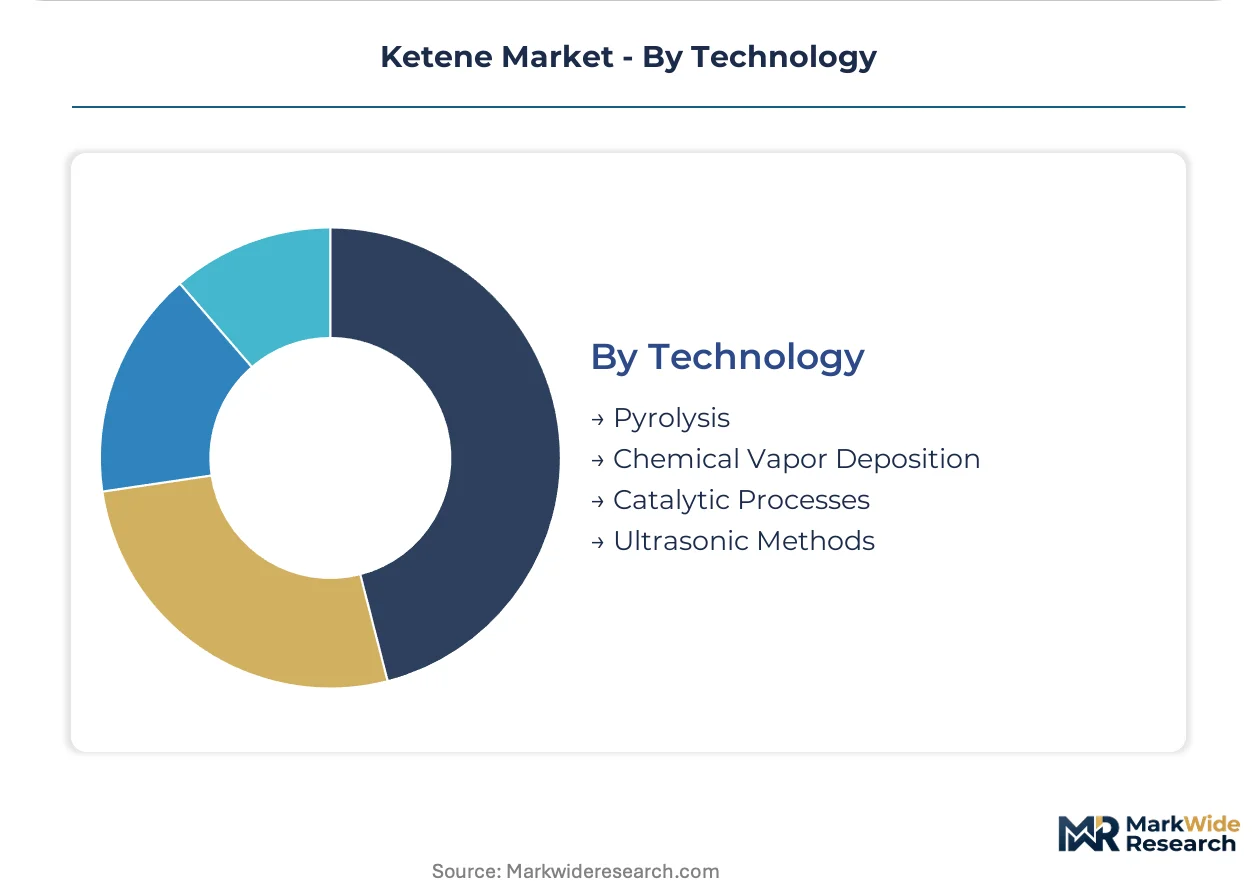
Technology:
Technology adoption tracks capital availability and workforce specialization depth.
- Pyrolysis:High-temperature acetic acid cracking at 700°C-plus dominates industrial production. Shandong province clusters achieve feedstock cost advantages through integrated acetic acid-to-ketene configurations, though MEE emission limits force scrubber upgrades.
- Catalytic Processes:Heterogeneous catalyst systems enable lower-temperature ketene generation with improved selectivity. Pharmaceutical-grade producers adopt catalytic acetic acid cracking with membrane separation for six-nines purity output.
- Chemical Vapor Deposition:Thin-film applications in electronics manufacturing employ specialized ketene delivery systems.
- Ultrasonic Methods:Laboratory-scale synthesis utilizes acoustic cavitation for controlled ketene generation.
Installed capacity clusters in pyrolysis; catalytic processes gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acetic acid feedstock availability in Shandong province anchors ketene production geography, with pyrolysis clusters concentrated where integrated acetic acid supply chains minimize feedstock logistics costs.
China
Shandong province hosts expanding diketene derivative capacity serving domestic agrochemical and pharmaceutical manufacturers. MEE volatile organic compound discharge limits force scrubber upgrades at legacy pyrolysis facilities. Qingdao and Zibo industrial clusters concentrate integrated acetic acid-to-ketene manufacturing with captive feedstock supply.
United States
Pharmaceutical-grade ketene derivative demand from beta-lactam antibiotic manufacturers drives specialty intermediate imports. EPA TSCA oversight shapes facility siting and emissions controls for domestic pyrolysis operations. Texas Gulf Coast petrochemical corridors host merchant acetic anhydride producers absorbing commodity ketene for bulk acetylation.
Germany
REACH registration requirements mandate comprehensive toxicological dossiers for ketene derivative importers, extending qualification timelines. ECHA scrutiny of respiratory sensitization data intensifies compliance burdens. Ludwigshafen and Leverkusen chemical parks anchor pharmaceutical intermediate formulation for European antibiotic supply chains.
India
Domestic pharmaceutical producers secure five-year supply commitments to insulate against feedstock volatility and lock in regulatory qualification status. CDSCO GMP certification requirements tighten procurement standards for beta-lactam precursors. Maharashtra and Gujarat manufacturing corridors concentrate agrochemical formulators expanding pyrethroid active ingredient production.
Switzerland
Pharmaceutical manufacturers adopt catalytic acetic acid cracking with membrane separation for six-nines purity output. Swissmedic oversight of antibiotic intermediate production enforces batch traceability and quality system documentation. Basel chemical cluster anchors high-specification ketene derivative demand for cephalosporin synthesis.
Ketene Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and regulatory qualification dimensions. The vendor base stratifies between captive pyrolysis operators, pharmaceutical-grade specialists, and merchant derivative suppliers. Three archetypes dominate: integrated acetic acid-to-ketene producers achieving feedstock cost advantages; GMP-certified pharmaceutical intermediate specialists commanding premium pricing; and regional commodity derivative manufacturers serving agrochemical formulators. Capacity expansion and dual-source qualification protocols represent the dominant competitive moves reshaping procurement relationships.
Within the integrated producer tier, Shandong Yuhuang Chemical Co., Ltd and DIC Corporation exemplify backward control over acetic acid feedstock and pyrolysis output. Lonza Group occupies a position among pharmaceutical-grade specialists, anchoring GMP-certified supply chains for beta-lactam antibiotic precursors. These three entities represent distinct strategic archetypes: regional feedstock dominance, vertical manufacturing control, and regulatory-qualified specialization.
| Leading Market Players |
|---|
| DIC Corporation |
| LANXESS AG |
| Lonza Group |
| Mitsui Chemicals, Inc. |
| Shandong Yuhuang Chemical Co., Ltd |
| Kemira Oyj |
| Eastman Chemical Company |
| Laxmi Organic Industries |
| Daicel Corporation |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification premiums separate six-nines purity ketene derivatives from commodity acetylating agents, with REACH dossier compliance costs embedding directly into supplier qualification protocols and long-term offtake contract structures. This bifurcation concentrates pricing power among GMP-certified producers while forcing agrochemical buyers into dual-source arrangements that absorb regulatory risk across divergent purity tiers.
Pricing Analysis
Service bundling distinguishes pharmaceutical-grade supply agreements, where technical documentation, batch traceability, and regulatory filing support are included, from commodity transactions stripped to bare product delivery. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with beta-lactam antibiotic manufacturers least price-sensitive due to GMP lock-in requirements. Pricing pressure stems from acetic acid feedstock volatility compressing margins for non-integrated pyrolysis operators. Agrochemical formulators in Shandong province exhibit highest price sensitivity, sourcing diketene derivatives through spot-market channels when long-term contracts expire.
Supply Chain Analysis
Scarce pyrolysis reactor operators in Shandong, Texas Gulf Coast, and Ludwigshafen chemical parks constrain capacity expansion timelines and shift coverage at legacy facilities. Feedstock supply draws from captive acetic acid production, merchant anhydride markets, and acetone cracking operations, with energy costs representing a volatile input layer. Single-source vulnerability concentrates in Shandong province, where MEE emission enforcement has triggered unplanned operational halts. Distribution runs through integrated chemical park pipelines for captive consumption, with merchant derivatives moving via specialized tanker networks to pharmaceutical and agrochemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story, where REACH authorization timelines for respiratory sensitization data erect twelve-to-eighteen-month barriers that protect qualified incumbents from price-commoditization pressure.
For Market Incumbents: Extend GMP certification coverage into adjacent beta-lactam precursors before CDSCO and NMPA alignment tightens qualification standards. Backward integration into catalytic acetic acid cracking with membrane separation preserves margin position against feedstock volatility. Capacity addition in Switzerland and Germany anchors high-purity output for cephalosporin synthesis demand. For New Entrants and Emerging Players: Capture white space in cellulose ester modification for coating applications, where solubility-enhanced diketene derivatives face limited qualified competition. India's domestic pharmaceutical corridor offers the most penetrable geography, with five-year offtake contracting norms enabling regulatory qualification lock-in. A go-to-market angle emphasizing continuous flow reactor engineering and yield consistency differentiates against legacy batch pyrolysis suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with GMP-certified pharmaceutical intermediate specialists given long-term offtake contracting displacement of spot purchasing. Five-to-ten year viability favors producers with captive acetic acid supply and dual-jurisdiction dossier completion. The signal to watch is ECHA authorization timeline compression for respiratory sensitization data, which would accelerate consolidation among REACH-compliant derivative manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Shandong Yuhuang's captive feedstock supply achieves cost advantages against merchant-dependent competitors. |
| GMP Certification Investment | Lonza Group's pharmaceutical-grade specialization commands premium pricing from beta-lactam antibiotic manufacturers. |
| Continuous Flow Reactor Upgrade | DIC Corporation's pyrolysis engineering transition enables tighter temperature control and yield consistency. |
| Long-term Supply Agreement | Indian pharmaceutical producers' five-year offtake commitments insulate against feedstock volatility and lock qualification status. |
| Dual-Jurisdiction Dossier Filing | REACH and TSCA parallel registration reduces market access friction for multi-site production qualification. |
Research Methodology
Multi-period observation of pyrolysis capacity utilization, REACH authorization timelines, and acetic acid price spreads anchored the trend analysis, supplemented by interviews with plant managers at Shandong and Texas Gulf Coast facilities, procurement leads at agrochemical formulators, technical R&D directors in pharmaceutical intermediate synthesis, and distribution channel partners in specialty chemical logistics. Secondary validation drew from customs and trade data, Cefic and ACC industry reports, SEC 10-K filings from listed chemical producers, and ECHA registration dossiers. Bottom-up capacity modeling and top-down demand segmentation were triangulated against price realization data.
Input-output matrices mapped acetic acid feedstock flows through pyrolysis and catalytic cracking configurations to derivative output tiers across the projection horizon. Segmentation dimensions modeled included purity grade tier, end-use industry application, regional production hub concentration, and technology configuration. CAGRs were derived from slope analysis of historical capacity additions against demand elasticity estimates, incorporating MEE emission limit compliance costs and pyrolysis reactor construction lead times as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization timeline shifts, acetic acid supply disruptions, and pyrolysis operator certification scarcity. Forecasts reflect assumptions about regulatory stability and feedstock cost normalization without guarantee. Material deviation in ECHA scrutiny intensity or Shandong province environmental enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
India High Purity Solvents Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Green Solvents Market
Solvents
Global Glycidol Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Solvent Green 7 Market
Solvents
Isoamylene Market
Solvents
Global Acetonitrile Market
Solvents
Toluene Market
Solvents
Hydrofluoroether Market
Solvents
Isoparaffin Solvents Market
Solvents
Solvent Recovery Systems Market
Solvents
Aliphatic Solvents Market
Solvents
Fluorinated Solvents Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Vapor Degreasing Solvents Market