
 Wood-Based Sheet Materials Market | 2026-2036
Wood-Based Sheet Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Wood-Based Sheet Materials Market Insights
The EU Green Deal's cascading requirements for embodied carbon disclosure in building materials is expanding addressable demand for low-emission engineered wood products. Kronospan leverages its integrated resin and substrate operations to control feedstock costs across Central European mills. Georgia-Pacific sustains extensive softwood fiber sourcing agreements across the US Southeast, anchoring its OSB and plywood capacity. Arauco competes through radiata pine plantation management in Chile, extending harvest-cycle predictability to panel manufacturing customers.
Wood-based sheet materials comprise engineered panels manufactured from veneers, particles, fibers, or strands bonded under heat and pressure with synthetic or bio-based adhesives, typically ranging in density from 160 kg/m³ for insulation boards to 1,000 kg/m³ for high-density fiberboard. These products serve primarily as structural substrates, finished surfaces, and load-bearing elements across construction, furniture, and transport packaging applications. Plywood and OSB dominate structural construction applications where moisture resistance and shear strength determine specification, while MDF captures margin pools in furniture manufacturing through its uniform surface for lacquering and thermoforming. Particleboard occupies the economy tier of furniture substrates, pressured by laminate flooring demand shifting toward water-resistant SPC and WPC alternatives.
EPA formaldehyde emission standards under TSCA Title VI, the EU Construction Products Regulation with CE marking requirements, and Japan's JIS A 5908 for particleboard collectively shape product formulation, third-party certification costs, and export market access for panel producers. Health Canada's PMRA reviews of phenol-formaldehyde resins influence adhesive substitution timelines toward soy-based and PMDI alternatives. Stakeholders must monitor regulatory divergence between North American and European VOC thresholds, as compliance fragmentation threatens to segment supply chains and strand capital in single-jurisdiction certification systems.
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are compressing specification windows for traditional steel and concrete substrates, redirecting mid-rise commercial and residential procurement toward engineered timber panels with verified environmental product declarations.
Growth Catalysts
- EU Green Deal embodied carbon benchmarks:Residential construction firms in Germany and Austria are scaling procurement of certified engineered panels to meet cascading disclosure requirements for building materials.
- Mass timber structural systems:Cross-laminated timber and mass plywood panels are capturing specification share from steel and concrete in mid-rise commercial builds across the Pacific Northwest and British Columbia.
- Radiata pine plantation cycles:Chilean plantation management extends harvest-cycle predictability to panel manufacturing customers, reducing feedstock volatility for export-oriented producers.
Market Restraints
- Formaldehyde resin cost volatility:Phenol-formaldehyde and urea-formaldehyde adhesive prices fluctuate with petrochemical feedstock markets, squeezing margin pools on commodity particleboard and MDF.
- Softwood fiber supply concentration:US Southeast timberland ownership concentrates among integrated forest products companies, limiting independent OSB and plywood producers' bargaining leverage.
- Moisture-resistant SPC and WPC flooring:Stone-polymer composite and wood-polymer composite alternatives are displacing laminate flooring demand that historically absorbed particleboard substrates.
Strategic Opportunities
- US Inflation Reduction Act domestic content bonuses:Mass timber projects in federal buildings qualify for enhanced tax credits, accelerating specification pipelines for cross-laminated timber in government construction.
- Bio-based adhesive convergence:Soy-based and PMDI resin technologies are maturing alongside phenol-formaldehyde substitution timelines driven by Health Canada PMRA reviews.
- Direct-to-fabricator digital channels:Furniture manufacturers in Poland and Italy are bypassing traditional distributor networks to source MDF and particleboard through platform-based procurement systems.
Industry Challenges
- CE marking certification timelines:EU Construction Products Regulation third-party verification creates six-to-twelve-month approval gaps between formulation adjustments and market access.
- Resin chemistry technical talent:Adhesive formulation expertise concentrates among aging specialist cohorts, constraining R&D velocity for bio-based binder development.
- Multi-jurisdiction VOC threshold divergence:EPA TSCA Title VI, EU ECHA classifications, and Japan's JIS A 5908 create compliance fragmentation that strands capital in single-market certification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood-Based Sheet Materials Market |
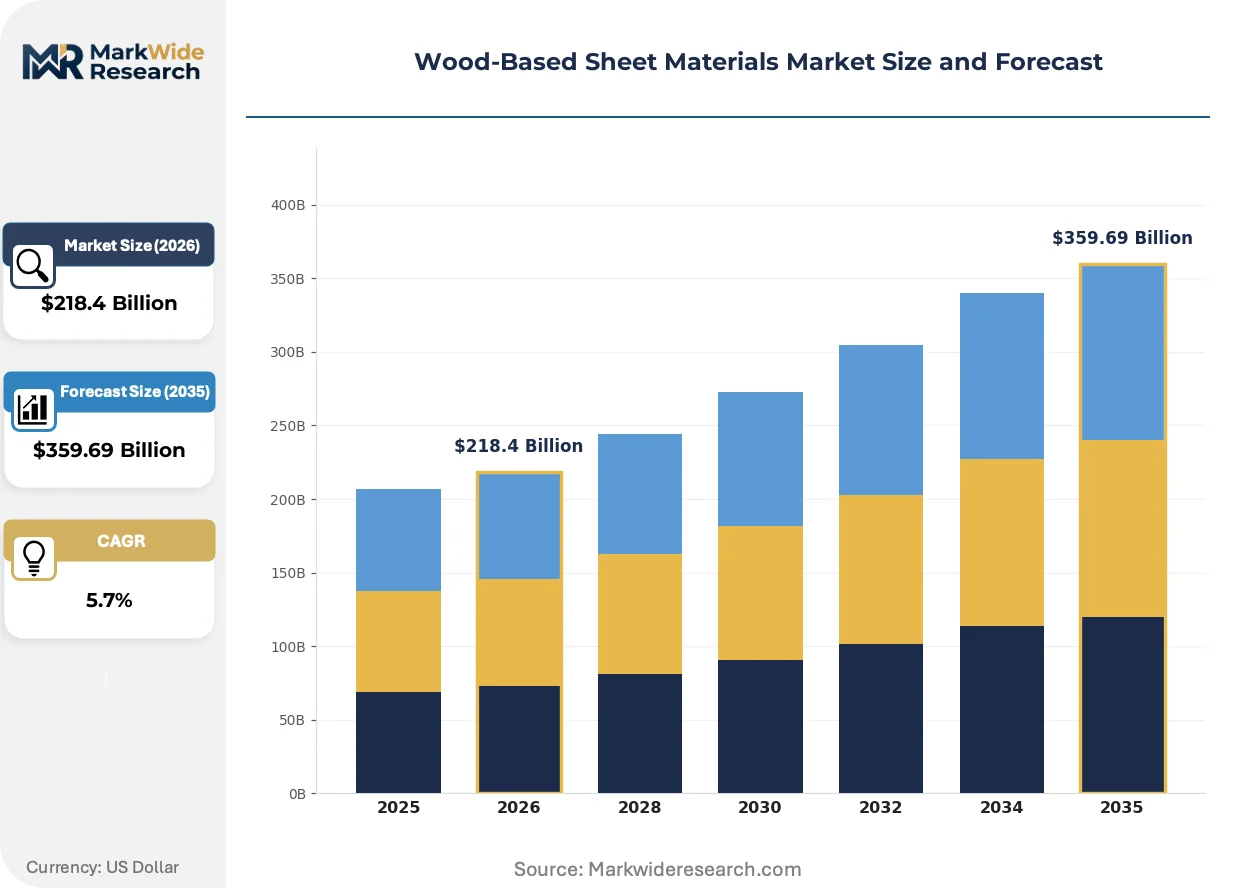
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $359.69 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Particleboard, MDF, OSB, Veneer, Hardboard Application: Furniture Manufacturing, Interior Paneling, Flooring, Packaging, Construction, Exhibition Stands End User: Carpentry Workshops, Cabinet Makers, Construction Firms, Packaging Companies, Set Designers, Furniture Retailers Surface Treatment: Laminated, Melamine Faced, Veneered, Coated, Untreated |
| Companies Covered | Kronospan, Georgia-Pacific, Weyerhaeuser Company, Arauco, West Fraser Timber Co., EGGER Group, Boise Cascade Company, Louisiana-Pacific Corporation, Swiss Krono Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood-Based Sheet Materials Market Trends and Innovations
Digital manufacturing integration and adhesive chemistry substitution are compressing product development cycles while regulatory disclosure requirements reshape specification authority across construction value chains.
Cross-laminated timber (CLT) and mass plywood panel (MPP) systems are electrifying structural design conventions for five-to-twelve-story commercial buildings. Architects in British Columbia and Oregon are specifying these systems for accelerated construction timelines. The technology is electrifying competitive positioning between regional mass timber fabricators and incumbent precast concrete suppliers.
REACH authorization procedures and EU Green Deal cascading requirements are tightening disclosure obligations for embodied carbon in building materials. Panel producers must now maintain chain-of-custody documentation from forest certification through finished product. German and Austrian residential developers are prioritizing suppliers with verified environmental product declarations in competitive bidding.
Specification authority is migrating from general contractors to architect-engineer consortiums as environmental performance data becomes a threshold qualification. Mass timber projects in the Pacific Northwest now require upfront embodied carbon modeling before substrate selection. This shift compresses traditional distributor influence and rewards manufacturers with transparent supply chain data infrastructure.
Wood-Based Sheet Materials Market Segmentation
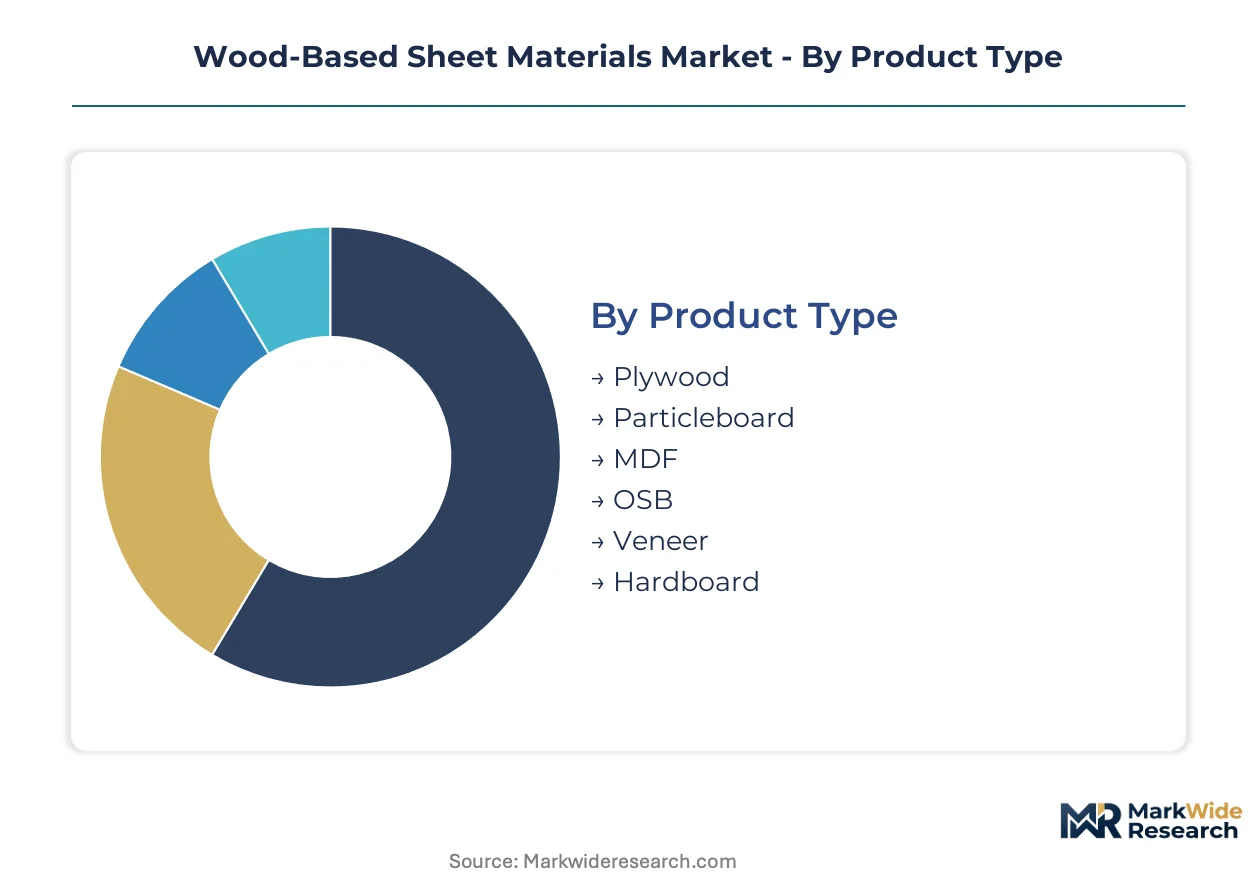
Segmentation in wood-based sheet materials determines specification pathways through divergent certification burdens, moisture resistance requirements, and surface finish tolerances. Each product category carries distinct adhesive chemistry constraints that gate access to residential, commercial, or export markets.
Product Type:
Plywood and OSB require TSCA Title VI or CE marking compliance for structural applications, while MDF and particleboard face additional E1/E0 formaldehyde emission classifications in EU and Japanese markets.
- Plywood:Cross-bonded veneer construction delivers shear strength and dimensional stability under cyclic moisture loading. Construction firms in British Columbia specify marine-grade Douglas fir plywood for mid-rise mass timber projects where EU Green Deal embodied carbon thresholds apply.
- OSB:Oriented strand mat configuration aligns wood flakes in cross-directional layers for racking resistance. US Southeast production clusters serve residential wall sheathing demand where IRC building code compliance mandates structural panel ratings.
- MDF:Homogeneous fiber mat pressing yields uniform density surfaces suited to thermoforming and lacquering. Furniture manufacturers in Poland source E1-classified MDF for laminate flooring substrates facing REACH SVHC disclosure requirements.
- Particleboard:Flaked wood particles bonded with urea-formaldehyde resin occupy economy-tier furniture applications. Cabinet makers in Italy are shifting procurement toward water-resistant alternatives as SPC flooring displaces traditional laminate demand.
- Veneer:Thin rotary-cut or sliced decorative layers overlay lower-grade substrates for aesthetic surfacing. Set designers in Germany specify FSC-certified veneer for exhibition stand construction under CSRD supply chain disclosure rules.
- Hardboard:Exploded wood fiber reconstitution under extreme pressure creates dense panels for pegboard and furniture backing. Packaging companies in Austria utilize tempered hardboard for reusable shipping crates requiring moisture resistance.
Leading the category by volume: OSB in North American residential construction. Expanding most quickly: Plywood in mass timber structural systems.
Application:
Construction and furniture manufacturing absorb divergent cost tiers, with structural applications prioritizing span ratings and furniture production emphasizing surface uniformity for finishing operations.
- Furniture Manufacturing:MDF and particleboard substrates dominate case goods production where thermoforming and edge-banding operations require consistent density profiles. Polish fabricators are bypassing distributors to source panels through digital procurement platforms.
- Construction:Plywood and OSB structural panels carry APA or TECO certification for shear wall and roof diaphragm applications. Pacific Northwest architects specify mass plywood panels for five-to-twelve-story commercial buildings accelerating project timelines.
- Interior Paneling:Veneered MDF and melamine-faced particleboard serve wall cladding where surface aesthetics override structural loading. German residential developers prioritize suppliers with verified environmental product declarations in competitive bidding.
- Flooring:High-density fiberboard underlayment supports laminate and engineered wood floor systems. Stone-polymer composite alternatives are compressing particleboard demand in moisture-prone installations.
- Packaging:Plywood and hardboard crates protect capital equipment during international shipment. Chilean radiata pine plantation cycles extend supply predictability to export-oriented crate manufacturers.
- Exhibition Stands:Lightweight particleboard and veneer panels enable rapid assembly and disassembly for trade show installations. Italian set designers specify low-formaldehyde substrates to meet indoor air quality standards for temporary occupied spaces.
Dominant by revenue: Construction applications in mass timber adoption corridors. Steepest expansion trajectory: Interior paneling driven by EU Green Deal procurement mandates.
End User:
Customer scale fragments procurement patterns, with national construction firms negotiating long-term fiber supply agreements while carpentry workshops purchase through distributor networks.
- Construction Firms:Large-scale developers in Germany and Austria are scaling certified engineered panel procurement to meet cascading embodied carbon disclosure requirements under EU Green Deal regulations.
- Furniture Retailers:Flat-pack assemblers specify E1-classified particleboard and MDF for ready-to-assemble case goods sold through European and North American big-box channels.
- Cabinet Makers:Custom millwork shops source moisture-resistant plywood and thermally fused laminate panels for kitchen and bath installations requiring ANSI/KCMA durability certification.
- Carpentry Workshops:Small-batch fabricators purchase cut-to-size panels through regional distributors, limiting direct manufacturer relationships and compressing price transparency.
- Packaging Companies:Industrial crate manufacturers specify ISPM-15 compliant plywood for export shipments, requiring heat treatment or fumigation documentation at port of entry.
- Set Designers:Film and exhibition production teams prioritize lightweight, paint-ready surfaces with rapid turnaround specifications for temporary installations.
Highest volume concentration: Construction firms in Pacific Northwest and Central European mass timber corridors. Procurement velocity climbing fastest: Furniture retailers consolidating supplier bases through platform-based direct sourcing.
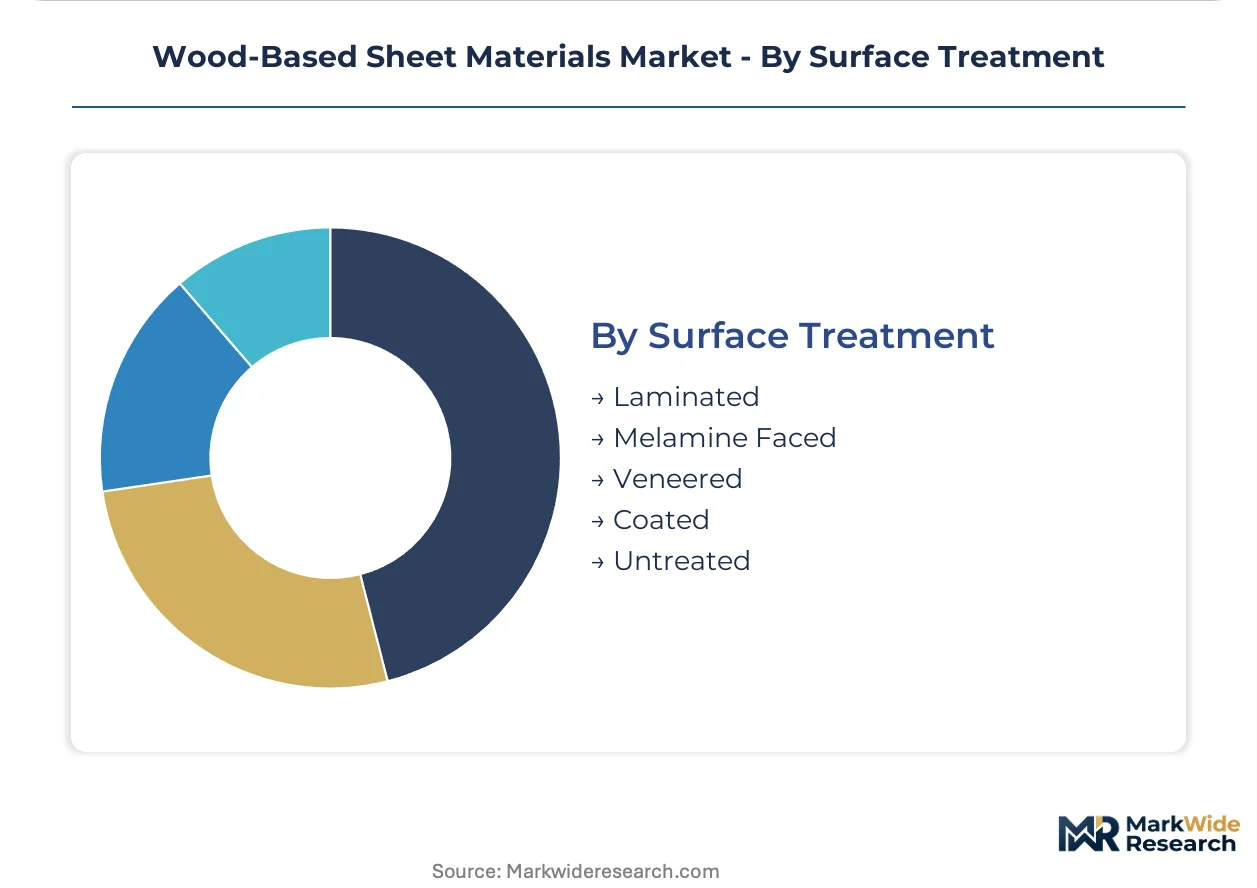
Surface Treatment:
Finish specification determines margin pools, with untreated commodity panels competing on fiber cost while laminated and veneered surfaces capture value through design differentiation and durability warranties.
- Melamine Faced:Thermally fused resin-impregnated paper creates scratch-resistant surfaces for kitchen cabinetry and office furniture. German manufacturers specify post-formable grades for curved edge applications.
- Veneered:Natural wood decorative layers command premium positioning in residential and hospitality interiors where grain matching and figure variation drive aesthetic value.
- Laminated:High-pressure laminate overlays deliver impact and chemical resistance for healthcare and laboratory casework requiring stringent cleanability standards.
- Coated:UV-cured acrylic and polyurethane finishes provide factory-applied protection for flooring and paneling applications, reducing field finishing labor.
- Untreated:Raw substrate surfaces serve paint-grade applications and secondary manufacturing steps where subsequent processing determines final appearance.
Revenue leadership: Melamine faced panels in European furniture manufacturing. Gaining share fastest: Veneered surfaces in sustainable hospitality and residential specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in timber-rich jurisdictions while consumption tilts toward urbanized construction corridors. Germany and Austria import engineered panels to meet EU Green Deal procurement mandates. British Columbia exports mass timber systems to Pacific Northwest commercial projects.
United States
Residential construction absorbs OSB and plywood volumes across the Southeast and Midwest. EPA TSCA Title VI compliance shapes adhesive formulation decisions for structural panel exports. Georgia-Pacific anchors production capacity across Alabama and Louisiana mills serving domestic wall sheathing demand.
Germany
Residential developers in Bavaria and North Rhine-Westphalia prioritize certified engineered panels with verified environmental product declarations. EU Construction Products Regulation CE marking requirements compress approval timelines for imported substrates. Kronospan operates integrated resin and substrate facilities across Central European mill networks.
Canada
British Columbia mass timber fabricators supply cross-laminated timber to Oregon and Washington commercial projects. Health Canada PMRA reviews of phenol-formaldehyde resins accelerate adhesive substitution toward bio-based alternatives. Vancouver architects specify mass plywood panels for five-to-twelve-story buildings accelerating construction schedules.
Chile
Radiata pine plantation management extends harvest-cycle predictability to export-oriented panel manufacturers. Arauco controls fiber supply through vertically integrated forestry operations in the Biobío and Maule regions. Santiago-based producers ship plywood and fiberboard to North American and Asian furniture manufacturers.
Austria
Passivhaus construction standards drive specification of low-emission MDF and particleboard for interior applications. EU Green Deal cascading disclosure requirements mandate chain-of-custody documentation from forest certification through finished product. Upper Austrian mill clusters supply German furniture retailers through direct digital procurement channels.
Wood-Based Sheet Materials Market Competitive Landscape
The competitive structure tilts toward integrated forest products companies with captive fiber supply. North American producers concentrate OSB and plywood capacity near softwood timberland holdings. European specialists dominate MDF and particleboard through resin chemistry control and surface treatment differentiation. Scale-driven capacity expansion and bio-based adhesive R&D partnerships constitute the dominant competitive vectors.
Among North American integrated producers, Georgia-Pacific and West Fraser Timber Co. exemplify the fiber-captive archetype, while Kronospan represents the European model of resin-substrate integration. Arauco anchors the Southern Hemisphere plantation-to-panel supply chain. These three occupy positions across divergent regulatory environments—EPA TSCA Title VI in North America, EU Green Deal embodied carbon thresholds in Europe, and export-oriented certification requirements in Latin America.
| Leading Market Players |
|---|
| Kronospan |
| Georgia-Pacific |
| Weyerhaeuser Company |
| Arauco |
| West Fraser Timber Co. |
| EGGER Group |
| Boise Cascade Company |
| Louisiana-Pacific Corporation |
| Swiss Krono Group |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists across Central Europe and the US Southeast anchor supply discipline through multi-generational timberland stewardship, translating harvest-cycle predictability into long-term contract pricing stability for construction and furniture buyers.
Pricing Analysis
Cost-down pressure on commodity particleboard accelerates as stone-polymer composite flooring displaces traditional laminate demand, compressing specification windows for economy-tier substrates. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified mass timber systems from CE-marked structural panels and untreated commodity boards. Price differentiation hinges on embodied carbon disclosure grade and moisture resistance certification. Residential construction firms in Germany exhibit highest price sensitivity, while Passivhaus developers in Austria accept premiums for low-emission MDF with verified environmental product declarations.
Supply Chain Analysis
Direct-to-fabricator channels handle hyperscale furniture manufacturer demand in Poland and Italy, bypassing traditional distributor markups. Fiber supply concentrates in Chile, the US Southeast, and British Columbia, with radiata pine plantation cycles, softwood timberland ownership, and coastal Douglas fir harvests feeding panel production. Raw material dependencies center on phenol-formaldehyde resins, urea-formaldehyde adhesives, and bio-based binder precursors. Single-source vulnerability in petrochemical-derived adhesive supply threatens margin stability. Distribution runs through integrated mill-direct contracts for construction volume and platform-based procurement for furniture substrate sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adhesive formulation capacity constraints prop pricing power for resin-integrated producers, as bio-based substitution timelines lag regulatory pressure curves.
For Market Incumbents: Anticipate formaldehyde resin cost volatility by securing long-term phenol supply agreements or accelerating PMDI and soy-based adhesive R&D partnerships. Defend position through backward integration into plantation forestry in Chile or the US Southeast, locking fiber cost predictability. Monitor Health Canada PMRA review outcomes as a regulatory inflection point for chemistry substitution mandates. For New Entrants and Emerging Players: Capture specification share in mass timber structural systems across Pacific Northwest commercial construction, where EU Green Deal-aligned embodied carbon thresholds create procurement urgency for cross-laminated timber and mass plywood panels. Target digital procurement platform partnerships with Polish and Italian furniture fabricators seeking direct mill relationships. Lead with transparent chain-of-custody documentation as a competitive wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor resin-substrate integrated specialists in Central Europe with captive CE marking certification infrastructure and established environmental product declaration libraries. Long-term viability rests on bio-based adhesive transition execution and mass timber specification pipeline depth. Watch US Inflation Reduction Act domestic content bonus uptake in federal building projects as a demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Forestry | Chilean radiata pine cycles extend harvest predictability to export-oriented panel manufacturers. |
| Bio-Based Adhesive R&D Partnership | Soy-based and PMDI resin maturation accelerates phenol-formaldehyde substitution timelines driven by Health Canada PMRA reviews. |
| Mass Timber Certification Investment | CE marking and environmental product declaration infrastructure qualifies producers for EU Green Deal procurement mandates in Germany and Austria. |
| Direct-to-Fabricator Digital Channel | Platform-based procurement bypasses distributor networks for Polish and Italian furniture manufacturers. |
| Long-Term Fiber Supply Agreement | US Southeast softwood sourcing anchors OSB and plywood capacity for residential construction demand. |
Research Methodology
Independent corroboration across mill operations executives, resin chemistry R&D directors, furniture procurement leads, and construction specification architects underwrites the qualitative findings. Primary interviews with distribution channel partners and regulatory affairs specialists at panel producers combined with secondary validation from EPA TSCA Title VI filings, EU Construction Products Regulation documentation, customs trade data, and forest certification databases. Bottom-up volume modeling triangulates against top-down construction spending and furniture production indices.
Rate-of-change decomposition across the analysis window segments growth by product type, application, surface treatment, and end-user scale. The forecast framework models plywood, OSB, MDF, particleboard, veneer, and hardboard categories through construction activity indices, furniture manufacturing output, and mass timber adoption curves. CAGRs derive from regression against historical price elasticities and substitution dynamics. Embodied carbon disclosure mandate penetration and bio-based adhesive substitution timelines serve as key forecast inputs.
The model holds under stable regulatory enforcement intensity and intact construction credit availability; deviation in tariff regimes or adhesive feedstock supply disruption would shift volume trajectories. Forecasts reflect documented assumptions on mass timber specification velocity and EU Green Deal cascading requirement implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Unbleached Kraft Pulp Market
Paper Products
North America Thermal Paper Market
Paper Products
Overlay Paper Market
Paper Products
Pulp Market
Paper Products
White Line Chipboard Market
Paper Products
Synthetic Paper Market
Paper Products
Global Direct Thermal Ticket Paper Market
Paper Products
Glassine Paper Market
Paper Products
Organic Tissue Paper Market
Paper Products
Paper Glass Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Paper Machinery Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Softwood Pulp Market
Paper Products
Paper and Board Technologies Market