
 Recovered Paper Market | 2026-2036
Recovered Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Recovered Paper Market Outlook
Packaging converters are reorganizing recovered paper procurement away from printing publishers toward e-commerce fulfillment centers and corrugated box plants. Smurfit WestRock dominates containerboard integration across North America and Europe. Pratt Industries anchors its competitive position through in-house recycling infrastructure at multiple US mill sites. International Paper Company sustains long-term supply agreements with municipal collection programs.
Recovered paper consists of post-consumer and post-industrial fiber streams that are sorted, de-inked, pulped, and refined to specified brightness and contamination thresholds for re-entry into paper manufacturing. The material serves primarily as a lower-cost fiber substitute in packaging grades where strength specifications tolerate shorter fiber lengths. Cardboard collection through commercial channels commands premium pricing due to lower contamination rates and predictable volume flows. Mechanical recycling retains fiber length and dominates volume throughput, while chemical recycling approaches remain limited to specialty de-inking applications with higher margin recovery.
EPA guidelines under the Resource Conservation and Recovery Act shape contamination standards for municipal recovery facilities, while China's SAMR enforces import quality thresholds that redirect regional trade flows. India's BIS certification requirements for recycled packaging materials are tightening testing protocols for heavy metal content. Stakeholders must monitor how fragmented collection infrastructure in emerging economies affects feedstock availability against tightening end-product specifications.
Market Dynamics
China's GB standards for recycled fiber content are forcing packaging converters across Asia-Pacific to requalify their entire recovered paper supply chains, tightening contamination thresholds and redirecting procurement away from mixed-waste streams toward single-source cardboard collection.
Growth Catalysts
- Corporate Sustainability Mandates:E-commerce fulfillment centers in India and Southeast Asia are establishing direct collection partnerships with containerboard mills to secure post-consumer fiber streams that satisfy Scope 3 emissions reporting requirements under CSRD-aligned corporate frameworks.
- India's Western Industrial Corridor Expansion:Domestic containerboard capacity additions in Gujarat and Maharashtra are concentrating recovered paper demand in a geographic cluster where logistics costs favor localized procurement networks over import-dependent supply.
- Mechanical Recycling Process Refinement:Advanced optical sorting and robotic separation technologies are reducing contamination rates in municipal recovery facilities, enabling higher-grade fiber recovery that meets tightening board specifications without chemical de-inking.
Market Restraints
- Import Quality Threshold Friction:China's SAMR enforcement of strict contamination ceilings has eliminated a historical export destination for lower-grade mixed paper, forcing US and European collectors to absorb price discounts or divert volumes to landfill.
- Regional Supply Concentration Risk:Cardboard collection infrastructure concentrates in urban commercial corridors, leaving rural and semi-urban feedstock stranded with uneconomic transport costs to nearest mill processing capacity.
- Chemical Recycling Cost Barrier:Specialty de-inking applications for high-brightness graphic paper remain confined to niche markets where fiber recovery margins cannot justify capital intensity against mechanical alternatives.
Strategic Opportunities
- India BIS Certification Tailwind:Tightening testing protocols for heavy metal content in recycled packaging materials create first-mover advantage for collectors and processors who invest in pre-sorting infrastructure ahead of mandatory compliance deadlines.
- E-commerce Reverse Logistics Integration:Direct partnerships between packaging converters and last-mile delivery networks enable capture of post-consumer corrugated at point of delivery, bypassing fragmented municipal collection systems entirely.
- Chemical-Mechanical Hybrid Process Convergence:Pilot installations combining enzymatic treatment with conventional pulping are opening fiber recovery pathways for contaminated streams previously rejected by mechanical systems alone.
Industry Challenges
- Sorting Technician Skill Scarcity:Optical and robotic separation systems require operators trained in machine vision calibration and contamination spectroscopy, a workforce profile absent from traditional paper recycling labor pools.
- Mill-Side Capex Intensity:De-inking and refining equipment upgrades to process higher-contamination feedstock demand capital commitments that strain mid-scale containerboard producers with limited balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recovered Paper Market |
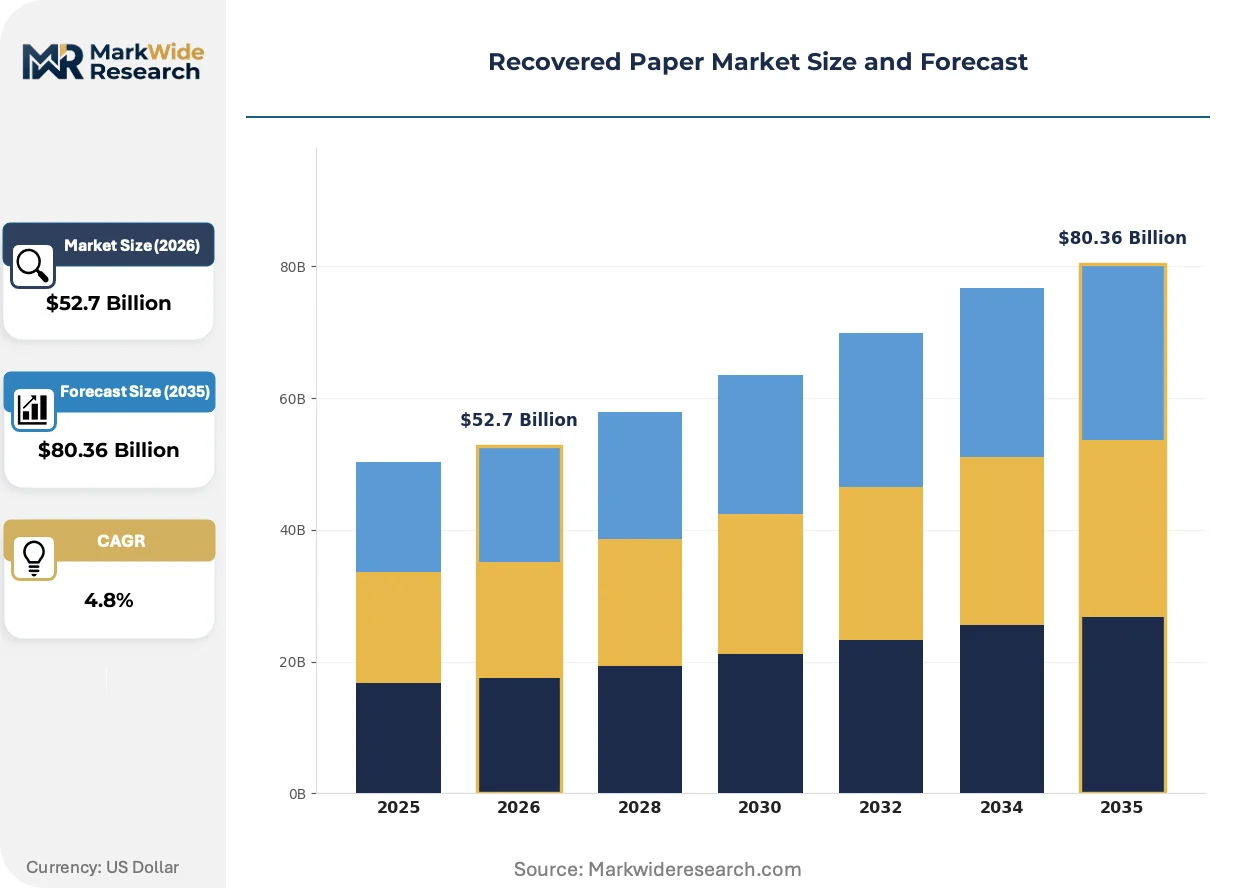
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Newsprint, Cardboard, Office Paper, Tissue End Use Industry: Packaging, Printing, Construction, Consumer Goods Collection Method: Curbside Collection, Drop-off Centers, Commercial Collection, Industrial Collection Recycling Process: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Biodegradable Processing |
| Companies Covered | Cascades, Nine Dragons Paper, Smurfit WestRock, Bio Pappel, Graphic Packaging International, International Paper Company, Georgia-Pacific, Stora Enso Oyj, Pratt Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recovered Paper Market Strategic Shifts
Recovered paper processing is bifurcating between high-volume mechanical systems serving packaging grades and emerging hybrid technologies targeting fiber preservation in contaminated streams. Equipment suppliers and mill operators are racing to align capital deployment with diverging end-product specifications.
Enzymatic fiber conditioning is displacing conventional alkaline de-inking for post-consumer cardboard processing. Smurfit WestRock and Pratt Industries are retrofitting select mill lines with enzyme-assisted pulping systems that reduce chemical load while maintaining strength properties. This technology is displacing capital-intensive flotation de-inking installations that dominated recovered paper preparation for the past three decades.
EPA guidelines under the Resource Conservation and Recovery Act are tightening contamination monitoring protocols for municipal recovery facilities. Facilities must now document rejected stream volumes and destination, creating audit trails that expose inefficient collection practices. Mixed-waste processors in the US Southeast are responding by investing in secondary optical sorting to pre-qualify fiber for containerboard mills.
Buyer consolidation among e-commerce fulfillment operators is compressing supplier qualification cycles for recovered paper contracts. Amazon and Flipkart are unbundling packaging procurement from logistics services, establishing direct fiber sourcing relationships that bypass traditional merchant converter networks. This pattern concentrates most visibly in India's Maharashtra and Karnataka warehouse clusters where domestic containerboard mills compete for dedicated supply agreements.
Recovered Paper Market Segmentation
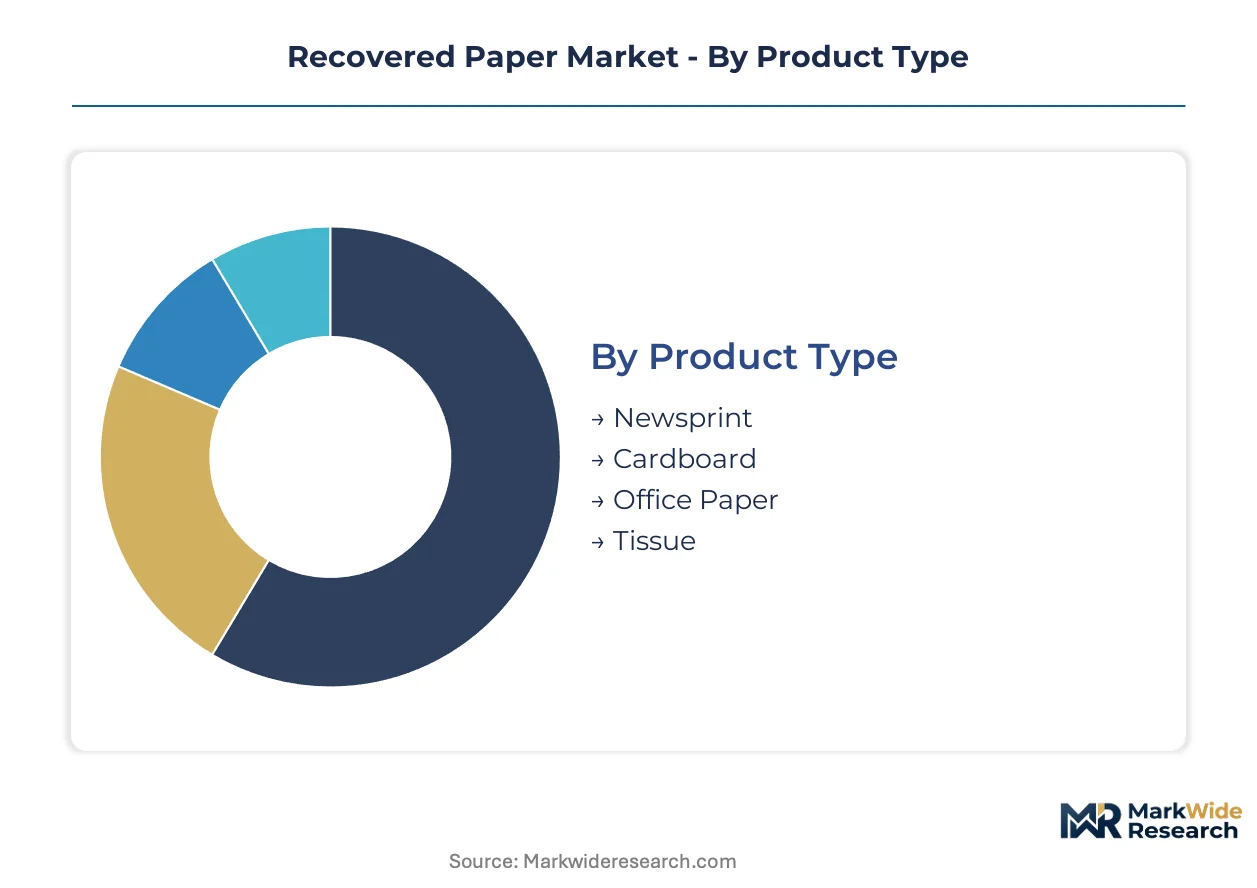
Recovered paper flows through distinct channels that shape fiber quality, pricing power, and mill compatibility. Segment boundaries determine which collectors capture premium margins and which processors absorb contamination risk.
Product Type:
Cardboard dominates export-led procurement from e-commerce fulfillment centers, while newsprint and office paper concentrate in domestic municipal streams with higher contamination exposure.
- Cardboard:Post-consumer corrugated fiber with longer strand retention and predictable volume flows from retail and logistics operations. Demand concentrates in India's western industrial corridor where Gujarat and Maharashtra containerboard mills compete for dedicated supply agreements against Scope 3 reporting requirements.
- Newsprint:Shorter cellulose fibers from de-inked newspaper with limited brightness recovery. Domestic procurement dominates as China's SAMR import bans eliminated historical export outlets, forcing US and European collectors into price-discounted local diversion or landfill absorption.
- Office Paper:High-brightness post-consumer fiber requiring chemical de-inking for graphic paper re-entry.
- Tissue:Lower-grade mixed fiber streams with sanitary contamination barriers limiting reprocessing pathways.
Cardboard commands the established base. The steepest expansion runs through office paper as enzymatic conditioning reduces chemical de-inking intensity.
End Use Industry:
Packaging absorbs volume at standard-grade pricing, while printing and consumer goods split between premium brightness specifications and economy-grade tolerance.
- Packaging:Containerboard and boxboard grades tolerating shorter fiber lengths and moderate contamination. Demand clusters in Asia-Pacific fulfillment networks where Smurfit WestRock and Pratt Industries anchor integrated mill-converter supply chains.
- Printing:Newsprint and graphic paper requiring de-inked pulp at specified brightness thresholds. Cost pressure intensifies as digital displacement compresses volume, leaving specialty catalog and direct mail as residual demand pockets.
- Construction:Gypsum linerboard and insulation-facing grades with lower fiber quality tolerance.
- Consumer Goods:Tissue and towel products with strict sanitary standards limiting post-consumer fiber inclusion.
Packaging retains volume leadership. Printing faces the sharpest structural compression as end-use digitization accelerates.
Collection Method:
Commercial and industrial channels concentrate in urban corridors with logistics efficiency, while curbside and drop-off fragmentation spreads contamination risk across rural feedstock.
- Commercial Collection:Direct cardboard recovery from retail, warehouse, and logistics operations with pre-sorted bale consistency. Pricing premiums reflect lower contamination rates and predictable volume commitments that satisfy mill procurement specifications.
- Curbside Collection:Mixed residential streams requiring municipal recovery facility sorting under EPA Resource Conservation and Recovery Act contamination monitoring. India's fragmented urban infrastructure strands semi-urban feedstock with uneconomic transport distances to nearest mill capacity.
- Drop-off Centers:Self-directed consumer deposit with highly variable quality control.
- Industrial Collection:Post-industrial trim and converting scrap with minimal contamination and direct mill return loops.
Commercial collection secures margin stability. Curbside infrastructure is expanding most quickly under municipal circular economy mandates.
Recycling Process:
Mechanical systems dominate capital deployment and throughput volume, while chemical and thermal alternatives occupy niche positions where fiber preservation or energy recovery justifies cost premiums.
- Mechanical Recycling:Pulping, screening, and cleaning without fiber dissolution, retaining strand length for strength-critical packaging grades. Smurfit WestRock and Pratt Industries are retrofitting enzyme-assisted variants that reduce chemical load while maintaining tensile properties.
- Chemical Recycling:De-inking and bleaching for high-brightness graphic paper with capital intensity confining deployment to specialty mills. Cost barriers limit adoption against mechanical alternatives except where India's BIS certification mandates heavy metal testing protocols.
- Thermal Recycling:Energy recovery from non-recyclable fiber fractions with declining regulatory tolerance.
- Biodegradable Processing:Composting pathways for contaminated streams rejected by fiber recovery systems.
Mechanical recycling holds installed capacity dominance. Chemical-mechanical hybrid processes are gaining share fastest as enzymatic conditioning opens previously rejected feedstock pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep-water port infrastructure at Ningbo-Zhoushan and Jawaharlal Nehru Port anchors Asia-Pacific fiber trade flows, while Rotterdam's automated container terminals mediate European recovered paper distribution to hinterland mills.
China
GB standards for recycled fiber content are tightening contamination thresholds for packaging board, forcing converters to requalify supply chains toward single-source cardboard collection. SAMR import quality enforcement has eliminated historical outlets for lower-grade mixed paper. Containerboard demand clusters in the Yangtze River Delta where domestic mills compete for post-consumer fiber against e-commerce fulfillment networks.
India
BIS certification requirements for heavy metal content in recycled packaging materials are accelerating pre-sorting infrastructure investment ahead of mandatory compliance deadlines. The western industrial corridor in Gujarat and Maharashtra concentrates domestic containerboard capacity expansion. Mumbai-Pune logistics networks enable localized procurement that undercuts import-dependent supply economics.
United States
EPA guidelines under the Resource Conservation and Recovery Act are tightening contamination monitoring protocols for municipal recovery facilities, forcing documentation of rejected stream volumes. Mixed-waste processors in the Southeast are investing in secondary optical sorting to pre-qualify fiber for containerboard mills. Georgia-Pacific and Pratt Industries anchor integrated mill-converter supply chains across the Gulf Coast and Southeast.
Germany
EU Green Deal circular economy mandates are accelerating commercial cardboard collection partnerships between packaging converters and retail logistics operators. REACH compliance requirements for recycled content traceability are reshaping procurement documentation standards. The Rhine-Ruhr industrial corridor concentrates de-inking capacity serving graphic paper producers with high-brightness specifications.
Brazil
ANVISA sanitary standards for food-contact packaging are limiting post-consumer fiber inclusion in tissue and towel products. São Paulo's urban commercial corridors concentrate cardboard collection infrastructure with lower contamination rates than fragmented curbside systems. Bio Pappel anchors integrated recycling-to-packaging operations serving Latin American e-commerce growth.
Recovered Paper Market Competitive Environment
Concentration sits with integrated containerboard producers who command captive recycling infrastructure. The market structure tiers between multinational scale players with mill-converter integration and regional collectors serving fragmented municipal streams. Three archetypes dominate: North American integrated producers with in-house recycling networks, Asia-Pacific volume leaders leveraging domestic fiber demand, and European sustainability-focused operators prioritizing circular certification. Competitive moves center on strategic partnerships with e-commerce fulfillment networks and capacity expansion in high-growth industrial corridors.
Within the integrated producer tier, Smurfit WestRock and Pratt Industries exemplify the North American archetype of mill-converter control over fiber supply chains. Nine Dragons Paper occupies a position representing Asia-Pacific volume scale. These three entities anchor competitive dynamics through their contrasting geographic footprints and integration depth.
| Leading Market Players |
|---|
| Cascades |
| Nine Dragons Paper |
| Smurfit WestRock |
| Bio Pappel |
| Graphic Packaging International |
| International Paper Company |
| Georgia-Pacific |
| Stora Enso Oyj |
| Pratt Industries |
| Others |
Value Chain & Pricing Dynamics
India's BIS certification for heavy metal content in recycled packaging materials gates both supply qualification and price differentiation simultaneously, forcing collectors to invest in pre-sorting infrastructure that separates certified-grade fiber from unqualified streams before mill delivery.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates recovered paper procurement. Premium tiers attach to certified low-contamination cardboard from commercial collection channels, while economy tiers absorb mixed municipal streams with higher rejection risk. Price differentiation rests on contamination rates and volume predictability, with commercial bales commanding substantial premiums over curbside alternatives. Pricing pressure stems from China's SAMR import bans eliminating historical export outlets for lower-grade fiber, forcing US and European collectors into discounted domestic diversion. Containerboard mills exhibit lowest price sensitivity due to integrated supply chains, while independent converters face margin compression from feedstock volatility.
Supply Chain Analysis
Inbound logistics costs from port congestion at Ningbo-Zhoushan and Jawaharlal Nehru Port reshape regional procurement economics, favoring localized collection networks over import-dependent supply. Raw material flows concentrate in the United States, China, and India as primary fiber generation hubs. Supply chains draw from post-consumer cardboard, de-inked newsprint, and office paper streams with varying contamination profiles. Single-source vulnerability runs through China's GB standard enforcement redirecting regional trade flows. Distribution runs through integrated mill-converter networks anchored by Smurfit WestRock and Pratt Industries, bypassing traditional merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recovered paper processing equipment and technical services represent a service-attach opportunity expanding faster than commodity fiber sales, as mills retrofit enzyme-assisted pulping systems and optical sorting infrastructure to meet tightening contamination standards.
For Market Incumbents: Secure dedicated supply agreements with e-commerce fulfillment networks before independent collectors capture last-mile cardboard streams. Lock in backward integration into municipal collection infrastructure to defend against regional supply concentration risk. Invest in enzymatic conditioning capacity ahead of BIS certification deadlines to capture premium pricing tiers.
For New Entrants and Emerging Players: Differentiate on pre-certified low-contamination bales targeting India's western industrial corridor containerboard mills. Target fragmented curbside collection in semi-urban India where logistics costs strand feedstock from existing mill networks. Pursue direct partnerships with Flipkart and Amazon reverse logistics operations as a go-to-market angle bypassing traditional merchant channels.
For Investors and Strategic Acquirers: India's BIS certification mandate reshapes the acquisition landscape toward collectors with pre-installed optical sorting and spectroscopy capabilities. The five-to-ten year viability window favors integrated processors over pure-play collectors as margin compression intensifies. Target acquisition archetypes include regional collectors with commercial channel density in urban logistics corridors. Monitor China's SAMR enforcement patterns as the signal to watch for directional shifts in export market accessibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Pulping Retrofit | Reduces chemical load while meeting GB strength specifications for packaging board. |
| Commercial Collection Partnership | Secures predictable volume flows from Amazon and Flipkart fulfillment networks. |
| BIS Pre-Certification Investment | Captures premium pricing tiers ahead of mandatory heavy metal testing deadlines. |
| Optical Sorting Infrastructure | Enables higher-grade fiber recovery from contaminated municipal streams. |
| Reverse Logistics Integration | Bypasses fragmented collection systems through point-of-delivery cardboard capture. |
Study Parameters
A spread of perspectives from containerboard mill procurement directors, municipal recovery facility operators, e-commerce logistics managers, and optical sorting equipment suppliers converged on the working assumptions underlying fiber demand projections. Primary fieldwork combined structured interviews with secondary validation through EPA contamination monitoring reports, China's SAMR import quality bulletins, India's BIS certification protocols, and trade flow data from Ningbo-Zhoushan and Jawaharlal Nehru Port authorities. Bottom-up volume modeling from individual mill capacity additions triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type, end-use industry, collection method, and recycling process across the projection horizon. The analytical framework applied growth rate derivation from historical capacity utilization patterns, regulatory compliance cost trajectories, and e-commerce packaging intensity metrics. Forecast inputs incorporated enzyme-assisted pulping adoption curves and BIS certification rollout timelines without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth, stable GB standard enforcement, and functional municipal collection infrastructure would require recalibration. Forecasts reflect documented assumptions regarding fiber substitution rates and contamination threshold tightening. Specific risk factors including China's SAMR policy reversals, India's logistics cost inflation, and enzymatic process scale-up failures could revise trajectory projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Latex-Saturated Paper Market
Paper Products
Americas Stone Paper Market
Paper Products
Overlay Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Filtration Paper Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
Thin Printing Paper Market
Paper Products
Billing Paper Market
Paper Products
Paper Glass Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Sawn Wood Market
Paper Products
Digital Printing Paper Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Thermal Paper Market
Paper Products
Stone Paper Market