
 Eco Flooring Market | 2026-2036
Eco Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Eco Flooring Market Foresight
Europe is narrowing its supply deficit for low-VOC adhesives and certified sustainable substrates. Forbo Holding leverages integrated linoleum manufacturing across the Netherlands and Switzerland to sustain premium positioning. Mohawk Industries anchors North American distribution through recycled-content carpet tile and rigid core capacity. Interface competes on closed-loop material flows and carbon-neutral product claims across commercial fit-outs.
Eco flooring comprises surface coverings engineered from renewable, recycled, or rapidly renewable raw materials with certified low embodied carbon and indoor air quality compliance, typically manufactured through hot-press lamination, calendaring, or woven fiber binding for durable residential and commercial installation. Bamboo flooring leads volume globally due to three-year harvest cycles and hardness ratings rivaling oak, while bio-based plastic segments capture margin pools through petroleum displacement and injection-molded interlocking systems. Reclaimed wood occupies niche premium positioning where LEED certification and heritage aesthetics command specification in luxury retail and hospitality.
The EU Green Deal and REACH chemical restrictions shape material eligibility across European markets, while the EPA's TSCA Title VI formaldehyde emissions standard governs composite wood products in the United States. California's CARB ATCM maintains the most stringent state-level thresholds, effectively setting the compliance floor for national distribution. Stakeholders must monitor evolving EPD requirements and bio-based content verification protocols as procurement specifications harden.
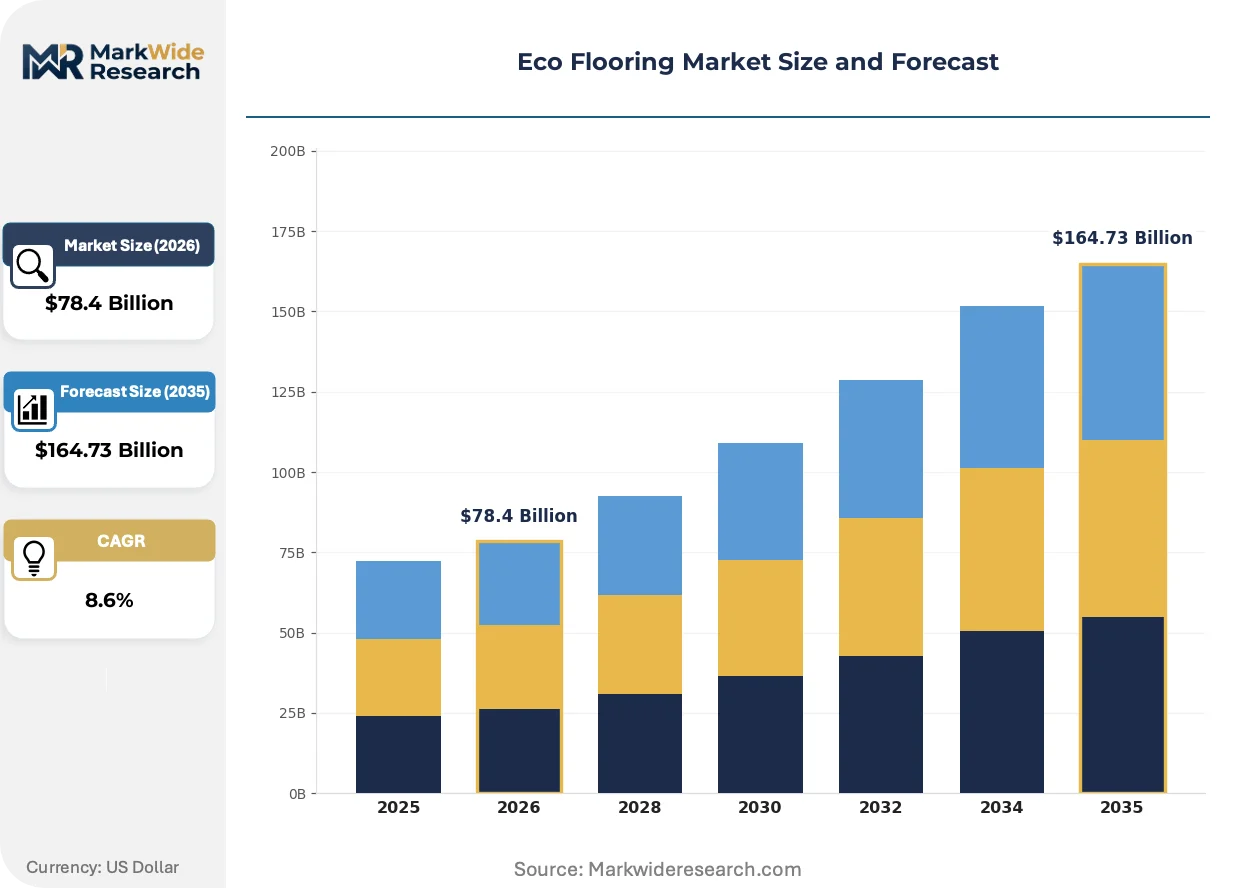
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandate is compressing specification timelines for construction products across European markets, forcing substrate suppliers to revalidate supply chains before Q3 procurement cycles close.
Growth Catalysts
- REACH chemical restrictions:France's hospitality renovation pipeline is accelerating specification of bio-based adhesives as legacy solvent systems face authorization sunset clauses. Project developers in Lyon and Marseille are front-loading orders to secure compliant material.
- Three-year bamboo harvest cycles:Residential builders in Germany are specifying rapidly renewable flooring at rates outpacing oak alternatives, driven by LEED v4.1 credit thresholds for rapidly renewable content. Munich and Frankfurt clusters show dense contractor adoption.
- California CARB ATCM:The state's formaldehyde emission thresholds have become the de facto national compliance floor for US distribution, creating uniform product standards that reduce SKU complexity for cross-border manufacturers.
Market Restraints
- Petroleum price volatility:Bio-based plastic flooring segments face margin compression when polyethylene feedstock costs spike, as petroleum displacement claims lose economic credibility during oil price troughs.
- Adhesive supply concentration:Low-VOC adhesive production clusters heavily in the Netherlands and Switzerland, creating geographic single-point-of-failure risk for linoleum and resilient flooring assemblers.
- Reclaimed wood volume ceiling:Heritage timber salvage operations cannot scale beyond niche premium positioning due to structural supply constraints from demolition permit timelines and deconstruction labor costs.
Strategic Opportunities
- CSRD reporting mandates:Large EU enterprises must disclose Scope 3 embodied carbon from 2025, creating procurement preference for Environmental Product Declaration-certified flooring among corporate real estate teams.
- Closed-loop material flows:Interface's carbon-neutral product claims demonstrate commercial viability for take-back programs, suggesting white space for competitors to establish similar reverse logistics in underpenetrated Nordic markets.
- Injection-molded interlocking systems:Bio-based rigid core flooring with click-lock installation is capturing renovation demand from DIY retail channels previously dominated by glue-down sheet vinyl.
Industry Challenges
- EPD verification timelines:Third-party embodied carbon certification for novel bio-based substrates requires 12-18 month validation cycles, delaying product launches past specification windows.
- Deconstruction labor scarcity:Reclaimed wood suppliers face skilled worker shortages for heritage timber salvage, limiting volume recovery rates from eligible demolition sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco Flooring Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bamboo Flooring, Cork Flooring, Reclaimed Wood, Linoleum Flooring Material: Natural Fiber, Bio-based Plastic, Recycled Rubber, Sustainable Wood Installation: Glue-down, Floating, Nail-down, Interlocking End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Forbo Holding, Armstrong Flooring, Mohawk Industries, Mannington Mills, Gerflor, Shaw Industries, Interface, Pergo, Tarkett, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco Flooring Market Shifts & Advancements
Digital specification tools and bio-based material science are compressing traditional product development cycles, while regulatory disclosure requirements force transparency through supply chain tiers previously opaque to buyers.
Digital twin modeling for embodied carbon calculation is rendering obsolete static lifecycle assessment spreadsheets that relied on industry-average emission factors. Commercial architects in Copenhagen and Stockholm are mandating real-time carbon tracking during design iterations. This capability compresses specification timelines from months to weeks for large-scale fit-outs.
The EU Green Deal's construction product regulation amendments are tightening material eligibility criteria across member states. Manufacturers must now submit verified bio-based content percentages to national databases before public procurement tender participation. German and French flooring assemblers are restructuring supplier qualification protocols to maintain bid eligibility.
Corporate sustainability officers are consolidating flooring procurement under master service agreements that bundle installation, maintenance, and end-of-life take-back. Facility management firms are displacing traditional distributor relationships with direct manufacturer contracts in the Netherlands and Belgium. This concentration shifts margin capture toward vertically integrated producers with captive recycling infrastructure.
Eco Flooring Market Segmentation
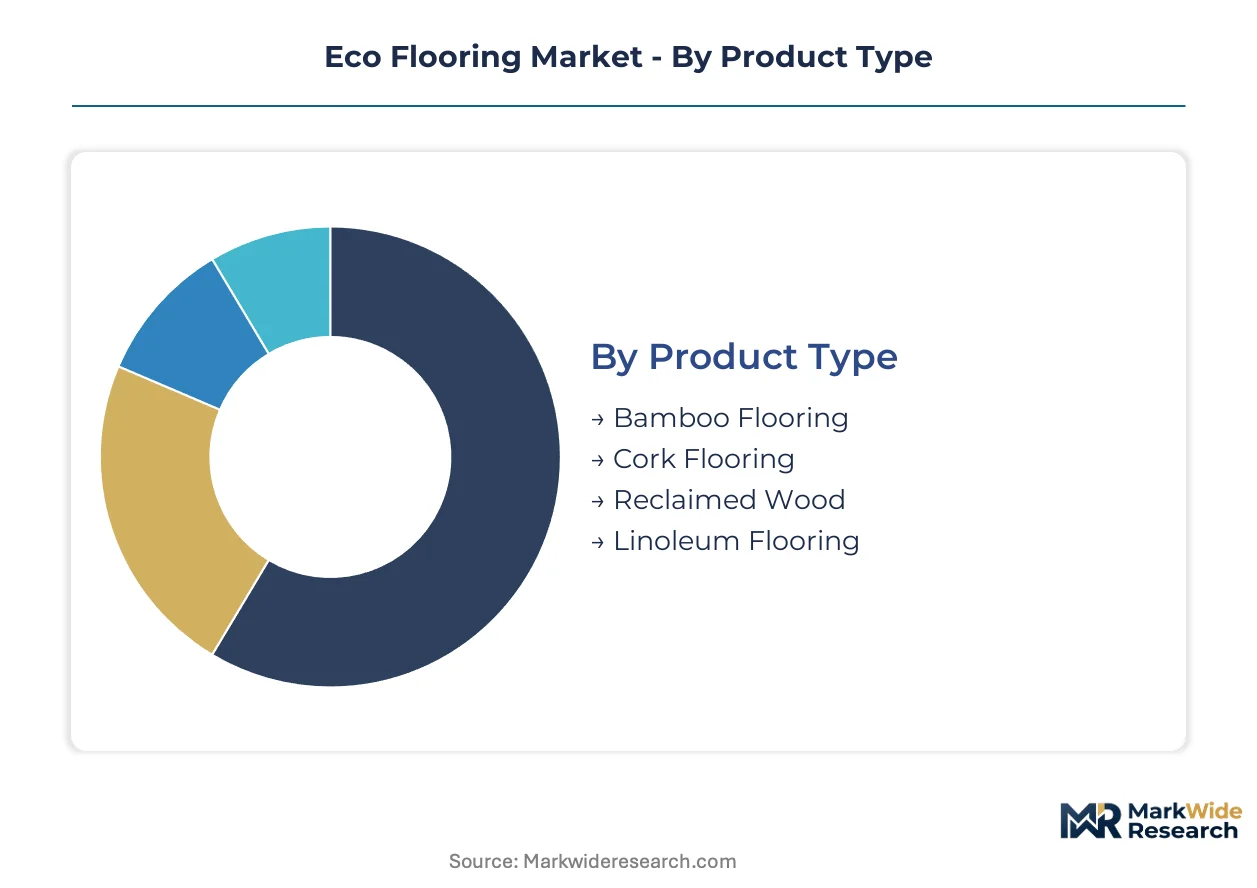
Eco flooring segmentation reveals divergent replacement cycles across product categories, with rapidly renewable materials commanding shorter specification windows than heritage salvage alternatives. Material composition and installation complexity further stratify procurement timelines and margin capture potential.
Product Type:
Bamboo and cork flooring turn inventory fastest due to three-year harvest cycles and straightforward manufacturing, while reclaimed wood and linoleum operate on extended timelines dictated by salvage logistics and oxidation curing requirements.
- Bamboo Flooring:Engineered from Moso bamboo harvested at three-year maturity, this segment delivers hardness ratings rivaling oak with significantly lower embodied carbon. Residential builders across Germany specify bamboo for LEED v4.1 rapid-renewable credits, compressing decision cycles to weeks rather than months.
- Linoleum Flooring:Composed of oxidized linseed oil, cork flour, and wood flour on jute backing, this material requires 3-4 week curing periods that extend manufacturer lead times. Forbo Holding's integrated Netherlands and Switzerland production sustains premium positioning as REACH solvent restrictions eliminate competing vinyl alternatives.
- Cork Flooring:Harvested from Quercus suber bark without tree destruction, offering natural acoustic dampening and thermal insulation.
- Reclaimed Wood:Heritage timber salvage from demolition sites, constrained by deconstruction permit timelines and skilled labor scarcity.
Bamboo flooring anchors the volume base while reclaimed wood gains share at the steepest rate among premium specification tiers.
Material:
Cost tier stratification separates commodity feedstocks from certified sustainable alternatives, with bio-based plastics commanding manufacturing premiums over natural fibers.
- Bio-based Plastic:Polyethylene derived from sugarcane or corn starch enables injection-molded interlocking systems with petroleum displacement claims. Margin pools concentrate here when oil prices elevate, though price volatility erodes credibility during crude troughs.
- Natural Fiber:Jute, sisal, and coir bindings provide woven surface coverings with minimal processing energy. Hospitality renovation pipelines in France favor these materials for biophilic design specifications.
- Recycled Rubber:Post-consumer tire crumb incorporated into resilient underlayments and athletic surfaces.
- Sustainable Wood:FSC-certified timber from managed forests with chain-of-custody documentation.
Natural fiber represents the fastest-growing trajectory in commercial fit-outs as CSRD disclosure mandates elevate bio-based content verification.
Installation:
Customer type divides the market between professional contractor dependence and DIY accessibility, with interlocking systems capturing renovation demand from previously adhesive-bound segments.
- Interlocking:Click-lock rigid core systems eliminate adhesive curing periods and skilled labor requirements. DIY retail channels in North American markets stock these configurations for homeowner self-installation.
- Glue-down:Full-spread adhesive application delivers superior acoustic performance and dimensional stability for commercial heavy-traffic zones.
- Floating:Laminate and engineered wood assemblies resting on underlayment without substrate attachment.
- Nail-down:Traditional solid wood tongue-and-groove fastening requiring plywood subfloor preparation.
Glue-down installation retains commercial specification dominance while interlocking methods expand most quickly in residential renovation.
End User:
Application-specific performance requirements differentiate procurement criteria, with hospitality and retail segments prioritizing aesthetic durability over residential cost sensitivity.
- Commercial:Office and institutional fit-outs demand Environmental Product Declaration certification for CSRD compliance. Corporate real estate teams in the Netherlands and Belgium consolidate procurement under master service agreements bundling installation and take-back.
- Hospitality:Hotel renovation pipelines in Lyon and Marseille accelerate bio-based adhesive specification as legacy solvent systems face REACH authorization sunset.
- Residential:Single-family and multi-family construction with LEED credit thresholds driving rapid-renewable material preference.
- Retail:Luxury storefront and flagship specifications commanding heritage aesthetic premiums for reclaimed wood.
Commercial end use anchors the volume base while hospitality gains share fastest as EU Green Deal embodied carbon disclosure compresses specification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated linoleum manufacturing concentrates in the Netherlands and Switzerland, while bamboo processing clusters in Zhejiang Province and Vietnam's northern highlands. Specification timelines compress fastest where EU Green Deal mandates intersect with active hospitality renovation pipelines.
United States
Residential builders in California and Texas specify rigid core flooring with recycled content for LEED v4.1 compliance. EPA's TSCA Title VI formaldehyde emissions standard governs composite wood products nationwide, though California's CARB ATCM maintains the most stringent thresholds. Dallas-Fort Worth contractors front-load orders to secure low-VOC adhesive supply before Q3 procurement cycles close.
Germany
Munich and Frankfurt clusters show dense contractor adoption of rapidly renewable flooring materials outpacing oak alternatives. The EU Green Deal mandates embodied carbon disclosure for construction products entering public procurement. Bavarian flooring assemblers restructure supplier qualification protocols to maintain bid eligibility under tightened material eligibility criteria.
France
Hotel renovation pipelines in Lyon and Marseille accelerate bio-based adhesive specification as legacy solvent systems face REACH authorization sunset clauses. Project developers front-load orders to secure compliant material before specification windows narrow. Île-de-France corporate real estate teams consolidate flooring procurement under master service agreements bundling installation and end-of-life take-back.
Netherlands
Facility management firms displace traditional distributor relationships with direct manufacturer contracts in Randstad urban corridors. CSRD reporting mandates from 2025 create procurement preference for Environmental Product Declaration-certified flooring among Dutch corporate real estate teams. Eindhoven-based linoleum producers sustain premium positioning as REACH solvent restrictions eliminate competing vinyl alternatives.
China
Zhejiang Province bamboo processors supply three-year harvest cycle raw material to global flooring assemblers. The country's dual carbon goals shape material eligibility for construction products entering public infrastructure procurement. Yangtze River Delta manufacturers invest in bio-based plastic injection-molded interlocking systems for export markets.
Eco Flooring Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified substrates and low-VOC adhesives. The vendor base separates into three tiers: multinational surface covering conglomerates with captive recycling infrastructure, mid-cap regional assemblers serving single-country procurement specifications, and niche heritage timber salvage operators. Dominant competitive moves include backward integration into bio-based raw material cultivation and strategic partnerships with facility management firms for master service agreement positioning.
Among European-based integrated manufacturers, Forbo Holding and Gerflor exemplify the platform integrator archetype with linoleum production spanning the Netherlands and Switzerland. Mohawk Industries anchors North American distribution capacity. Interface occupies a position demonstrating commercial viability for closed-loop material flows and carbon-neutral product claims across commercial fit-outs.
| Leading Market Players |
|---|
| Forbo Holding |
| Armstrong Flooring |
| Mohawk Industries |
| Mannington Mills |
| Gerflor |
| Shaw Industries |
| Interface |
| Pergo |
| Tarkett |
| Others |
Supply & Pricing Matrix
Single-source dependency on Netherlands and Switzerland low-VOC adhesive production compresses pricing tier spreads while forcing linoleum assemblers into premium positioning to offset geographic concentration risk. EU Green Deal embodied carbon disclosure mandates further stratify procurement costs between EPD-certified and uncertified substrate tiers.
Pricing Analysis
EU Green Deal embodied carbon disclosure mandates dictate the pricing tier structure across European specification markets. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified bio-based substrates from REACH-compliant alternatives and commodity vinyl replacements. Cost compression in the standard tier is intensifying because petroleum price volatility erodes bio-based plastic margin credibility during crude troughs. Residential DIY channels show highest price sensitivity, while corporate real estate teams in the Netherlands and Belgium demonstrate lowest sensitivity due to CSRD compliance bundling.
Supply Chain Analysis
Moso bamboo feedstock from Zhejiang Province and Vietnam's northern highlands anchors rapidly renewable flooring volume, while oxidized linseed oil and cork flour from Mediterranean suppliers sustains linoleum curing operations. Raw material flows hinge on three-year harvest cycle synchronization, REACH-authorized solvent availability, and FSC chain-of-custody documentation. Single-source vulnerability concentrates in low-VOC adhesive production clusters. Distribution runs through facility management direct contracts displacing traditional distributor relationships in Randstad urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
End-of-life take-back program bundling expands faster than hardware margins as corporate real estate teams consolidate flooring procurement under master service agreements covering installation, maintenance, and material recovery.
For Market Incumbents: Pre-empt bio-based rigid core displacement by anchoring captive recycling infrastructure in underpenetrated Nordic markets. Backward integration into Moso bamboo cultivation secures harvest cycle control against Zhejiang supply volatility. Certification investment in third-party EPD verification maintains bid eligibility as EU Green Deal procurement specifications harden. For New Entrants and Emerging Players: Establish a beachhead in hospitality renovation pipelines across Lyon and Marseille where REACH solvent sunset clauses accelerate bio-based adhesive specification. Heritage timber salvage operations in France offer white space for deconstruction labor arbitrage. Direct manufacturer contracts with facility management firms bypass entrenched distributor relationships in Belgium and the Netherlands. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors vertically integrated producers with captive recycling infrastructure. Long-term viability centers on carbon-neutral product claims validated through closed-loop material flows. Watch Nordic market penetration rates for Interface-style take-back program adoption as the inflection indicator for service-attach revenue scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstock Cultivation | Moso bamboo plantation control secures three-year harvest cycle supply against Zhejiang concentration risk. |
| EPD Certification Investment | Third-party embodied carbon verification maintains EU Green Deal public procurement bid eligibility. |
| Facility Management Direct Contracting | Randstad urban corridor consolidation displaces traditional distributor margin capture. |
| Closed-loop Take-back Program Launch | Carbon-neutral product claims demonstrate commercial viability across Copenhagen and Stockholm fit-outs. |
| Injection-molded Interlocking System Expansion | Click-lock rigid core captures DIY renovation demand from glue-down sheet vinyl channels. |
Research Methodology
The analysis maps bamboo flooring, linoleum, cork, and reclaimed wood segments, each validated through contractor procurement leads, facility management directors, and sustainability officers at corporate real estate teams. Primary interviews with flooring assemblers, adhesive suppliers, and demolition salvage operators combined with secondary validation from EU construction product databases, REACH authorization registries, and FSC chain-of-custody records. Bottom-up volume triangulation against top-down regulatory mandate sizing anchored the market framework.
Fixed assumptions held petroleum price volatility and EU Green Deal implementation timelines constant across the analysis window, while bio-based content verification protocols and CSRD disclosure adoption curves were varied. Segmentation dimensions modeled include product type, material composition, installation method, and end-user application. CAGRs derived from replacement cycle analysis and specification pipeline tracking. Industry-specific inputs encompassed LEED credit threshold evolution and hospitality renovation permit flows.
Stress conditions across crude oil price bands, REACH authorization sunset schedules, and deconstruction labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory enforcement consistency and bio-based feedstock harvest yields. Cross-checking against national construction product procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Solar Glass Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Green Rebar Market
Green Building Materials
Green Coatings Market
Green Building Materials
United States Green Cement Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Non-Residential Green Building Market
Green Building Materials
Global Green Walls Market