
 Asia-Pacific Solar Concentrator Market | 2026-2036
Asia-Pacific Solar Concentrator Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Solar Concentrator Market Analytics
CE marking under the EU Green Deal is redrawing competitive access for Asia-Pacific exporters targeting European offtake agreements. ACWA Power leverages its integrated project development model across Saudi Arabia and broader Middle East markets. Siemens Energy anchors its position through precision engineering in dual-axis tracking systems. BrightSource Energy competes on tower technology leadership with operational scale in utility deployments.
A solar concentrator harnesses mirrors or lenses to focus sunlight onto a receiver, achieving temperatures exceeding 400°C for thermal-electric conversion or industrial heat applications. The device relies on high-reflectivity silvered glass or aluminum substrates with tracking precision within 0.1 degrees to maintain optical efficiency. Parabolic troughs dominate installed capacity due to mature supply chains and proven bankability. Concentrated photovoltaic technology records the fastest expansion where high-direct-normal-irradiance sites in Australia and India justify premium module costs. Utility-scale installations capture the deepest margin pools through long-term power purchase agreements and economies in civil works.
India's Ministry of New and Renewable Energy enforces domestic content requirements under the PLI scheme that reshape component sourcing for foreign developers. Australia's Clean Energy Regulator issues large-scale generation certificates that monetize concentrated solar output for industrial buyers. Saudi Arabia's Energy Ministry sets localization targets that condition market access on joint ventures with domestic fabricators. Stakeholders must weigh technology specificity against policy durability as subsidy architectures evolve across jurisdictions.
Market Dynamics
China's dual carbon goals and India's PLI scheme for renewable manufacturing are restructuring procurement patterns across the Asia-Pacific solar concentrator value chain. These policy frameworks are forcing technology providers to localize fabrication and reconfigure supply partnerships.
Growth Catalysts
- Utility-scale electricity generation:Long-term power purchase agreements from industrial offtakers in Saudi Arabia and Australia provide revenue visibility that attracts project finance. Bankable contract structures reduce developer risk.
- India's PLI scheme:Domestic content requirements under this incentive program reshape component sourcing for foreign developers. Local manufacturing mandates accelerate in-country fabrication capacity.
- High-direct-normal-irradiance sites:Concentrated solar output in Australia's interior and India's Rajasthan region justifies premium tracking system investments. Superior resource quality improves project returns.
Market Restraints
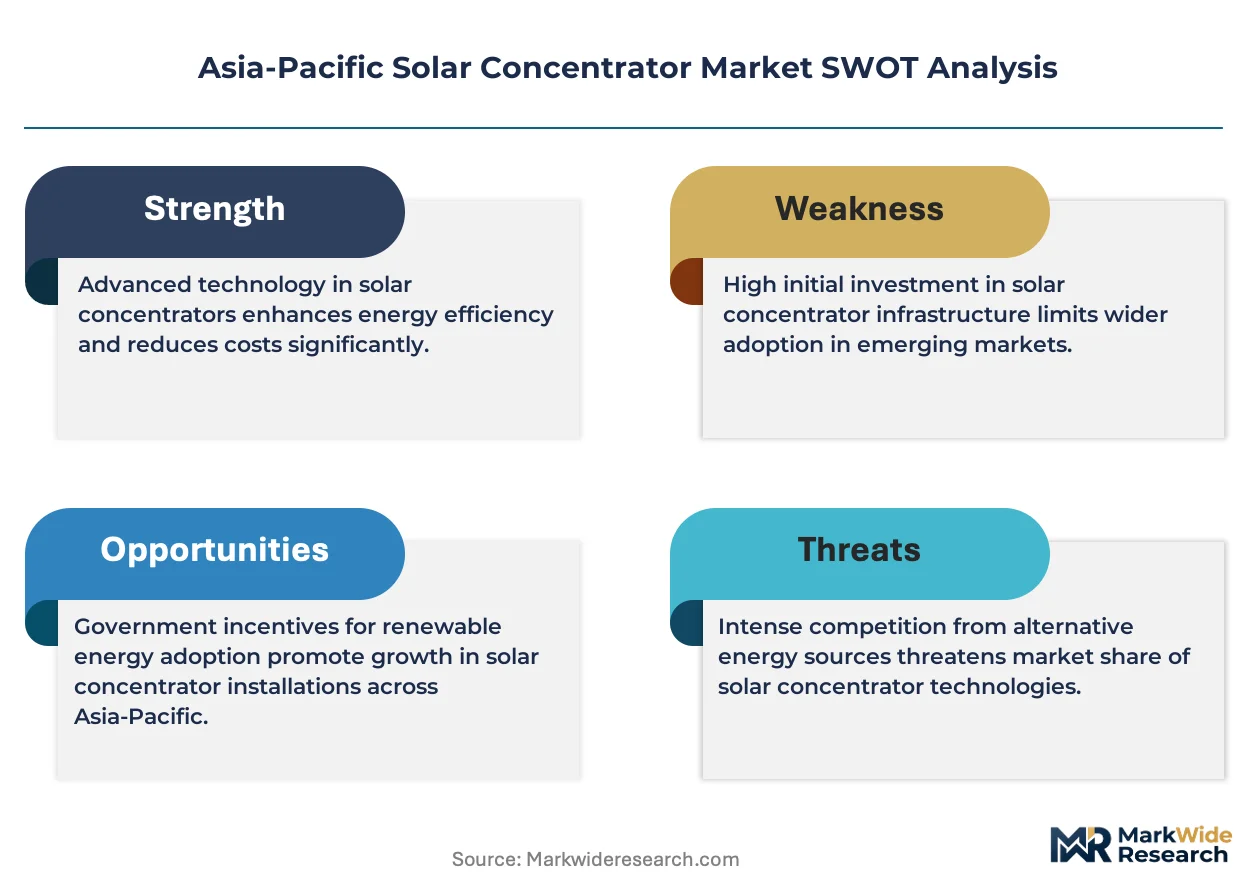
- Silvered glass supply concentration:High-reflectivity mirror substrates depend on limited metallurgical coating capacity concentrated in China. Input cost volatility compresses margins for trough and tower developers.
- Dual-axis tracking precision:Mechanical systems must maintain 0.1-degree accuracy under thermal cycling and wind loading. Technical limitations in bearing durability raise O&M cost projections.
- Saudi localization targets:Joint venture requirements with domestic fabricators condition market access. Regulatory friction extends project development timelines for foreign technology providers.
Strategic Opportunities
- Industrial process heat:Concentrated solar thermal above 400°C displaces fossil fuel in cement and chemical manufacturing. Emerging application segments in India and Australia offer first-mover positioning.
- Australia's large-scale generation certificates:This monetization mechanism for concentrated solar output creates a secondary revenue stream. Regulatory tailwind attracts corporate PPA offtakers.
- Concentrated photovoltaic hybrids:Technology convergence between thermal collection and high-efficiency PV cells opens dual-output configurations. Module suppliers can capture premium pricing in high-DNI zones.
Industry Challenges
- Precision alignment workforce:Installation and commissioning of dual-axis tracking systems requires specialized optical-mechanical technicians. Talent scarcity in Australia and Saudi Arabia extends construction schedules.
- CE marking compliance:European offtake agreements require conformity assessment under the EU Green Deal. Certification timeline uncertainty complicates export planning for Asia-Pacific fabricators.
- Legacy grid integration:Concentrated solar output variability challenges dispatch scheduling in India's state transmission networks. Integration complexity requires storage co-location or flexible gas backup.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Solar Concentrator Market |
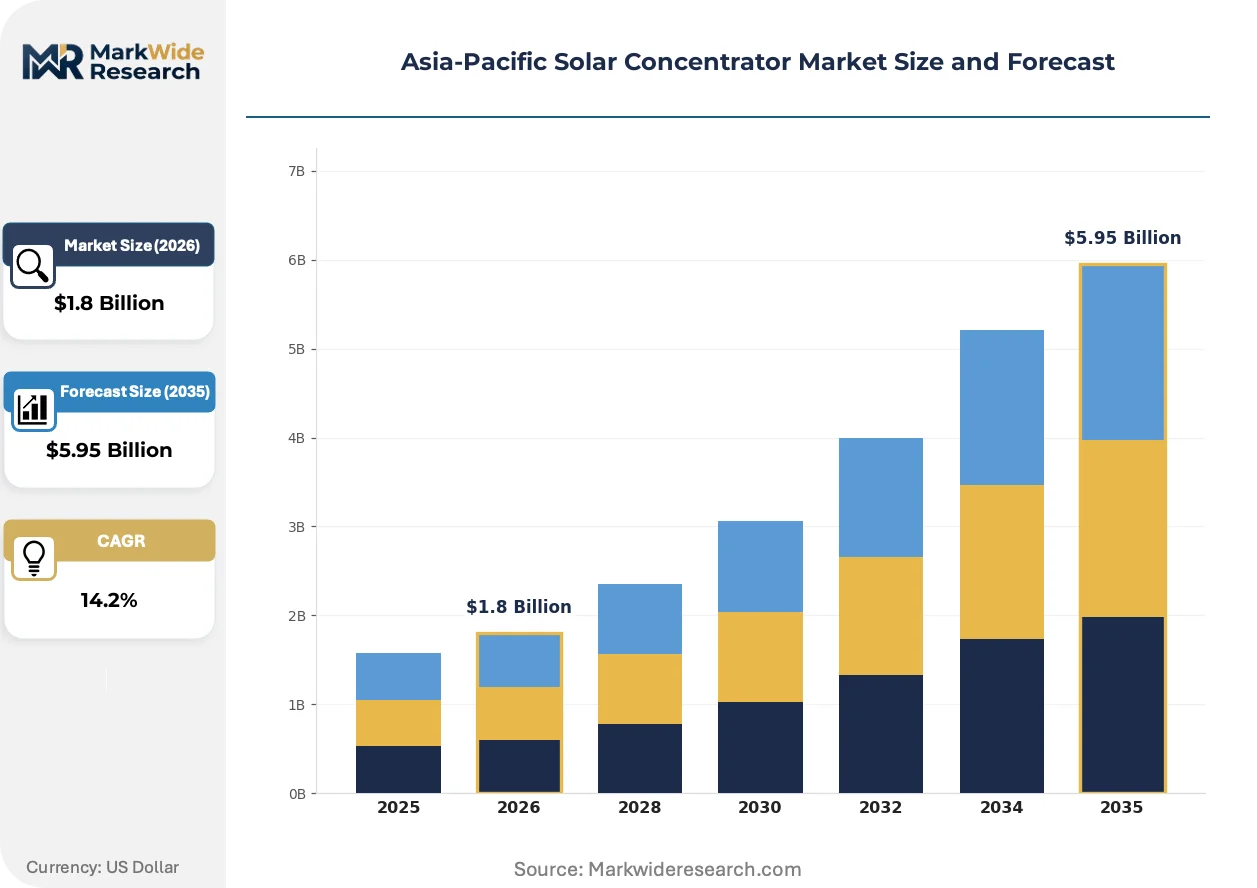
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresnel Reflectors, Parabolic Troughs, Dish Solar Collectors, Hybrid Systems Technology: Single Axis Tracking, Dual Axis Tracking, Fixed Tilt, Concentrated Photovoltaic Application: Electricity Generation, Water Heating, Industrial Processes, Desalination Size: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | ACWA Power, Abengoa Solar, BrightSource Energy, Siemens Energy, Acciona, Aalborg CSP, Enel Green Power, Torresol Energy, TSK Flagsol Engineering, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Solar Concentrator Market Evolving Landscape
Tower technology configurations and molten salt storage integration are reshaping competitive differentiation in utility-scale deployments. Advanced tracking algorithms and receiver designs are compressing LCOE benchmarks.
Molten salt thermal storage is fragmenting project development economics by decoupling generation from irradiance availability. Saudi developers are adopting this configuration for 24-hour dispatch capability. The technology is fragmenting traditional PV-plus-battery project comparisons by offering longer duration at lower incremental cost.
India's Central Electricity Authority mandates renewable purchase obligations that escalate annually for distribution licensees. This regulatory pressure forces state utilities to contract concentrated solar capacity. Western and southern states with superior DNI resources are accelerating procurement to meet compliance deadlines.
Industrial buyers in Australia are unbundling engineering-procurement-construction contracts from long-term O&M agreements. This procurement model change allows specialist operators to bid separately on plant performance guarantees. Mining and minerals processing verticals in Western Australia are driving this segmentation to optimize lifecycle cost accountability.
Asia-Pacific Solar Concentrator Market Segmentation
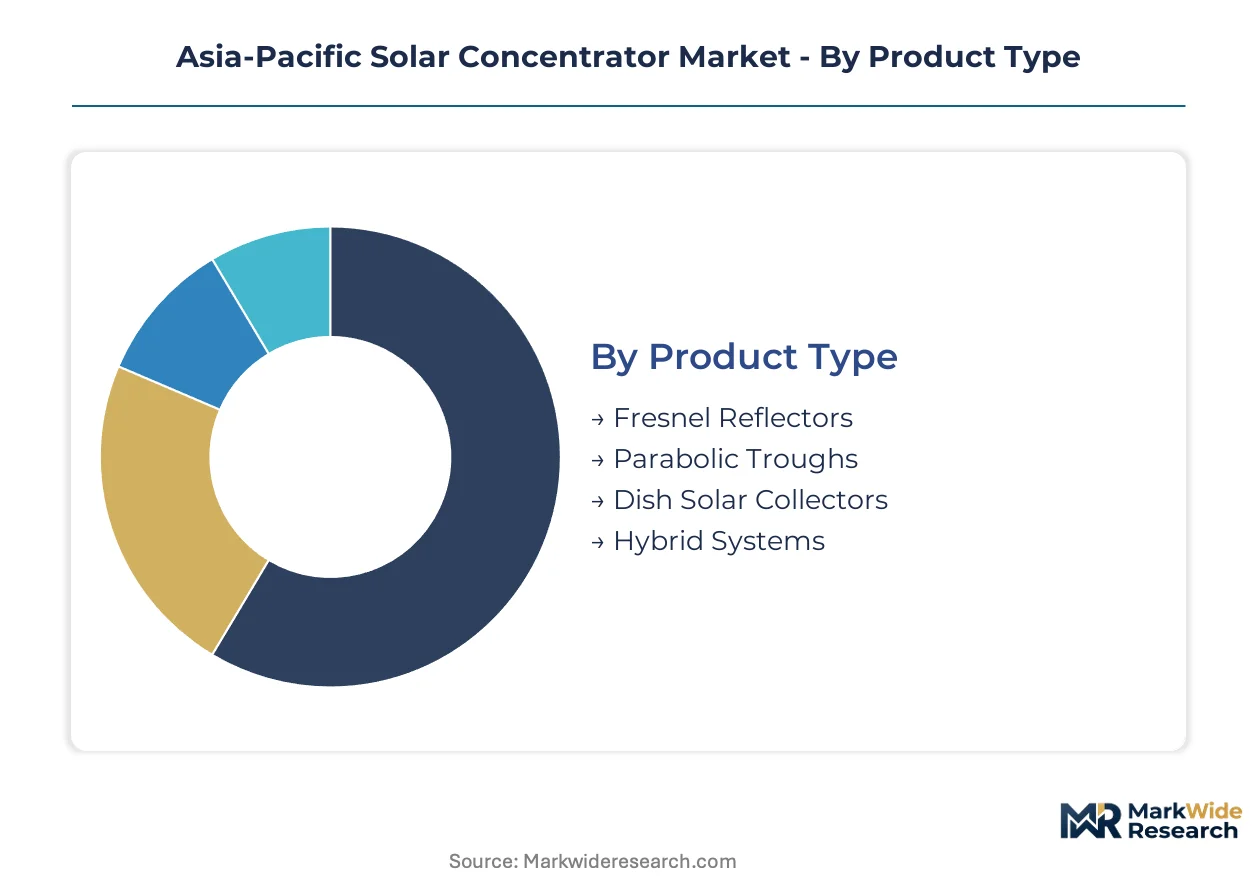
Technology and application boundaries in the Asia-Pacific solar concentrator market are blurring as developers optimize for specific irradiance conditions and offtake contract structures. Segmentation clarity determines procurement channel selection and project finance access.
Product Type:
Parabolic troughs flow through established EPC channels with proven bankability, while emerging configurations require direct manufacturer engagement.
- Parabolic Troughs:These systems employ silvered-glass reflectors in linear configurations to heat thermal transfer fluid above 390°C. Demand concentrates in India's Rajasthan and Saudi Arabia's Tabuk region where linear fields integrate with molten salt storage for dispatchable output.
- Fresnel Reflectors:Flat mirror arrays with secondary concentrators achieve comparable temperatures at reduced wind loading and structural cost. Australian developers in New South Wales are adopting this architecture for industrial process heat applications requiring steam generation.
- Dish Solar Collectors:Point-focus systems with Stirling engines suit remote off-grid installations in Australia's interior.
- Hybrid Systems:Combined thermal and photovoltaic collection addresses load-following requirements in India's western states.
By volume, Parabolic Troughs leads. By growth pace, Hybrid Systems is climbing the fastest.
Technology:
Tracking precision requirements create cost tier differentiation between mature mechanical systems and advanced control architectures.
- Dual Axis Tracking:Two-degree-of-freedom positioning maintains 0.1-degree optical alignment accuracy across diurnal and seasonal sun paths. High-direct-normal-irradiance sites in Australia's Pilbara and India's Gujarat justify the 15-20% capital premium through enhanced capacity factors.
- Concentrated Photovoltaic:Multi-junction cells under Fresnel lenses convert 40% of incident radiation to electricity. Premium module costs find offtakers in Saudi Arabia's NEOM development and Australian mining camps where diesel displacement economics are compelling.
- Single Axis Tracking:East-west rotation dominates trough installations where cost optimization outweighs peak efficiency.
- Fixed Tilt:Stationary concentrator designs serve low-temperature thermal applications in India's distributed solar thermal programs.
By installed base, Single Axis Tracking dominates. By margin expansion, Concentrated Photovoltaic is gaining share fastest.
Application:
End-use thermal specifications determine receiver design and working fluid selection across procurement channels.
- Electricity Generation:Rankine cycle conversion at 540°C turbine inlet temperature requires tower or trough configurations with molten salt storage. Saudi Arabia's ACWA Power and Indian developers under CEA renewable purchase obligations anchor procurement volumes.
- Industrial Processes:Steam generation at 150-400°C displaces natural gas in cement kilns and chemical processing. Australian minerals processors in Western Australia are contracting concentrated solar thermal for calcination and leaching operations.
- Water Heating:Low-temperature flat-plate and evacuated tube collectors serve residential and commercial demand across India.
- Desalination:Multi-effect distillation driven by solar thermal addresses water scarcity in Saudi Arabia's coastal regions.
By project count, Electricity Generation leads. By contract value acceleration, Industrial Processes shows the steepest expansion trajectory.
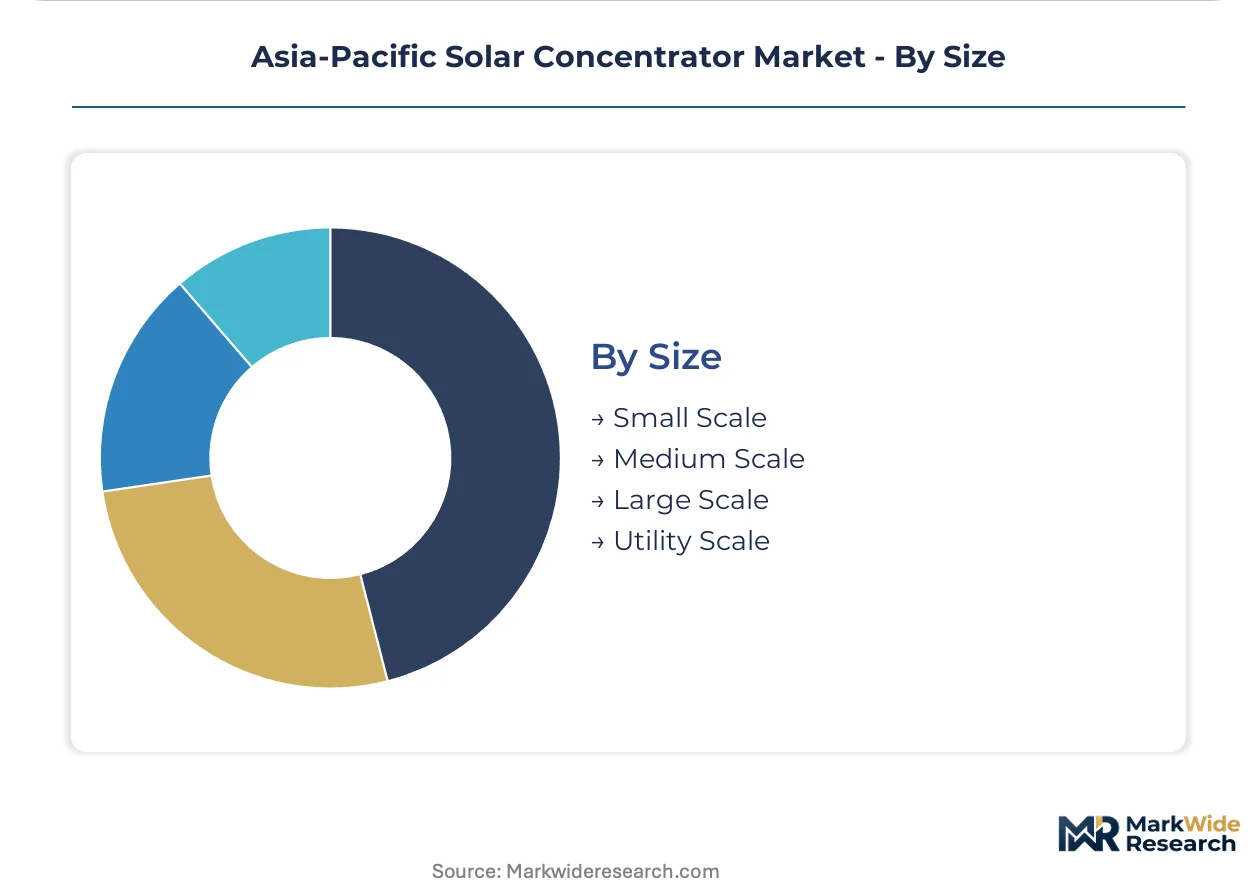
Size:
Scale thresholds gate access to power purchase agreement tenors and development finance structures.
- Utility Scale:Installations exceeding 50 MW capacity secure 25-year power purchase agreements with sovereign offtakers. India's SECI tenders and Saudi Arabia's PIF-backed projects concentrate procurement through competitive auctions with domestic content requirements.
- Large Scale:10-50 MW developments serve industrial captive power and merchant exposure strategies. Australian mining operators in Queensland and Western Australia favor this scale for behind-the-meter configurations.
- Medium Scale:1-10 MW systems address commercial and institutional loads with limited grid interconnection.
- Small Scale:Sub-MW installations serve distributed process heat and rural electrification in India's off-grid segments.
By capital deployment, Utility Scale dominates. By project initiation rate, Large Scale is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qinghai-Tibet grid interconnector underwrites China's transmission capacity for high-altitude solar thermal projects. Saudi Arabia's Red Sea coastal corridor hosts concentrated solar towers feeding industrial zones. Australia's Nullarbor rail link enables component logistics to interior high-DNI sites.
China
Domestic mirror manufacturing scales through metallurgical coating capacity in Jiangsu and Shandong provinces. The dual carbon goals mandate renewable procurement quotas for state grid operators. Dunhuang in Gansu province anchors tower deployments with molten salt storage integration for 24-hour dispatch.
India
Rajasthan's Bhadla solar park concentrates trough installations under SECI auction mechanisms. The PLI scheme enforces domestic content requirements for cells and modules that reshape foreign developer sourcing. Gujarat's Kutch district hosts hybrid thermal-PV configurations serving western state utilities under CEA renewable purchase obligations.
Saudi Arabia
ACWA Power's integrated development model leverages sovereign offtake guarantees for utility-scale towers. The Energy Ministry's localization targets condition market access on joint ventures with domestic fabricators. NEOM's northwest corridor attracts concentrated photovoltaic deployments for mining camp electrification and desalination feedstock.
Australia
Western Australia's Pilbara minerals processors contract concentrated solar thermal for calcination operations displacing diesel. The Clean Energy Regulator's large-scale generation certificates monetize output for corporate PPA offtakers. New South Wales developers adopt Fresnel reflector architectures for industrial steam generation in the Hunter Valley.
Japan
Island grid constraints in Kyushu drive interest in molten salt storage for dispatchable renewable capacity. METI's feed-in tariff adjustments favor technologies with storage co-location. Nagasaki prefecture hosts demonstration trough installations supplying process heat to regional manufacturing clusters.
Asia-Pacific Solar Concentrator Market Competitive Landscape
Listed leaders compete with private specialists across project development and precision engineering capabilities. The vendor base stratifies between integrated utilities, technology licensors, and component fabricators with distinct risk-return profiles. Scale-driven developers anchor procurement through sovereign offtake relationships; precision engineering specialists capture margin in tracking systems and receiver design. Dominant competitive moves include strategic partnerships with domestic fabricators and technology licensing for localized manufacturing.
Within the integrated developer tier, ACWA Power and BrightSource Energy exemplify project origination capabilities spanning multiple high-DNI geographies. Siemens Energy occupies a position among precision engineering specialists, with dual-axis tracking systems representing a technical differentiation vector. These three anchors illustrate how competitive positioning fragments across development risk, manufacturing precision, and technology licensing rather than consolidating around unified platform strategies.
| Leading Market Players |
|---|
| ACWA Power |
| Abengoa Solar |
| BrightSource Energy |
| Siemens Energy |
| Acciona |
| Aalborg CSP |
| Enel Green Power |
| Torresol Energy |
| TSK Flagsol Engineering |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for silvered-glass mirror substrates concentrate procurement leverage with Chinese metallurgical coaters, amplifying pricing power for trough and tower developers facing input cost volatility. This lead-time exposure tightens margins across India's PLI-mandated domestic content requirements and Saudi Arabia's localization-conditioned project finance.
Pricing Analysis
Volume-discount tiering structures separate utility-scale developers securing 25-year power purchase agreements from industrial captive power buyers at 10-50 MW scale. Pricing stratifies across premium dual-axis tracking systems, standard single-axis trough configurations, and economy fixed-tilt thermal collectors. Cost compression in standard tiers intensifies as Chinese mirror exports face CE marking compliance timelines for European offtake agreements. Utility-scale offtakers in Saudi Arabia and India exhibit lowest price sensitivity due to sovereign guarantee structures, while Australian mining operators at large scale drive hardest bargain on lifecycle cost accountability.
Supply Chain Analysis
China and India anchor silvered-glass mirror fabrication and steel structural component production respectively. The supply chain draws from high-reflectivity metallurgical coating capacity concentrated in Jiangsu and Shandong provinces, thermal transfer fluid formulators in Gujarat, and precision bearing manufacturers in Japan. Single-source vulnerability in silvered-glass substrates exposes developers to commodity price volatility in metallurgical-grade silver. Distribution runs through integrated EPC contractors for parabolic troughs and direct manufacturer engagement for emerging Fresnel and tower configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where molten salt storage interoperability is fragmenting traditional PV-plus-battery comparisons and creating new ecosystem lock-in dynamics around 24-hour dispatch capability.
For Market Incumbents: Fortify positions through backward integration into precision bearing and tracking control manufacturing to offset single-source vulnerability in Japanese mechanical component supply. Anchor procurement relationships with Saudi sovereign wealth-backed developers before localization mandates harden joint venture requirements. Prioritize CE marking certification investment to secure European offtake agreement eligibility as the EU Green Deal reshapes export access. For New Entrants and Emerging Players: Lead with industrial process heat applications in Australia's Western Australia minerals processing corridor where diesel displacement economics justify premium concentrated solar thermal configurations. Target 150-400°C steam generation for cement calcination and chemical leaching operations as the most penetrable white space. Pursue unbundled O&M contracting models that separate performance guarantees from EPC delivery to capture lifecycle accountability premiums. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility hybrid play because molten salt storage integration creates irreversible asset specificity and captive offtake relationships spanning decades. Acquire precision engineering specialists with dual-axis tracking system IP and demonstrated 0.1-degree alignment accuracy under thermal cycling stress. Watch Saudi PIF project auction participation rates as the inflection signal for utility-scale deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Molten Salt Storage Integration | Decouples generation from irradiance availability for 24-hour dispatch capability in Saudi tower deployments. |
| Domestic Content Compliance | India's PLI scheme forces foreign developers to localize fabrication or forfeit auction eligibility under SECI tenders. |
| CE Marking Certification | EU Green Deal conformity assessment gates European offtake agreement access for Asia-Pacific mirror fabricators. |
| Industrial Process Heat Expansion | Australia's Western Australia mining operators contract concentrated solar thermal for calcination diesel displacement. |
| Precision Tracking System Licensing | Technology transfer agreements enable Saudi joint ventures to meet localization targets while accessing proprietary control algorithms. |
Research Methodology
Desk research of IEA renewable technology roadmaps, FERC interconnection queue filings, and project development databases preceded structured interviews with IPP project developers, EPC contractors, utility planning officers, and molten salt storage specialists. Primary fieldwork captured procurement decision criteria across India's SECI auction mechanisms, Saudi PIF-backed tender processes, and Australia's Clean Energy Regulator certificate monetization structures. Secondary validation drew from customs trade data on silvered-glass mirror substrates, SEC filings of listed energy developers, and bottom-up capacity aggregation triangulated against top-down regulatory mandate analysis.
Variance-decomposition framing isolates technology cost trajectory, policy durability, and grid integration complexity as the three primary uncertainty sources across the projection horizon. The analytical framework models segmentation across technology type, tracking architecture, application thermal specification, and project scale tier. CAGRs derive from installed capacity buildout curves weighted by regional regulatory enforcement probability and DNI resource quality scores. Forecast inputs incorporate molten salt storage cost learning curves and dual-axis tracking system reliability improvements under desert operating conditions.
The analysis sits within stated boundaries; outcomes outside sustained sovereign offtake guarantee availability, silver price stability, or grid interconnection investment continuity would require recalibration. Forecasts reflect documented assumptions regarding policy durability across India's PLI scheme renewal cycles and Saudi localization target phase-ins. Recalibration cycles align with material shifts in renewable purchase obligation enforcement intensity and molten salt storage technology cost breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Solar Thermal Market