
 Solar District Heating Market | 2026-2036
Solar District Heating Market Size, Share, and Industry Trends Forecast 2026-2036
Solar District Heating Market Analysis
Qualified solar thermal engineer availability is collapsing across Central Europe, constraining project execution timelines for utilities and municipalities. Arcon-Sunmark leverages its Danish manufacturing footprint to anchor procurement contracts across Scandinavia. Viessmann competes through integrated control systems that bridge solar collector fields with conventional boiler infrastructure. Bosch Thermotechnology sustains R&D intensity in flat-plate collector coatings, differentiating on frost-resistant absorber technology.
Solar district heating denotes centralized thermal energy systems that capture solar irradiance through large-scale collector arrays, typically operating at 80–120°C supply temperatures with seasonal pit or tank storage to bridge summer production and winter demand. The technology displaces fossil peaking in legacy district heating grids while integrating with biomass, heat pumps, or waste heat streams. Thermal storage systems dominate installed capacity due to their role in load shifting and grid stability, though hybrid configurations combining solar fields with heat pumps represent the fastest-expanding segment as operators seek year-round renewable coverage. Flat-plate technology leads the collector category on cost and durability metrics, while vacuum tube systems occupy premium niches in high-latitude installations where diffuse irradiance conditions demand superior efficiency.
Denmark's national energy regulator enforces renewable heat quotas that mandate solar thermal shares in new district heating capacity, while EU Ecodesign standards under the F-Gas Regulation shape equipment specifications for integrated heat pump components. Germany's BImSchG federal emission control act restricts fossil boiler replacements, channeling municipal investment toward solar-compatible district infrastructure. Stakeholders must monitor evolving storage cost curves and heat pump coefficient-of-performance thresholds to calibrate technology mix decisions in upcoming procurement cycles.
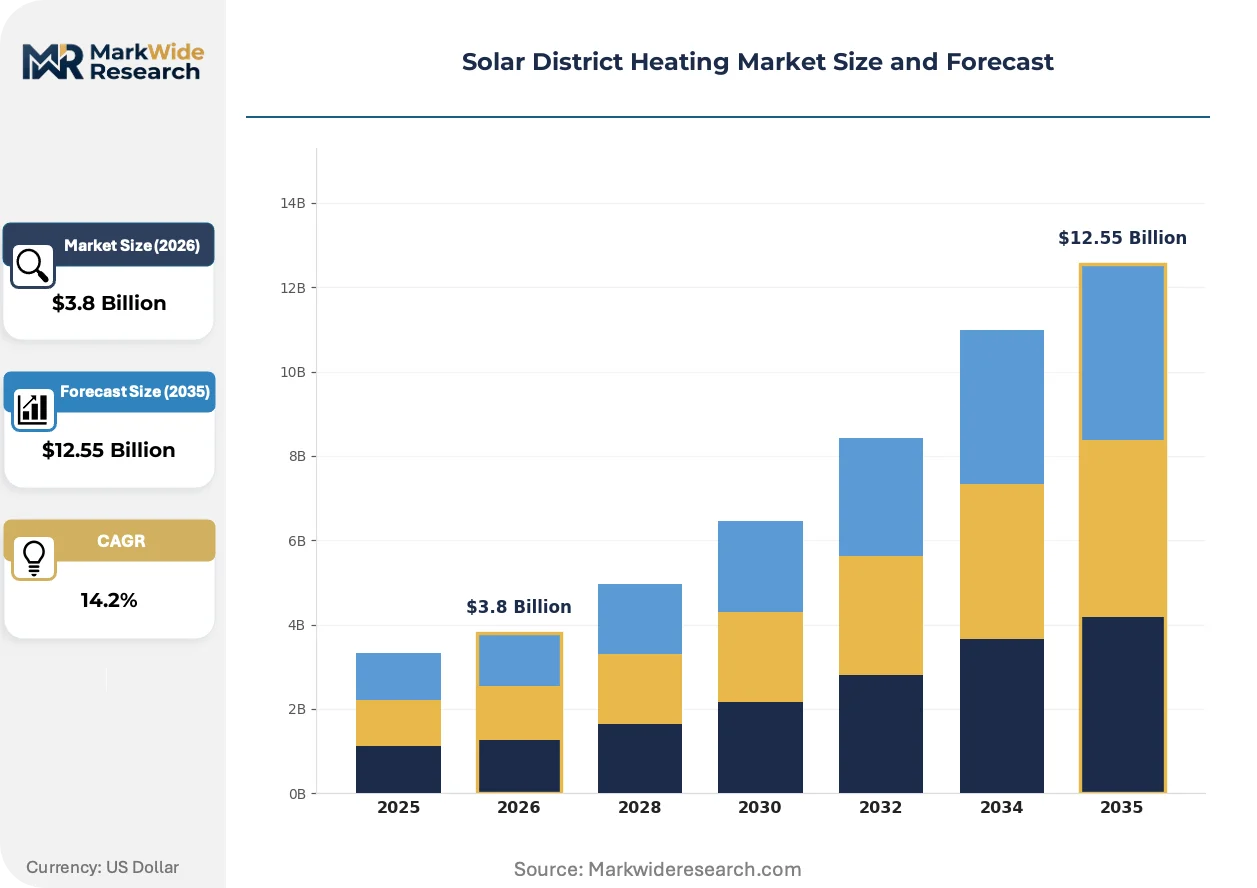
Market Dynamics
Denmark's F-Gas Regulation alignment with EU phase-down mandates is compressing project timelines for hybrid solar-thermal installations across Northern European municipal grids.
Growth Catalysts
- EU Ecodesign Standards:Denmark's national energy regulator enforces renewable heat quotas mandating solar thermal shares in new district heating capacity, directing municipal procurement toward collector arrays.
- Biomass Plant Retrofits:District energy operators in Denmark's Triangle Region around Silkeborg and Aarhus are retrofitting existing biomass infrastructure with solar thermal fields to displace fossil peaking.
- Heat Pump Convergence:F-Gas Regulation phase-down timelines are accelerating heat pump integration into hybrid solar thermal networks, creating year-round renewable coverage.
Market Restraints
- Engineer Supply Bottleneck:Qualified solar thermal engineer availability is collapsing across Central Europe, constraining project execution timelines for utilities and municipalities.
- Storage Capital Intensity:Seasonal pit and tank storage systems require substantial upfront capital deployment, limiting adoption among smaller district heating cooperatives.
- Heat Pump Substitution:Standalone heat pump installations compete for the same municipal capex allocations, particularly in jurisdictions with weaker solar thermal mandates.
Strategic Opportunities
- German BImSchG Channel:Germany's federal emission control act restricts fossil boiler replacements, channeling municipal investment toward solar-compatible district infrastructure.
- Vacuum Tube Premium Niche:High-latitude installations across Scandinavia present demand for vacuum tube systems where diffuse irradiance conditions require superior collector efficiency.
- Hybrid Configuration Growth:Solar fields combined with heat pumps represent the fastest-expanding segment as operators seek dispatchable renewable thermal supply.
Industry Challenges
- Absorber Coating Certification:Frost-resistant absorber technology requires extended validation cycles under EU Ecodesign protocols, delaying product commercialization.
- Legacy Grid Integration:Retrofitting solar thermal fields into existing district heating infrastructure demands complex hydraulic rebalancing and control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar District Heating Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Thermal Storage, Combined Heat and Power, Heat Pump, Hybrid System Heat Source: Solar Collectors, Biomass, Waste Heat, Geothermal Application: Residential, Commercial, Industrial, Community Technology: Flat Plate, Vacuum Tube, Concentrated Solar, PVT |
| Companies Covered | Arcon-Sunmark, Viessmann, Bosch Thermotechnology, Danfoss, Savosolar, Alfa Laval, LOGSTOR, Göteborg Energi, Solvis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar District Heating Market Emerging Trajectories
Large-scale collector arrays are displacing conventional boiler infrastructure across Northern European municipal grids, reshaping procurement patterns and vendor competitive dynamics.
Flat-plate collector technology dominates installed capacity on cost and durability metrics, with Danish manufacturing footprints anchoring procurement contracts across Scandinavia. Municipal housing authorities specify these systems for 80–120°C supply temperature networks. Vacuum tube systems are displacing flat-plate configurations in premium high-latitude niches where diffuse irradiance demands superior efficiency.
The EU F-Gas Regulation is compressing deployment timelines for hybrid solar-thermal systems by mandating heat pump integration into new district heating capacity. Equipment specifications for integrated components now face stricter coefficient-of-performance thresholds. Denmark's Triangle Region operators are responding by front-loading solar field procurement to secure heat pump allocation slots.
Municipal procurement is consolidating around integrated control systems that bridge solar collector fields with conventional boiler infrastructure. Engineering firms and utilities are unbundling after-sales service contracts from initial equipment supply, favoring vendors with captive software capabilities. This pattern concentrates in Denmark and Germany where district heating cooperatives possess technical staffing depth.
Solar District Heating Market Segmentation
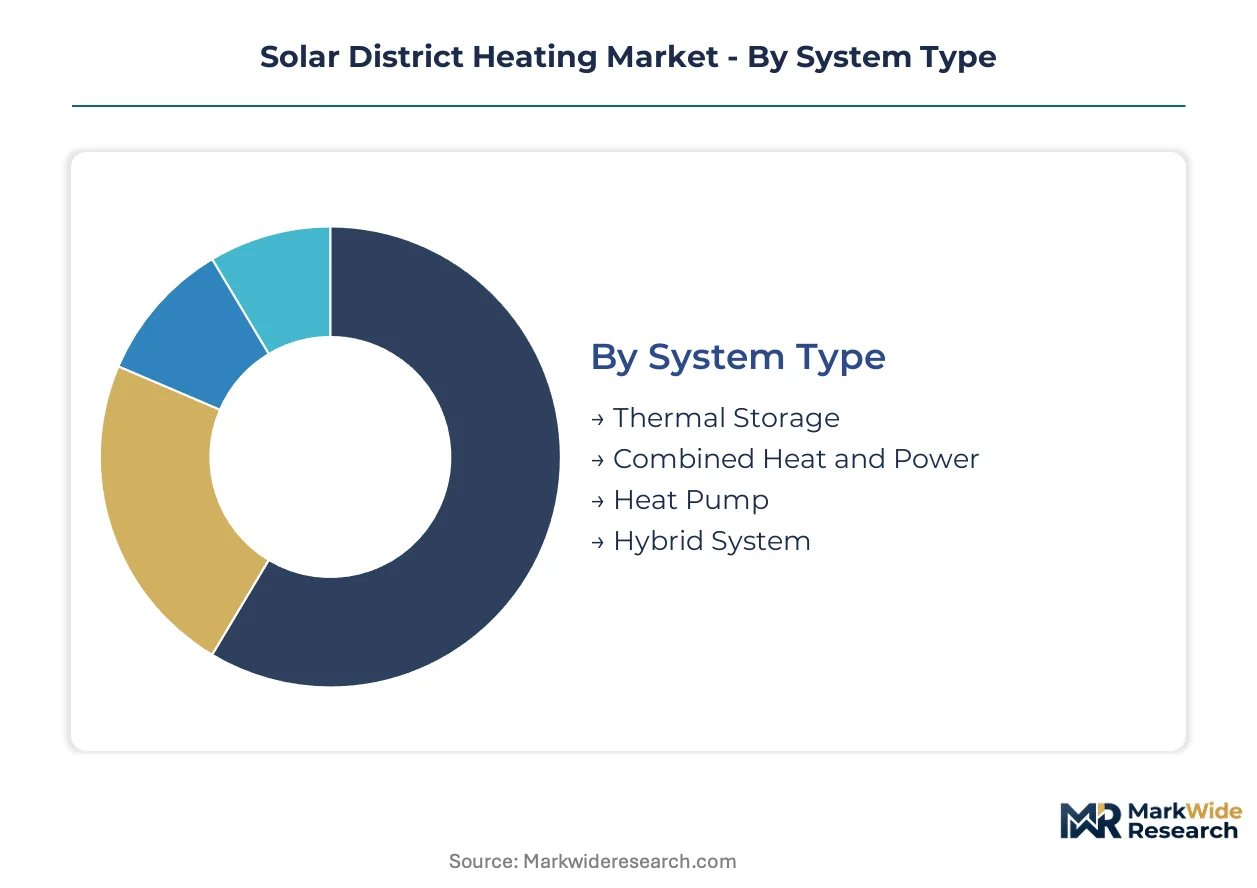
Technology selection in solar district heating hinges on thermal storage economics, collector efficiency at latitude, and integration complexity with legacy grids. Procurement patterns diver sharply between municipal operators prioritizing seasonal load shifting and industrial end-users demanding dispatchable baseload.
System Type:
Thermal storage systems face mounting substitution pressure from heat pump hybrids as F-Gas Regulation phase-downs compress project timelines across Northern European municipal grids.
- Thermal Storage:Seasonal pit and tank configurations bridge summer solar production with winter demand peaks. Danish Triangle Region operators around Silkeborg and Aarhus deploy these systems to retrofit biomass plants, though upfront capital intensity constrains adoption among smaller cooperatives.
- Hybrid System:Solar fields integrated with heat pumps create year-round renewable thermal coverage. Denmark's renewable heat quotas are accelerating municipal procurement of these configurations as operators front-load solar field procurement to secure heat pump allocation slots.
- Combined Heat and Power:Cogeneration units supplement solar thermal baseload with on-site electricity generation.
- Heat Pump:Standalone installations compete for municipal capex allocations, particularly in jurisdictions with weaker solar thermal mandates.
Thermal Storage retains volume leadership; Hybrid System holds the steepest expansion curve.
Heat Source:
Cost tier differentiation separates premium solar collector arrays from lower-capital biomass retrofits and waste heat recovery projects.
- Solar Collectors:Large-scale arrays operating at 80–120°C supply temperatures form the core renewable infrastructure. EU Ecodesign standards under the F-Gas Regulation now mandate solar thermal shares in new Danish district heating capacity.
- Biomass:Existing biomass plants across Denmark's Triangle Region are retrofitting with solar thermal fields to displace fossil peaking capacity. District energy operators favor this hybrid approach for grid stability.
- Waste Heat:Industrial off-take streams integrate into district networks where proximity permits.
- Geothermal:Subsurface thermal extraction supplements seasonal solar deficits in specific geological formations.
Solar Collectors dominate new capacity additions; Biomass retrofits command the largest installed base.
Application:
Customer type maturity varies from established municipal housing authorities to emerging industrial heat off-takers seeking renewable thermal contracts.
- Residential:Municipal housing authorities across Northern Europe anchor procurement of large-scale collector arrays. Denmark's national energy regulator enforces renewable heat quotas that direct this segment toward solar-compatible infrastructure.
- Community:District heating cooperatives in Denmark and Germany consolidate procurement around integrated control systems. Technical staffing depth enables these entities to unbundle after-sales service from initial equipment supply.
- Commercial:Office and retail complexes specify solar thermal for space heating and domestic hot water.
- Industrial:Process heat applications demand higher temperature delivery than standard district networks provide.
Residential commands procurement volume; Community applications are climbing the fastest as cooperative technical capabilities mature.
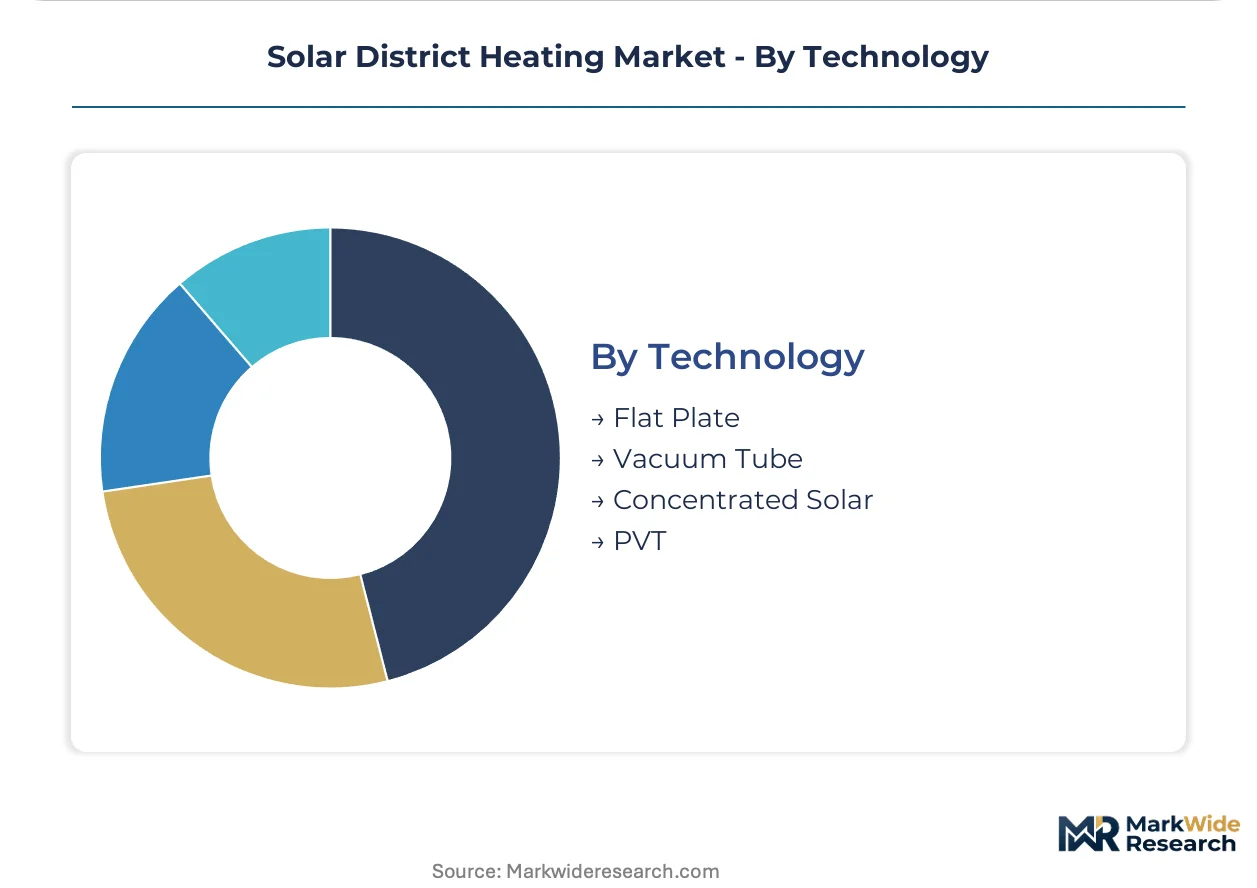
Technology:
Supply concentration in Danish manufacturing footprints shapes competitive dynamics across collector categories.
- Flat Plate:Cost and durability metrics dominate installed capacity. Municipal housing authorities specify these systems for standard 80–120°C networks, with Danish manufacturing anchoring procurement contracts across Scandinavia.
- Vacuum Tube:Superior efficiency under diffuse irradiance conditions captures premium high-latitude niches. Scandinavian installations facing limited winter sun hours specify these collectors despite higher capital requirements.
- Concentrated Solar:Parabolic trough and Fresnel configurations target industrial process heat above standard district temperatures.
- PVT:Photovoltaic-thermal hybrids generate concurrent electricity and thermal output for integrated building systems.
Flat Plate retains manufacturing scale advantages; Vacuum Tube captures margin expansion in high-latitude premium installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark consumes solar district heating through dense municipal networks with seasonal storage, while Germany deploys it as biomass retrofit complements and Scandinavia treats high-latitude vacuum tube installations as premium frost-resistant infrastructure.
Denmark
Municipal housing authorities in the Triangle Region around Silkeborg and Aarhus anchor procurement of large-scale collector arrays. The national energy regulator enforces renewable heat quotas mandating solar thermal shares in new district heating capacity. District energy operators here are retrofitting biomass plants with solar thermal fields to displace fossil peaking capacity.
Germany
Federal emission control restrictions under BImSchG channel municipal investment toward solar-compatible district infrastructure. The F-Gas Regulation alignment with EU phase-down mandates compresses project timelines for hybrid solar-thermal installations. District heating cooperatives in North Rhine-Westphalia and Bavaria consolidate procurement around integrated control systems.
Sweden
High-latitude installations face limited winter sun hours, driving specification of vacuum tube collectors despite higher capital requirements. EU Ecodesign standards shape equipment specifications for integrated heat pump components. Göteborg Energi anchors municipal procurement patterns across the Gothenburg metropolitan cluster.
Poland
Emerging district heating modernization programs create procurement windows for solar thermal retrofits in legacy coal-dependent grids. National energy efficiency directives align with EU Green Deal decarbonization timelines. Municipal operators in the Silesian and Greater Poland voivodeships pilot hybrid configurations combining solar fields with heat pumps.
Solar District Heating Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in solar district heating equipment supply. Danish manufacturing footprints anchor procurement contracts across Scandinavia, while German and Austrian engineering groups compete through control system integration. Three archetypes dominate: captive manufacturing specialists with in-house collector production, systems integrators bridging solar fields with conventional boiler infrastructure, and thermal storage engineering firms. Competitive moves concentrate on strategic partnerships for heat pump convergence and geographic expansion into Eastern European retrofit markets.
Within the integrated manufacturing tier, Arcon-Sunmark represents the Danish production anchor model, leveraging its domestic footprint to secure municipal procurement contracts. Viessmann and Bosch Thermotechnology exemplify the systems integration archetype, with the former occupying a position bridging collector fields with conventional boiler infrastructure and the latter sustaining R&D intensity in absorber coatings. These three entities anchor vendor competitive dynamics across Northern European municipal grids.
| Leading Market Players |
|---|
| Arcon-Sunmark |
| Viessmann |
| Bosch Thermotechnology |
| Danfoss |
| Savosolar |
| Alfa Laval |
| LOGSTOR |
| Göteborg Energi |
| Solvis |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign certification under the F-Gas Regulation gates both supplier qualification and price differentiation in solar district heating equipment, forcing manufacturers to absorb validation costs or tier offerings by frost-resistance grade while municipal buyers face extended procurement cycles for certified absorber technology.
Pricing Analysis
Long-term offtake contracts dominate municipal procurement, with Danish housing authorities and German cooperatives locking in decade-spanning agreements for collector arrays. Price differentiation stems from certification tier—EU Ecodesign-validated frost-resistant coatings command premium positioning—and after-sales service bundling. Cost compression in flat-plate collector manufacturing is intensifying because Danish producers are scaling output for Triangle Region retrofits. District heating cooperatives exhibit the sharpest price sensitivity, while industrial process heat buyers accept premium vacuum tube configurations.
Supply Chain Analysis
Strategic stockpiling of copper absorber substrates and low-iron glass characterizes procurement behavior, with manufacturers buffering against raw material volatility rather than pursuing lean inventory. Supply concentrates in Denmark, Germany, and Austria, drawing from Spanish and Chinese glass feedstock and Nordic copper refining. Single-source vulnerability runs through Danish seasonal tank engineering capacity. Distribution feeds through municipal procurement consortia and EPC contractors serving district energy operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents in solar district heating face a substitution defense against standalone heat pump installations, which are capturing municipal capex allocations in jurisdictions with weaker renewable heat quotas.
For Market Incumbents: Shield installed base relationships by embedding control software that bridges solar fields with heat pump hybrids, locking in technical switching costs. Deepen backward integration into seasonal storage engineering to capture margin from pit and tank deployments. Monitor F-Gas Regulation phase-down timelines that compress project windows and favor vendors with validated integrated components. For New Entrants and Emerging Players: After-sales service unbundling presents the most penetrable gap, as Danish and German cooperatives increasingly separate maintenance contracts from initial equipment supply. Target Polish municipal operators piloting hybrid retrofits in coal-dependent Silesian grids. Lead with thermal storage engineering capabilities rather than collector manufacturing to bypass incumbent production scale advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermal storage engineering firms that consolidated during the last decade of Danish biomass retrofit activity. Five-to-ten year viability hinges on heat pump convergence execution and Eastern European geographic expansion. Watch for heat pump coefficient-of-performance threshold announcements as the inflection signal that reshapes technology mix decisions and acquisition multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Convergence Partnership | Secures allocation slots under Denmark's F-Gas Regulation compliance timelines. |
| Seasonal Storage Engineering Acquisition | Captures margin from pit and tank capital intensity in biomass retrofit projects. |
| Control System Platform Integration | Locks in municipal cooperatives through software-embedded switching costs. |
| Polish Market Geographic Expansion | Accesses EU Green Deal modernization windows in coal-dependent district grids. |
| Vacuum Tube Premium Tier Development | Addresses Scandinavian high-latitude efficiency requirements with frost-resistant specifications. |
Methodological Framework
Initial hypotheses were tested against primary input from district energy planning officers, EPC contractor project managers, municipal procurement leads, and thermal storage engineering directors, then refined against secondary validation from EIA district heating databases, IEA renewable heat reports, EU Ecodesign regulatory filings, and Danish Energy Agency capacity statistics. Bottom-up project pipeline aggregation triangulated against top-down national renewable heat quota modeling.
Variance decomposition across the projection horizon isolates technology mix shifts, regulatory compliance timeline acceleration, and storage cost curve movements as primary uncertainty sources. Segmentation dimensions span system type, heat source, application, and collector technology, with hybrid configuration penetration and heat pump integration depth as industry-specific forecast inputs. CAGRs derive from installed capacity buildout trajectories and capital deployment patterns across municipal procurement cycles.
Forecasts assume regulatory continuity in EU F-Gas Regulation phase-down schedules and Danish renewable heat quota enforcement; material policy shifts would require re-modeling. Revision becomes warranted when heat pump substitution rates in German municipal allocations cross threshold levels that threaten solar thermal capacity additions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Solar Watch Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Botswana Renewable Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Solar Chair Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Romania Power Market
Renewable Energy
United Arab Emirates Renewable Energy Market