
 Global Survey Software Market | 2026-2036
Global Survey Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Survey Software Market Outlook
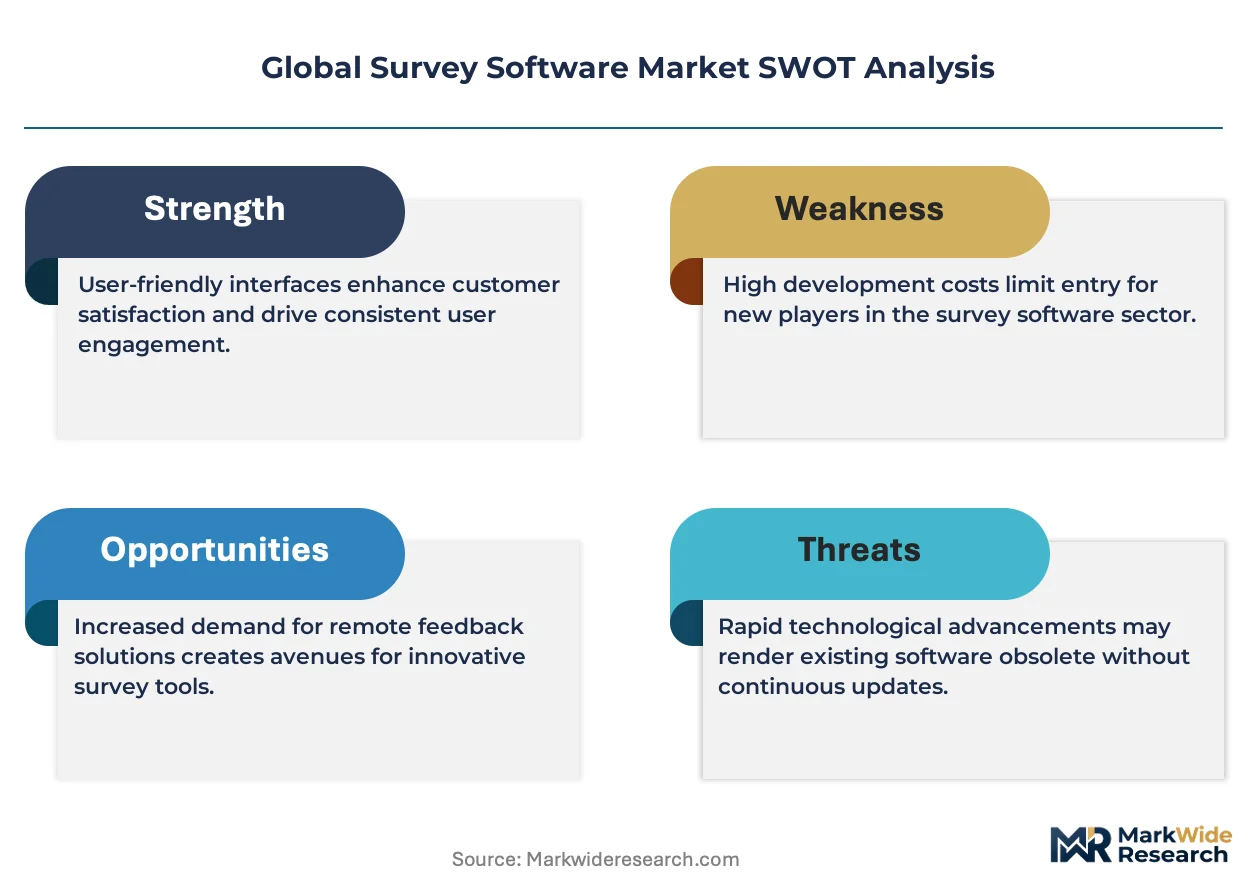
The EU Green Deal is pivoting enterprise buyers toward carbon-conscious vendor selection, with sustainability disclosure requirements now embedded in procurement scorecards. Qualtrics International Inc. leverages its XM platform to anchor climate reporting integrations for European clients. Microsoft Corporation competes through Azure-hosted survey infrastructure that sustains energy-efficient data center commitments. Momentive Global Inc. specializes in ESG-aligned questionnaire templates that differentiate its offering for sustainability officers.
Survey software comprises digital platforms that design, distribute, collect, and analyze structured feedback through web interfaces, mobile applications, and API-connected systems, typically processing responses with statistical engines that apply weighting algorithms and cross-tabulation logic. Cloud-based deployment leads structural share due to elastic scaling for seasonal research cycles, while mobile surveys represent the fastest-expanding format as smartphone penetration extends respondent reach in emerging markets. Subscription licensing dominates revenue pools by locking in recurring enterprise relationships, though pay-per-use models are gaining traction among project-based market research firms.
The EU AI Act and GDPR jointly constrain automated survey analysis by mandating human oversight for algorithmic decision-making and strict consent documentation, while the SEC climate disclosure rules in the United States push publicly traded clients to demand audit-ready feedback trails. ISO 27001 certification has become a baseline market access requirement for vendors serving financial and healthcare segments. Stakeholders must monitor regulatory divergence between jurisdictions to determine where compliance investments yield competitive protection versus mere cost burden.
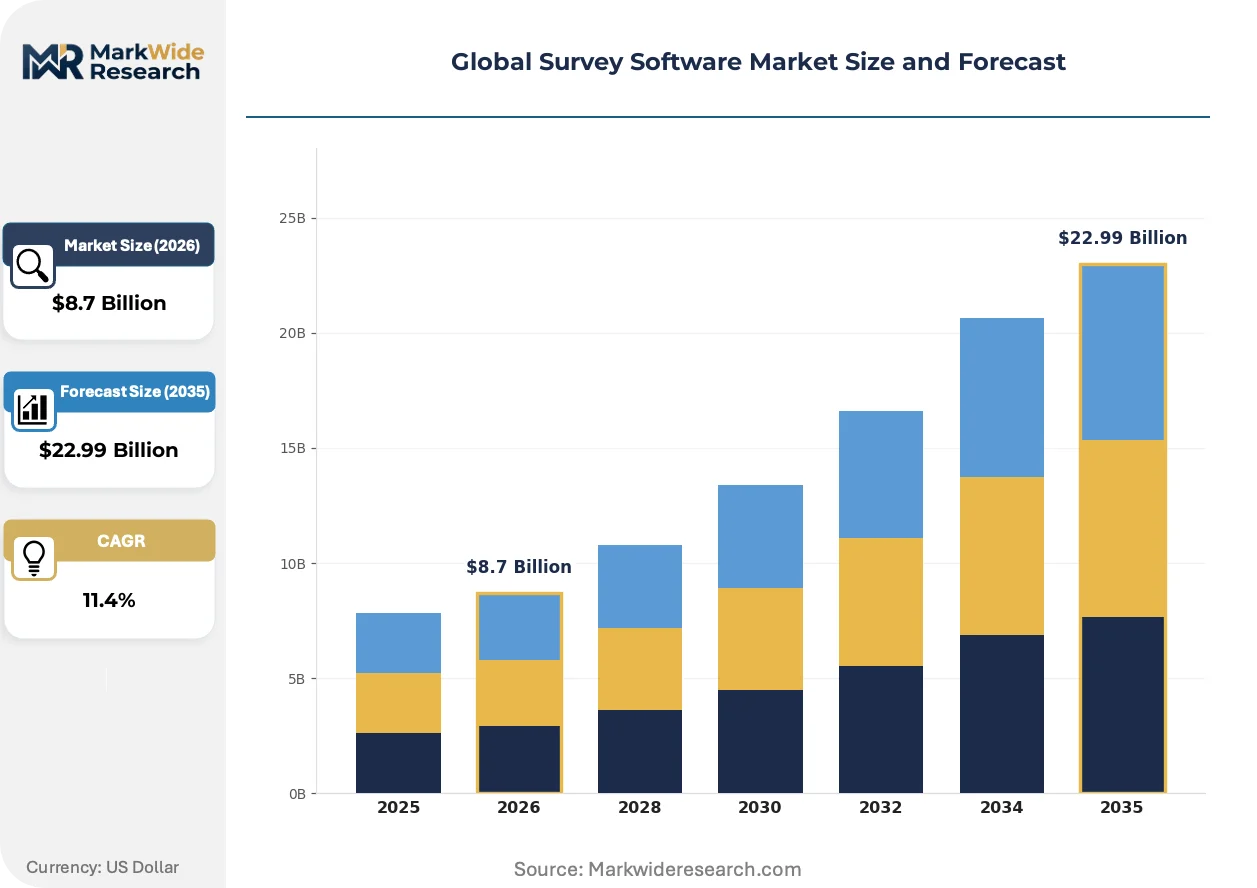
Market Dynamics
Healthcare providers are expanding survey deployments for patient experience measurement, while the EU AI Act and SEC climate disclosure rules force vendors to rebuild compliance architectures around consent documentation and audit-ready feedback trails.
Growth Catalysts
- GDPR and EU AI Act:These frameworks mandate human oversight for algorithmic survey analysis, creating specialized demand for compliance-integrated platforms among European enterprises.
- Smartphone penetration:Mobile surveys are capturing respondent populations previously unreachable through desktop channels, particularly across emerging markets in Southeast Asia and Latin America.
- Cloud elasticity:Seasonal research cycles in retail and political polling drive preference for subscription models that scale compute resources without capital commitment.
Market Restraints
- ISO 27001 certification costs:Financial and healthcare segments now require this baseline credential, imposing fixed compliance burdens that disadvantage smaller vendors.
- API dependency:Enterprise survey platforms rely on third-party connectivity layers, concentrating operational risk around a narrow set of integration specialists.
- Regulatory divergence:Jurisdictional fragmentation between GDPR, HIPAA, and emerging AI governance forces redundant engineering investments without proportional revenue protection.
Strategic Opportunities
- India's digital public infrastructure:The country's expanding smartphone base and Aadhaar-linked identity systems enable frictionless respondent authentication for survey platforms entering this market.
- CSRD-aligned ESG reporting:European sustainability disclosure requirements are embedding climate-conscious vendor selection into procurement scorecards, favoring platforms with carbon-tracking integrations.
- Voice-to-text convergence:Natural language processing paired with telephony infrastructure is opening voice-based survey channels for illiterate and elderly populations.
Industry Challenges
- Statistical engineering talent:Vendors face acute shortages of professionals capable of designing weighting algorithms and cross-tabulation engines that meet academic and regulatory standards.
- Legacy system integration:Enterprise clients demand seamless API connections to decades-old CRM and ERP installations, stretching implementation timelines and technical support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Survey Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Online Surveys, Mobile Surveys, Offline Surveys, Panel Surveys Deployment: Cloud-Based, On-Premise, Hybrid, Integrated Solutions End User: Education, Healthcare, Retail, Market Research Firms Licensing Model: Subscription, One-Time Purchase, Freemium, Pay-Per-Use |
| Companies Covered | Qualtrics International Inc., Momentive Global Inc., Google LLC, Alchemer LLC, Zoho Corporation Pvt. Ltd., Typeform S.L., Microsoft Corporation, Medallia Inc., QuestionPro Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Survey Software Market Strategic Shifts
Artificial intelligence is compressing the interval between survey fielding and insight delivery, while regulatory pressure and shifting procurement patterns are fragmenting vendor selection criteria across geographies and end-use verticals.
Natural language generation is automating the production of survey instruments from unstructured business questions, reducing questionnaire design cycles from weeks to hours. Market research departments at Fortune 500 manufacturers are deploying these tools for weekly pulse studies. This capability is automating the displacement of traditional research agency retainers with self-service platform subscriptions.
The EU AI Act's risk-classification framework is redefining permissible automation in feedback systems, prohibiting fully automated profiling for sensitive health and financial decisions. Vendors serving European healthcare networks must now engineer human-in-the-loop review stages. German hospital systems and French pharmaceutical panels are prioritizing platforms with built-in escalation workflows to preempt regulatory enforcement.
Subscription fatigue among mid-market buyers is fragmenting procurement toward modular, API-first components rather than monolithic experience management suites. Research departments at US universities and Indian NGOs are unbundling distribution, analysis, and visualization functions across specialized vendors. This pattern is most visible in North American higher education and South Asian development sectors, where budget constraints favor pay-per-use pricing over annual commitments.
Global Survey Software Market Segmentation
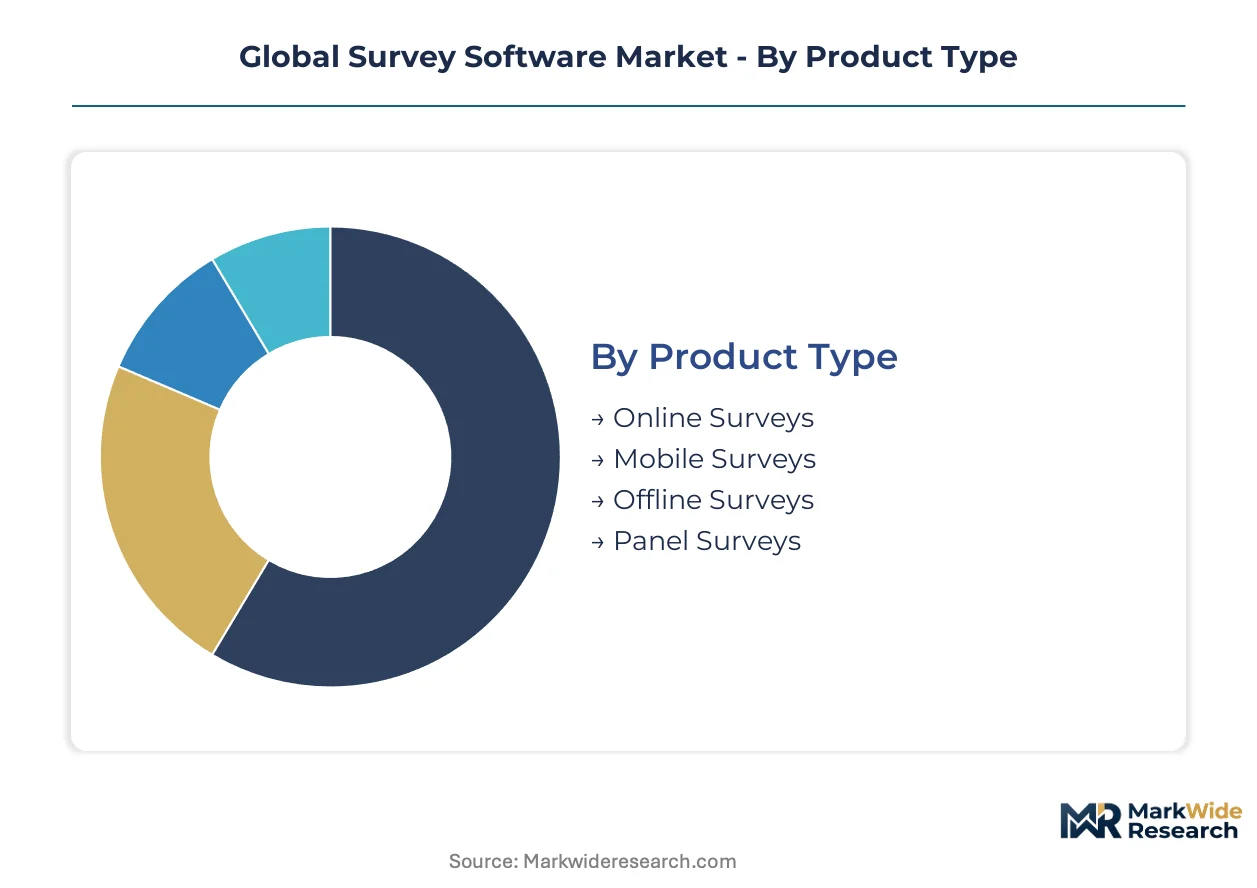
Segmentation in survey software reveals how procurement criteria diverge across buyer sophistication levels and compliance exposure. Cloud elasticity attracts seasonal research operations, while regulatory-heavy sectors demand deployment architectures that satisfy audit requirements.
Product Type:
Buyer priorities around respondent reach and field conditions determine format selection, with connectivity infrastructure and literacy rates shaping regional preferences.
- Online Surveys:Web-browser instruments dominate enterprise feedback programs through desktop-optimized interfaces and embedded multimedia capabilities. North American corporations and European pharmaceutical panels concentrate procurement here, driven by GDPR-mandated consent workflows and complex branching logic requirements. ISO 27001 certification has become a baseline filter for financial services buyers sourcing these platforms.
- Mobile Surveys:Smartphone-native instruments capture respondent populations unreachable through desktop channels, utilizing geofencing and camera integration for contextual data capture. India's expanding digital public infrastructure and Southeast Asia's smartphone penetration are accelerating procurement from development organizations and consumer goods manufacturers seeking rural demographic access.
- Offline Surveys:Local-storage instruments with delayed synchronization serve field researchers operating beyond reliable connectivity, common in sub-Saharan agricultural extension programs and remote mining community consultations.
- Panel Surveys:Pre-recruited respondent pools with verified demographic attributes command premium pricing from political pollsters and brand trackers requiring representative sampling frames.
Online surveys lead on scale; mobile surveys lead on momentum.
Deployment:
Infrastructure control preferences split along data sovereignty requirements and seasonal volume volatility, with compliance architecture costs tilting decisions toward hosted or hybrid arrangements.
- Cloud-Based:Elastic compute resources scale without capital commitment, attracting retail seasonal research cycles and political polling operations with spiky demand patterns. Microsoft's Azure-hosted infrastructure competes through energy-efficient data center commitments that satisfy EU Green Deal procurement scorecards.
- On-Premise:Local server installations satisfy national data localization mandates and air-gapped security requirements, prevalent in German automotive supply chain audits and Saudi government citizen feedback programs.
- Hybrid:Split architectures process sensitive fields locally while leveraging cloud analytics for aggregate reporting, gaining traction among French hospital systems navigating EU AI Act risk classifications.
- Integrated Solutions:Pre-connected modules embedding survey distribution within CRM and ERP workflows reduce implementation timelines for Fortune 500 manufacturers with legacy system dependencies.
Cloud-based deployment commands volume leadership; hybrid architectures are climbing the fastest as regulatory fragmentation intensifies.
End User:
Sector-specific compliance exposure and feedback frequency determine platform sophistication requirements, with healthcare and education presenting divergent procurement timelines.
- Healthcare:Patient experience measurement programs require HIPAA-compliant audit trails and human-in-the-loop review stages for EU AI Act adherence. German hospital systems and US health networks are expanding deployments for HCAHPS-equivalent metrics.
- Education:Course evaluation and institutional research departments favor modular, API-first components over monolithic suites, with North American universities unbundling functions across specialized vendors due to budget constraints.
- Retail:Seasonal research cycles and post-purchase feedback loops drive preference for subscription licensing with elastic scaling, particularly among Southeast Asian e-commerce platforms.
- Market Research Firms:Project-based operations with variable client loads are shifting toward pay-per-use pricing models that align costs with fielding schedules.
Healthcare leads on compliance-driven average contract value; education is gaining share fastest through procurement unbundling.
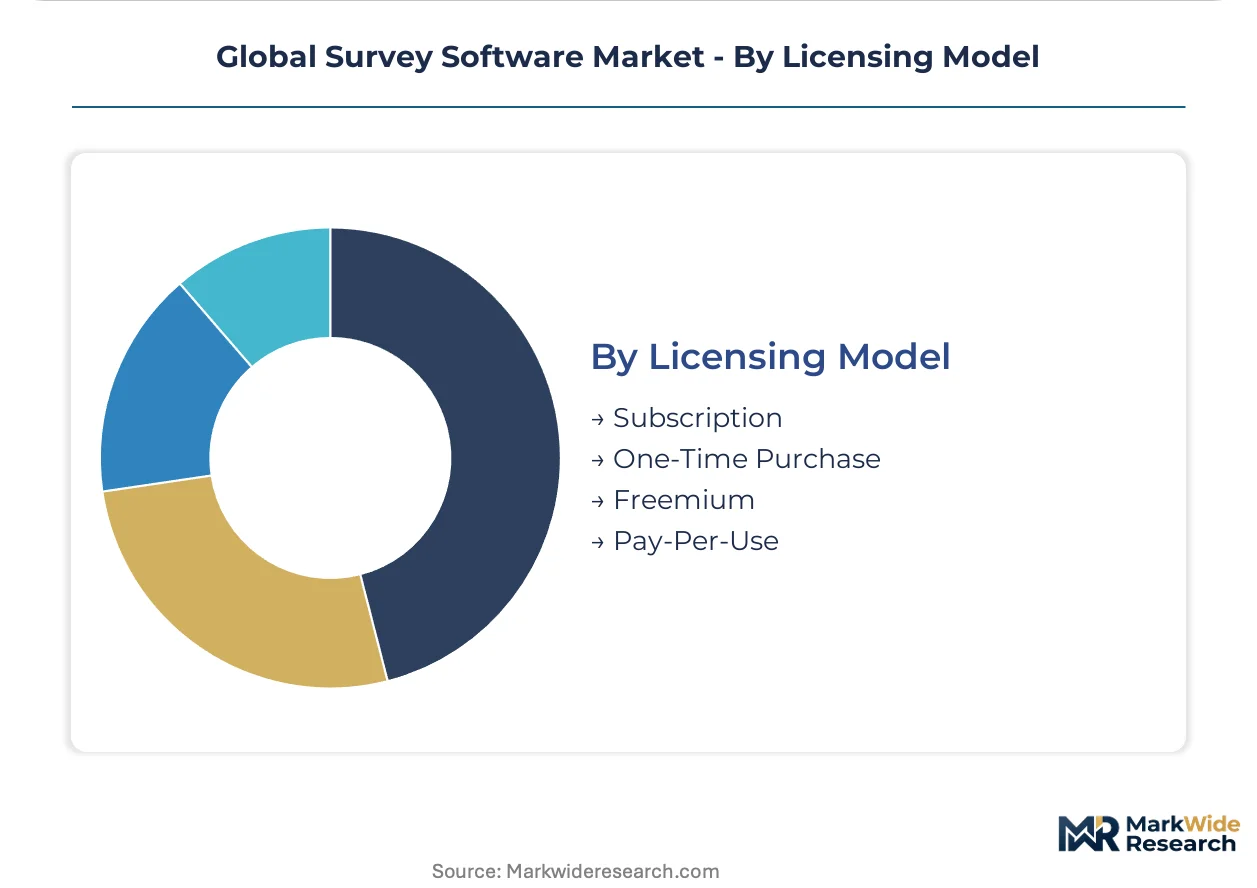
Licensing Model:
Payment structure preferences correlate with buyer size predictability and research operation regularity, with enterprise relationships locking in recurring revenue while smaller buyers seek flexibility.
- Subscription:Annual or multi-year commitments dominate enterprise procurement, securing recurring revenue relationships with manufacturers and healthcare networks running continuous experience programs.
- One-Time Purchase:Perpetual licenses with maintenance add-ons persist in government and university settings with capital budget cycles and multi-year appropriation structures.
- Freemium:Tiered entry points with feature-gated upgrades capture individual researchers and early-stage NGOs, converting to paid tiers at response volume thresholds.
- Pay-Per-Use:Consumption-based pricing aligns costs with project fielding, attracting Indian development sector consultants and Latin American political pollsters with irregular research calendars.
Subscription licensing leads on revenue concentration; pay-per-use is expanding most quickly among project-based buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The survey software industry traces its commercial origins to the United States enterprise technology corridor, where cloud infrastructure and SaaS business models first converged to deliver scalable feedback platforms.
United States
Healthcare networks and Fortune 500 manufacturers drive enterprise procurement for patient experience and employee engagement programs. SEC climate disclosure rules push publicly traded clients to demand audit-ready feedback trails with carbon-tracking capabilities. The San Francisco Bay Area and Seattle technology clusters host the dominant platform engineering centers.
Germany
Automotive supply chain audits and hospital system digitization create sustained demand for on-premise and hybrid deployment architectures. The EU AI Act and GDPR jointly mandate human-in-the-loop review stages for algorithmic survey analysis. Bavaria and Baden-Württemberg concentrate procurement from industrial Mittelstand firms and university research departments.
India
Development sector consultants and political polling operations favor pay-per-use models aligned with irregular research calendars. The country's digital public infrastructure and Aadhaar-linked identity systems enable frictionless respondent authentication. Bangalore and Hyderabad anchor the technical support and platform customization hubs serving Southeast Asian expansion.
United Kingdom
Financial services compliance and higher education institutional research sustain demand for ISO 27001-certified platforms with modular API architectures. The CSRD-aligned sustainability disclosure requirements embed climate-conscious vendor selection into procurement scorecards. London and the Southeast corridor concentrate fintech and professional services adoption.
Japan
Enterprise feedback management and customer loyalty programs drive adoption among electronics manufacturers and retail conglomerates. METI guidelines on data governance shape platform requirements for cross-border response handling. The Tokyo-Osaka corridor dominates procurement, with Nagoya-based automotive suppliers extending deployment into supplier quality audits.
Global Survey Software Market Competitive Environment
Capital-heavy infrastructure providers compete with asset-light platform developers for enterprise relationships, creating a tiered structure where scale advantages concentrate among established cloud hosts while specialized vendors capture vertical niches. The vendor base fragments across three strategic archetypes: integrated experience management suites, modular API-first components, and vertical-specific compliance platforms. M&A activity targets niche analytics capabilities, while strategic partnerships with CRM and ERP incumbents dominate distribution channel development.
Within the integrated platform tier, Qualtrics International Inc. and Microsoft Corporation exemplify contrasting approaches to enterprise anchoring, with the former representing vertical experience management specialization and the latter leveraging cloud infrastructure scale. Momentive Global Inc. occupies a position among modular specialists emphasizing ESG-aligned questionnaire templates for sustainability officers. These three entities collectively illustrate how competitive positioning diverges between suite consolidation and functional unbundling strategies.
| Leading Market Players |
|---|
| Qualtrics International Inc. |
| Momentive Global Inc. |
| Google LLC |
| Alchemer LLC |
| Zoho Corporation Pvt. Ltd. |
| Typeform S.L. |
| Microsoft Corporation |
| Medallia Inc. |
| QuestionPro Inc. |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration through API-first component unbundling anchors supply position for modular vendors while concentrating pricing power among integrated platform providers serving compliance-heavy healthcare and financial segments. Cloud infrastructure partnerships with hyperscalers feed cost advantages downstream, compressing margins for pure-play survey developers lacking captive compute capacity.
Pricing Analysis
Subscription-based SaaS tiers with annual commitments dominate enterprise procurement, separating ISO 27001-certified premium platforms from standard self-serve tools and freemium entry points for individual researchers. Price differentiation rests on audit-ready compliance architecture and human-in-the-loop AI review capabilities mandated by EU AI Act risk classifications. Cost compression in the mid-market tier is intensifying because procurement unbundling lets buyers mix specialized vendors rather than pay suite premiums. Individual researchers and early-stage NGOs exhibit highest price sensitivity, while German hospital systems and US health networks prioritize compliance over cost.
Supply Chain Analysis
Software engineering talent shortages in India and Poland constrain platform customization capacity for vendors expanding into Southeast Asian and European markets. Cloud compute supply concentrates in the United States, Ireland, and Singapore, with data center energy commitments now feeding into EU Green Deal procurement scorecards. Raw material dependencies span semiconductor chips for edge devices, lithium-ion batteries for field hardware, and rare earth elements for server infrastructure. Single-source vulnerability around NVIDIA GPU allocations for AI-powered survey analysis poses structural risk. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and systems integrators serving Fortune 500 manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in survey software hinges on automation compressing questionnaire design cycles from weeks to hours, allowing vendors to capture premium pricing for AI-accelerated insight delivery while reducing human researcher hours per engagement.
For Market Incumbents: Hedge against modular unbundling by embedding survey distribution deeper into CRM and ERP workflows through pre-built connectors, reducing buyer incentive to fragment procurement across specialized vendors. Acquire natural language generation capabilities to preempt displacement by self-service tools displacing traditional research agency retainers. Prioritize EU AI Act compliance investments in German and French hospital systems where enforcement risk concentrates.
For New Entrants and Emerging Players: API-first distribution channels unlock white-space penetration among North American universities and Indian development sector consultants seeking pay-per-use pricing without annual commitments. Target voice-to-text convergence for illiterate and elderly populations in sub-Saharan agricultural extension programs where offline field conditions exclude incumbent cloud-native platforms. Lead with frictionless Aadhaar-linked authentication for India's expanding smartphone base.
For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific compliance platforms because regulatory divergence between GDPR, HIPAA, and emerging AI governance creates acquisition targets with trapped customer bases facing high switching costs. Mid-market vendors with ISO 27001 certification and healthcare sector concentration offer strongest 5-10 year viability as audit requirements harden. Watch for EU AI Act enforcement actions against fully automated profiling systems as inflection indicator for human-in-the-loop platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built CRM connectors reduce implementation timelines for Fortune 500 manufacturers with legacy ERP dependencies. |
| Acquisition of Specialist Firm | Natural language generation targets compress questionnaire design cycles from weeks to hours for weekly pulse studies. |
| Strategic Partnership | Hyperscaler marketplace placement exposes platforms to AWS and Azure procurement officers controlling enterprise cloud budgets. |
| Product Launch | Voice-to-text survey channels unlock respondent populations previously unreachable through smartphone-native instruments. |
| Geographic Expansion | Aadhaar-linked authentication infrastructure enables frictionless rural demographic access for India's development sector. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists alongside secondary validation. SEC filings, hyperscaler capex disclosures, App Annie mobile analytics, and EU regulatory databases provided external benchmarks. Bottom-up respondent volume modeling and top-down enterprise spending estimates were triangulated against disclosed platform revenues.
Granularity-level modeling deployed deployment mode, organization size, vertical industry, and integration complexity as primary segmentation dimensions across the analysis window. CAGRs were derived from elasticity-adjusted adoption curves incorporating seasonal research cycle patterns and compliance-driven procurement delays. AI governance timeline assumptions and smartphone penetration trajectories in Southeast Asia fed scenario-weighted outputs.
The model assumes a particular technology adoption path; alternative pathways for voice-to-text natural language processing would alter the outlook if telephony infrastructure deployment lags smartphone penetration in target markets. Forecasts reflect documented assumptions regarding EU AI Act enforcement intensity and SEC climate disclosure rule durability. Material deviation in named regulatory triggers or hyperscaler energy commitment credibility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Webcasting Software Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Terminal Emulator Software Market
Software & Services
Global Business Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Performing Arts Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Enterprise Application Market
Software & Services
Global Virtualization Software Market