
 Global Business Software and Service Market | 2026-2036
Global Business Software and Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Software and Service Market Foresight
Artificial intelligence is consolidating its position as the dominant computational substrate across enterprise software stacks, displacing rule-based automation in core financial and operational workflows. Microsoft Corporation leverages its Azure cloud infrastructure to anchor generative AI capabilities throughout productivity suites and enterprise resource planning modules. Oracle Corporation sustains database-to-application vertical integration that competes with best-of-breed alternatives in high-transaction environments. SAP SE specializes in industry-specific process logic that dominates manufacturing and supply chain verticals across European industrial clusters.
Business software and services encompass programmable applications, middleware, and professional services that automate, analyze, and orchestrate commercial operations across distributed computing environments, typically delivered through subscription or perpetual licensing models with service-level agreements governing uptime, security, and data portability. Enterprise Resource Planning solutions retain the largest installed base and renewal revenue pools, though Customer Relationship Management segments exhibit the fastest expansion as sales and service organizations demand unified customer data platforms. Cloud-Based deployment now leads new contract value, while Hybrid architectures capture growing share among regulated industries requiring partitioned workload management between sovereign infrastructure and elastic public capacity.
The EU AI Act, GDPR, and ISO 27001 standards collectively reshape product roadmaps by mandating explainable algorithms, data residency controls, and certified information security management systems before market access. The Securities and Exchange Commission in the United States imposes comparable disclosure and cybersecurity governance obligations on publicly traded software consumers that cascade into vendor procurement requirements. Stakeholders must monitor how divergent sovereignty frameworks across the European Union, China, and India fragment cloud architecture standards and force localization investments that alter scale economics for platform providers.
Market Dynamics
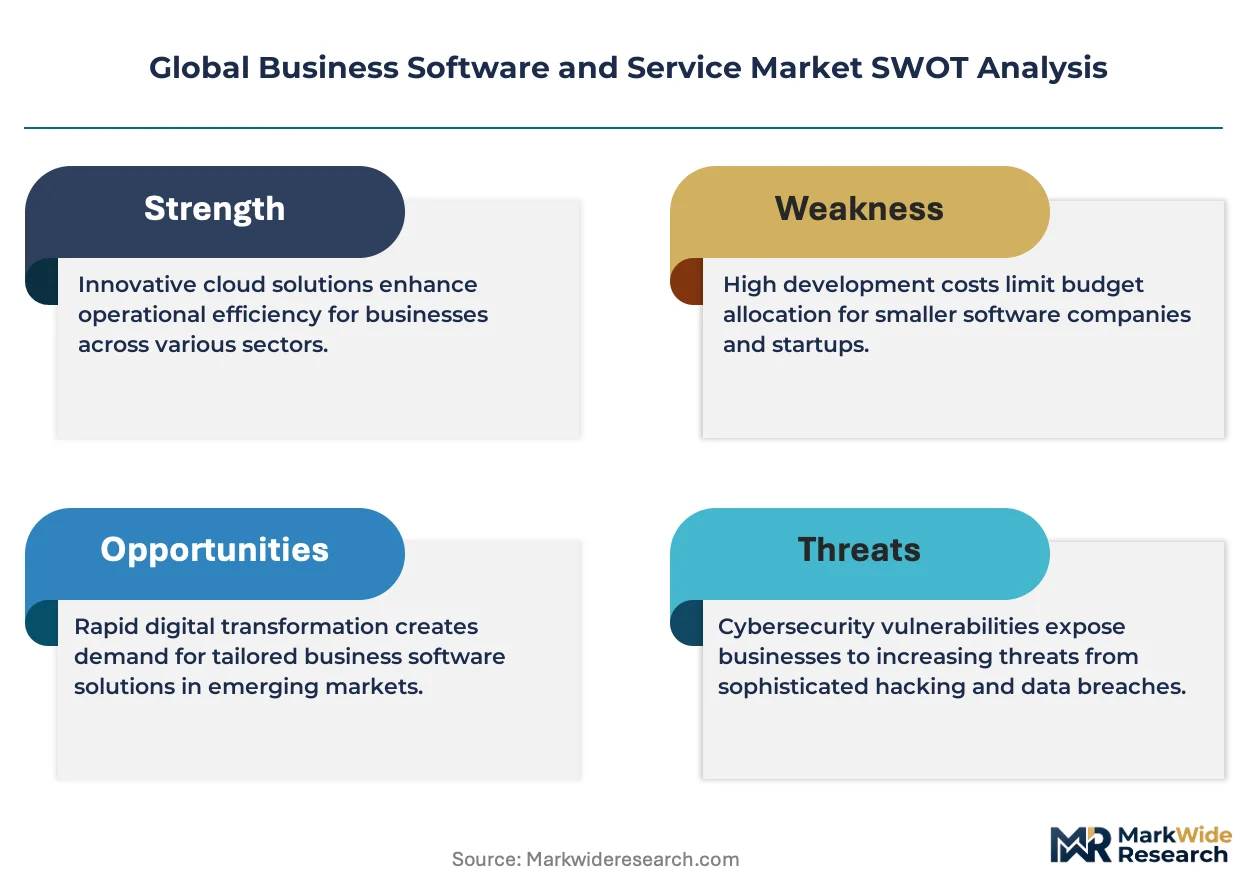
Cloud-native architectures are compressing deployment cycles while the EU AI Act and GDPR impose algorithmic governance mandates that reshape vendor roadmaps and procurement criteria across financial services and industrial verticals.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions in Germany and France must embed explainability and audit trails into automated decision systems, creating captive demand for governance-embedded platforms.
- Hybrid cloud orchestration:Enterprises in Singapore and South Korea partition workloads between sovereign infrastructure and elastic public capacity, requiring middleware that spans both environments.
- Generative AI integration:Sales and service organizations demand unified customer data platforms that embed large language models into workflow automation.
Market Restraints
- Data residency enforcement:China's data localization requirements and India's digital sovereignty frameworks fragment cloud architecture standards, forcing redundant infrastructure investments.
- Cybersecurity certification bottlenecks:ISO 27001 and SOC 2 Type II audit timelines stretch 6-14 months, gating market access for new entrants.
- Legacy system entrenchment:Mainframe-dependent institutions in Japan face technical debt that slows migration to API-first architectures.
Strategic Opportunities
- Regulatory technology (RegTech) convergence:The SEC's cybersecurity disclosure rules and CSRD reporting requirements in Europe create demand for automated compliance monitoring tools.
- Edge computing deployment:Manufacturing clusters in Bavaria and Osaka require low-latency processing for predictive maintenance applications.
- Vertical-specific process logic:Supply chain orchestration platforms tailored to automotive and pharmaceutical serialization standards capture premium pricing.
Industry Challenges
- AI/ML engineering scarcity:MLOps and responsible AI governance expertise concentrates in San Francisco, London, and Bangalore, inflating compensation costs.
- Interoperability fragmentation:Divergent API standards between SAP, Oracle, and Salesforce ecosystems force costly integration middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Software and Service Market |
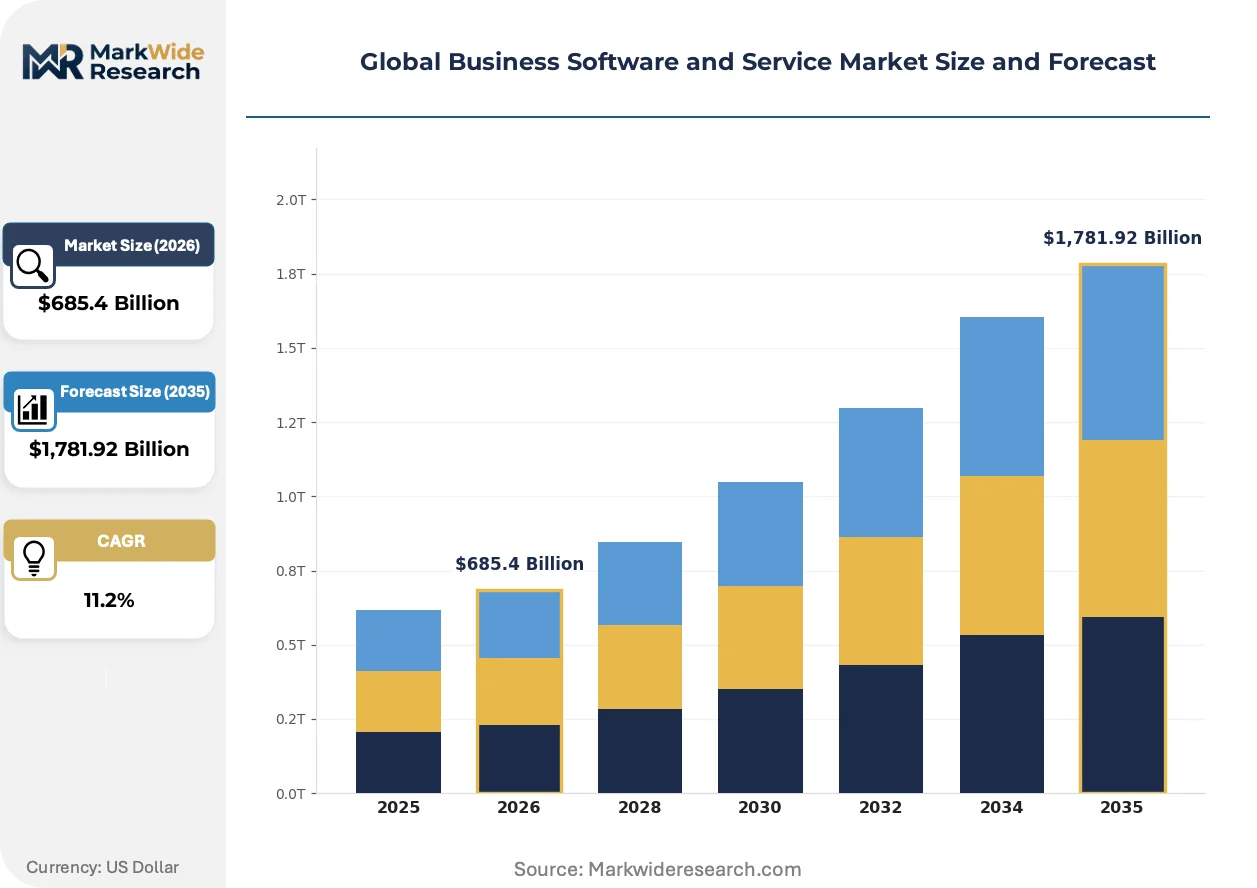
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,781.92 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud, Public Cloud Solution Type: Enterprise Resource Planning, Customer Relationship Management, Supply Chain Management, Human Capital Management, Business Intelligence End User Industry: Manufacturing, Telecommunications, Transportation, Financial Services, Education Service Offering: Consulting, System Integration, Managed Services, Support & Maintenance, Training |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP SE, IBM Corporation, Salesforce Inc., Adobe Inc., ServiceNow, Workday Inc., Intuit Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Software and Service Market Shifts & Advancements
Generative AI capabilities are embedding into core enterprise workflows, while regulatory pressure accelerates investment in explainable algorithms and sovereign cloud infrastructure. Three developments are compressing competitive timelines.
Agentic AI systems are unifying task automation across previously siloed enterprise applications. Procurement teams at Fortune 500 manufacturers deploy autonomous agents that span ERP, CRM, and supply chain modules without human handoffs. This compression of integration layers threatens standalone RPA vendors and forces platform consolidation.
REACH chemical safety registration and the EU AI Act's risk classification framework are mandating algorithmic impact assessments before deployment. Industrial software vendors must now document training data provenance and model drift monitoring. High-risk applications in credit scoring and medical diagnostics face 12-18 month certification cycles that favor incumbents with compliance infrastructure.
Subscription fatigue among mid-market buyers is driving unbundling of professional services from software licenses. Chief financial officers in the United Kingdom and Netherlands now demand consumption-based pricing tied to transaction volumes rather than seat counts. This shift compresses upfront contract values while extending revenue recognition timelines, forcing vendors to restructure sales compensation and cash flow management.
Global Business Software and Service Market Segmentation
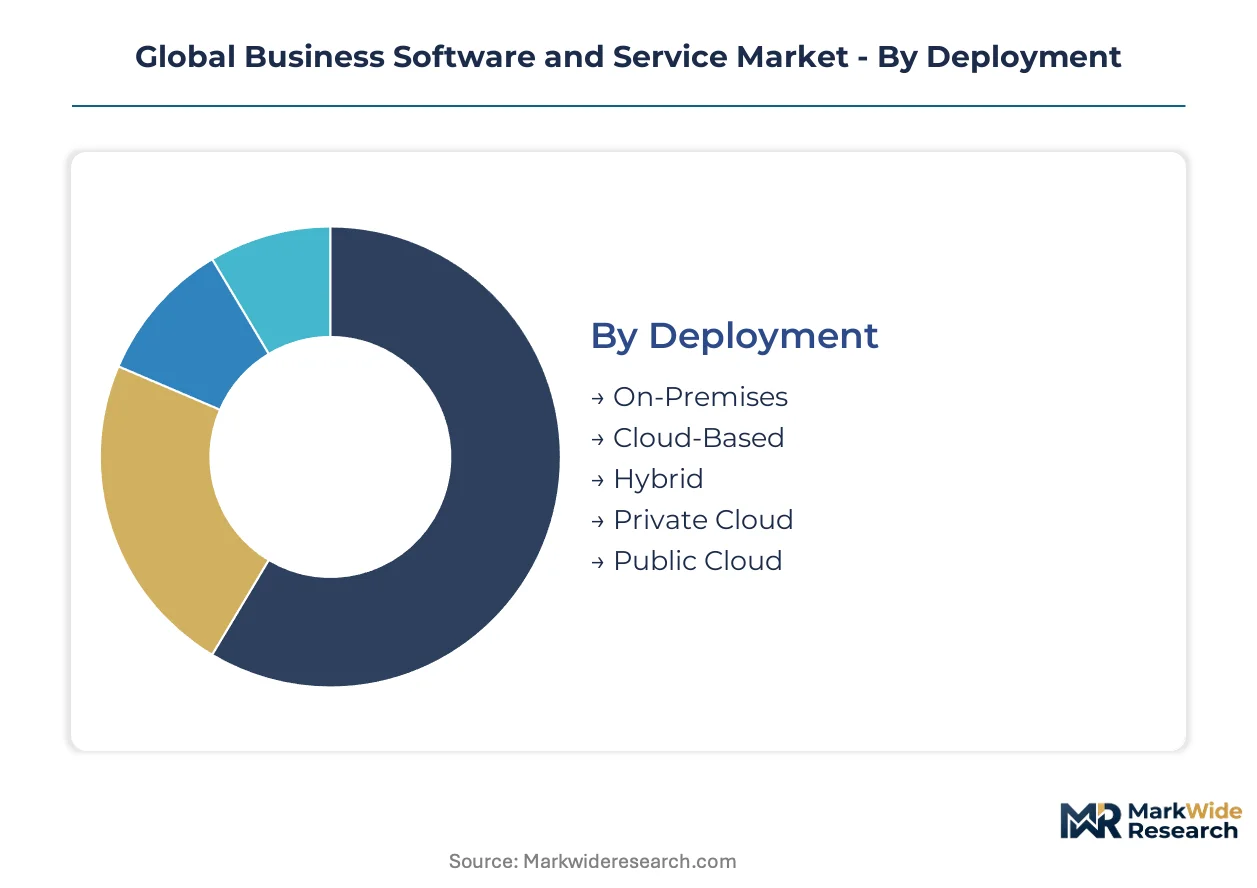
Enterprise software procurement patterns diverge sharply across deployment architectures, solution categories, and service models. Vendors must align pricing structures and implementation roadmaps with distinct technical requirements and compliance obligations within each segment.
Deployment:
Supply concentration in hyperscale infrastructure is reshaping how enterprises provision compute resources across sovereignty boundaries.
- On-Premises:Dedicated hardware installations within enterprise-controlled data centers deliver sub-millisecond latency for algorithmic trading systems. German automotive manufacturers and Japanese financial institutions retain these deployments to satisfy METI and BSI audit requirements for sensitive operational data.
- Cloud-Based:Multi-tenant architectures abstract infrastructure management through subscription consumption models. Singaporean fintech startups and South Korean e-commerce platforms drive demand for elastic capacity that scales with transaction volumes during peak retail periods.
- Hybrid:Partitioned workloads span sovereign private infrastructure and public cloud capacity. Enterprises in the United Kingdom and Netherlands deploy this architecture to balance GDPR data residency mandates with cost optimization.
- Private Cloud:Single-tenant virtualized environments deliver dedicated resource pools without shared infrastructure risks. Swiss pharmaceutical manufacturers and Australian healthcare providers favor this model for patient data processing.
- Public Cloud:Shared infrastructure services from hyperscale providers enable rapid provisioning without capital expenditure. Indian SaaS startups and Brazilian agribusinesses leverage this segment for geographic expansion.
Cloud-Based deployments absorb the bulk of installed capacity; Hybrid architectures are expanding most quickly among regulated industries.
Solution Type:
Application maturity curves determine margin structures and renewal economics across functional categories.
- Enterprise Resource Planning:Integrated modules for finance, procurement, and operations form the backbone of manufacturing execution. Bavarian industrial clusters and Osaka precision engineering firms maintain extensive customization layers that complicate migration.
- Customer Relationship Management:Unified customer data platforms embed predictive analytics for sales forecasting. United States-based technology vendors and United Kingdom retail banking networks invest heavily in generative AI enhancements for service automation.
- Supply Chain Management:Multi-echelon inventory optimization and demand sensing tools coordinate distributed production networks. Automotive OEMs in Stuttgart and pharmaceutical distributors in Basel deploy these systems for serialization compliance.
- Human Capital Management:Workforce planning, payroll, and talent acquisition modules standardize HR operations across multinational footprints. French luxury goods conglomerates and Indian IT services firms drive adoption of skills-based talent marketplaces.
- Business Intelligence:Data visualization and augmented analytics platforms democratize access to operational metrics. Dutch logistics operators and Israeli cybersecurity vendors leverage embedded machine learning for anomaly detection.
Enterprise Resource Planning retains the deepest installed base; Customer Relationship Management is climbing the fastest as sales organizations consolidate point solutions.
End User Industry:
Vertical-specific compliance requirements and transaction patterns shape solution configuration and pricing power.
- Manufacturing:Shop-floor integration, quality management, and predictive maintenance applications dominate software portfolios. Discrete manufacturers in Baden-Württemberg and process industries in Houston prioritize MES-ERP connectivity for OEE optimization.
- Telecommunications:OSS/BSS modernization and network inventory management drive transformation spending. 5G rollout timelines in South Korea and spectrum auction obligations in India accelerate cloud-native replacement cycles.
- Transportation:Fleet optimization, route planning, and freight matching platforms coordinate multimodal logistics. Container shipping lines in Copenhagen and last-mile delivery networks in São Paulo invest in real-time visibility tools.
- Financial Services:Core banking replacement, risk calculation engines, and regulatory reporting systems consume substantial IT budgets. EU AI Act compliance deadlines in Frankfurt and SEC cybersecurity disclosure rules in New York reshape procurement priorities.
- Education:Student information systems, learning management platforms, and alumni engagement tools support institutional operations. Research universities in Massachusetts and vocational training networks in Ontario modernize legacy administrative systems.
Financial Services commands the highest per-seat pricing; Manufacturing is gaining share fastest as Industry 4.0 investments accelerate.
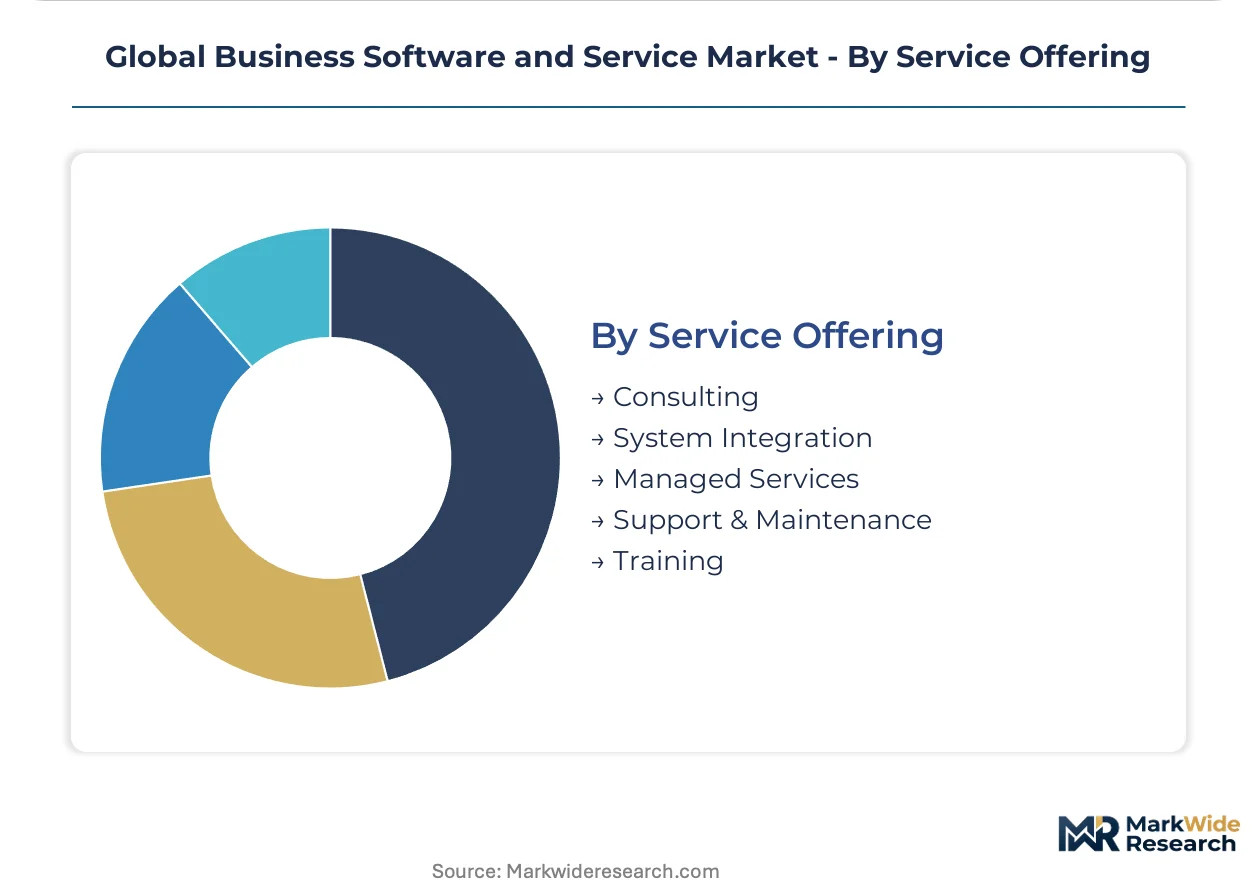
Service Offering:
Professional services attachment rates vary with solution complexity and internal IT capabilities across customer segments.
- Consulting:Business process reengineering and digital transformation advisory defines implementation scope. Large-scale SAP migrations at German industrial conglomerates and Oracle cloud transitions at US healthcare systems require extensive change management support.
- System Integration:API development, data migration, and middleware deployment connect heterogeneous application landscapes. Salesforce-Workday integrations at London-based professional services firms and Microsoft Dynamics extensions at Nordic manufacturers represent typical engagements.
- Managed Services:Outsourced application management and infrastructure monitoring transfer operational accountability. Mid-market enterprises in Australia and Canada favor this model to address cybersecurity skill shortages.
- Support & Maintenance:Break-fix services, patch management, and version upgrade assistance sustain production environments. Japanese enterprises with extended ERP support contracts represent a concentrated renewal revenue pool.
- Training:Certification programs and end-user enablement accelerate adoption curves. Salesforce Trailhead-style credentialing and SAP Learning Hub subscriptions compete for individual learner budgets.
Consulting captures the largest share of services revenue; Managed Services is expanding most quickly as IT talent scarcity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Bangalore concentrate software development talent pools that attract multinational captive centers. These zones offer tax holidays and simplified regulatory pathways that accelerate foreign direct investment. The resulting infrastructure clusters reshape regional competitive dynamics.
United States
SEC cybersecurity disclosure rules drive procurement of governance-embedded platforms among Fortune 500 financial institutions. The Securities and Exchange Commission mandates incident reporting timelines that compress vendor selection cycles. Silicon Valley and Seattle metropolitan areas host hyperscale cloud infrastructure that anchors generative AI development pipelines.
Germany
Industrial software demand concentrates in automotive and precision manufacturing verticals across Baden-Württemberg and Bavaria. The EU AI Act's risk classification framework mandates algorithmic impact assessments for automated decision systems. Stuttgart industrial clusters deploy MES-ERP connectivity solutions for OEE optimization in discrete manufacturing.
China
Data localization requirements under national cybersecurity law fragment cloud architecture standards for multinational enterprises. The Ministry of Industry and Information Technology enforces GB standards for information security management systems. Shenzhen Special Economic Zone concentrates SaaS development talent that serves domestic e-commerce and fintech platforms.
Japan
METI audit requirements sustain on-premises infrastructure deployments among mainframe-dependent financial institutions. The Ministry of Economy, Trade and Industry mandates operational technology security standards for critical infrastructure operators. Osaka precision engineering firms balance legacy system entrenchment with gradual API-first architecture migration.
Singapore
Monetary Authority of Singapore guidelines on cloud risk management accelerate hybrid deployment adoption among ASEAN fintech startups. The country's data protection framework permits cross-border data flows under adequacy arrangements that reduce compliance friction. Marina Bay financial district concentrates regional headquarters procurement decisions for enterprise software suites.
Global Business Software and Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform consolidation favoring integrated suites over point solutions. The vendor base organizes around three strategic tiers: hyperscale cloud providers with infrastructure-to-application vertical integration, enterprise software incumbents with deep industry-specific process logic, and best-of-breed challengers with narrow functional excellence. Dominant competitive moves include strategic partnerships that embed AI capabilities into core workflows and geographic expansion through localized data residency infrastructure.
Within the hyperscale tier, Microsoft Corporation and Oracle Corporation exemplify divergent approaches to platform consolidation. Microsoft leverages Azure infrastructure to anchor generative AI throughout productivity and ERP modules. Oracle sustains database-to-application vertical integration that competes in high-transaction environments. SAP SE occupies a position as the specialist in industry-specific process logic across European industrial clusters.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Salesforce Inc. |
| Adobe Inc. |
| ServiceNow |
| Workday Inc. |
| Intuit Inc. |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic impact assessment mandates gate qualified supply access and premium-tier pricing for governance-embedded platforms, compressing vendor margins while rewarding certified incumbents. Financial institutions in Frankfurt and Singapore demand audit-ready systems that command 40-60% price premiums over uncertified alternatives.
Pricing Analysis
Short lead-time deployments command substantial premiums as German automotive manufacturers and Japanese financial institutions pay for accelerated ISO 27001 certification cycles. Subscription-based SaaS tiers dominate, with price differentiation anchored in GDPR compliance grade and vertical-specific customization depth. Cost compression in mid-market standard tiers intensifies as consumption-based pricing replaces seat-count models. Small and medium enterprises exhibit highest price sensitivity; hyperscale cloud consumers least.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for critical middleware components across United States, Ireland, and Singapore data center footprints. Software supply chains draw from Indian development centers, Israeli cybersecurity specialists, and Estonian digital infrastructure providers. Single-source vulnerability concentrates in generative AI model training pipelines. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where database-to-application control and infrastructure ownership determine margin capture. Players pursue downstream service revenue attachment as the decisive lever.
For Market Incumbents: Acquire specialized RegTech compliance modules to fortify against best-of-breed challengers. SAP and Oracle must embed EU AI Act audit automation directly into core ERP workflows before governance-embedded platforms displace their installed base. Certification infrastructure investments in Frankfurt and Singapore data centers anchor premium pricing power.
For New Entrants and Emerging Players: Capture mid-market manufacturing verticals in Baden-Württemberg and Osaka where legacy MES-ERP integration gaps persist. Agentic AI orchestration for supply chain workflows represents the most penetrable white space. Partner with systems integrators lacking proprietary middleware development capabilities.
For Investors and Strategic Acquirers: ISO 27001 certification backlog expansion is the leading indicator that cybersecurity-governance convergence will drive consolidation premiums. Five-to-ten year viability favors platforms with sovereign cloud infrastructure in three or more regulatory jurisdictions. Watch MLOps talent compensation inflation as the signal for inorganic capability acquisition urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure anchors generative AI across productivity suites, compressing standalone RPA vendor relevance. |
| Acquisition of Specialist Firm | RegTech compliance automation targets address EU AI Act certification bottlenecks in Frankfurt financial services. |
| Geographic Expansion | Sovereign cloud infrastructure in Singapore and Switzerland satisfies data residency mandates for pharmaceutical manufacturers. |
| Strategic Partnership | Salesforce-Workday integration partnerships capture professional services firms migrating to unified customer data platforms. |
| Product Launch | Agentic AI systems unifying ERP-CRM-supply chain workflows threaten standalone automation vendors. |
Research Methodology
Independent corroboration across CTO interviews, IT procurement officer surveys, and platform engineer assessments underwrites the qualitative findings. Primary fieldwork engaged chief information security officers at German automotive manufacturers, Singaporean fintech compliance leads, and United States healthcare system integration specialists. Secondary validation drew from SEC cybersecurity disclosure filings, hyperscaler capital expenditure disclosures, and ISO 27001 certification registry data. Bottom-up deployment model estimates triangulated against top-down market size benchmarks.
Rate-of-change decomposition structured the analytical framework across deployment architecture, organization size tier, vertical industry, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from segment-level adoption curves weighted by contract value concentration. Forecast inputs incorporated EU AI Act implementation timelines and cloud infrastructure capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to divergent sovereignty frameworks across China, India, and the European Union. Deviation in MLOps talent availability or generative AI training cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Desktop Hypervisor Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
User Feedback Software Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
OCR Scanning Software Market
Software & Services
Global Data Recovery Software Market
Software & Services
3PL Software Market
Software & Services
Movie Editing Software Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Lead Management Software Market
Software & Services
Workstation Software Market
Software & Services
POS Software Market
Software & Services
File Analysis Software Market