
 Global Personalisation Software Market | 2026-2036
Global Personalisation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personalisation Software Market Foresight
Subscription-based financing and usage-metered cloud contracts is rewriting competitive entry barriers for mid-sized retailers seeking enterprise-grade personalisation. Optimizely leverages its experimentation heritage to anchor premium pricing in the A/B testing layer. Salesforce.com Inc. sustains platform stickiness through native CRM integration that reduces data pipeline costs. Segment competes on data infrastructure neutrality, allowing clients to avoid vendor lock-in across the activation stack.
Personalisation software encompasses algorithmic systems that ingest behavioral signals, demographic attributes, and contextual variables to dynamically tailor digital content, product assortments, and messaging across customer touchpoints. These platforms typically operate through real-time decisioning engines with sub-100-millisecond latency requirements, serving their primary commercial purpose of improving conversion rates and customer lifetime value. Cloud-based deployment dominates solution delivery due to elastic scaling requirements during peak retail events, while behavioral targeting captures the deepest margin pools as brands prioritize intent-based segmentation over basic demographic filtering. Content personalisation represents the fastest-growing solution category as publishers and streaming services compete for attention retention.
The EU AI Act imposes algorithmic transparency obligations on automated decisioning systems, while GDPR restricts profiling without explicit consent, collectively elevating compliance costs for vendors serving European enterprises. The FDA has begun scrutinizing health-related personalisation claims in digital therapeutics, creating precedent that could extend to wellness-oriented consumer applications. Stakeholders must monitor how China's SAMR enforces algorithmic recommendation regulations on cross-border software providers, as this will determine market access architecture for global platforms.
Market Dynamics
Real-time decisioning latency requirements below 100 milliseconds are compressing vendor margins while forcing infrastructure investments in edge computing architectures and specialized GPU clusters.
Growth Catalysts
- EU AI Act compliance mandates:Enterprises across Germany, France, and Italy must deploy auditable recommendation algorithms by 2026, creating replacement demand for legacy black-box systems.
- Streaming service subscriber retention wars:Netflix, Disney+, and regional platforms in South Korea and Brazil are expanding content personalisation budgets to reduce churn.
- First-party data activation:Retailers are rebuilding customer data platforms around server-side tagging to replace deprecating third-party cookies.
Market Restraints
- GDPR profiling restrictions:Explicit consent requirements for automated decisioning limit behavioral targeting depth in European markets.
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud control 65% of elastic compute supply, creating vendor lock-in risk during peak retail events.
- Technical talent scarcity:Machine learning engineers with sub-100ms optimization experience command premium compensation in San Francisco, London, and Singapore.
Strategic Opportunities
- India's digital commerce acceleration:Flipkart and Reliance JioMart are deploying vernacular-language personalisation for tier-2 and tier-3 city expansion.
- Healthcare digital therapeutics:FDA precedent on algorithmic wellness claims opens regulated personalisation for chronic disease management applications.
- Federated learning architectures:Privacy-preserving model training across distributed datasets addresses GDPR constraints without centralizing sensitive behavioral data.
Industry Challenges
- Legacy CRM integration complexity:Enterprises with decades-old Salesforce or SAP installations face 12-18 month data pipeline reconstruction timelines.
- Algorithmic bias audit requirements:The EU AI Act mandates ongoing fairness testing for high-risk recommendation systems, demanding specialized compliance personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personalisation Software Market |
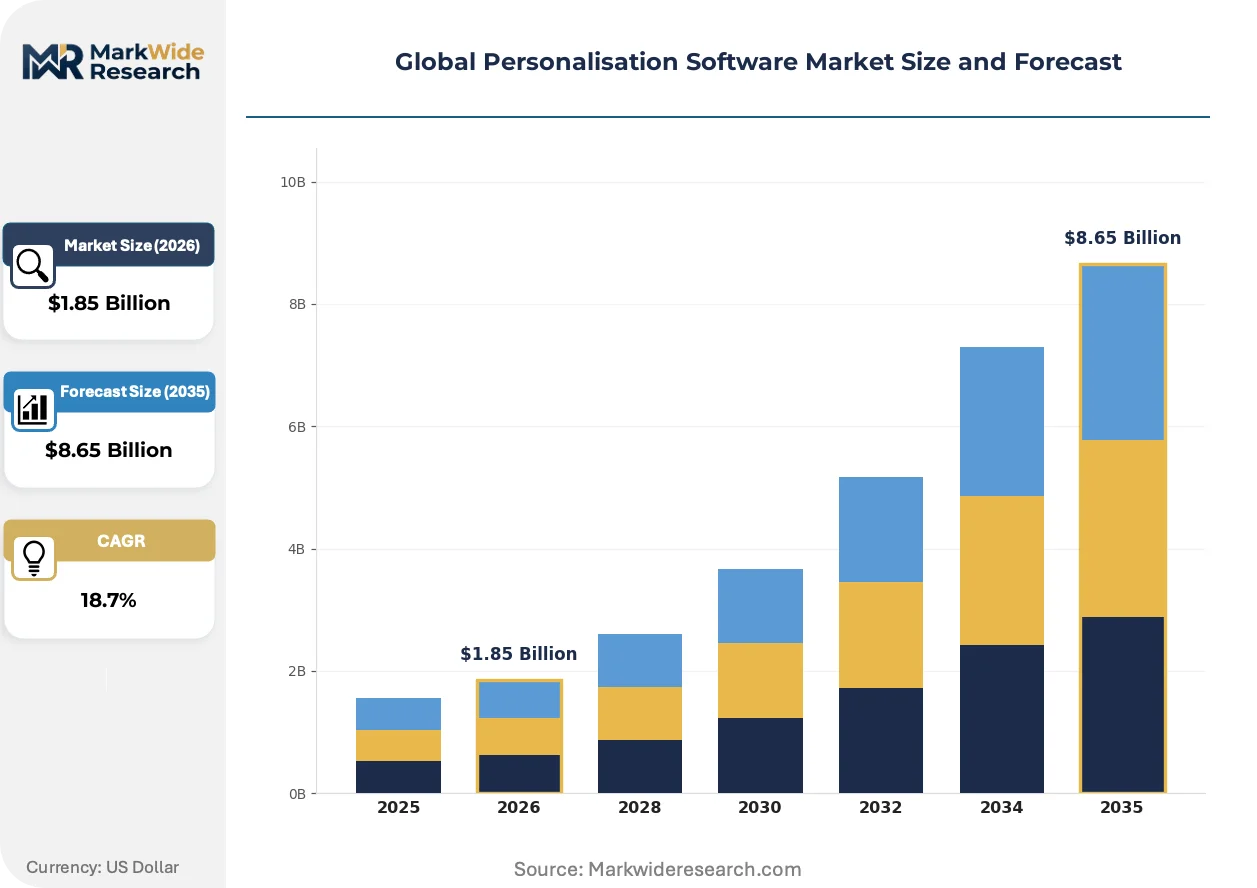
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution: Behavioral Targeting, Content Personalisation, Product Recommendation, Customer Profiling, Campaign Management Application: E-Commerce, Digital Publishing, Financial Services, Travel Booking, Telecommunications End User: Retailers, Publishers, Banks, Airlines, Telecom Operators |
| Companies Covered | Dynamic Yield, Optimizely, Segment, Adobe Inc., Salesforce.com Inc., Oracle Corporation, IBM Corporation, Marketo, MoEngage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personalisation Software Market Shifts & Advancements
Edge-deployed inference engines and federated learning protocols are redistributing computational load away from centralized cloud regions toward localized processing nodes.
Transformer-based large language models are virtualizing content generation pipelines, enabling streaming platforms and publishers to dynamically assemble headlines, descriptions, and promotional copy. Media companies in the United States and United Kingdom are deploying these systems for real-time A/B testing at scale. The technology is virtualizing traditional creative production workflows, compressing campaign launch cycles from weeks to hours.
The EU AI Act's algorithmic transparency obligations are forcing vendors to deploy explainable AI modules that surface decision logic to end-users. This regulatory pressure elevates engineering costs for European deployments while creating competitive differentiation for compliant architectures. Healthcare and financial services segments in Germany and the Netherlands are prioritizing vendors with pre-built audit trails.
Buyer procurement patterns are consolidating around usage-metered contracts that align software costs with actual recommendation volumes served. Mid-sized retailers in Australia and Canada are abandoning fixed annual licenses for elastic pricing tied to peak event traffic. This shift rewards vendors with granular infrastructure cost controls and penalizes those with rigid capacity planning.
Global Personalisation Software Market Segmentation
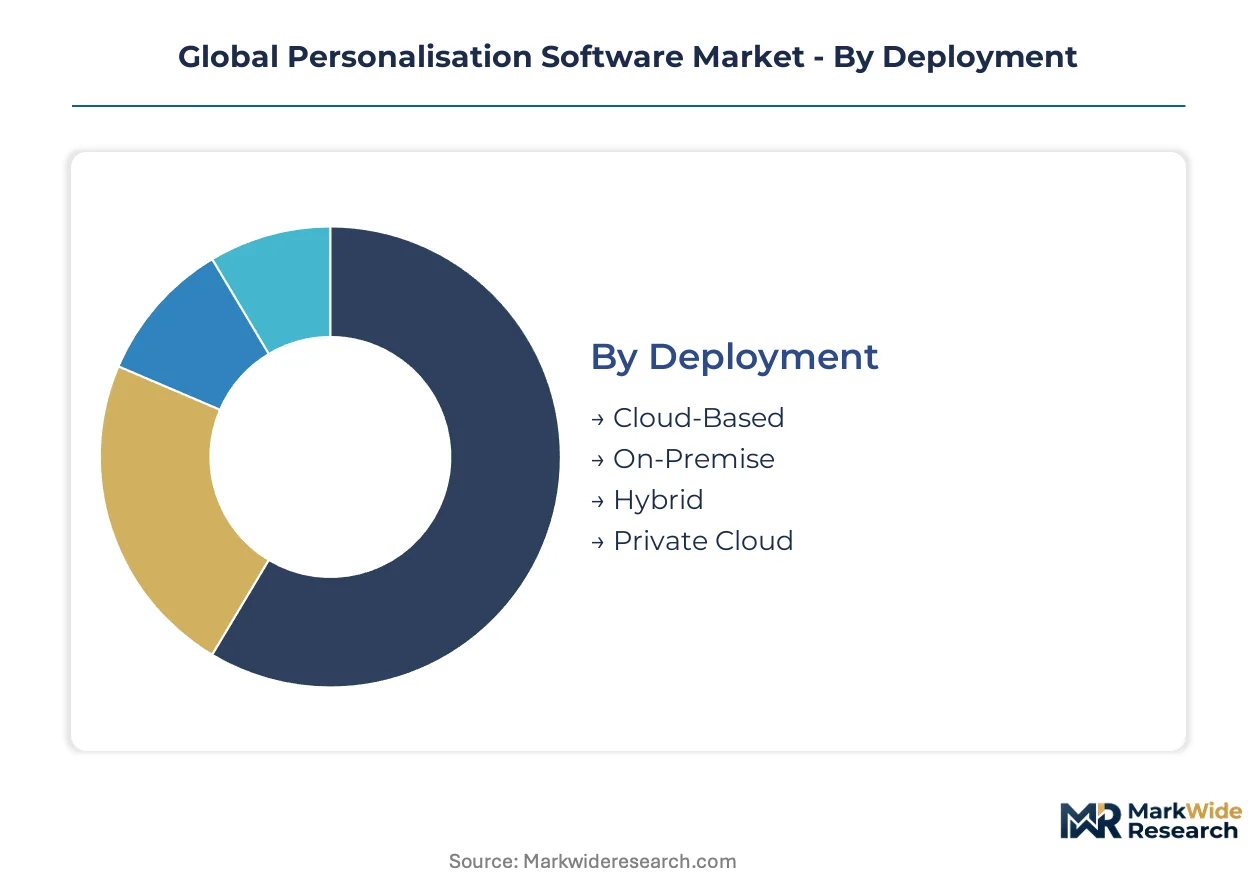
Personalisation software vendors architect their product lines around four distinct segmentation axes. Deployment mode determines infrastructure economics and compliance posture. Solution type maps to customer maturity and data sophistication. Application verticals expose divergent latency requirements and regulatory exposure. End-user scale shapes pricing models and implementation complexity.
Deployment:
Mature cloud architectures dominate enterprise procurement, though regulatory pressure is resurrecting on-premise and private cloud alternatives across Europe and Asia-Pacific.
- Cloud-Based:Elastic compute pools scale recommendation throughput during Black Friday and Singles' Day traffic spikes. AWS, Azure, and Google Cloud host the majority of production workloads, though EU AI Act data residency clauses are forcing regional instance commitments in Frankfurt and Amsterdam.
- On-Premise:Air-gapped deployments persist in German automotive and Swiss banking sectors where GDPR Article 44 cross-border transfer restrictions apply. Hardware refresh cycles extend 5-7 years, compressing vendor recurring revenue.
- Hybrid:Split architectures process PII on-premise while pushing anonymized model training to public cloud. Japanese manufacturers and South Korean conglomerates favor this pattern for operational technology integration.
- Private Cloud:Dedicated tenant environments address SAMR algorithmic audit requirements for foreign software providers operating in China. Sovereign cloud partnerships with local carriers are becoming mandatory for market access.
Cloud-Based retains volume leadership; Private Cloud holds the steepest expansion curve as data sovereignty mandates proliferate.
Solution:
Functional modules stratify by customer data maturity, with basic demographic filtering giving way to real-time behavioral inference.
- Behavioral Targeting:Intent scoring engines process clickstream, scroll depth, and session duration signals to predict purchase probability. Retailers in the United States and United Kingdom allocate the largest budgets here, though GDPR consent friction limits European deployment depth.
- Content Personalisation:Transformer models dynamically assemble headlines, thumbnails, and promotional copy. Streaming platforms in Brazil and South Korea are expanding investment fastest as subscriber acquisition costs climb.
- Product Recommendation:Collaborative filtering and neural architectures match users to SKUs. E-commerce marketplaces in India deploy vernacular-language models for tier-2 city expansion.
- Customer Profiling:Unified identity graphs consolidate first-party data across touchpoints. Server-side tagging rebuilds are accelerating post-third-party cookie deprecation.
- Campaign Management:Orchestration layers sequence multi-channel messaging. Mid-market retailers in Australia and Canada are consolidating point solutions into integrated suites.
Behavioral Targeting commands the largest revenue pool; Content Personalisation is climbing the fastest as generative AI compresses production cycles.
Application:
Vertical-specific latency requirements and regulatory exposure create divergent vendor specialization patterns.
- E-Commerce:Sub-100 millisecond recommendation serving during checkout flows. Amazon and Flipkart infrastructure investments set performance benchmarks competitors must match.
- Digital Publishing:Paywall optimization and article recommendation for retention. Publishers in the United Kingdom and Germany face GDPR subscription consent complexity.
- Financial Services:Algorithmic transparency mandates under EU AI Act Article 52 constrain black-box credit and insurance personalization. Dutch and German banks prioritize audit-trail vendors.
- Travel Booking:Dynamic packaging of flights, hotels, and ancillary services. Airlines in the United States and Singapore leverage loyalty data for real-time pricing.
- Telecommunications:Churn prediction and upsell targeting across prepaid and postpaid segments. Indian and Indonesian operators deploy vernacular interfaces for rural market penetration.
E-Commerce anchors deployment volume; Financial Services is gaining share fastest as regulatory compliance creates replacement demand.
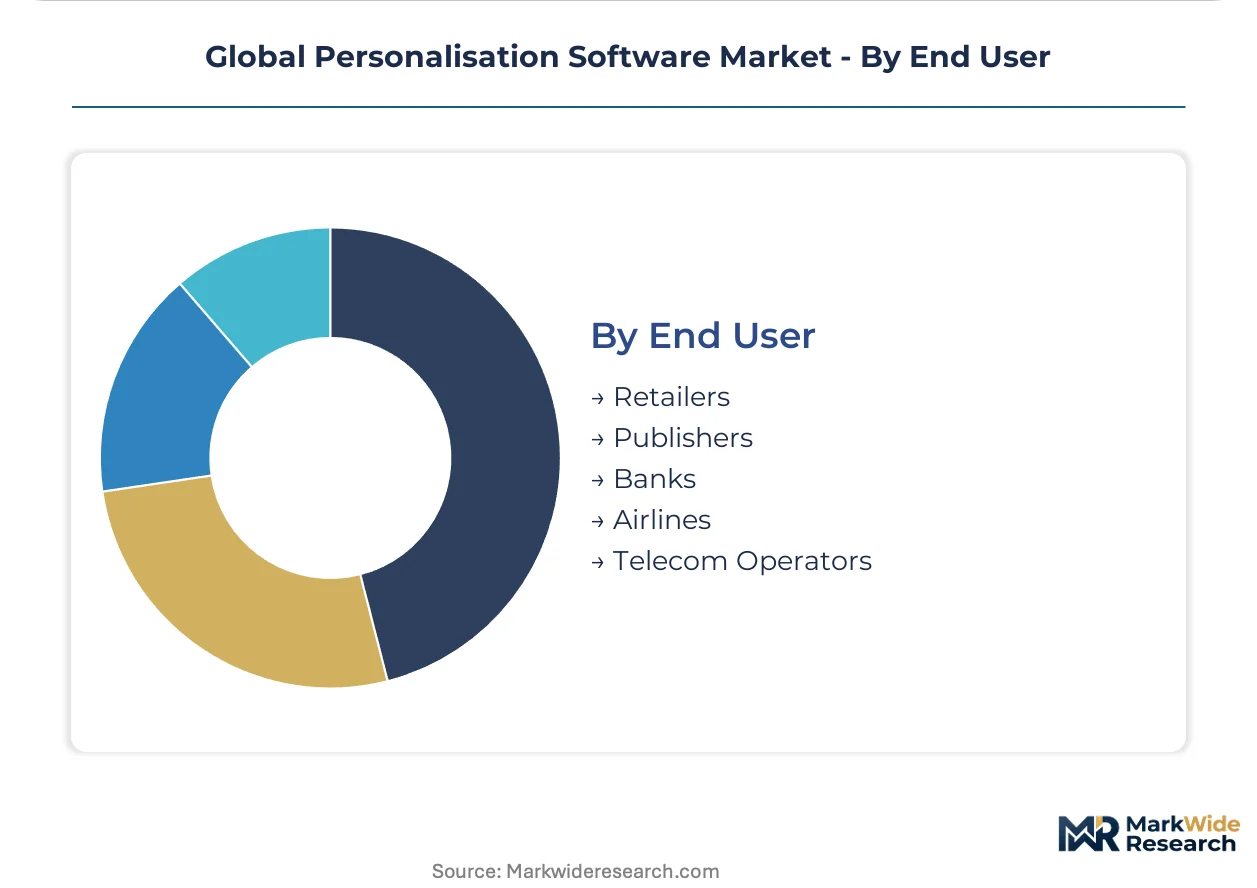
End User:
Procurement sophistication varies dramatically by organizational scale and data infrastructure heritage.
- Retailers:Omnichannel personalization spanning web, mobile, and in-store kiosk. Walmart and Target martech budgets exceed many national software markets.
- Publishers:Subscription retention and ad inventory optimization. New York Times and Axel Springer data strategies diverge on first-party versus third-party data reliance.
- Banks:Wealth management personalization and fraud-adaptive authentication. JPMorgan Chase and DBS Bank investment levels reflect digital transformation maturity gaps.
- Airlines:Loyalty program personalization and dynamic ancillary pricing. Delta and Singapore Airlines compete on predictive service recovery.
- Telecom Operators:Network usage personalization and digital service bundling. Reliance Jio and T-Mobile scale advantages reshape competitive dynamics.
Retailers retain volume leadership; Banks hold the steepest expansion curve as open banking data access proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise martech budgets in the United States command premium pricing multiples unavailable to vendors competing for share in India or Southeast Asia. This asymmetry reflects cloud infrastructure maturity gaps and differential regulatory compliance burdens across national markets.
United States
Walmart and Target deploy sub-100 millisecond recommendation engines across omnichannel touchpoints. The FTC scrutinizes algorithmic discrimination in credit and housing personalization, elevating vendor audit requirements. Seattle and San Francisco clusters concentrate machine learning engineering talent commanding compensation premiums that compress vendor margins.
Germany
Automotive OEMs and industrial conglomerates demand air-gapped, on-premise deployments for GDPR Article 44 compliance. The EU AI Act mandates algorithmic transparency modules for automated decisioning systems by 2026. Munich and Stuttgart industrial clusters prioritize vendors with pre-built audit trails for high-risk recommendation applications.
United Kingdom
Publishers like Axel Springer and News UK rebuild first-party data platforms around server-side tagging post-cookie deprecation. The Information Commissioner's Office enforces GDPR subscription consent complexity for paywall optimization. London's financial services sector drives demand for explainable AI in wealth management personalization.
India
Flipkart and Reliance JioMart deploy vernacular-language models for tier-2 and tier-3 city expansion. The Digital Personal Data Protection Act imposes consent-layer requirements on behavioral profiling systems. Bangalore and Hyderabad technology clusters host engineering centers optimizing recommendation latency for mobile-first commerce.
South Korea
Coupang and Naver compete on predictive delivery personalization and content recommendation retention. The Personal Information Protection Commission enforces strict cross-border data transfer limitations. Seoul's streaming platform ecosystem drives investment in transformer-based content generation for K-content global distribution.
Global Personalisation Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in data infrastructure and experimentation layers. The vendor landscape stratifies around three archetypes: cloud-native personalization engines, legacy enterprise marketing suites, and independent data infrastructure providers. Consolidation pressure intensifies as mid-sized retailers abandon point solutions for integrated suites. M&A activity targets experimentation heritage and first-party data activation capabilities.
Within the cloud-native tier, Optimizely and Segment exemplify divergent strategic positioning. Optimizely anchors premium pricing in A/B testing heritage, while Segment occupies data infrastructure neutrality that reduces client vendor lock-in. Salesforce.com Inc. sits within the enterprise marketing suite archetype, leveraging native CRM integration to reduce data pipeline costs for Fortune 500 deployments. Adobe Inc. represents the creative-cloud-adjacent positioning that bundles personalization with content production workflows.
| Leading Market Players |
|---|
| Dynamic Yield |
| Optimizely |
| Segment |
| Adobe Inc. |
| Salesforce.com Inc. |
| Oracle Corporation |
| IBM Corporation |
| Marketo |
| MoEngage |
| Others |
Supply & Pricing Matrix
AWS, Azure, and Google Cloud control two-thirds of elastic compute supply for real-time recommendation engines, concentrating infrastructure pricing power with hyperscalers while compressing vendor margins downstream. This upstream concentration forces personalisation software vendors to absorb cost volatility or pass through usage-metered contracts that shift risk to mid-sized retailers.
Pricing Analysis
Configured-to-order deployments command 40-60% premiums over standard SaaS tiers due to custom latency optimization and on-premise data residency requirements. Three-tier pricing structure across premium, standard, and economy levels aligns with integration complexity and recommendation throughput volumes. Cost compression in the mid-market tier is intensifying because usage-metered contracts from Australian and Canadian retailers demand granular infrastructure controls. Enterprise retailers with dedicated cloud infrastructure budgets exhibit lowest price sensitivity, while tier-2 e-commerce operators in emerging markets face acute margin constraints.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud contracts and supply-chain finance facilities are restructuring vendor working capital requirements, with 90-120 day receivables becoming standard for European enterprise deployments. GPU cluster provisioning draws from Taiwan, South Korea, and the United States for advanced semiconductor fabrication. Supply chain risk centers on single-source vulnerability for NVIDIA H100 and A100 inference accelerators, where foundry concentration creates allocation bottlenecks during peak retail events. Distribution runs through direct cloud marketplace listings and systems integrator channel partners for complex hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as mid-sized retailers abandon point solutions for integrated suites, consolidating procurement leverage around experimentation heritage and first-party data activation capabilities.
For Market Incumbents: Entrench platform stickiness through native CRM integration and server-side tagging infrastructure that increases switching costs. Deepen backward integration into edge computing hardware partnerships to secure sub-100 millisecond latency guarantees. Defend against cloud-native challengers by pre-building EU AI Act audit trail modules that accelerate compliance timelines for German automotive and financial services clients. For New Entrants and Emerging Players: Establish a beachhead in vernacular-language personalisation for Indian tier-2 and tier-3 city expansion, where Flipkart and Reliance JioMart infrastructure investments validate demand. Target federated learning architectures as a privacy-preserving wedge against centralized cloud incumbents constrained by GDPR cross-border transfer restrictions. Lead with usage-metered pricing transparency that contrasts with opaque enterprise license structures. For Investors and Strategic Acquirers: Capital is best deployed toward experimentation heritage platforms with pre-built statistical inference engines and established mid-market retailer relationships. Long-term viability favors vendors with vertical integration into data infrastructure neutrality rather than point-solution personalisation layers. Watch hyperscaler marketplace certification velocity as an inflection indicator for distribution leverage consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and Adobe connectivity reduces data pipeline reconstruction timelines for legacy CRM enterprises. |
| Acquisition of Specialist Firm | Experimentation heritage from A/B testing vendors anchors premium pricing in statistical inference capabilities. |
| Geographic Expansion | Vernacular-language model deployment captures Indian tier-2 city commerce acceleration beyond metro saturation. |
| Strategic Partnership | Sovereign cloud alliances with European carriers satisfy EU AI Act data residency mandates for Frankfurt deployments. |
| Product Launch | Explainable AI modules surface decision logic to end-users, satisfying algorithmic transparency obligations under EU AI Act Article 52. |
Research Methodology
Desk research of SEC filings from public cloud providers, hyperscaler capex disclosures, and EU regulatory documentation preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists. Primary fieldwork with personalisation software vendors and enterprise martech buyers was cross-validated against secondary sources including App Annie mobile commerce data, Nielsen retail audit metrics, and customs records for GPU import flows. Bottom-up sizing of recommendation engine deployments was triangulated with top-down cloud infrastructure spend allocation models.
Fixed assumptions included sustained third-party cookie deprecation timelines, EU AI Act enforcement commencing 2026, and cloud infrastructure concentration ratios across the analysis window. Segmentation dimensions modeled encompass deployment architecture, organization scale, vertical application, integration complexity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted throughput projections and vendor pricing trajectory analysis, with inputs from real-time decisioning latency requirements and compliance cost escalation curves.
Sensitivities concentrate around hyperscaler pricing power consolidation, GDPR enforcement variance across national data protection authorities, and transformer model inference cost trajectories. Forecasts reflect documented assumptions regarding cloud marketplace distribution velocity and enterprise martech budget allocation patterns. Macroeconomic contraction in retail discretionary spending, regulatory acceleration of algorithmic audit requirements, or breakthrough federated learning commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Global Journal App Market
Software & Services
Global OEE Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
Global Board Management Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
High Education Software Market
Software & Services
Lending Software Market
Software & Services
Dealer Management System Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Global Video Streaming Software Market
Software & Services
Account-Based Direct Mail Software Market
Software & Services
Vacation Rental Software Market
Software & Services
Vlog Editing Software Market