
 Global Cloud Testing Market | 2026-2036
Global Cloud Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Testing Market Foresight
The EU Green Deal is shifting enterprise procurement criteria toward energy-efficient cloud infrastructure, compelling vendors to redesign testing platforms for lower carbon intensity. Microsoft leverages its Azure sustainability metrics to anchor enterprise contracts in regulated European industries. Amazon Web Services competes through dedicated local zones that reduce latency for compliance-sensitive workloads. Sauce Labs specializes in browser-automation grids optimized for renewable-energy data centers, differentiating its environmental positioning against conventional providers.
Cloud testing encompasses the remote execution of software quality assurance across distributed virtual environments, utilizing containerized browser instances, synthetic user agents, and API emulation protocols to validate application performance before production deployment. The primary commercial purpose is to eliminate capital expenditure on physical device labs while enabling parallel test execution at elastic scale. Public cloud deployment leads volume adoption due to pay-per-use economics, yet hybrid cloud configurations capture margin concentration from enterprises with data residency requirements. Security testing solutions are expanding fastest as zero-trust architecture mandates proliferate across financial services and government verticals.
FDA guidelines for software-as-a-medical-device, EMA's cybersecurity expectations for health applications, and India's BIS cloud standards collectively shape product certification requirements and market access conditions for testing platform vendors. The EU AI Act further imposes conformity obligations on automated decision systems that rely on cloud-validated machine learning pipelines. Stakeholders must monitor evolving cross-border data governance frameworks to anticipate where testing infrastructure localization becomes mandatory versus where centralized global delivery remains permissible.
Market Dynamics
Zero-trust architecture mandates from financial services and government verticals are compressing testing cycles while forcing infrastructure localization decisions across distributed cloud environments.
Growth Catalysts
- FDA software-as-a-medical-device guidelines:Health technology developers require validated cloud testing pipelines for regulatory submission, expanding platform demand across digital therapeutics and diagnostic applications.
- Containerized browser grids:Synthetic user agents enable parallel execution across thousands of virtual device configurations, eliminating physical device lab capital expenditure for mobile application developers.
- Financial services migration:Banks and insurers in the United States, Germany, and India are retiring on-premise quality assurance infrastructure for elastic cloud consumption models.
Market Restraints
- Data residency compliance costs:The EU AI Act and India's BIS cloud standards impose infrastructure localization requirements that fragment platform economics and duplicate operational overhead.
- Specialized talent scarcity:Shortage of engineers proficient in both cloud-native architectures and security testing protocols constrains enterprise adoption velocity.
- Legacy integration friction:Mainframe and on-premise enterprise resource planning systems resist API-based test automation, requiring costly middleware development.
Strategic Opportunities
- EU Green Deal procurement criteria:Energy-efficient testing platforms gain preferential vendor status in European enterprise tenders, rewarding renewable-energy data center investments.
- API-first security validation:Microservices architectures in fintech and health technology create demand for continuous automated penetration testing integrated into CI/CD pipelines.
- Hybrid cloud configurations:Enterprises with sovereignty requirements seek split deployments combining public cloud scale with private infrastructure for sensitive workloads.
Industry Challenges
- Cross-border data governance fragmentation:Divergent localization requirements between the EU AI Act, FDA submission protocols, and India's BIS standards complicate global platform delivery models.
- Skills gap in ML pipeline validation:Shortage of engineers capable of testing automated decision systems under emerging conformity obligations slows AI application deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Testing Market |
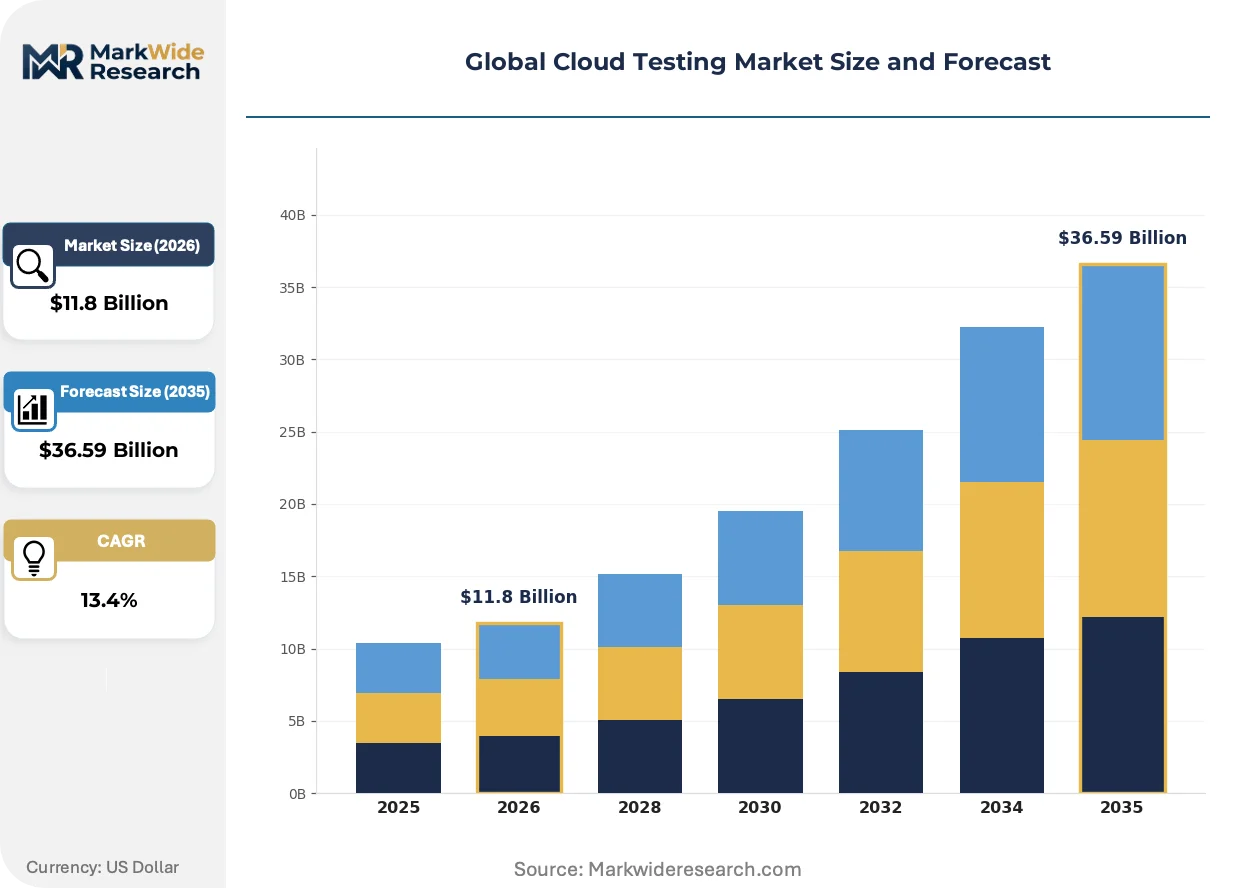
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $36.59 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Performance Testing, Functional Testing, Security Testing, Compatibility Testing, Usability Testing Application: E-Commerce Platforms, Financial Services, Telecommunications, Education Technology, Government Services End User: IT Service Providers, Software Vendors, Independent Software Testers, Managed Service Vendors |
| Companies Covered | LambdaTest, Microsoft, Amazon Web Services, Perfecto, Oracle Corporation, Sauce Labs, IBM, Akamai Technologies, BrowserStack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Testing Market Shifts & Advancements
Synthetic testing environments are displacing physical infrastructure while regulatory fragmentation forces architectural adaptation across compliance jurisdictions.
Chaos engineering is expanding into production-adjacent testing workflows. Platform teams at financial services and e-commerce operators inject controlled failures into distributed systems to validate resilience before peak traffic events. This practice compresses mean-time-to-detection for latency anomalies and database connection failures.
The EU AI Act imposes conformity assessment obligations on automated decision systems that rely on cloud-validated machine learning pipelines. Health technology and credit scoring vendors must document testing protocols for bias detection and performance drift. European national regulators are developing sector-specific guidance that affects platform certification requirements.
Consumption-based pricing models are displacing fixed-term enterprise agreements in mid-market segments. DevOps teams prefer metered access to browser automation grids over annual commitments. This shift is most visible among Series B and C software companies in the United States and Germany seeking capital-efficient quality assurance scaling.
Global Cloud Testing Market Segmentation
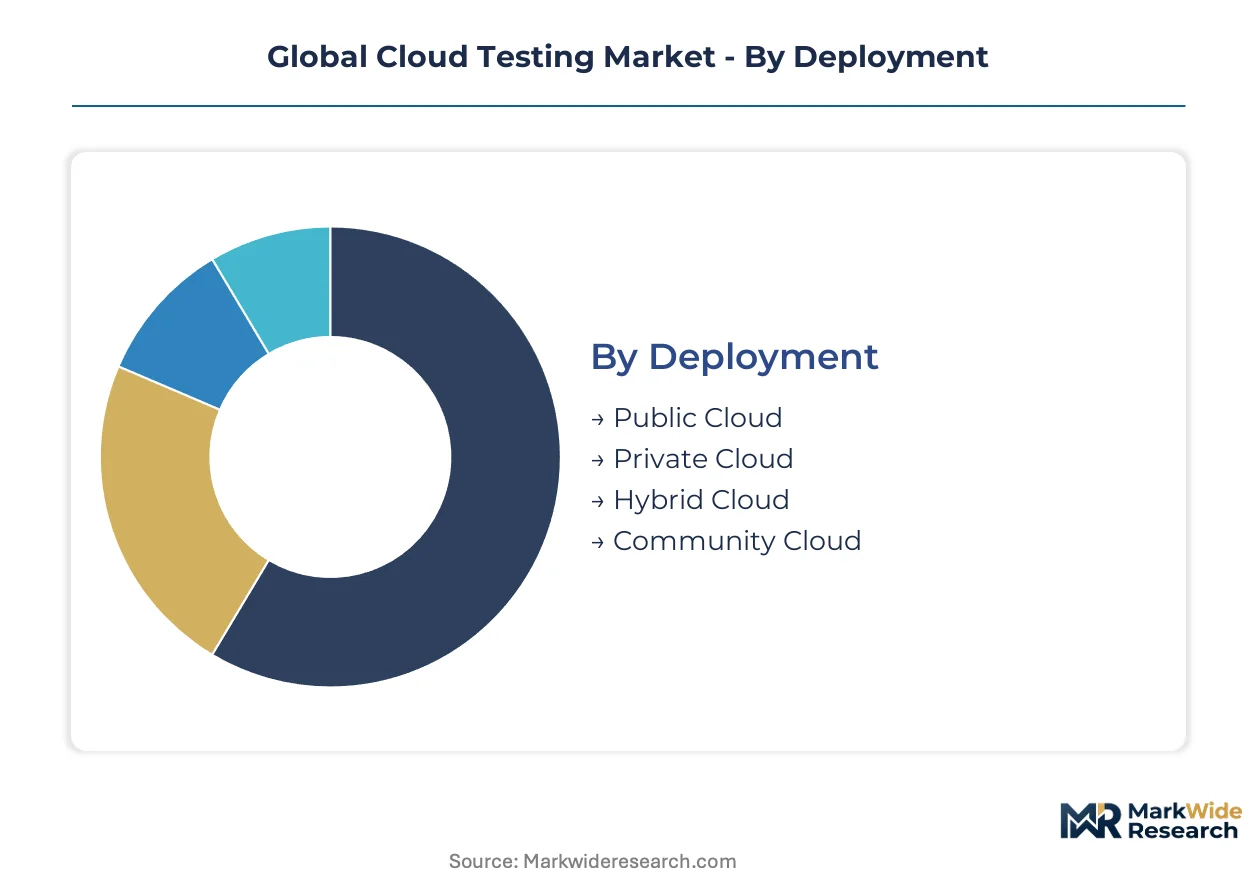
Cloud testing architectures fragment across deployment models, solution types, and vertical applications as enterprises balance elasticity against compliance mandates. Procurement patterns diverge sharply between capital-constrained software vendors and regulated financial institutions with data sovereignty requirements.
Deployment:
Upgrade cycles from on-premise infrastructure are compressing as container orchestration matures and hybrid management tools standardize.
- Public Cloud:Elastic compute pools enable pay-per-execution testing without reserved capacity commitments. Financial services firms in the United States and Germany favor this model for non-production workloads where data classification permits external hosting.
- Hybrid Cloud:Split architectures route sensitive test data through private infrastructure while bursting peak loads to public endpoints. India's BIS cloud standards and the EU AI Act are accelerating adoption among enterprises with cross-border data governance obligations.
- Private Cloud:Dedicated virtualization stacks serve defense contractors and government agencies with air-gapped security requirements. Capital intensity limits deployment to large enterprises with established data center footprints.
- Community Cloud:Shared infrastructure among industry consortiums reduces compliance duplication for health technology developers navigating FDA software-as-a-medical-device guidelines.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest.
Solution Type:
Security testing commands premium pricing as zero-trust mandates proliferate across financial services and government verticals.
- Security Testing:Automated penetration testing and vulnerability scanning integrate into CI/CD pipelines for fintech microservices. The EU AI Act imposes conformity obligations on automated decision systems that require validated security protocols.
- Performance Testing:Load generation and latency measurement validate application behavior under synthetic traffic spikes. E-commerce operators in Germany and India deploy these tools before seasonal demand peaks.
- Functional Testing:Regression suites verify business logic across browser and mobile configurations. DevOps teams in the United States favor containerized execution grids for parallel test distribution.
- Compatibility Testing:Cross-browser and cross-device validation ensures consistent rendering across fragmented endpoint ecosystems. Mobile application developers rely on synthetic device farms to eliminate physical lab expenditure.
- Usability Testing:Synthetic user agents and heatmap analytics capture interaction patterns without human panel recruitment. Education technology vendors use these capabilities to validate accessibility compliance.
Security Testing captures the highest margin tier, with Performance Testing expanding most quickly.
Application:
Vertical specialization is deepening as sector-specific regulators mandate validated testing protocols for market access.
- Financial Services:Banks and insurers in the United States, Germany, and India are retiring on-premise quality assurance infrastructure. Zero-trust architecture mandates from Basel Committee guidance and national regulators compress testing cycles while forcing localization decisions.
- E-Commerce Platforms:Peak traffic events require elastic load testing before Black Friday and Diwali shopping seasons. Chaos engineering practices validate resilience against database connection failures and latency anomalies.
- Telecommunications:Network function virtualization demands continuous validation of 5G service orchestration. Indian operators under TRAI guidelines invest in automated regression for billing and provisioning systems.
- Government Services:Federal agencies in the United States and national ministries in Germany require FedRAMP and BSI-compliant testing environments. Data residency restrictions favor domestic cloud providers with certified facilities.
- Education Technology:Accessibility testing for learning management platforms serves K-12 and higher education procurement criteria. Section 508 and WCAG conformance drive automated validation demand.
Financial Services anchors revenue concentration, with Government Services gaining share fastest.
End User:
Service provider consolidation is reshaping procurement patterns as enterprises outsource testing operations to specialized vendors.
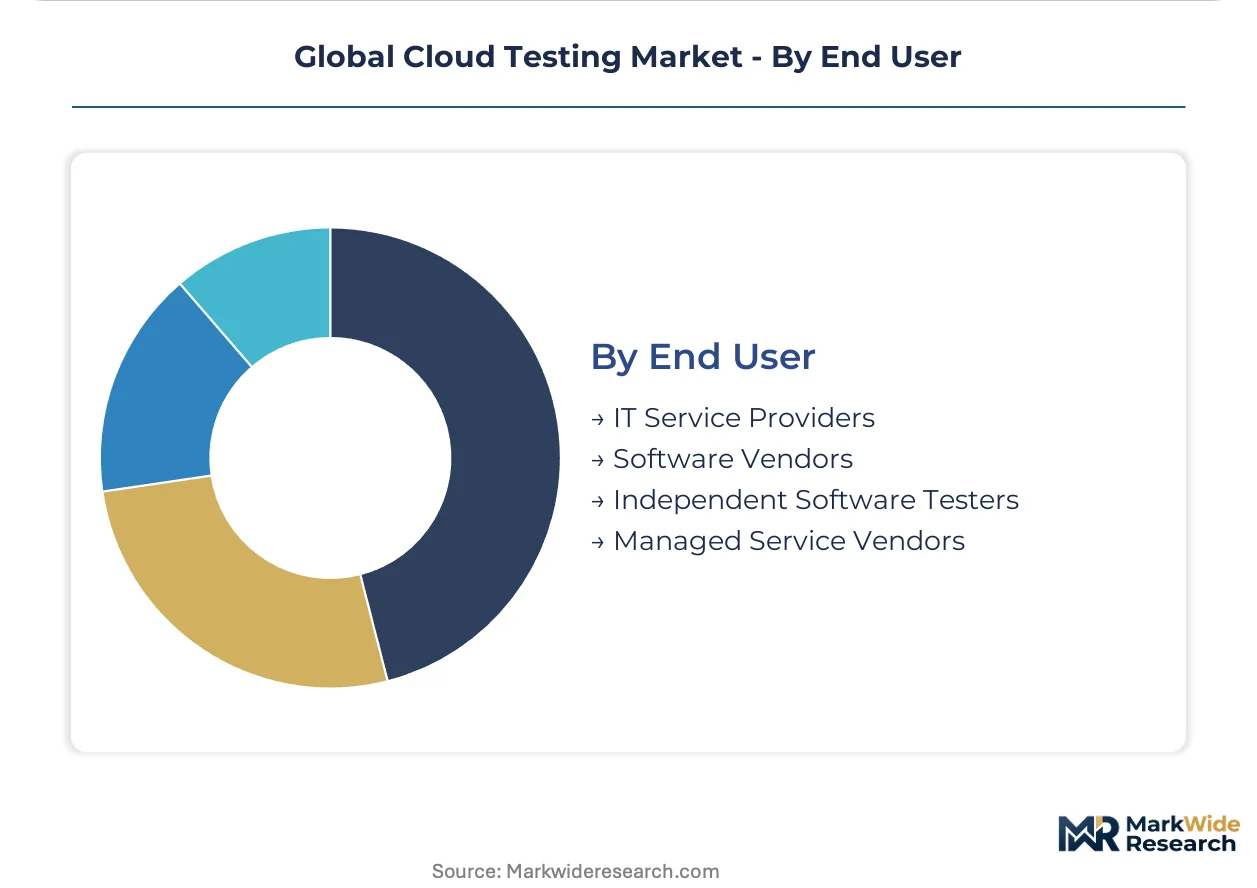
- IT Service Providers:Systems integrators embed testing platforms into managed transformation contracts for legacy modernization. Accenture and TCS scale delivery through proprietary automation frameworks layered over commercial cloud grids.
- Managed Service Vendors:Dedicated testing operations centers offer outcome-based pricing tied to defect detection rates. European providers leverage EU Green Deal criteria to differentiate renewable-energy data center commitments.
- Software Vendors:Product companies integrate testing into DevOps pipelines for continuous delivery. Series B and C companies in the United States and Germany prefer metered consumption over annual platform commitments.
- Independent Software Testers:Boutique specialists serve regulated industries with domain-specific validation expertise. FDA submission support for digital therapeutics commands premium hourly rates.
IT Service Providers dominate contract volume, with Managed Service Vendors expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud testing infrastructure originated in United States technology corridors during the early SaaS era, then diffused through European financial centers and Indian IT hubs as enterprises abandoned capital-intensive device labs for elastic consumption models.
United States
Financial services firms in New York and San Francisco dominate enterprise consumption, retiring on-premise quality assurance infrastructure for pay-per-use models. FDA software-as-a-medical-device guidelines compel health technology developers to maintain validated testing pipelines for regulatory submission. Silicon Valley product companies prefer metered access to browser automation grids over annual platform commitments.
Germany
Automotive and industrial software vendors in Munich and Stuttgart drive demand for hybrid cloud configurations balancing elasticity with data sovereignty. EU AI Act conformity obligations force automated decision system vendors to document testing protocols for bias detection. Frankfurt's financial services cluster invests heavily in zero-trust architecture validation for Basel Committee compliance.
India
IT service providers in Bengaluru and Hyderabad embed testing platforms into managed transformation contracts for global clients. BIS cloud standards impose infrastructure localization requirements that fragment platform economics for multinational vendors. Mumbai's banking sector accelerates migration from legacy quality assurance infrastructure under RBI digital transformation mandates.
United Kingdom
Fintech operators in London deploy chaos engineering practices to validate resilience before peak traffic events. Financial Conduct Authority cybersecurity expectations compress testing cycles while forcing architectural decisions across distributed environments. The Thames Valley technology corridor concentrates Series B and C software companies seeking capital-efficient quality assurance scaling.
Japan
Telecommunications operators in Tokyo and Osaka invest in automated regression for 5G service orchestration under METI digital infrastructure guidelines. Manufacturing software vendors require validated testing pipelines for industrial IoT applications. The Nagoya automotive technology cluster demands compatibility testing across fragmented endpoint ecosystems for connected vehicle platforms.
Global Cloud Testing Market Competitive Landscape
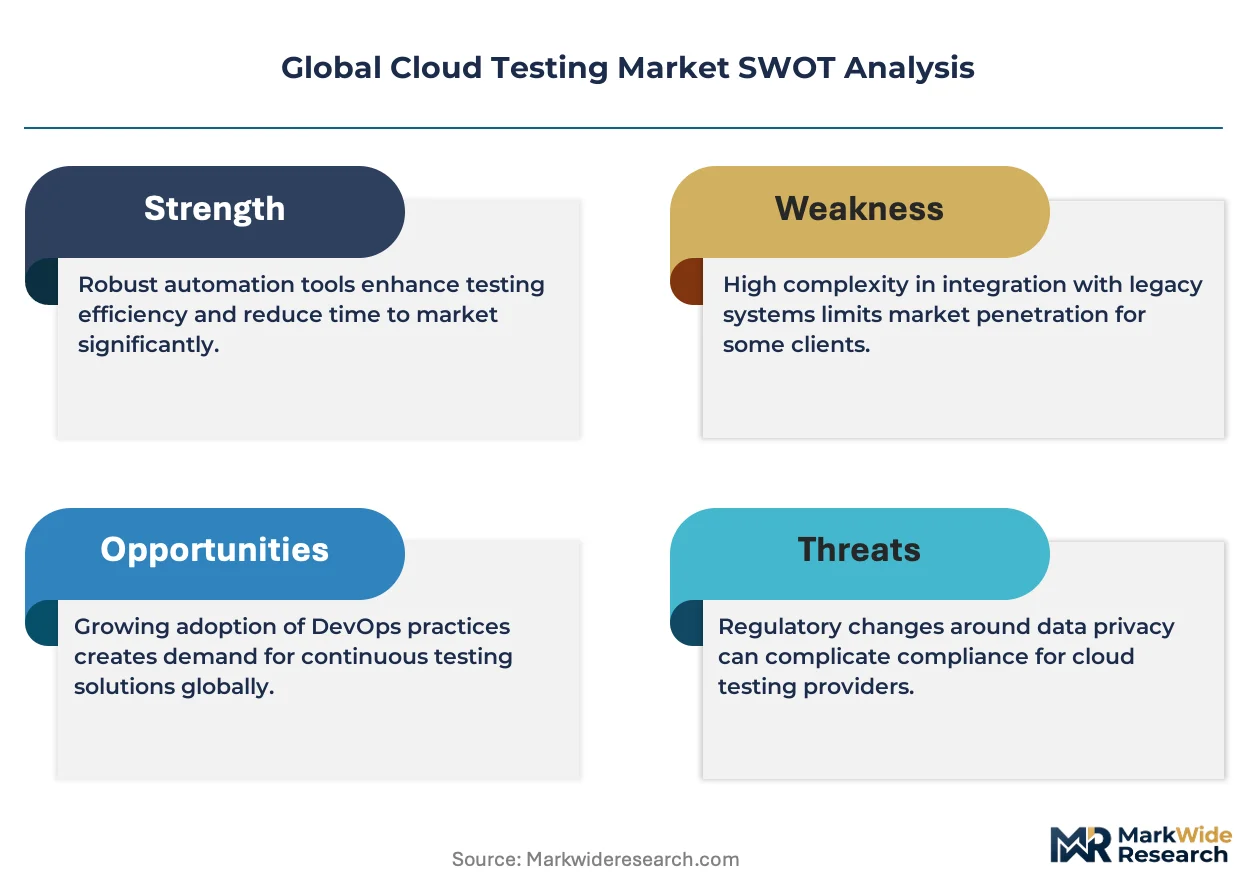
Premium-margin players sit above commodity-margin players across specialization depth, with security testing and compliance-validated pipelines commanding pricing multiples over generic browser automation. The vendor base stratifies into three tiers: hyperscale cloud providers with integrated testing modules, pure-play testing specialists with vertical expertise, and IT service providers wrapping third-party platforms into managed contracts. Consolidation pressure intensifies as enterprises prefer single-vendor relationships over fragmented toolchains. Geographic expansion and portfolio diversification represent the dominant competitive vectors.
Within the hyperscale tier, Microsoft and Amazon Web Services anchor enterprise relationships through integrated cloud infrastructure stacks. Sauce Labs occupies a specialist position with renewable-energy data center commitments that differentiate its environmental positioning for EU Green Deal procurement criteria. LambdaTest exemplifies the mid-market pure-play archetype serving DevOps teams with metered consumption models.
| Leading Market Players |
|---|
| LambdaTest |
| Microsoft |
| Amazon Web Services |
| Perfecto |
| Oracle Corporation |
| Sauce Labs |
| IBM |
| Akamai Technologies |
| BrowserStack |
| Others |
Supply & Pricing Matrix
Horizontal integration across hyperscale cloud infrastructure anchors supply positioning and pricing power for dominant platform vendors, as Microsoft and Amazon Web Services bundle testing modules within broader compute commitments to lock in enterprise spend. This integration pattern compresses margin capture for standalone testing specialists while rewarding vendors with renewable-energy data center footprints under EU Green Deal procurement criteria.
Pricing Analysis
Metered consumption models dominate mid-market segments, with DevOps teams preferring pay-per-execution access to browser automation grids over annual platform commitments. Price differentiation rests on compliance certification depth and data residency guarantees, with FDA-validated pipelines commanding substantial premiums over generic functional testing tiers. Cost compression in standard browser-automation services is intensifying as LambdaTest and BrowserStack compete for Series B software company contracts. Series B and C vendors in the United States and Germany exhibit highest price sensitivity, while regulated financial institutions in Frankfurt and Singapore prioritize compliance-validated tiers regardless of cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand, with systems integrators embedding testing platforms into managed transformation contracts. Geographic supply concentrates in the United States, Germany, and India, where hyperscaler regions and specialist data centers cluster. Compute infrastructure draws from Taiwan semiconductor foundries, renewable energy installations in Nordic markets, and submarine cable networks across the Atlantic. Single-source vulnerability in specialized browser-grid orchestration software presents structural risk. Distribution runs through IT service providers and managed testing operations centers rather than pure software marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud testing infrastructure investment functions as a geographic-arbitrage play, with vendors capturing margin spreads between India's lower operational costs and Europe's premium compliance-validated pricing tiers.
For Market Incumbents: To counter margin erosion from metered consumption models, hyperscale providers should deepen backward integration into renewable-energy data center assets and secure FedRAMP and BSI certifications for government verticals. Certification investment in FDA-validated pipelines for health technology developers defends pricing power against mid-market pure-plays. For New Entrants and Emerging Players: Capture underserved demand from Indian IT service providers seeking white-label testing infrastructure under BIS localization mandates. The most penetrable segment lies in chaos-engineering tooling for e-commerce operators preparing for seasonal traffic peaks. A channel partnership strategy with Bengaluru-based systems integrators accelerates contract velocity without direct enterprise sales investment. For Investors and Strategic Acquirers: Roll-up economics work for specialized security-testing boutiques because zero-trust mandates across financial services and government verticals create sustained demand for validated penetration-testing protocols. Long-term viability hinges on consolidation of FDA and EU AI Act compliance expertise into integrated platforms. The signal to watch is Series B software company procurement shifting from metered consumption back toward annual commitments as capital efficiency pressures ease.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft embeds testing modules within Azure commitments to anchor enterprise relationships. |
| Acquisition of Specialist Firm | Security-testing boutiques with FDA validation expertise command premium valuations from hyperscalers. |
| Geographic Expansion | Local zone deployment in Frankfurt satisfies EU AI Act data residency requirements for German banks. |
| Strategic Partnership | Sauce Labs leverages renewable-energy data center commitments to differentiate for EU Green Deal tenders. |
| Product Launch | Chaos-engineering tooling targets e-commerce operators validating resilience before Black Friday peaks. |
Research Methodology
Coverage spans the United States, Germany, India, and the United Kingdom, with primary inputs from each market cluster. The analysis combines structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, and regulatory submission databases. Bottom-up contract analysis and top-down infrastructure spend estimates were triangulated to anchor volume and value outputs.
Granularity-level modeling disaggregated the market across deployment models, solution types, vertical applications, and end-user categories, with additional dimensioning by integration complexity and regional regulatory cluster. CAGRs were derived from trend extrapolation of adoption velocity curves and infrastructure localization requirements. Forecast inputs included DevOps tooling spend patterns, zero-trust mandate implementation timelines, and renewable-energy data center buildout schedules.
Regulatory reinterpretation, hyperscaler pricing strategy shifts, and cross-border data governance fragmentation are the dominant revision risks for this analysis. Forecasts reflect documented assumptions regarding compliance obligation enforcement intensity and enterprise cloud migration pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Retail Core Banking Solution Market
Software & Services
Global Absence Management Software Market
Software & Services
Family Law Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
North America IT Services Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Global SEO Software Market
Software & Services
Global Decision Making Software Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Movie Editing Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Construction Suites Software Market
Software & Services
Remote Sensing Software Market