
 Global HMI Software Market | 2026-2036
Global HMI Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global HMI Software Market Foresight
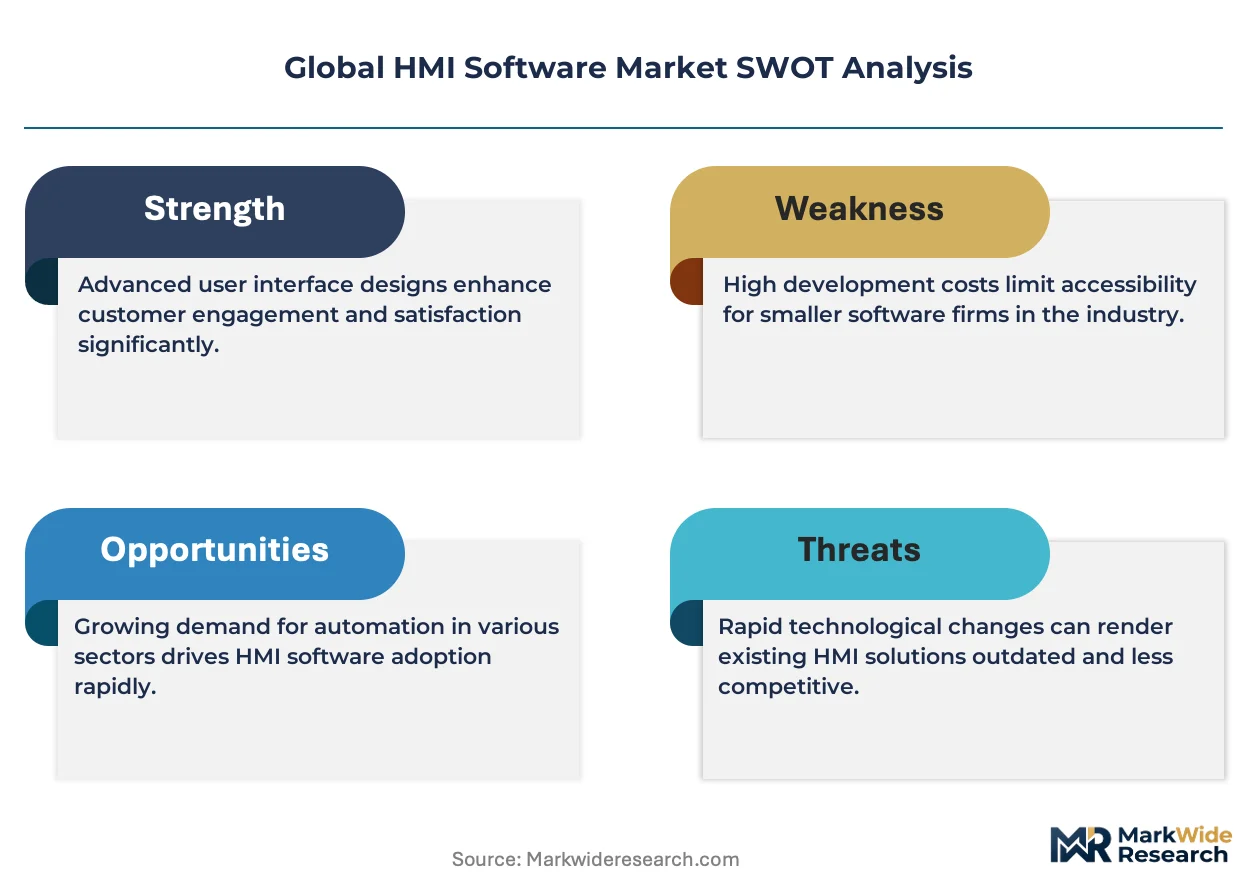
The EU Green Deal is decoupling energy-intensive manufacturing from legacy control architectures, forcing plant operators to replace static interfaces with adaptive HMI platforms. Siemens AG leverages its digital twin portfolio to anchor European utility retrofits. Rockwell Automation competes through FactoryTalk software specialization in North American automotive assembly. Schneider Electric SE extends its EcoStruxure platform to dominate building management HMI deployments across France and Germany.
Human-machine interface software encompasses visualization, control, and diagnostic applications that translate machine telemetry into operator-readable graphics through protocols like OPC UA and MQTT, enabling real-time process intervention in industrial environments. Cloud deployment solutions are capturing the fastest expansion as manufacturers shift supervisory control away from on-premise servers to reduce IT overhead. Diagnostics and analytics solution types command premium pricing due to predictive maintenance integration with SCADA layers. Process optimization use cases sustain margin pools in oilfield services and chemical processing where downtime costs exceed interface investments.
The FDA's 21 CFR Part 11 electronic records requirements shape pharmaceutical HMI validation protocols in the United States, while China's GB/T standards for industrial control system security mandate domestic software certification. Japan's METI pushes SME manufacturers toward interoperable HMI standards through subsidy programs. Stakeholders must weigh cloud migration timelines against cybersecurity compliance as regulatory fragmentation between North American, European, and Asian frameworks intensifies vendor certification burdens.
Market Dynamics
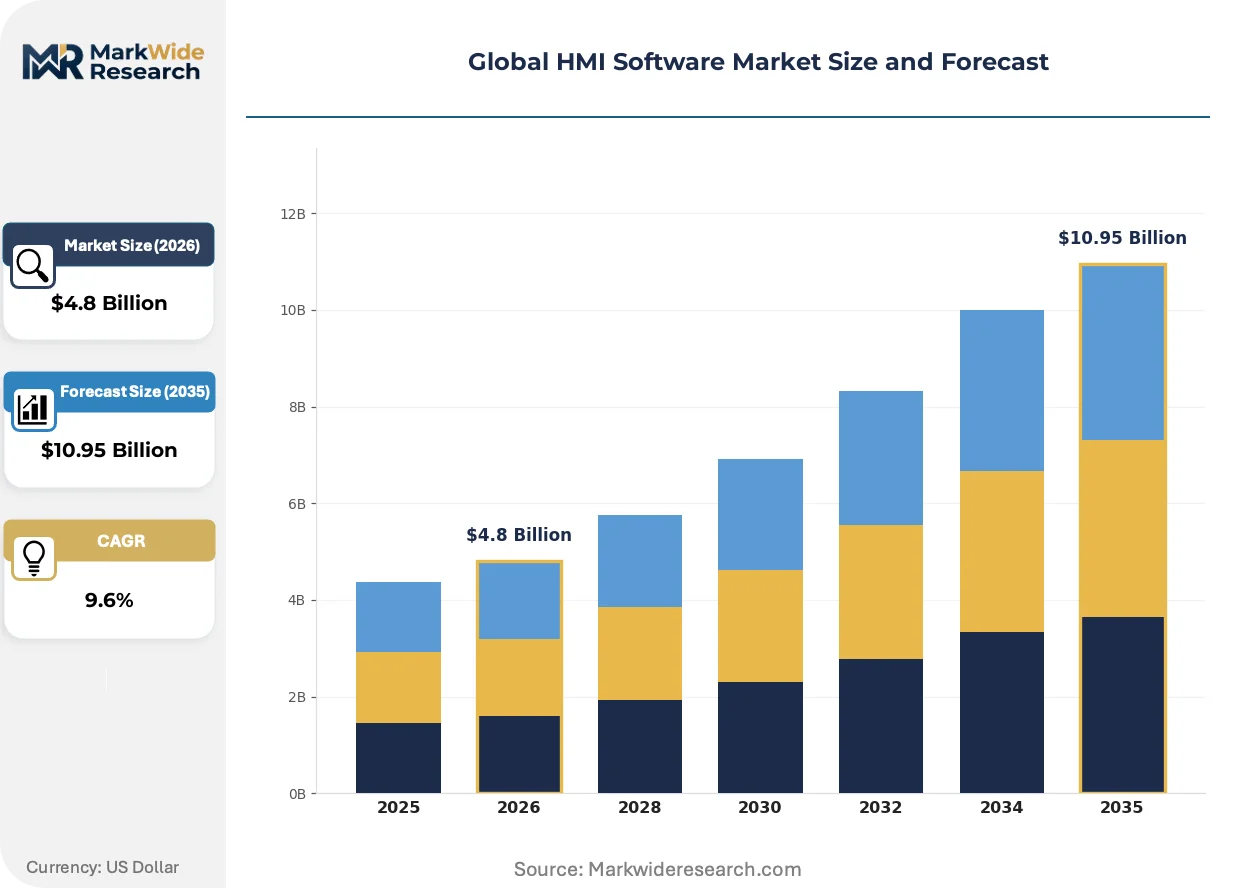
Manufacturing automation buyers are consolidating supervisory control onto cloud-native platforms, forcing incumbent vendors to rearchitect legacy client-server products for containerized deployment. This migration pressure is compressing R&D timelines while expanding addressable markets beyond traditional process industries.
Growth Catalysts
- Smart factory mandates:China's MIIT industrial internet initiative subsidizes HMI upgrades in automotive and electronics assembly. Domestic certification requirements under GB/T standards lock in sustained replacement cycles.
- EU AI Act compliance:Risk-based classification of industrial AI systems mandates auditable human oversight interfaces. Plant operators in Germany and France must retrofit existing panels with explainable control layers.
- Digital twin convergence:Oilfield services operators deploy unified visualization platforms linking reservoir simulation to surface facility control. Real-time synchronization between virtual and physical assets eliminates redundant operator stations.
Market Restraints
- Semiconductor supply concentration:Industrial panel PC processors depend on TSMC and Samsung foundry capacity. Lead times for ARM-based touch controllers extend procurement cycles by 8-14 months.
- Cybersecurity certification fragmentation:IEC 62443 compliance requirements diverge between German BSI technical guidelines and US NIST frameworks. Multi-region vendors face redundant audit costs.
- Legacy protocol entrenchment:Proprietary fieldbus networks in chemical processing plants resist OPC UA migration. Brownfield integration costs exceed greenfield deployment budgets by 3-5x.
Strategic Opportunities
- India PLI scheme manufacturing:Production-linked incentives for electronics and automotive sectors fund HMI modernization in Pune and Chennai industrial corridors. Domestic system integrators lack mature visualization portfolios.
- Edge-to-cloud orchestration:Kubernetes-based workload management converges local HMI runtime with centralized analytics. Hybrid architectures reduce bandwidth costs for remote asset monitoring.
- Japan METI SME interoperability:Subsidy programs for small manufacturers prioritize open-standard HMI adoption. JIS-compliant visualization tools gain preferential procurement status.
Industry Challenges
- OT-IT skill convergence:Control engineers lack Kubernetes and zero-trust networking expertise. Training timelines delay cloud migration projects by 6-12 months.
- FDA 21 CFR Part 11 validation:Pharmaceutical HMI deployments require documented electronic signature integrity. Validation documentation consumes 30-40% of project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HMI Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, Edge Compute Solution Type: Visualization, Control, Diagnostics, Analytics, Simulation Use Case: Manufacturing Automation, Building Management, Transportation Control, Energy Monitoring, Process Optimization End User Industry: OEMs, Smart Infrastructure, Aerospace, Utilities, Oilfield Services |
| Companies Covered | Siemens AG, Rockwell Automation, Schneider Electric SE, ABB, Honeywell International Inc., Mitsubishi Electric Corporation, General Electric Company, Emerson Electric Co., Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HMI Software Market Shifts & Advancements
Generative AI is rewriting interface design workflows, compressing the gap between operator intent and system response. Three developments are restructuring competitive positioning.
Voice-controlled HMI is electrifying hands-free interaction in hazardous environments. Chemical processing operators at BASF Ludwigshafen and Dow Texas City deploy natural language commands for valve sequencing. This modality is compressing training requirements while reducing touchpanel contamination in cleanroom pharmaceutical suites.
REACH substance restrictions on display panel chemistries are forcing industrial monitor redesigns. Cadmium and mercury limitations in backlighting components trigger supply chain requalification. Automotive assembly plants in Stuttgart and Wolfsburg accelerate LED replacement timelines to maintain CE marking continuity.
Subscription licensing is displacing perpetual software ownership in mid-market manufacturing. Packaging machinery OEMs in Italy and Spain bundle HMI runtime fees into equipment-as-a-service contracts. This shift concentrates vendor cash flow predictability while transferring upgrade risk to software providers.
Global HMI Software Market Segmentation
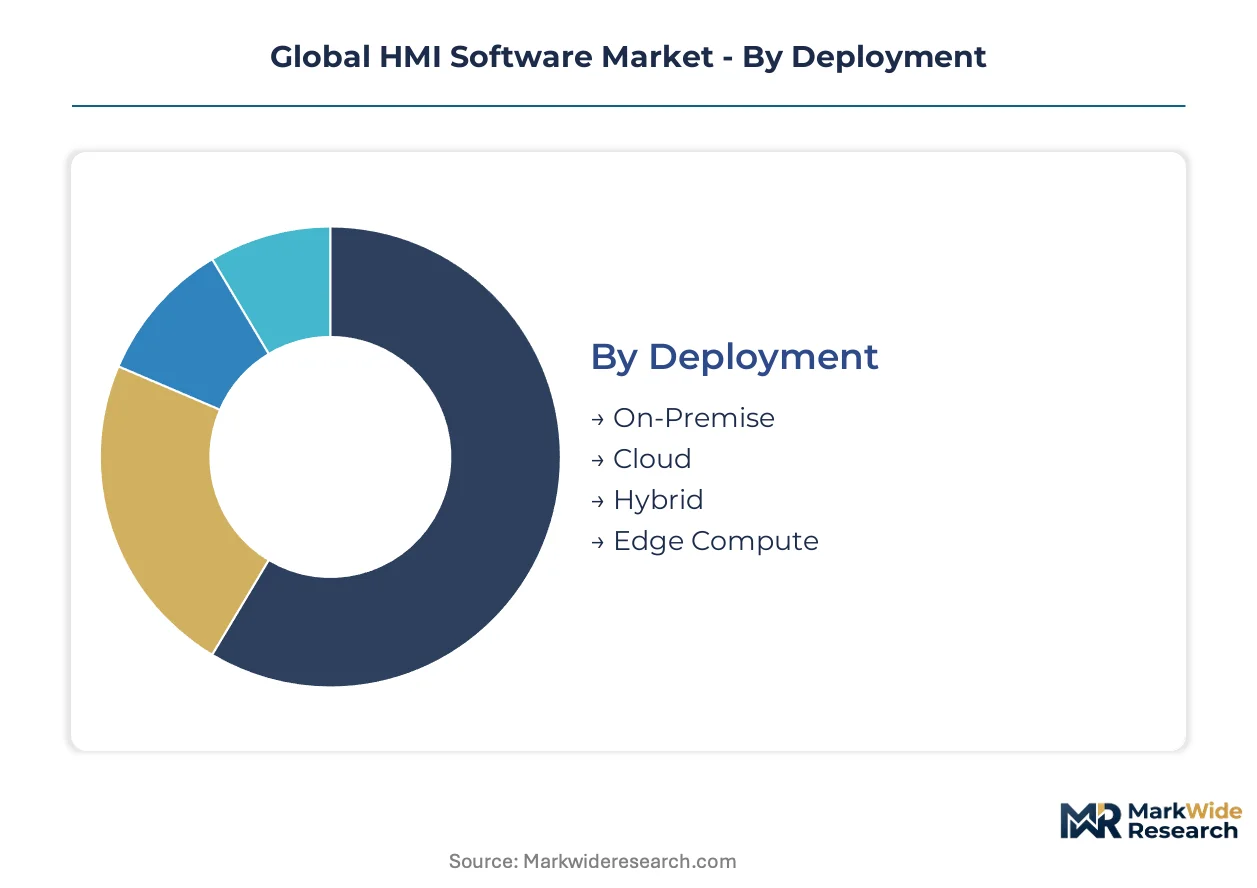
Deployment architecture determines total cost of ownership and cybersecurity exposure for plant operators. Solution type selection reflects the depth of operational intelligence required. Use case and end-user industry segmentation reveal where interface investments concentrate across industrial verticals.
Deployment:
IT infrastructure modernization budgets drive deployment decisions, with cloud migration timelines varying by data sensitivity and connectivity reliability.
- On-Premise:Legacy server installations retain dominance in pharmaceutical manufacturing and defense applications where air-gapped networks satisfy FDA 21 CFR Part 11 and ITAR requirements. German chemical processors at BASF Ludwigshafen maintain on-premise SCADA layers despite cloud pressure from corporate IT.
- Cloud:Browser-accessible platforms eliminate client software maintenance and enable centralized patch management. Packaging machinery OEMs in Italy bundle cloud HMI subscriptions into equipment-as-a-service contracts, transferring upgrade liability to vendors.
- Hybrid:Split architectures keep critical control loops local while pushing analytics to remote servers. Japanese automotive plants in Toyota City deploy hybrid models to balance METI interoperability mandates with proprietary process protection.
- Edge Compute:Containerized runtime on plant-floor gateways reduces latency for vision-guided robotics. Semiconductor fabs in Hsinchu, Taiwan deploy edge HMI nodes to minimize network dependency for wafer handling systems.
On-premise deployments lead on scale; cloud configurations lead on momentum.
Solution Type:
Functional depth correlates with pricing tier and integration complexity across SCADA and MES layers.
- Visualization:Basic graphics rendering and alarm annunciation form the entry tier. Chinese electronics assemblers under MIIT subsidies standardize on visualization-first upgrades before advancing to analytics modules.
- Control:Direct manipulation of PLC logic and motion sequences requires deterministic response times. Rockwell Automation's FactoryTalk View SE dominates North American automotive assembly for its tight integration with ControlLogix processors.
- Diagnostics:Fault tracing and event logging support root-cause analysis in continuous process industries. Oilfield services operators in Houston link diagnostics layers to predictive maintenance systems for subsea equipment.
- Analytics:Statistical process control and anomaly detection command premium licensing fees. Schneider Electric's EcoStruxure Machine Advisor bundles analytics for French and German building management deployments.
- Simulation:Virtual commissioning and operator training systems reduce physical startup risks. Siemens digital twin integration anchors European utility retrofit projects.
Visualization solutions lead on installed base; analytics modules lead on expansion trajectory.
Use Case:
Operational context dictates interface complexity, from simple status displays to multi-layered process optimization dashboards.
- Manufacturing Automation:Assembly line synchronization and quality data collection dominate volume. China's automotive and electronics sectors absorb the majority of new HMI seats under industrial internet initiatives.
- Building Management:HVAC and lighting integration prioritize energy efficiency dashboards. Schneider Electric extends EcoStruxure dominance across French commercial real estate and German industrial parks.
- Transportation Control:Railway signaling and airport baggage systems demand SIL-rated safety interfaces. Alstom and Siemens compete for European rail modernization contracts with certified visualization platforms.
- Energy Monitoring:Grid substation and renewable asset supervision require protocol flexibility for IEC 61850 and DNP3. US utilities defer cloud migration until FERC cybersecurity guidance stabilizes.
- Process Optimization:Real-time setpoint adjustment and model predictive control sustain margin pools. Dow Chemical and BASF deploy advanced HMI layers where unplanned downtime costs dwarf interface investments.
Manufacturing automation leads on unit volume; process optimization leads on value per seat.
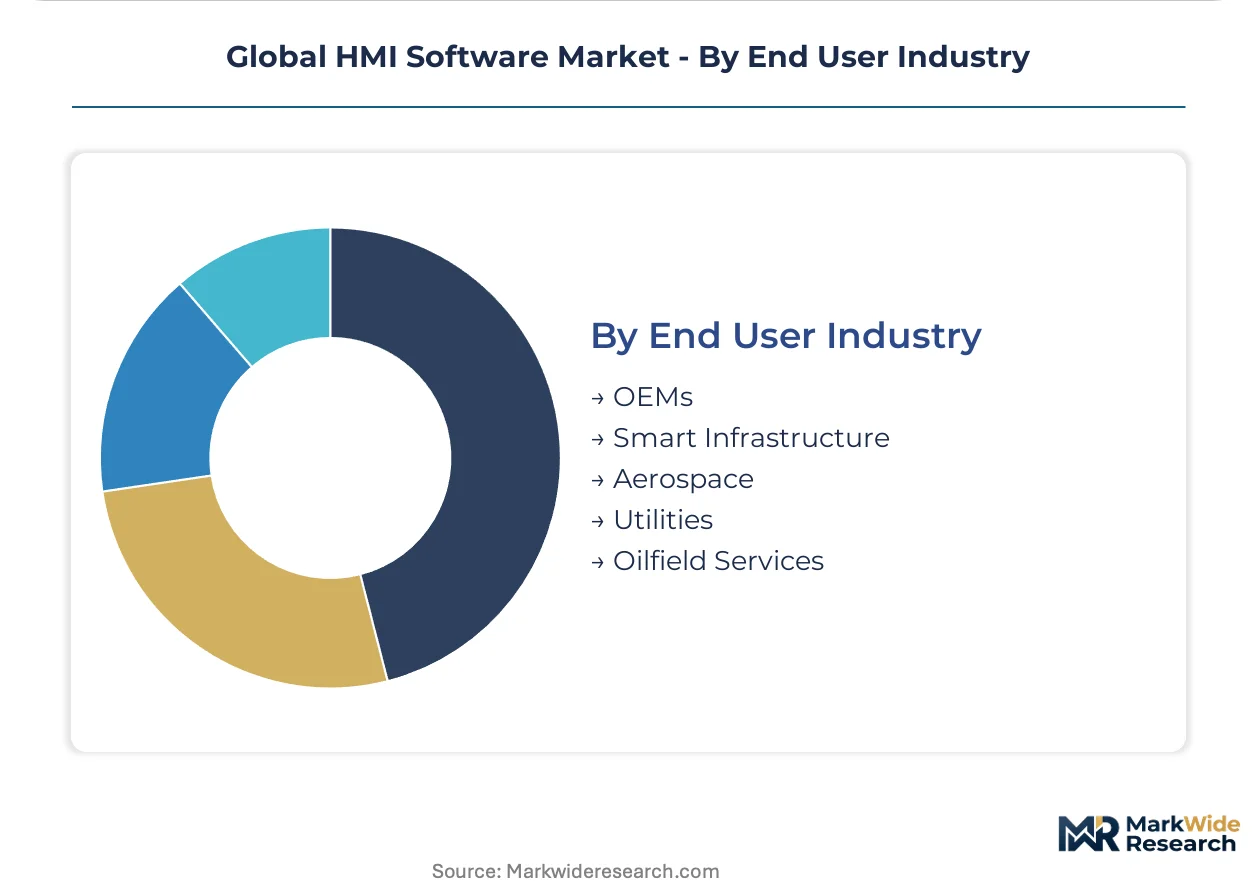
End User Industry:
Procurement authority and specification influence vary sharply between capital equipment builders and facility owner-operators.
- OEMs:Machine builders embed HMI runtime into delivered equipment, creating recurring license streams. Italian packaging machinery specialists in Bologna and Milan standardize on subscription pricing to align with equipment-as-a-service models.
- Smart Infrastructure:City-scale deployments for traffic management and water distribution demand scalable architectures. India's Pune and Chennai industrial corridors under PLI schemes lack mature domestic visualization portfolios.
- Aerospace:Flight test and ground support equipment require DO-178C software certification. Boeing and Airbus suppliers in Toulouse and Hamburg maintain specialized HMI validation protocols.
- Utilities:Generation and T&D operators balance NERC CIP compliance with modernization pressure. German grid operators retrofit existing panels to satisfy EU AI Act risk classification requirements.
- Oilfield Services:Remote drilling and production platforms prioritize satellite-bandwidth efficiency. Halliburton and Schlumberger deploy unified visualization linking reservoir simulation to surface facility control.
OEMs lead on license volume; oilfield services lead on technical sophistication requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Control systems engineers in Germany's Ruhr industrial corridor anchor European HMI software demand through automotive and chemical plant modernization. Japanese automation specialists in Nagoya and Osaka sustain Asia-Pacific technical standards. US-based SCADA integrators in Houston and Detroit drive North American deployment velocity.
United States
Pharmaceutical manufacturers in New Jersey and North Carolina expand FDA 21 CFR Part 11-validated HMI installations for electronic batch records. The FDA mandates documented electronic signature integrity for drug manufacturing interfaces. Houston's oilfield services cluster deploys unified visualization linking reservoir simulation to surface facility control.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg retrofit static panels with adaptive HMI platforms under EU Green Deal decarbonization pressure. The EU AI Act risk-based classification mandates auditable human oversight interfaces for industrial AI systems. BASF Ludwigshafen maintains on-premise SCADA layers despite corporate cloud migration pressure.
China
Electronics assemblers in Shenzhen and Dongguan standardize on visualization-first HMI upgrades before advancing to analytics modules. MIIT industrial internet initiative subsidies under GB/T standards lock in sustained replacement cycles. Shanghai automotive plants absorb the majority of new HMI seats under smart factory mandates.
Japan
SME manufacturers in Toyota City and Nagoya adopt interoperable HMI standards through METI subsidy programs. JIS-compliant visualization tools gain preferential procurement status under national industrial policy. Semiconductor fabs in Hsinchu deploy edge HMI nodes to minimize network dependency for wafer handling systems.
India
Electronics and automotive sectors in Pune and Chennai industrial corridors fund HMI modernization through PLI scheme production-linked incentives. Domestic system integrators lack mature visualization portfolios, creating vendor entry opportunities. Maharashtra and Tamil Nadu state industrial policies prioritize open-standard automation adoption.
Global HMI Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as cloud-native entrants rearchitect legacy client-server products for containerized deployment. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with digital twin portfolios, specialized automation software houses, and emerging edge-to-cloud orchestration specialists. Incumbent consolidation and strategic partnerships dominate competitive moves as R&D timelines compress.
Within the diversified industrial tier, Siemens AG and Rockwell Automation exemplify contrasting geographic anchoring strategies. Schneider Electric SE occupies a position bridging European building management dominance with process industry expansion. These three conglomerates represent the established center of gravity against which cloud-native challengers must differentiate.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation |
| Schneider Electric SE |
| ABB |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| General Electric Company |
| Emerson Electric Co. |
| Yokogawa Electric Corporation |
| Others |
Supply & Pricing Matrix
Containerized deployment architectures are compressing R&D timelines while simultaneously concentrating procurement leverage among cloud-native platform vendors. German automotive assemblers and US pharmaceutical manufacturers now face bundled subscription economics that reshape traditional perpetual licensing supply relationships.
Pricing Analysis
Three-tier pricing structure across premium analytics, standard visualization, and economy runtime levels dominates vendor portfolios. Certification grade under EU AI Act risk classification and FDA 21 CFR Part 11 validation tier create price differentiation between regulated and non-regulated deployments. Cost compression in economy runtime tiers is intensifying because mid-market manufacturers demand SaaS-convertible licensing. Small electronics assemblers in India and Mexico exhibit highest price sensitivity; oilfield services operators in Houston accept premium diagnostics pricing due to downtime cost exposure.
Supply Chain Analysis
Freight cost volatility for industrial panel PC shipments from Taiwan and South Korea is compressing margin structures for ARM-based touch controller procurement. Semiconductor fabrication draws from TSMC foundry capacity in Taiwan, Samsung facilities in South Korea, and Intel expansion in the United States. Single-source vulnerability around TSMC's advanced node concentration threatens procurement continuity for edge compute gateways. Distribution runs through authorized system integrator networks in Germany, Japan, and the United States rather than direct vendor-to-plant sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in analytics-tier software where predictive maintenance integration commands pricing premiums. Cloud-native delivery models reduce cost-to-serve while capturing recurring revenue streams from manufacturing automation buyers.
For Market Incumbents: Cement platform dominance through digital twin portfolio integration and exclusive certification partnerships with German TÜV and US FDA validation bodies. Cloud-native entrants threaten mid-market share with Kubernetes-based orchestration; backward integration into edge hardware manufacturing secures supply continuity for containerized runtime deployments.
For New Entrants and Emerging Players: Small and medium electronics manufacturers in India's Pune and Chennai industrial corridors represent the most penetrable buyer archetype. Domestic system integrators lack mature visualization portfolios, creating white-space for JIS-compliant and GB/T-certified platform offerings. Partner with Maharashtra state industrial development corporations for preferential procurement status under PLI scheme incentives.
For Investors and Strategic Acquirers: Roll-up economics work for specialized edge-to-cloud orchestration specialists because OT-IT skill convergence creates capability scarcity that incumbents cannot address through organic hiring. Target acquisition profiles include containerized HMI runtime developers with existing Kubernetes certifications and pharmaceutical validation documentation capabilities. Watch for inflection when METI interoperability subsidy programs accelerate open-standard procurement in Japan's SME manufacturing base.
| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Platform Migration | Kubernetes-based runtime reduces IT overhead for German chemical processors maintaining OPC UA fieldbus integration. |
| Regulatory Certification Investment | FDA 21 CFR Part 11 and EU AI Act compliance unlocks pharmaceutical and automotive assembly procurement channels. |
| Edge Hardware Backward Integration | Captive ARM-based controller production insulates against TSMC foundry lead time volatility for Taiwanese semiconductor fabs. |
| Subscription Pricing Transition | Equipment-as-a-service bundling aligns vendor cash flow with Italian packaging machinery OEM lifecycle revenue models. |
| Digital Twin Portfolio Integration | Unified visualization linking reservoir simulation to surface control anchors Siemens' European utility retrofit positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with control systems engineers, plant IT directors, OEM procurement managers, and SCADA integration specialists informed deployment architecture and pricing model assessments. Secondary validation drew from SEC 10-K filings of industrial automation conglomerates, MIIT industrial internet initiative documentation, EU AI Act implementation guidance, and pharmaceutical validation protocol databases. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-checked for consistency.
Segment-weighting approaches applied differential growth assumptions across deployment architectures, solution types, and end-user industries. Modeled dimensions included cloud-native versus on-premise infrastructure, visualization versus analytics functional depth, and OEM versus facility owner-operator procurement authority. CAGRs were derived from trend extrapolation of industrial software spending patterns and smart factory investment trajectories. Forecast inputs incorporated MIIT subsidy disbursement schedules and EU Green Deal decarbonization retrofit timelines.
Underlying measurement precision varies by segment; cloud deployment and analytics solution forecasts carry tighter precision than legacy on-premise visualization estimates due to disclosed vendor subscription metrics. Forecasts reflect documented assumptions about regulatory implementation pace and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Data Visualization Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Server Software Market
Software & Services
Audit Management Software Market
Software & Services
Global Big Data Software Market
Software & Services
Global Gamification Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Global Budgeting Software Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Fiber Simulation Software Market
Software & Services
Language Translation Software Market
Software & Services
Lead Management Software Market
Software & Services
PCB CAD Software Market
Software & Services
Global Guidewire Market
Software & Services
Global Proposal Management Software Market