
 Global Process Mining Software Market | 2026-2036
Global Process Mining Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Process Mining Software Market Foresight
Event-data capture from enterprise system logs is tilting toward real-time streaming architectures that embed process intelligence directly into operational workflows. Celonis leverages proprietary object-centric process mining to anchor its technology leadership in complex supply-chain environments. UiPath competes by extending robotic process automation with native discovery and mining capabilities. Software AG sustains its position through deep integration with IoT and business process management platforms.
Process mining software applies specialized algorithms to event logs extracted from ERP, CRM, and workflow systems to reconstruct, analyze, and optimize business processes through conformance checking, bottleneck detection, and variant analysis. The technology ingests timestamped activity records in XES or CSV formats, applies directed-graph models or Petri nets, and outputs operational KPIs with root-cause diagnostics for process deviation. Cloud deployment now leads adoption as enterprises prioritize elastic scalability and reduced infrastructure overhead, while on-premise installations persist in regulated sectors with strict data-residency mandates. The BFSI end-user segment generates substantial demand for compliance management solutions that automate audit trails and regulatory reporting.
The EU AI Act imposes risk-classification requirements on automated decision systems that process mining increasingly supports, while GDPR mandates granular data-lineage documentation that mining tools must embed by design. The US FDA and SEC are separately tightening expectations for algorithmic transparency in pharmaceutical supply chains and financial trading operations. Stakeholders should monitor how emerging ISO standards for process intelligence governance reshape procurement criteria and vendor qualification frameworks.
Market Dynamics
Real-time streaming architectures for event-data capture are compressing implementation timelines and embedding process intelligence directly into operational workflows, eliminating the traditional separation between analysis and execution.
Growth Catalysts
- EU AI Act risk-classification mandates:Automated decision systems in financial services and healthcare must demonstrate algorithmic transparency, creating procurement pull for conformance-checking and audit-trail capabilities.
- Industrial engineering digitization in Germany:Advanced manufacturing clusters in Bavaria and Baden-Württemberg are deploying object-centric process mining to optimize supply-chain orchestration across automotive and precision engineering ecosystems.
- Cloud-native deployment elasticity:Enterprises are prioritizing SaaS delivery models that reduce infrastructure overhead and accelerate time-to-value for process discovery initiatives.
Market Restraints
- Specialized data-science talent scarcity:Shortage of professionals trained in Petri net modeling and directed-graph analysis limits enterprise adoption velocity and implementation quality.
- Data-residency compliance costs:Strict GDPR localization requirements and sector-specific mandates in Germany, France, and Switzerland sustain on-premise infrastructure investments that cloud-native competitors bypass.
- Legacy ERP integration complexity:Proprietary data formats in older SAP and Oracle deployments require expensive custom extraction pipelines before mining algorithms can ingest event logs.
Strategic Opportunities
- Pharmaceutical supply-chain transparency in the US:FDA tightening of algorithmic documentation requirements for drug distribution creates demand for end-to-end process lineage and deviation-tracking solutions.
- Convergence of process mining with IoT telemetry:Integration of sensor-derived event streams from manufacturing equipment enables real-time bottleneck detection beyond traditional ERP log sources.
- ISO process intelligence governance standards:Emerging certification frameworks will reshape vendor qualification criteria and create first-mover advantages for compliant platform providers.
Industry Challenges
- XES standardization gaps:Inconsistent timestamp granularity and attribute definitions across vendor implementations complicate multi-source data fusion and cross-platform interoperability.
- Event-log quality degradation:Missing timestamps, duplicate records, and schema drift in operational systems require expensive data-cleansing workflows before algorithmic analysis can proceed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Process Mining Software Market |
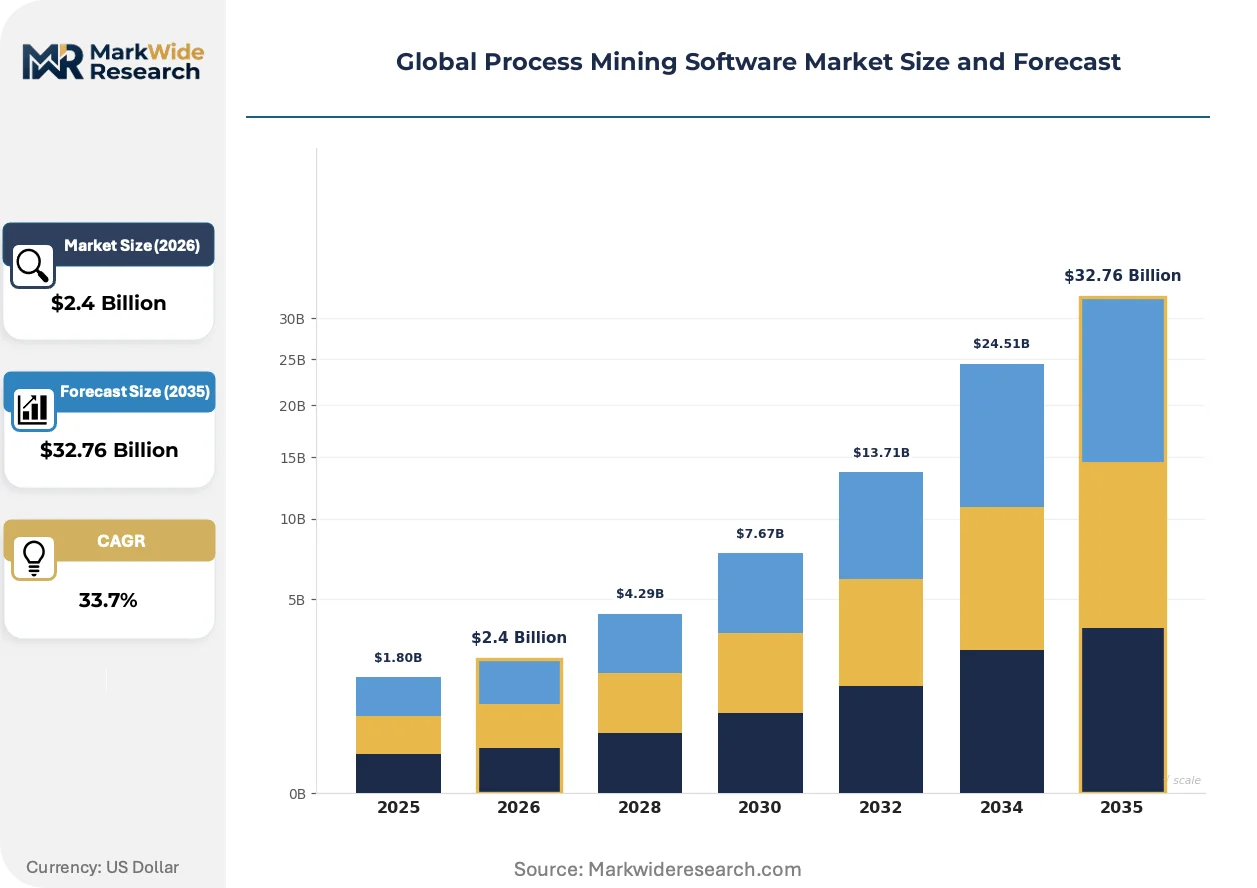
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $32.76 Billion |
| CAGR (2026 – 2036) | 33.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, SaaS End User: Manufacturing, BFSI, Retail, Healthcare Solution: Process Optimization, Compliance Management, Performance Monitoring, Root Cause Analysis Industry Vertical: Automotive, Telecommunications, Energy, Government |
| Companies Covered | SAP SE, Microsoft, Celonis, iGrafx, KYP.ai, UiPath, Software AG, Pegasystems, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Process Mining Software Market Shifts & Advancements
Process mining technology is undergoing architectural transformation as vendors compete to embed intelligence deeper into operational technology stacks and respond to tightening algorithmic accountability requirements.
Object-centric process mining is migrating from academic research into production supply-chain environments. This approach models business objects rather than activities, enabling multi-dimensional analysis of complex order-to-cash and procure-to-pay workflows. Automotive and industrial equipment manufacturers in Germany are piloting these capabilities to trace materials across fragmented supplier networks, compressing root-cause analysis from weeks to hours.
The EU AI Act's risk-based classification system for automated decision-making is forcing financial institutions to retrofit transparency mechanisms into existing algorithmic workflows. Banks and insurers must now maintain granular documentation of how process models inform credit decisions and claims processing, with national regulators in France and Germany conducting algorithmic audits. This regulatory pressure is accelerating procurement of mining tools with built-in lineage tracking and explainability features.
Enterprise buyers are consolidating vendor relationships around platforms that unify process discovery, robotic automation, and workflow orchestration. Procurement teams in BFSI and manufacturing verticals now evaluate solutions on end-to-end coverage rather than specialized mining depth alone. This preference shift is most pronounced in the US and UK, where CIOs prioritize reduction of integration overhead over best-of-breed functional superiority.
Global Process Mining Software Market Segmentation
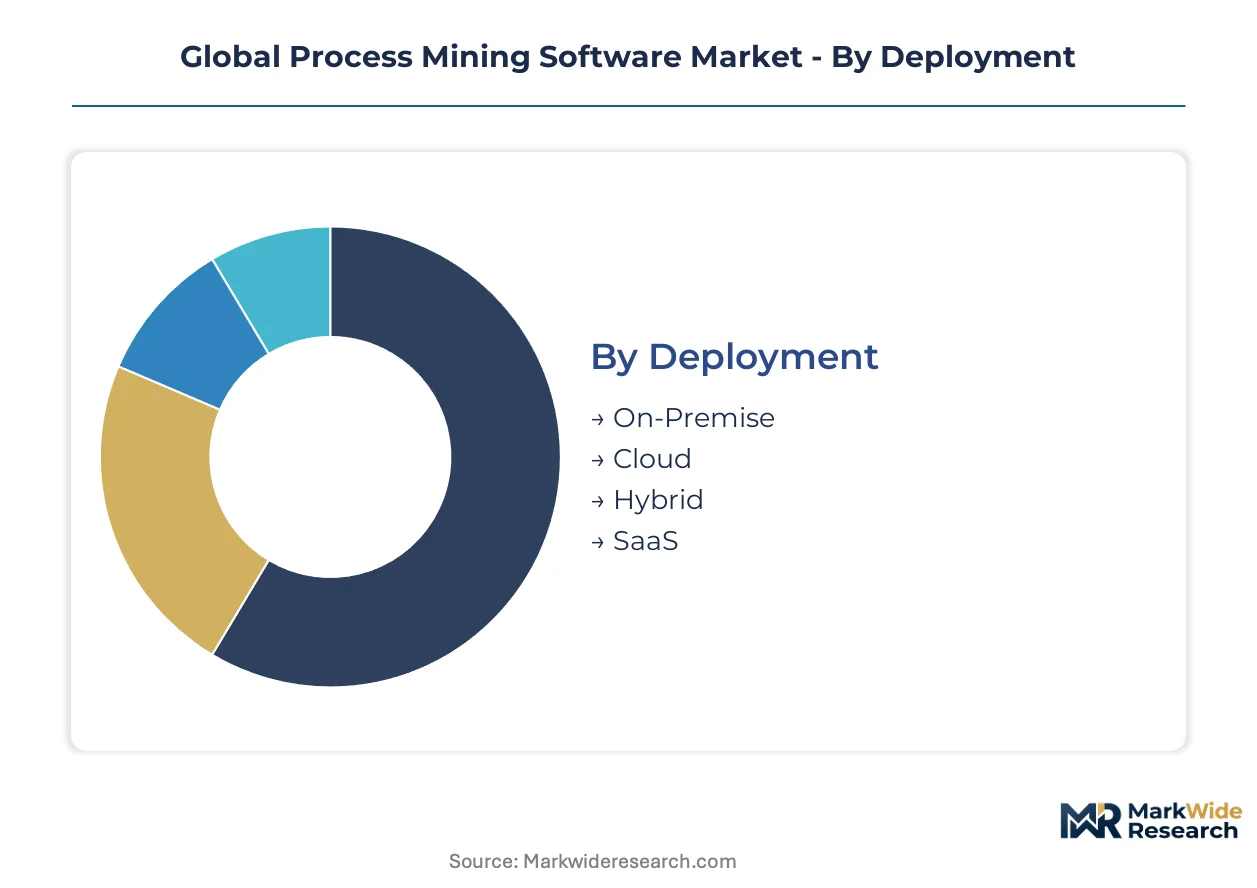
Process mining software vendors structure pricing and implementation roadmaps around deployment architecture, end-user complexity, and regulatory exposure. Segment boundaries determine integration requirements, data-residency obligations, and the depth of algorithmic transparency demanded by auditors.
Deployment:
Deployment architecture determines infrastructure ownership, data sovereignty compliance costs, and elasticity for seasonal process analysis workloads.
- On-Premise:Licensed software installed within enterprise data centers with direct control over event-log storage and processing hardware. German automotive manufacturers and Swiss pharmaceutical firms favor this model to satisfy GDPR localization mandates and sector-specific data-residency requirements from BaFin and Swissmedic.
- Cloud:Vendor-managed infrastructure with elastic compute scaling for variable-volume process discovery. US financial services firms and UK retail chains are migrating here to compress implementation timelines and eliminate capital expenditure on mining-specific hardware clusters.
- Hybrid:Split architecture retaining sensitive event logs on-premise while pushing anonymized process models to cloud analytics layers. French banking consortiums deploy this pattern to reconcile CNIL audit requirements with SaaS convenience for non-PII workflow optimization.
- SaaS:Fully managed subscription delivery with zero infrastructure footprint and automatic feature updates. Mid-market manufacturers in Italy and Spain prioritize this tier for rapid deployment without dedicated data-science teams.
On-Premise holds installed capacity. SaaS is rotating up the share rankings.
End User:
End-user segmentation reflects divergent regulatory pressure intensity and process complexity tolerance across sectoral buyers.
- Manufacturing:Heavy event-log generation from MES, SCADA, and ERP systems with multi-site supply-chain orchestration requirements. German precision engineering clusters and Japanese automotive plants drive demand for object-centric mining to trace materials across tiered supplier networks.
- BFSI:Transaction-intensive operations with strict algorithmic accountability mandates under EU AI Act and SEC trading surveillance rules. US investment banks and EU insurers require built-in lineage tracking for credit decisions and claims processing workflows.
- Retail:High-velocity order-to-cash and returns processing with seasonal demand spikes. UK e-commerce platforms and Nordic omnichannel retailers leverage cloud elasticity for Black Friday and holiday period process diagnostics.
- Healthcare:Patient-flow optimization and clinical pathway analysis with HIPAA and GDPR health-data constraints. US hospital networks and Dutch healthcare consortia pilot mining for emergency department throughput and surgical scheduling efficiency.
BFSI commands premium pricing. Manufacturing is rotating up the share rankings.
Solution:
Solution type maps to buyer maturity and the specific operational pain point triggering procurement.
- Process Optimization:Algorithmic identification of bottlenecks, rework loops, and variant paths for throughput improvement. German industrial equipment manufacturers deploy this capability to compress order-to-delivery cycles across fragmented supplier ecosystems.
- Compliance Management:Automated audit-trail generation and regulatory reporting with embedded data-lineage documentation. EU financial institutions facing BaFin and ECB algorithmic transparency audits treat this as non-negotiable procurement criteria.
- Performance Monitoring:Real-time KPI dashboards with deviation alerting for service-level agreement enforcement. US telecommunications carriers use this for customer onboarding and field service dispatch tracking.
- Root Cause Analysis:Deep diagnostic tracing from outcome anomalies back to originating process events. Pharmaceutical distributors in Switzerland and the US apply this for FDA-mandated supply-chain deviation investigations.
Process Optimization holds installed capacity. Compliance Management is rotating up the share rankings.
Industry Vertical:
Vertical specialization dictates integration depth with sector-specific operational technology and the regulatory frameworks governing algorithmic decision systems.
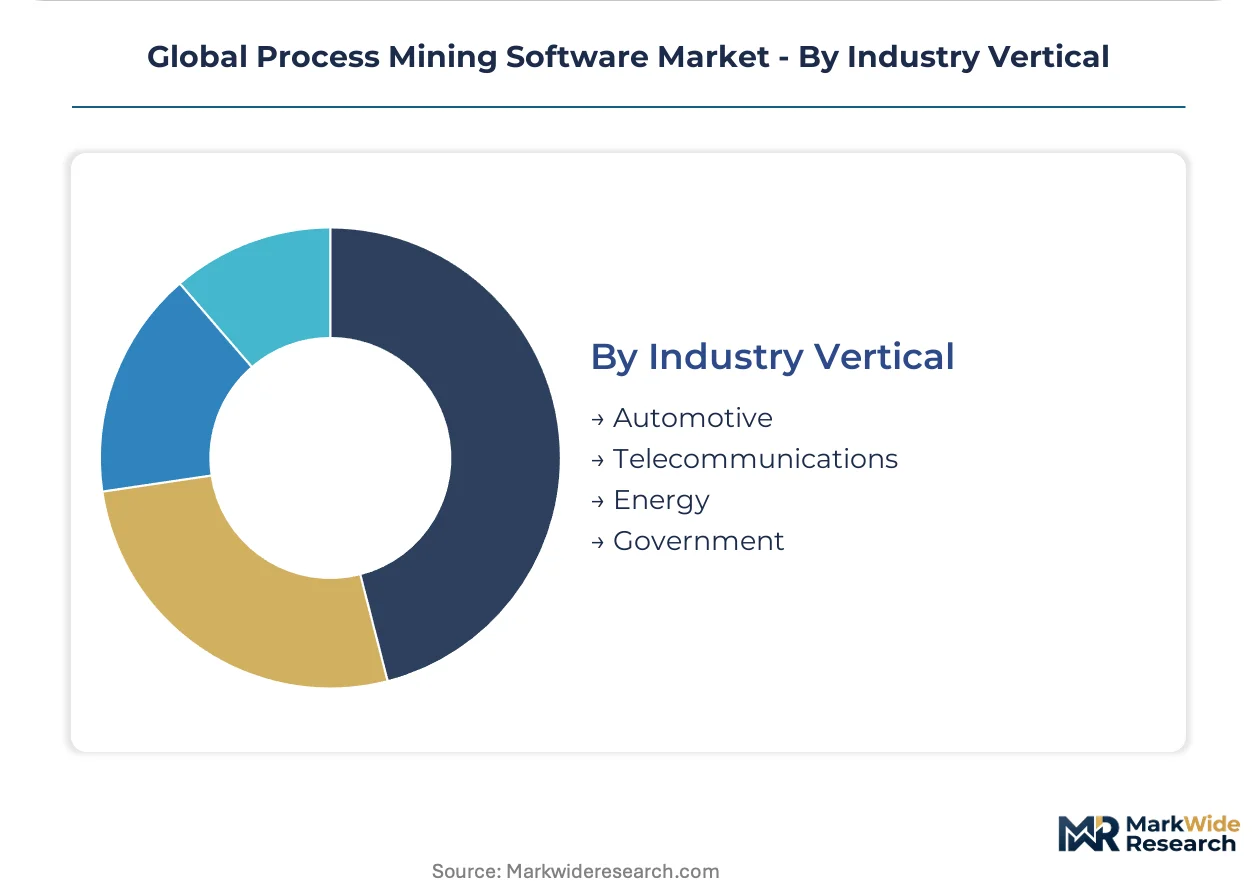
- Automotive:Complex bill-of-materials tracking and just-in-sequence supplier coordination across multi-tier networks. Bavarian and Baden-Württemberg manufacturing clusters anchor European demand for object-centric process mining.
- Telecommunications:Network provisioning, customer activation, and field service orchestration with massive event volumes. Nordic and UK operators lead adoption for churn reduction through process friction elimination.
- Energy:Grid operations, maintenance scheduling, and regulatory compliance for distributed generation assets. German utilities responding to Bundesnetzagentur transparency requirements are early adopters of real-time mining architectures.
- Government:Citizen service delivery, procurement integrity, and fraud detection in administrative workflows. Dutch and Estonian digital government initiatives pilot mining for benefit claims processing and public contract oversight.
Automotive holds installed capacity. Energy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in financial services and advanced manufacturing concentrate procurement activity across five national markets. Each geography presents distinct regulatory pressure points and industrial cluster characteristics that shape deployment preferences and vendor selection criteria.
United States
Investment banks and pharmaceutical distributors drive enterprise adoption. SEC trading surveillance rules and FDA supply-chain documentation mandates force algorithmic transparency investments. Boston and San Francisco Bay Area technology clusters anchor pilot deployments of real-time process intelligence in biotech supply chains.
Germany
Automotive OEMs and precision engineering suppliers generate the densest concentration of object-centric mining deployments. BaFin algorithmic audit requirements and GDPR localization mandates sustain hybrid cloud-on-premise architectures. Bavarian and Baden-Württemberg manufacturing clusters coordinate multi-tier supplier networks through embedded process analytics.
United Kingdom
Retail banking and e-commerce platforms prioritize cloud-native delivery models. Financial Conduct Authority expectations for model explainability intersect with ICO data lineage requirements. London fintech clusters and Manchester logistics hubs compress implementation timelines through SaaS procurement patterns.
Japan
Automotive and electronics manufacturers deploy mining for supplier quality management and production scheduling. METI digital transformation incentives accelerate IoT-integrated process discovery. Nagoya industrial corridor and Osaka manufacturing belt lead adoption of sensor-derived event stream analysis.
France
Banking consortiums and luxury goods manufacturers balance CNIL audit requirements with cloud convenience. EU AI Act risk classification drives credit decision documentation investments. Paris financial services cluster and Lyon industrial automation corridor pilot hybrid architectures for sensitive workflow optimization.
Global Process Mining Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure concentrates around enterprise software incumbents with existing ERP relationships and independent mining specialists with algorithmic depth. Strategic archetypes include platform consolidators extending automation suites, pure-play mining vendors defending technical differentiation, and industrial software houses integrating IoT telemetry. Dominant competitive moves encompass acquisition of specialized algorithm teams and geographic expansion through localized cloud infrastructure.
Within the pure-play specialist tier, Celonis and KYP.ai occupy positions defined by technical architecture choices rather than channel breadth. UiPath represents the platform consolidation archetype, embedding discovery capabilities within broader automation frameworks. SAP SE exemplifies the incumbent software house pattern, leveraging existing ERP installed bases to cross-sell mining functionality as a module extension.
| Leading Market Players |
|---|
| SAP SE |
| Microsoft |
| Celonis |
| iGrafx |
| KYP.ai |
| UiPath |
| Software AG |
| Pegasystems |
| IBM |
| Others |
Supply & Pricing Matrix
GDPR data-residency mandates constitute the dominant risk vector compressing both pricing tier spreads and supply chain configuration, forcing vendors to maintain parallel on-premise infrastructure alongside cloud-native delivery and fragmenting procurement economics across hybrid deployment patterns.
Pricing Analysis
Cost-plus contracts with named indexation to cloud-compute consumption anchor enterprise SaaS agreements, while perpetual licensing persists for German and Swiss on-premise deployments. Pricing stratifies across premium object-centric suites, standard process discovery modules, and economy-tier compliance-only packages, with differentiation driven by ISO process intelligence certification grade and embedded algorithmic explainability depth. Cost compression in the economy tier intensifies as mid-market buyers in Italy and Spain demand rapid-deployment SaaS without dedicated implementation teams. Manufacturing conglomerates exhibit lowest price sensitivity, prioritizing multi-tier supply-chain traceability over per-seat economics.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms now structure vendor relationships as cloud hyperscalers compete for process mining workload commitments. Software development concentrates in Germany, the United States, and Israel, with algorithmic R&D anchored in academic partnerships at RWTH Aachen and Technion. The technology stack draws from open-source Petri net libraries, proprietary graph databases, and API integration layers for ERP connectivity. Single-source vulnerability in specialized process intelligence talent pools threatens implementation velocity. Distribution runs through direct enterprise sales, systems integrator channels, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process mining software functions as a service-attach opportunity where recurring revenue from compliance audit automation and algorithmic lineage documentation expands faster than initial platform licensing, embedding vendors deeper into operational technology stacks.
For Market Incumbents: Insulate installed base relationships by embedding object-centric mining modules directly into existing ERP contracts, neutralizing pure-play specialists' technical differentiation. Prioritize backward integration into IoT telemetry ingestion to preempt sensor-derived event stream competition from industrial software houses. Invest in BaFin and ECB pre-certification for algorithmic audit capabilities to accelerate procurement cycles with EU financial institutions. For New Entrants and Emerging Players: Mid-market pharmaceutical distributors in the United States represent the most penetrable entry point, with FDA supply-chain documentation mandates creating urgent demand unmet by incumbent complexity. French healthcare consortia piloting patient-flow optimization offer a second white-space target with lighter competitive density than German manufacturing. Lead with SaaS-native deployment and pre-built connectors for SAP S/4HANA to compress time-to-value against legacy integration requirements. For Investors and Strategic Acquirers: The EU AI Act's risk-classification enforcement deadline reshapes the acquisition landscape, elevating targets with built-in explainability frameworks and regulatory pre-certification. Position holdings for long-term viability by favoring platforms with hybrid deployment architecture capable of serving both cloud-native and data-residency-constrained buyers. Monitor ISO process intelligence governance standard finalization as the signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Object-Centric Process Mining Launch | Automotive OEMs in Bavaria pilot multi-tier supplier traceability compressing root-cause analysis timelines. |
| Platform Integration with RPA Suites | UiPath and Automation Anywhere partnerships embed discovery directly into bot orchestration workflows. |
| Strategic Partnership with Hyperscalers | Microsoft Azure and AWS marketplace listings accelerate mid-market procurement without direct sales investment. |
| Acquisition of Specialist Algorithm Teams | RWTH Aachen and Eindhoven University spinouts deliver Petri net optimization IP for supply-chain environments. |
| Geographic Expansion via Localized Cloud | Swiss and German sovereign cloud instances satisfy BaFin and Swissmedic data-residency mandates. |
Research Methodology
The analysis maps cloud-native, on-premise, hybrid, and SaaS deployment architectures, each validated through CTO interviews, IT procurement officers at BFSI institutions, platform engineers, and systems integrator partners. Primary fieldwork combined with secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and ISO draft standard documentation. Bottom-up segment sizing triangulated against top-down market aggregation.
Assumption sets held regulatory enforcement timelines and cloud adoption curves fixed while varying enterprise digital maturity and sector-specific algorithmic accountability pressure across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, solution type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves and replacement-cycle dynamics, with inputs from MES integration complexity and data-science talent availability.
Practitioners should monitor EU AI Act implementation variance across member states and ISO process intelligence standard publication for early signals of procurement criteria shift. Forecasts reflect documented assumptions on regulatory enforcement intensity and cloud sovereignty framework evolution. Macroeconomic contraction in manufacturing investment, regulatory delay, or breakthrough in automated process modeling would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Attendance Management Software Market
Software & Services
Global Polling Software Market
Software & Services
Software Consulting Market
Software & Services
Global Managed Application Services Market
Software & Services
Interior Design Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Proxy Services and Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Global Florist Software Market
Software & Services
Newsroom Software Market
Software & Services
India Software Services Export Market