
 Glass Lens Market | 2026-2036
Glass Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Lens Market Intelligence
Medical imaging is decoupling from traditional microscopy demand as semiconductor lithography and AR waveguide applications absorb premium borosilicate capacity. Corning Incorporated leverages its fusion draw process to dominate large-format wafer-level substrates for photonics foundries. Hoya Corporation anchors Japanese ophthalmic supply chains through captive grinding and polishing networks. EssilorLuxottica competes across retail-laboratory integration, controlling prescription fulfillment density in Western Europe.
A glass lens is an optically transparent component formed from silica-based melts with controlled refractive indices, typically finished through precision grinding, polishing, or molding to achieve surface accuracies below half a wavelength. Its primary purpose is to focus, collimate, or redirect light in instruments ranging from smartphone cameras to excimer laser steppers. Progressive lenses command the highest value-per-unit in eyewear as aging demographics expand presbyopia correction needs. Camera applications now drive faster growth than microscopy as smartphone multi-array designs multiply lens counts per device. Lens coating technology concentrates margin pools through anti-reflective and hydrophobic stack patents held by equipment-laboratory hybrids.
The FDA ophthalmic device framework and EU MDR classify corrective and protective lenses under active post-market surveillance, forcing manufacturers to maintain batch-level traceability. ISO 8980 and JIS standards govern refractive power tolerances and abrasion resistance, creating compliance barriers for new molders entering ophthalmic supply chains. REACH restrictions on heavy metal oxides in high-index formulations are pushing reformulation investments across European coating lines. Stakeholders must monitor whether Chinese GB standards on blue-light filtering claims expand beyond voluntary labeling into mandatory testing protocols.
Market Dynamics
Waveguide optics in AR/VR headsets are consuming precision borosilicate capacity that previously served microscopy, forcing medical imaging suppliers to compete for constrained molding slots against photonics foundries.
Growth Catalysts
- EU MDR surface quality mandates:Tighter ophthalmic device certifications are elevating barrier-to-entry for new molders and consolidating premium supply among certified laboratories.
- Semiconductor lithography optics:Excimer laser steppers require fused silica lenses with sub-nanometer surface roughness, absorbing capacity from traditional scientific instrument channels.
- China's precision molding clusters:Concentrated capacity in Guangdong and Jiangsu provinces is shortening lead times for smartphone camera array suppliers.
Market Restraints
- Heavy metal oxide input costs:REACH restrictions on lanthanum and niobium oxides in high-index formulations are forcing European coating lines into expensive reformulation cycles.
- Japanese grinding network concentration:Captive polishing capacity in the Nagoya-Osaka corridor creates single-source vulnerability for ophthalmic finishers elsewhere.
- Plastic waveguide substitution:Polymer substrates are penetrating lower-tier AR devices, compressing addressable volume for glass waveguide suppliers.
Strategic Opportunities
- India's ophthalmic laboratory buildout:Domestic lens finishing capacity is underdeveloped relative to presbyopia demographics, creating whitespace for grinding equipment deployment.
- Blue-light filtering GB standards:Voluntary Chinese labeling protocols are likely to harden into mandatory testing, opening certification service revenue pools.
- Photonics foundry integration:Wafer-level substrate suppliers can backward integrate into lens polishing to capture margin from AR headset OEMs.
Industry Challenges
- Master optician skill scarcity:Precision grinding and interferometric testing expertise is retiring faster than vocational programs in Germany and Japan can replenish.
- Multi-standard certification timelines:Simultaneous FDA 510(k) and EU MDR submissions for progressive lenses extend time-to-revenue by 18-24 months.
- Coating stack IP fragmentation:Anti-reflective and hydrophobic layer patents are distributed across equipment OEMs, complicating royalty negotiations for independent laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Lens Market |
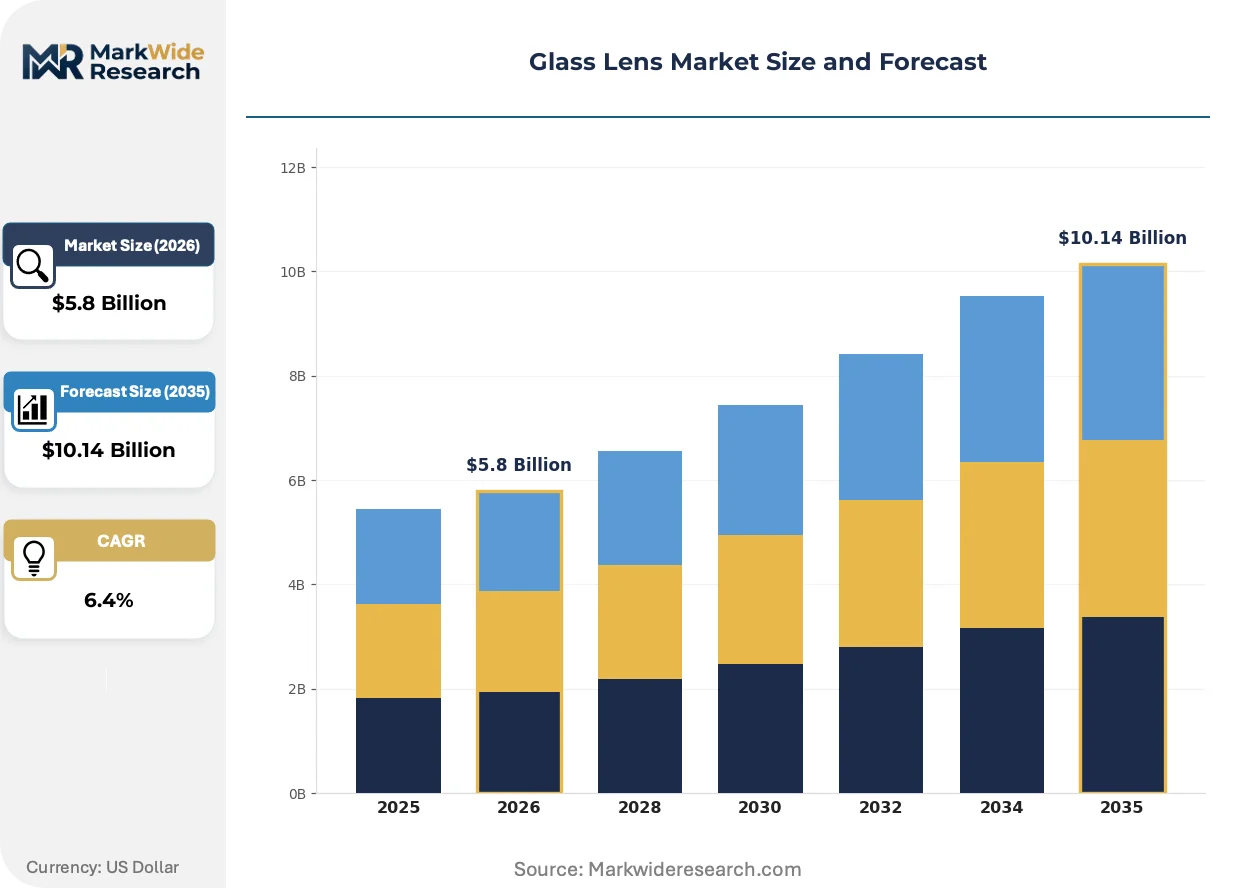
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Photochromic Application: Eyewear, Camera, Microscope, Telescope End User: Optical Retailers, Manufacturers, Laboratories, Consumers Technology: Lens Coating, Molding, Grinding, Polishing |
| Companies Covered | Schott AG, Corning Incorporated, EssilorLuxottica, Seiko Optical Products, Rodenstock, Hoya Corporation, Nikon Corporation, Canon Inc., Carl Zeiss Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Lens Market Strategic Shifts & Innovations
Precision molding is compressing the traditional grind-polish-fabricate sequence into single-step net-shape forming, redistributing value from labor-intensive finishing toward capital-intensive toolmaking and metrology.
Fused silica blanks produced through the fusion draw process are rewriting substrate economics for photonics foundries. Corning's large-format wafers enable lithography-grade flatness across 300mm diameters. AR waveguide manufacturers are adopting these substrates faster than microscope builders can secure allocation, compressing delivery schedules for scientific instrument OEMs.
EU MDR post-market surveillance requirements are forcing batch-level traceability investments across ophthalmic supply chains. Manufacturers must now maintain device history records linking each lens to raw material lots and polishing equipment calibration logs. Western European laboratories are responding by consolidating supplier panels to reduce audit complexity, favoring vertically integrated molders over fragmented grinding networks.
Smartphone camera array procurement is compressing lens qualification cycles from annual to quarterly rhythms. Multi-lens per module designs multiply qualification volumes while shortening approval windows. Chinese handset OEMs are driving this pace most aggressively, pressuring Japanese and German suppliers to accelerate metrology throughput or risk design-out from next-generation flagship specifications.
Glass Lens Market Segmentation
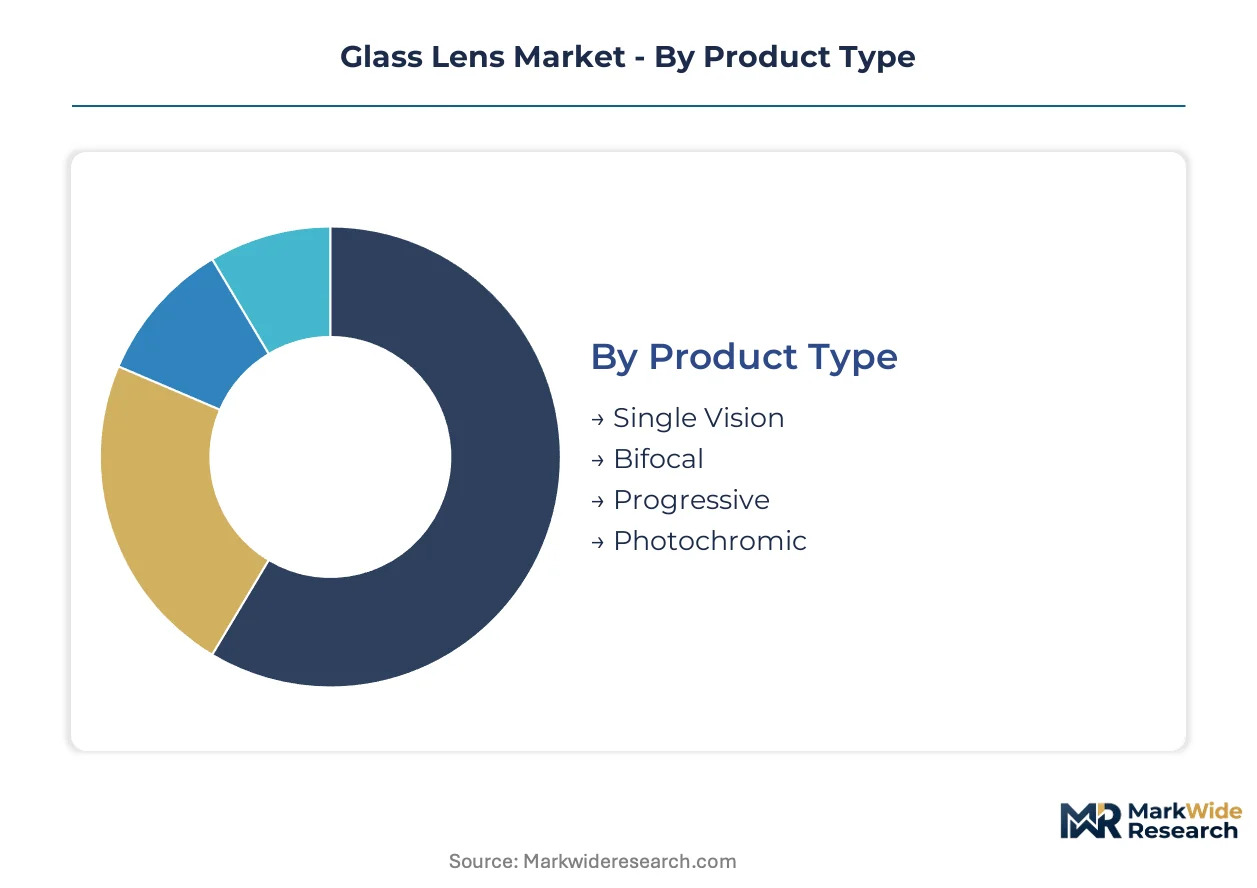
Glass lens procurement patterns diverge sharply across technical specifications and end-use requirements. Upgrade cycles in ophthalmic correction, smartphone imaging, and scientific instrumentation create distinct demand rhythms that suppliers must synchronize against.
Product Type:
Replacement frequency varies from annual coating refreshes to multi-decade progressive lens prescriptions, reshaping inventory strategies across the value chain.
- Progressive:Complex multi-zone surfaces with gradually varying refractive power correct presbyopia through a single lens. Aging demographics in Germany and Japan sustain premium pricing power despite EU MDR certification burdens.
- Single Vision:Uniform curvature throughout the lens aperture serves myopia and hyperopia correction with simpler manufacturing workflows. Mass-market eyewear chains in China drive volume procurement through standardized minus-power specifications.
- Bifocal:Discrete near-distance zones separated by visible dividing lines retain cost-sensitive segments where progressive adaptation fails.
- Photochromic:Silver halide or naphthopyran-doped substrates darken under UV exposure, commanding coating-line premiums for outdoor occupational use.
Volume placements concentrate in Single Vision; the faster expansion belongs to Progressive.
Application:
Cost tiers separate commodity ophthalmic fulfillment from capital equipment optics where surface roughness tolerances determine pricing multiples.
- Camera:Smartphone multi-array designs multiply lens counts per device while compressing qualification cycles to quarterly rhythms. Guangdong handset OEMs pressure Japanese suppliers to accelerate metrology throughput.
- Eyewear:Prescription fulfillment density controls margin capture across Western European retail-laboratory integration networks. EssilorLuxottica's captive grinding infrastructure defends against independent laboratory competition.
- Microscope:Medical imaging applications compete for constrained borosilicate molding capacity now absorbed by AR waveguide manufacturers.
- Telescope:Amateur and professional astronomical optics require large-diameter blanks with exceptional homogeneity, sourcing from specialized fusion draw producers.
Revenue pools deepen fastest in Camera; Eyewear sustains the broadest installed base.
End User:
Customer type dictates service intensity, with laboratories requiring technical support that retailers and consumers bypass entirely.
- Laboratories:Independent finishing operations grind and polish semi-finished blanks to final prescription specifications. REACH reformulation costs and coating stack IP fragmentation compress margins across European laboratory networks.
- Optical Retailers:Chain and independent dispensaries source finished lenses or rely on wholesale laboratory partnerships. India's underdeveloped domestic finishing capacity creates whitespace for grinding equipment deployment.
- Manufacturers:OEMs of smartphones, microscopes, and AR headsets procure polished blanks or molded net-shape components directly.
- Consumers:Direct-to-consumer channels bypass traditional retail through online prescription verification and home trial programs.
Procurement authority is shifting from Laboratories toward integrated Manufacturers; Retailers are gaining share fastest in emerging markets.
Technology:
Process maturity separates capital-intensive precision molding from labor-dependent finishing stages where skill scarcity concentrates supply.
- Molding:Net-shape forming compresses traditional grind-polish-fabricate sequences into single-step production. Corning's fusion draw process dominates large-format wafer-level substrates for photonics foundries.
- Polishing:Final surface accuracy below half-wavelength requirements demands interferometric testing expertise retiring faster than vocational programs replenish. Hoya Corporation's captive Nagoya-Osaka corridor creates single-source vulnerability.
- Lens Coating:Anti-reflective and hydrophobic stack patents held by equipment-laboratory hybrids concentrate margin pools through proprietary vacuum deposition sequences.
- Grinding:Initial material removal from semi-finished blanks establishes base curvature before polishing refinement.
Investment flows concentrate in Molding; Polishing faces the steepest capability constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's precision molding clusters in Guangdong and Jiangsu provinces concentrate capacity through special economic zone tax incentives. Germany's optical corridor from Jena to Munich anchors fused silica lithography optics. Japan's Nagoya-Osaka belt holds captive polishing networks. India's ophthalmic laboratory infrastructure remains underdeveloped against demographic demand. United States photonics foundries compete for borosilicate substrate allocation.
China
Smartphone camera array procurement drives demand for molded aspheric lenses at quarterly qualification rhythms. MIIT's GB standards on blue-light filtering claims are transitioning from voluntary labeling toward mandatory testing protocols. Guangdong and Jiangsu province clusters shorten lead times for handset OEMs while absorbing precision borosilicate capacity from traditional scientific channels.
Germany
Excimer laser stepper optics require fused silica substrates with sub-nanometer surface roughness specifications. EU MDR surface quality mandates elevate certification barriers for ophthalmic molders entering European supply chains. The Jena-Munich optical corridor concentrates lithography-grade polishing expertise that semiconductor equipment OEMs access through long-term supply agreements.
Japan
Aging demographics sustain premium progressive lens demand despite presbyopia correction alternatives. METI oversees JIS standards governing refractive power tolerances and abrasion resistance testing. The Nagoya-Osaka corridor's captive grinding and polishing networks create single-source vulnerability for ophthalmic finishers lacking vertical integration into these regions.
India
Underdeveloped domestic lens finishing capacity contrasts with expanding presbyopia correction needs among aging populations. BIS standards for ophthalmic devices are tightening import certification requirements for semi-finished blanks. Maharashtra and Gujarat states present whitespace for grinding equipment deployment as retail chains seek laboratory partnerships.
United States
AR waveguide manufacturers compete with microscope builders for constrained borosilicate molding slots. FDA 510(k) submissions for progressive lenses extend time-to-revenue timelines against EU MDR parallel certifications. Photonics foundries in Arizona and California integrate backward into lens polishing to capture margin from headset OEMs.
Glass Lens Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with ophthalmic correction favoring retail-laboratory integration while semiconductor optics concentrate around substrate-scale suppliers. The vendor base organizes into three archetypes: fusion-draw substrate specialists, captive grinding network operators, and precision molding equipment-laboratory hybrids. Consolidation pressure operates through M&A targeting metrology capabilities and strategic partnerships securing coating stack IP.
Among fusion-draw substrate specialists, Corning Incorporated and Schott AG exemplify scale-driven positions in large-format wafer supply. Hoya Corporation occupies a position within the captive grinding network tier, anchoring Japanese ophthalmic supply chains through Nagoya-Osaka corridor concentration. EssilorLuxottica represents retail-laboratory integration archetypes, controlling prescription fulfillment density across Western European markets.
| Leading Market Players |
|---|
| Schott AG |
| Corning Incorporated |
| EssilorLuxottica |
| Seiko Optical Products |
| Rodenstock |
| Hoya Corporation |
| Nikon Corporation |
| Canon Inc. |
| Carl Zeiss Vision |
| Others |
Cost & Logistics Intelligence
Captive polishing networks in Japan's Nagoya-Osaka corridor anchor ophthalmic supply chains while concentrating pricing power among vertically integrated molders who control both substrate production and finishing capacity. This integration pattern forces independent laboratories to accept compressed margins on semi-finished blanks or risk exclusion from premium certification tiers under EU MDR and FDA frameworks.
Pricing Analysis
Lead-time premiums dominate transactional pricing as smartphone OEMs in Guangdong province pay surcharges for quarterly-qualified molded aspherics while medical imaging buyers absorb 18-24 month certification delays. Three-tier pricing structure across premium, standard, and economy levels separates lithography-grade fused silica from ophthalmic semi-finished blanks and commodity single-vision stock. Cost compression in high-index formulations intensifies because REACH restrictions on lanthanum and niobium oxides force European coating lines into expensive reformulation cycles. Independent laboratories exhibit highest price sensitivity as coating stack IP fragmentation erodes negotiating leverage against equipment-laboratory hybrids.
Supply Chain Analysis
Dual-sourcing requirements from AR headset OEMs mandate multi-supplier qualification for borosilicate waveguide substrates, yet actual supply concentrates in Germany's Jena-Munich corridor, China's Guangdong-Jiangsu clusters, and Japan's captive polishing networks. Raw material dependencies center on high-purity silica sands, rare-earth oxides for refractive index modulation, and specialized grinding consumables. Single-source vulnerability permeates the Nagoya-Osaka belt where master optician retirements outpace vocational replenishment. Distribution runs through photonics foundries for semiconductor optics, retail-laboratory integrators for eyewear, and direct procurement channels for smartphone camera arrays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision borosilicate molding capacity operates as the binding constraint across AR waveguide and medical imaging demand, propping pricing power for substrate specialists who can secure allocation from fusion draw producers.
For Market Incumbents: Hedge against plastic waveguide substitution by accelerating metrology throughput for quarterly smartphone qualification rhythms while consolidating supplier panels under EU MDR batch-traceability mandates to reduce audit complexity. Backward integration into lens polishing captures margin from headset OEMs seeking captive supply arrangements. For New Entrants and Emerging Players: Capture whitespace in India's underdeveloped ophthalmic laboratory infrastructure where presbyopia demographics outrun domestic finishing capacity, deploying grinding equipment through partnerships with Maharashtra and Gujarat retail chains. Target certification service revenue as China's GB standards on blue-light filtering harden from voluntary labeling into mandatory testing protocols. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of metrology-capable precision molders by photonics foundries seeking upstream control over substrate finishing. Long-term viability favors suppliers with captive fusion draw access or locked semiconductor equipment OEM offtake agreements. Watch AR headset bill-of-materials shifts toward polymer substrates as the inflection signal for glass waveguide demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Molding Capacity Expansion | Corning's fusion draw process dominance enables large-format wafer supply for photonics foundries competing with microscope builders. |
| Backward Integration into Polishing | Arizona and California photonics foundries capture margin from headset OEMs by internalizing lens finishing operations. |
| EU MDR Certification Investment | Batch-level traceability systems defend laboratory access against consolidated supplier panels in Western Europe. |
| Blue-Light Filtering Certification Services | MIIT's transition toward mandatory GB standards creates revenue pools for testing laboratories serving Chinese eyewear brands. |
| Master Optician Training Programs | German and Japanese vocational investments replenish interferometric testing expertise retiring faster than replacement. |
Research Approach
Multi-period observation of molding capacity utilization, certification timeline extensions, and raw material oxide pricing anchored the trend analysis, supplemented by interviews with precision molding equipment directors, ophthalmic laboratory procurement managers, AR headset supply chain leads, photonics foundry operations heads, and EU MDR regulatory consultants. Secondary validation drew from FDA 510(k) ophthalmic device filings, ECHA REACH restriction notices, MIIT GB standard drafts, SEC 10-K disclosures from substrate specialists, and Japanese METI industrial statistics. Bottom-up lens count projections from smartphone multi-array designs triangulated against top-down ophthalmic prescription fulfillment data.
Segment-weighting across product type, application, end user, and technology dimensions structured the analytical framework across the analysis window. CAGRs derived from regression against smartphone camera array procurement rhythms, semiconductor lithography equipment shipments, and demographic presbyopia incidence curves. Modeled inputs included quarterly qualification cycle compression, REACH reformulation cost pass-through coefficients, and master optician retirement replacement ratios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polymer waveguide substitution rates in lower-tier AR devices and Chinese GB standard enforcement timing. Deviation in borosilicate substrate allocation priorities between photonics foundries and medical imaging OEMs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Laboratory Glass Container Market
Glass
GCC Flat Glass Market
Glass
Glass Prepreg Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Glass Substrate Market
Glass
Porous Glass Market
Glass
Insulating Glass Market
Glass
Laboratory Glassware Market
Glass
Glass Product Market
Glass
3D Glass Market
Glass
United States Flat Glass Market
Glass
North America Architectural Flat Glass Market
Glass
Europe Glassware Market
Glass
Mirrored Glass Market
Glass
Coated Solar Control Glass Market
Glass
Glass Polishing Powder Market