
 Liquid Ring Vacuum Pump Market | 2026-2036
Liquid Ring Vacuum Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Ring Vacuum Pump Market Analytics
ISO 5199 certification for centrifugal pump construction is bifurcating the supplier landscape into qualified OEMs and secondary fabricators. Atlas Copco leverages its global service network to anchor aftermarket revenue streams. Flowserve Corporation specializes in alloy casting capabilities for corrosive chemical environments. Busch Vacuum Solutions dominates oil-free system architectures for pharmaceutical cleanrooms.
A liquid ring vacuum pump creates suction by spinning an eccentrically mounted impeller within a cylindrical casing partially filled with service liquid, typically water or oil, achieving vacuum levels from 33 to 1013 mbar absolute pressure. The liquid ring both seals clearances and absorbs compression heat, enabling continuous duty in vapor-laden or particulate-heavy process streams. Two-stage configurations command premium positioning in chemical distillation where deeper vacuum improves separation efficiency, while oil-free architectures are gaining fastest in pharmaceutical freeze-drying applications driven by FDA validation requirements. Single-stage units retain volume leadership in pulp and paper dewatering where moderate vacuum suffices and capital constraints dominate.
EPA NESHAP standards for hazardous air pollutants and EU REACH chemical restrictions are tightening material specifications for pump construction, favoring duplex stainless steel and fluoropolymer-lined designs. FDA 21 CFR Part 11 and EU MDR traceability mandates are extending documentation burdens on pharmaceutical end users, who now demand serialized component histories from vacuum system suppliers. Buyers should monitor evolving PFAS restrictions in process liquids, as regulatory phaseouts could force rapid redesign of sealing and lubrication systems.
Market Dynamics
ISO 5199 certification requirements are splitting the supplier base into qualified OEMs and secondary fabricators, forcing procurement departments to maintain dual vendor rosters while chemical processors in Germany and India accelerate replacement cycles to meet tightening emissions standards.
Growth Catalysts
- REACH chemical restrictions:EU regulations on hazardous substances are mandating corrosion-resistant pump materials, creating replacement demand across European chemical processing facilities.
- Shanghai-Jiangsu industrial clusters:Concentrated petrochemical and pharmaceutical manufacturing in China's eastern provinces is driving bulk procurement of two-stage vacuum systems for distillation operations.
- Freeze-drying pharmaceutical applications:FDA validation requirements for sterile manufacturing are accelerating oil-free liquid ring pump deployment in biologics production facilities.
Market Restraints
- Specialized alloy input costs:Duplex stainless steel and fluoropolymer price volatility compresses margins for corrosion-resistant pump fabricators serving chemical end-users.
- Qualified supplier concentration:ISO 5199-certified OEM capacity clusters in Western Europe and select East Asian manufacturing centers, creating procurement bottlenecks during demand surges.
- Dry screw pump substitution:Oil-free rotary screw technology advances threaten liquid ring dominance in moderate vacuum pharmaceutical and food processing applications.
Strategic Opportunities
- Indian chemical processing expansion:Stricter domestic emissions enforcement and specialty chemical capacity buildouts create vacuum pump procurement windows in Gujarat and Maharashtra industrial corridors.
- PFAS regulatory phaseout preparation:Anticipated restrictions on perfluorinated sealing materials position fluoropolymer-lined pump specialists to capture redesign contracts ahead of compliance deadlines.
- Digital twin integration:Convergence of IoT condition monitoring with predictive maintenance platforms enables premium service-tier pricing for continuous-duty installations.
Industry Challenges
- Serialized component documentation:FDA 21 CFR Part 11 and EU MDR traceability mandates extend procurement cycles as pharmaceutical buyers verify supplier quality management systems.
- Retrofit integration complexity:Legacy pulp and paper dewatering installations require custom engineering to accommodate two-stage vacuum upgrades without production line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Ring Vacuum Pump Market |
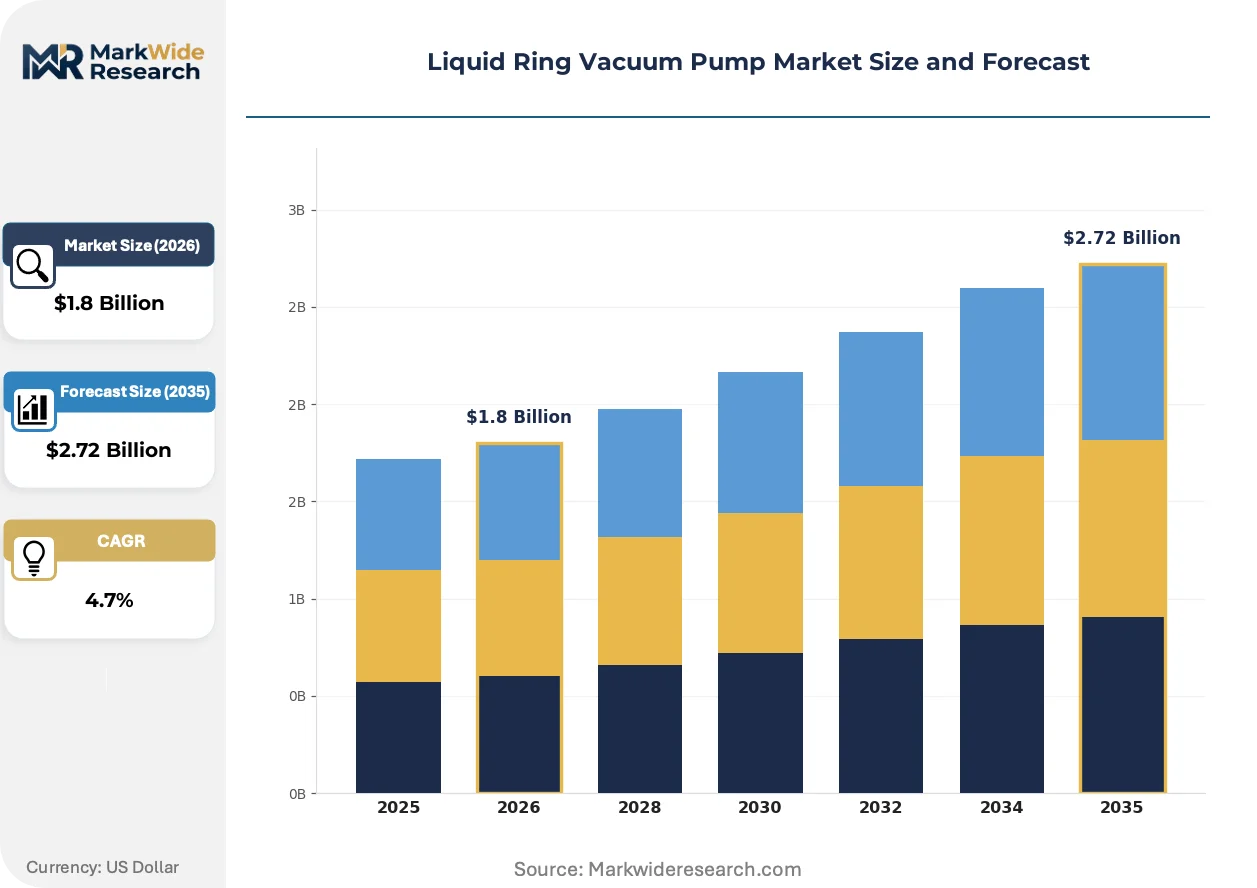
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single-Stage, Two-Stage, Oil-Free, Dry Application: Pulp & Paper, Food Processing, Chemical Industry, Pharmaceuticals End User: Manufacturing, Mining, Oil & Gas, Agriculture Drive Type: Electric, Hydraulic, Pneumatic, Steam |
| Companies Covered | Atlas Copco, Flowserve Corporation, Busch Vacuum Solutions, Graham Corporation, Ingersoll Rand, DEKKER Vacuum Technologies, Cutes Corp., Speck, OMEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Ring Vacuum Pump Market Evolving Landscape
Corrosion-resistant coating technologies and oil-free system architectures are displacing conventional sealed designs across pharmaceutical and chemical processing installations, while digital service platforms reconfigure aftermarket revenue models.
Advanced ceramic and fluoropolymer composite coatings for impeller and casing surfaces are extending service intervals in acid-laden chemical process streams. Specialty chemical producers in Germany's Ruhr industrial region are adopting these treatments to reduce unplanned maintenance during continuous distillation campaigns. The technology is miniaturizing the acceptable trade-off between capital cost and lifecycle maintenance, compressing payback calculations for premium-coated systems.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are tightening specifications for process liquid selection and containment in vacuum pump seal systems. Chemical processors must now document service liquid environmental profiles across equipment lifecycles, favoring water-based ring designs over oil-sealed alternatives in emission-sensitive applications. Pharmaceutical cleanroom installations in the Netherlands and Belgium are responding fastest, specifying oil-free architectures to preempt regulatory exposure.
Service contract unbundling is fragmenting traditional aftermarket relationships as end-users separate spare parts procurement from technical support agreements. Large chemical conglomerates in China's Jiangsu province are building in-house maintenance capabilities for standard single-stage units while outsourcing specialist repairs for two-stage chemical duty pumps. This bifurcation is most pronounced in pulp and paper verticals where capital constraints dominate and moderate vacuum requirements permit standardized component strategies.
Liquid Ring Vacuum Pump Market Segmentation
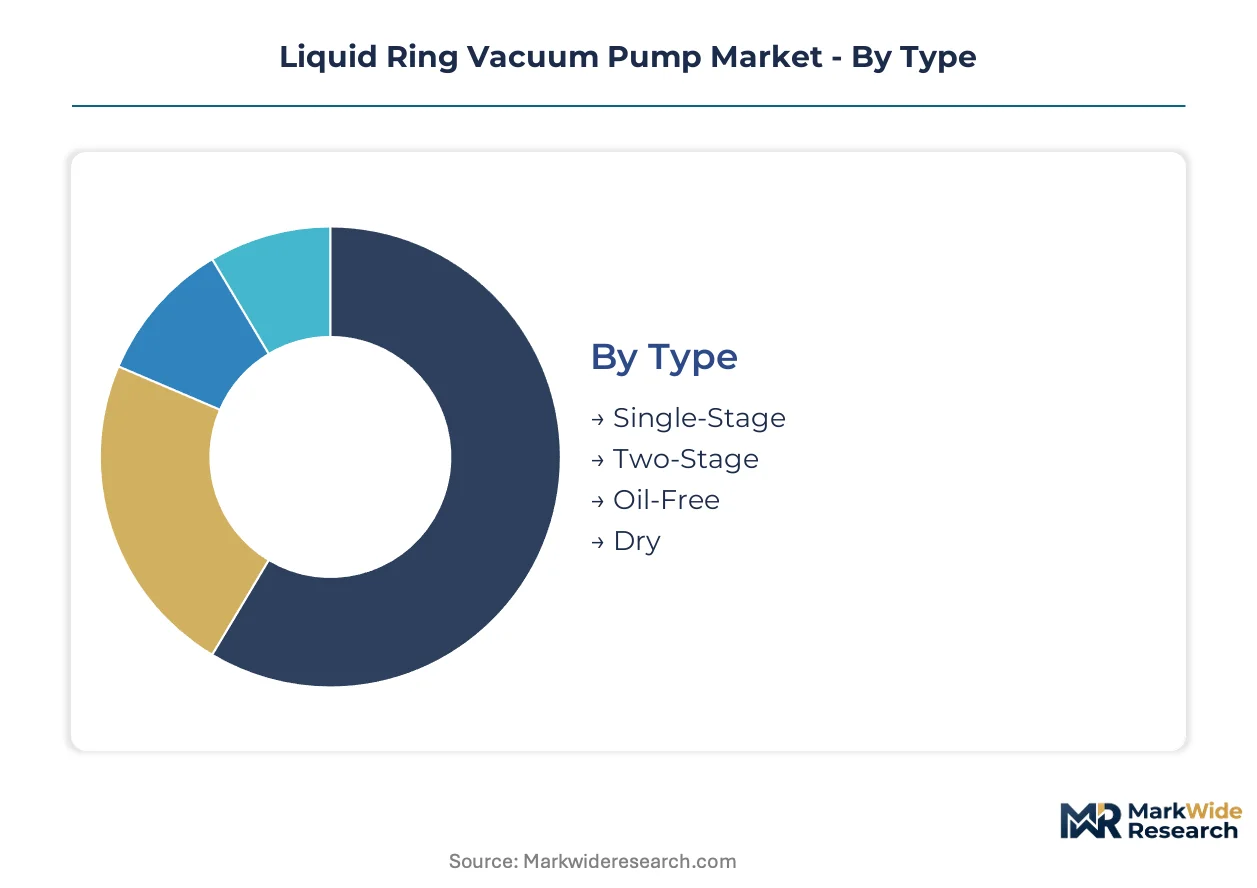
Pump type determines channel strategy fundamentally. Two-stage and oil-free units flow through certified OEM-direct relationships, while single-stage pumps distribute through regional industrial distributors serving capital-constrained buyers.
Type:
Channel structure splits sharply by performance tier. Premium two-stage and oil-free pumps move through OEM-direct channels with service bundling, while single-stage units distribute through regional industrial distributors.
- Single-Stage:Moderate vacuum capability (33-150 mbar) serves pulp and paper dewatering where capital constraints dominate procurement. Demand concentrates in China's Jiangsu province pulp mills and legacy North American paper installations where upgrade cycles lag.
- Two-Stage:Deeper vacuum (0.5-33 mbar) achieves through tandem impeller configurations in a common casing. Chemical distillation operations in Germany's Ruhr region and India's Gujarat corridor drive replacement demand as REACH compliance tightens.
- Oil-Free:Water-sealed ring designs eliminate hydrocarbon contamination risk for pharmaceutical freeze-drying. FDA validation requirements in US biologics facilities and EU MDR traceability mandates favor this architecture.
- Dry:Minimal liquid contact configurations handle solvent-laden vapor streams. Specialty chemical producers in Belgium and the Netherlands specify these for emission-sensitive batch processing.
Single-stage dominates installed base. Two-stage is where expansion concentrates.
Application:
Margin structure varies dramatically by process intensity. Pharmaceutical and chemical applications command premium pricing with service attach rates above 40%, while pulp and paper operates on thin distributor margins.
- Pulp & Paper:Dewatering applications tolerate moderate vacuum (80-150 mbar) with minimal process variation. Mills in Finland and Indonesia prioritize capital efficiency over efficiency optimization, sustaining single-stage volume leadership.
- Food Processing:Vacuum cooling and evaporation systems require oil-free certification for HACCP compliance. EU EFSA hygiene mandates and US FDA Food Safety Modernization Act enforcement drive specification upgrades in dairy and prepared food facilities.
- Chemical Industry:Distillation and solvent recovery demand corrosion-resistant materials. Duplex stainless steel and fluoropolymer-lined units serve acid-laden streams in Germany's BASF-Leverkusen complex and India's Reliance Jamnagar refinery.
- Pharmaceuticals:Sterile manufacturing mandates oil-free architectures with serialized component documentation. Freeze-drying applications in Massachusetts biotech clusters and Swiss Basel pharmaceutical hubs specify two-stage oil-free systems with predictive maintenance contracts.
Pulp and paper represents the largest installed base by unit count. Pharmaceuticals is climbing the fastest on value terms.
End User:
Procurement sophistication correlates with regulatory exposure. Oil and gas and pharmaceutical manufacturing employ dedicated reliability engineers, while agricultural buyers delegate to maintenance contractors.
- Manufacturing:Discrete and process manufacturers deploy vacuum for material handling and degassing. Automotive tier suppliers in Michigan and electronics fabricators in South Korea's Gyeonggi province standardize on electric-drive single-stage units.
- Mining:Mine dewatering and ventilation applications favor robust cast-iron construction. Australian coal operations in Queensland and Chilean copper mines in the Atacama specify hydraulic drive for explosion-risk environments.
- Oil & Gas:Vapor recovery and crude oil vacuum distillation require heavy-duty two-stage systems. US Gulf Coast refineries and Saudi Aramco facilities drive demand for API-compliant corrosion-resistant designs.
- Agriculture:Seed oil extraction and dairy vacuum systems operate intermittently with minimal technical support. Brazilian soybean processors and Dutch greenhouse operations favor pneumatic drive for remote installations without reliable electrical infrastructure.
Manufacturing holds the broadest installed base. Oil and gas generates the highest per-unit revenue.
Drive Type:
Energy cost trajectories and site infrastructure determine drive selection. Electric dominates where grid reliability permits; steam and hydraulic persist in process-integrated environments.
- Electric:Standard induction and permanent magnet motors deliver 85-95% drive efficiency with variable frequency control. German chemical processors and Japanese automotive plants specify these for precision vacuum control.
- Hydraulic:Fluid power transmission suits explosion-hazard zones and mobile installations. Underground mining operations in Poland and South Africa deploy these where electrical spark risk is prohibitive.
- Pneumatic:Compressed air drive eliminates electrical infrastructure for remote agricultural and temporary industrial applications. Australian wheat belt grain handling and Canadian oil sands camps favor this simplicity.
- Steam:Turbine drive integrates with cogeneration systems in pulp mills and refineries. Finnish paper producers and US Gulf Coast petrochemical complexes recover waste steam for vacuum generation.
Electric motors dominate new installations. Steam drive maintains share in integrated process facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical restrictions and EPA NESHAP enforcement are redirecting procurement toward certified corrosion-resistant designs across major industrial economies. Chemical processors in Germany and India are accelerating replacement cycles. China's Jiangsu and Shanghai clusters concentrate bulk demand for two-stage systems.
United States
Pharmaceutical freeze-drying facilities in Massachusetts and North Carolina are specifying oil-free architectures to satisfy FDA 21 CFR Part 11 traceability mandates. EPA NESHAP standards for hazardous air pollutants are tightening material specifications for chemical processing pumps. Gulf Coast refineries in Texas and Louisiana drive demand for API-compliant two-stage systems in vapor recovery applications.
Germany
Specialty chemical producers in the Ruhr industrial region are adopting fluoropolymer-lined pumps to meet EU REACH compliance deadlines for corrosive process streams. The country's national environmental regulator enforces strict emissions standards that mandate equipment replacement. BASF-Leverkusen complex and surrounding chemical parks anchor European demand for duplex stainless steel constructions.
China
Petrochemical capacity expansion in Shanghai and Jiangsu province is driving bulk procurement of two-stage vacuum systems for distillation operations. The Ministry of Ecology and Environment enforces dual carbon goals that favor energy-efficient pump retrofits. Yangtze River Delta industrial clusters concentrate domestic manufacturing of corrosion-resistant components.
India
Specialty chemical buildouts in Gujarat and Maharashtra industrial corridors are creating procurement windows as domestic emissions enforcement tightens. The Central Pollution Control Board implements stricter air quality standards that accelerate replacement demand. Reliance Jamnagar refinery and surrounding processing hubs specify alloy-cast pumps for acid-laden solvent recovery.
Netherlands
Pharmaceutical cleanroom installations around Rotterdam and Belgian border regions are specifying oil-free architectures to preempt EU F-Gas Regulation exposure. The national environmental agency enforces process liquid documentation requirements across equipment lifecycles. Port-adjacent chemical processors favor water-based ring designs for emission-sensitive batch operations.
Liquid Ring Vacuum Pump Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with ISO 5199 compliance splitting the supplier base into qualified OEMs and secondary fabricators. Publicly traded entities anchor aftermarket service networks while private specialists concentrate on alloy casting capabilities. Three archetypes dominate: global diversified industrials with service bundling, corrosion-resistant material specialists, and regional fabricators serving capital-constrained segments. Competitive moves center on strategic partnerships for digital twin integration and geographic expansion into Indian chemical corridors.
Within the certified OEM tier, Atlas Copco and Flowserve Corporation exemplify divergent strategic positions. Atlas Copco leverages its global service infrastructure to anchor recurring revenue streams through predictive maintenance platforms. Flowserve Corporation occupies a position as a material specialist, with its corporate structure suggesting concentrated capabilities in alloy-intensive fabrication. Busch Vacuum Solutions sits within the oil-free architecture segment, representing the pharmaceutical-facing specialization vector where FDA validation requirements concentrate procurement decisions.
| Leading Market Players |
|---|
| Atlas Copco |
| Flowserve Corporation |
| Busch Vacuum Solutions |
| Graham Corporation |
| Ingersoll Rand |
| DEKKER Vacuum Technologies |
| Cutes Corp. |
| Speck |
| OMEL |
| Others |
Value Network & Pricing Analysis
Fourteen-to-eighteen-week lead times for ISO 5199-certified alloy castings concentrate pricing power with Western European and East Asian OEMs while forcing secondary fabricators into commodity positioning. Inventory buffers at certified foundries in Germany and Japan insulate premium-tier suppliers from input volatility that compresses margins for non-certified competitors serving capital-constrained pulp and paper buyers.
Pricing Analysis
Certification level creates the primary spread between premium ISO 5199-compliant OEM-direct channels and economy-tier distributor sales. Three-tier pricing structure separates FDA-validated oil-free pharmaceutical systems from REACH-compliant chemical duty units and standard single-stage pulp mill equipment. Cost compression in economy single-stage pumps is intensifying because Chinese Jiangsu province manufacturers are expanding casting capacity. Pharmaceutical end-users exhibit lowest price sensitivity due to FDA 21 CFR Part 11 documentation burdens, while Indonesian pulp mills prioritize capital efficiency over lifecycle optimization.
Supply Chain Analysis
Strategic stockpiling of duplex stainless steel and fluoropolymer components dominates certified OEM procurement, while just-in-time sourcing exposes secondary fabricators to alloy price volatility. Manufacturing gravity centers on Germany, Japan, and China's Jiangsu province for precision casting and corrosion-resistant coating application. Supply chains draw from nickel ore processing in Indonesia, specialty steel from Finland, and fluoropolymer resin from Belgium. Single-source vulnerability concentrates in ISO 5199-certified foundry capacity clustered around Düsseldorf and Nagoya. Distribution runs through OEM-direct service bundling for premium two-stage and oil-free architectures, with regional industrial distributors handling single-stage volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phaseouts and FDA validation requirement expansions are reshaping competitive positioning by decoupling oil-free architecture premiums from commodity pump economics. This regulatory inflection creates asymmetric returns for suppliers with pre-positioned fluoropolymer lining capabilities and serialized documentation systems.
For Market Incumbents: Shield installed base relationships through predictive maintenance platform lock-in at pharmaceutical freeze-drying facilities in Massachusetts and Basel. Deepen backward integration into specialty alloy casting to secure supply of duplex stainless steel for REACH-compliant chemical duty pumps against Chinese Jiangsu province cost competition. Prioritize certification maintenance investments as ISO 5199 auditor capacity constraints lengthen recertification queues.
For New Entrants and Emerging Players: Anchor in Indian Gujarat and Maharashtra chemical corridors where domestic emissions enforcement is tightening faster than certified OEM capacity expansion. Target dry screw pump substitution vulnerabilities in moderate vacuum pharmaceutical applications where oil-free liquid ring architectures face performance pressure. Pursue joint development agreements with fluoropolymer composite coating specialists to bypass capital-intensive foundry investments.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because emissions standards and pharmaceutical traceability mandates are hardening globally. Acquisition focus should center on mid-cap specialists with captive ISO 5199 certification and existing pharmaceutical customer validation records. Monitor PFAS restriction legislative calendars as the signal to watch for forced redesign windows that favor pre-positioned fluoropolymer-lined pump portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Casting | Captive supply of duplex stainless steel insulates margin from nickel price volatility at German chemical processors. |
| Predictive Maintenance Platform Deployment | IoT condition monitoring locks in pharmaceutical customers facing FDA 21 CFR Part 11 documentation requirements. |
| Fluoropolymer Coating Capability Expansion | Advanced ceramic composite treatments extend service intervals for acid-laden streams at BASF-Leverkusen complex. |
| ISO 5199 Certification Investment | Qualified OEM status bifurcates supplier access to REACH-mandated replacement cycles in European chemical parks. |
| Geographic Expansion into Indian Chemical Corridors | Gujarat and Maharashtra specialty chemical buildouts create procurement windows ahead of domestic certified capacity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from listed pump manufacturers, trade customs data for vacuum equipment imports, and chemical industry association capacity reports. Interviews with maintenance directors at German Ruhr region chemical complexes, procurement leads at Indian Reliance Jamnagar refinery, aftermarket service heads at pulp mills in Finland, and biomedical engineers at Massachusetts freeze-drying facilities informed demand segmentation. Bottom-up unit deployment estimates triangulated against top-down industry spend analysis across pharmaceutical, chemical, and pulp and paper verticals.
Segmentation dimensions modeled include pump type architecture, application process intensity, end-user regulatory exposure tier, and drive type energy integration profile across the analysis window. CAGRs derived from installed base replacement cycle analysis, capacity expansion announcements, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporate REACH chemical restriction phaseout calendars and FDA validation requirement expansion trajectories for sterile manufacturing.
Decision-makers should treat outputs as directional under sustained alloy price volatility and stable emissions enforcement intensity assumptions; material deviation would warrant model refresh. Specific risks include accelerated PFAS regulatory phaseouts forcing rapid sealing system redesigns and dry screw pump technology advances capturing moderate vacuum pharmaceutical share. Revision becomes warranted when certified OEM capacity utilization crosses thresholds that extend lead times beyond customer tolerance bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Global Hydraulic Submersible Pump Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Global Reciprocating Pumps Market