
 Railway Telematics Market | 2026-2036
Railway Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Telematics Market Intelligence
Modular sensor-to-cloud bundles is realigning how freight operators evaluate vendor proposals. Wabtec Corporation leverages its integrated braking and telemetry portfolio to anchor long-term service contracts. Siemens AG dominates European signaling-to-telematics integration, while Railnova specializes in portable diagnostic hardware for smaller fleet operators.
Railway telematics encompasses onboard sensor networks, wayside monitoring equipment, and centralized analytics platforms that transmit locomotive health, track geometry, and traffic positioning data via cellular or satellite links. These systems process vibration signatures, thermal profiles, and GPS coordinates to predict component failures before they trigger service disruptions. Fleet Management applications currently command the largest revenue share as operators prioritize fuel optimization and crew scheduling across dispersed rolling stock. Condition Monitoring is expanding fastest where axle-bearing temperature sensors and pantograph-catenary monitoring feed machine-learning models that extend maintenance intervals. IoT connectivity layers are becoming the primary margin pool as hardware commoditization pushes value toward software subscriptions and data analytics services.
The Federal Railroad Administration mandates event recorder standards and positive train control interoperability, while the European Union Agency for Railways enforces ERTMS compatibility and cybersecurity certification under the EU Cybersecurity Act. Japan's Ministry of Land, Infrastructure, Transport and Tourism requires domestic Shinkansen operators to maintain centralized condition-monitoring databases accessible to METI auditors. Stakeholders must weigh cloud-deployment architectures against emerging edge-computing requirements as real-time safety applications demand millisecond-level latency that centralized servers cannot guarantee.
Market Dynamics
The migration from reactive maintenance to predictive failure modeling is compressing procurement cycles for freight operators while fragmenting vendor selection criteria across hardware, software, and service bundles.
Growth Catalysts
- EU Green Deal emissions mandates:The framework compels infrastructure operators to deploy real-time energy monitoring across traction power systems, accelerating telematics hardware refresh cycles.
- Freight rail predictive maintenance platforms:North American operators are mandating axle-bearing temperature telemetry and pantograph-catenary monitoring as standard fleet equipment.
- Edge computing architectures:Millisecond-latency safety applications are displacing centralized cloud processing for real-time collision avoidance and automatic train protection.
Market Restraints
- Semiconductor supply concentration:Specialized industrial-grade sensor chipsets face allocation constraints from Taiwan and South Korea foundries, extending hardware lead times.
- Legacy rolling stock integration:Pre-digital locomotive fleets require extensive retrofitting of power and data bus systems, inflating deployment costs per unit.
- Satellite connectivity pricing volatility:Geostationary and LEO bandwidth contracts for remote track monitoring expose operators to commodity-linked cost swings.
Strategic Opportunities
- India's Dedicated Freight Corridor:The 1,500-kilometer electrified network under construction creates greenfield demand for integrated signaling and telematics without legacy system burdens.
- Condition Monitoring-as-a-Service:Smaller European fleet operators are adopting portable diagnostic hardware subscriptions rather than capital-intensive permanent installations.
- 5G-Railway standard convergence:The integration of 3GPP Release 16 with ERTMS specifications enables unified communication infrastructure for both passenger and freight operations.
Industry Challenges
- Embedded systems cybersecurity certification:EU Cybersecurity Act compliance timelines for rolling stock telemetry exceed typical product development cycles, delaying market entry.
- Interoperability standard fragmentation:Divergent national implementations of ETCS baselines force vendors to maintain multiple hardware variants, complicating inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Telematics Market |
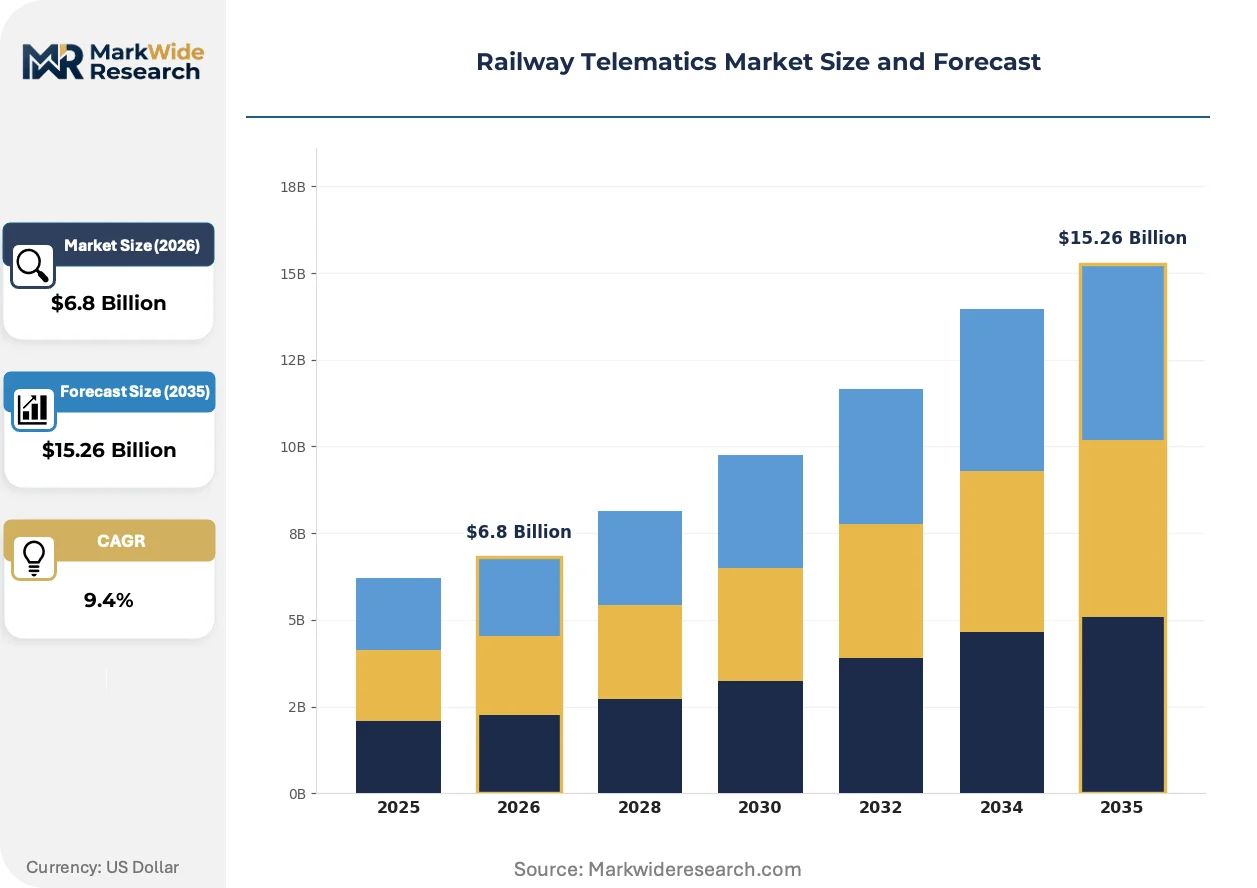
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, RFID, IoT, Cloud Computing Application: Fleet Management, Asset Tracking, Condition Monitoring, Operational Efficiency End User: Rail Operators, Freight Companies, Government Agencies, Maintenance Providers Deployment: On-premises, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Knorr-Bremse AG, Wabtec Corporation, Siemens AG, Orbcomm, Amsted Digital, Hitachi Ltd., Robert Bosch GmbH, Railnova, Alstom SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Telematics Market Strategic Shifts & Innovations
Sensor fusion architectures and machine-learning inference at the network edge are redefining how rail operators balance capital deployment against operational risk reduction.
Digital twin implementations for rolling stock and track infrastructure are electrifying how maintenance planners simulate component degradation under varying load and climate conditions. Deutsche Bahn and SNCF pilot programs demonstrate 15-20% extension of wheelset replacement intervals through vibration signature correlation with historical failure databases. The technology is electrifying competitive positioning among system integrators capable of bridging physics-based modeling with operational telemetry streams.
The European Union Agency for Railways is mandating cybersecurity certification under TS-50701 for all safety-related telematics subsystems. This creates a two-tier supplier landscape where certified vendors capture signaling-to-telematics integration contracts while uncertified hardware specialists retreat to non-safety applications. German and French infrastructure managers are prioritizing pre-certified component sourcing to compress project commissioning timelines.
Freight operators are unbundling long-term service contracts from initial hardware procurement, favoring metered analytics subscriptions tied to locomotive utilization hours. This shift disrupts traditional bundled pricing models and compresses vendor cash conversion cycles. The pattern is most visible in North American Class I railroads, where procurement teams now evaluate total cost of ownership across 10-year data service agreements rather than capital expenditure alone.
Railway Telematics Market Segmentation
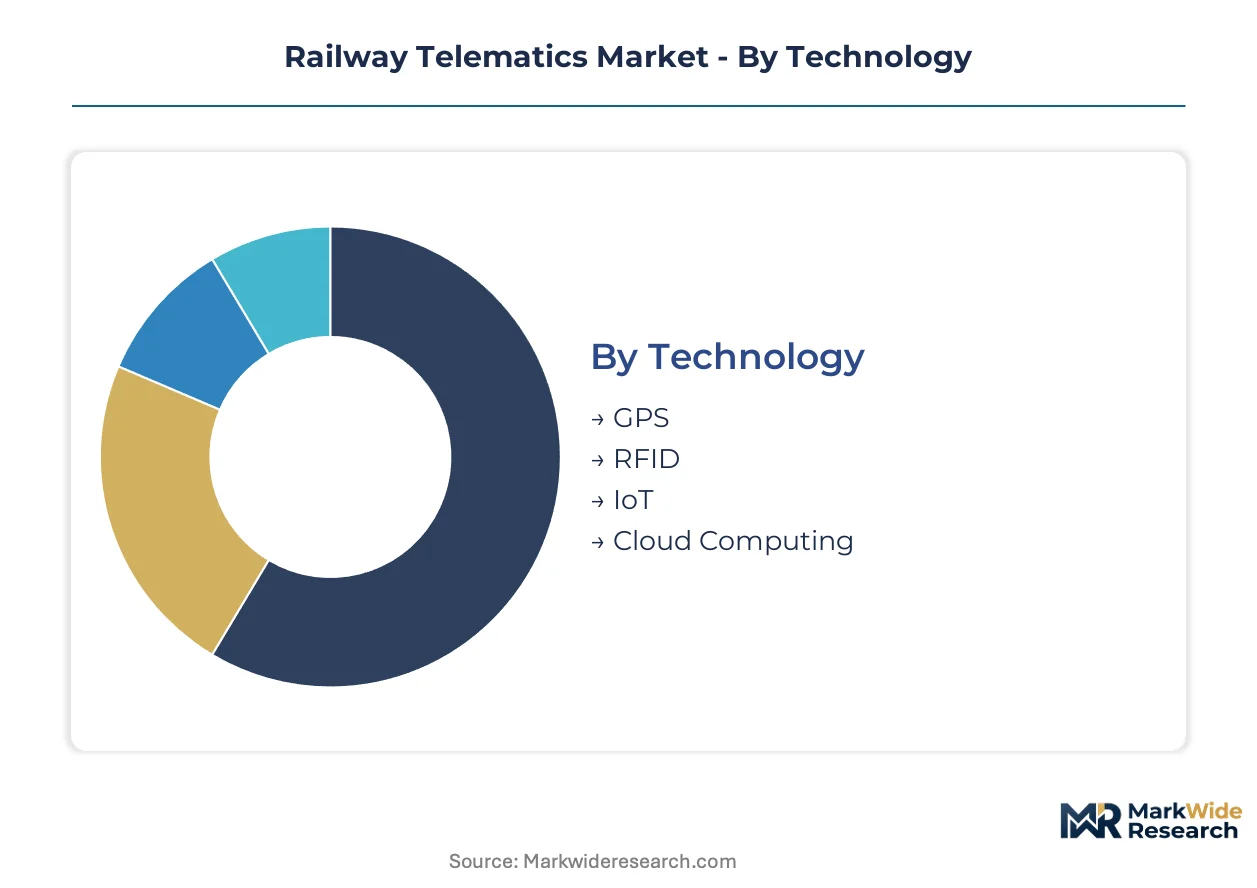
Railway telematics procurement hinges on how deeply sensor networks integrate with legacy control systems versus standalone deployments. Operators weigh capital intensity against operational risk reduction when segmenting vendor proposals across technology layers and deployment architectures.
Technology:
GPS and RFID segments function as discrete point solutions, while IoT and cloud layers embed directly into rolling stock control architectures.
- IoT:Onboard sensor networks capture vibration signatures, thermal profiles, and pantograph-catenary interaction data through industrial-grade chipsets. Deutsche Bahn's digitization programs in Germany are mandating IP-connected telemetry as baseline procurement for new rolling stock, compressing hardware refresh cycles under EU Green Deal emissions compliance timelines.
- Cloud Computing:Centralized analytics platforms process fleet-wide telemetry streams to predict component failures and optimize crew scheduling. North American Class I railroads are unbundling long-term data service agreements from initial hardware capital expenditure, shifting vendor revenue toward metered subscriptions tied to locomotive utilization hours.
- GPS:Satellite positioning modules provide traffic positioning and track geometry data via cellular or dual-mode links.
- RFID:Passive and active radio-frequency tags enable wayside asset identification and automated yard inventory management.
Volume placements concentrate in IoT sensor bundles; the faster expansion belongs to cloud computing platforms.
Application:
Cost tier stratification separates mission-critical safety systems from operational optimization tools in operator procurement evaluations.
- Fleet Management:Fuel optimization algorithms and crew scheduling platforms coordinate dispersed rolling stock across multi-thousand-mile networks. This application commands the largest revenue concentration as freight operators prioritize utilization metrics and route efficiency over predictive maintenance investments.
- Condition Monitoring:Axle-bearing temperature sensors and wheelset vibration analysis feed machine-learning models that extend maintenance intervals. Pilot programs at SNCF in France demonstrate 15-20% extension of component replacement cycles through historical failure database correlation.
- Asset Tracking:Real-time location services monitor high-value freight and maintenance equipment across yard and mainline environments.
- Operational Efficiency:Energy consumption analytics and traction power monitoring support emissions reduction mandates under regulatory compliance frameworks.
Capital deployment tilts toward fleet management platforms; condition monitoring gains share fastest where predictive maintenance contracts displace reactive service models.
End User:
Customer type determines whether procurement favors perpetual licenses, long-term service contracts, or portable diagnostic subscriptions.
- Rail Operators:Integrated passenger and freight carriers deploy end-to-end telematics stacks spanning signaling-to-telematics integration under centralized IT governance.
- Freight Companies:North American Class I railroads and European logistics specialists mandate standardized axle-bearing and pantograph monitoring as fleet-wide equipment.
- Government Agencies:Infrastructure managers under the Federal Railroad Administration and European Union Agency for Railways enforce interoperability and cybersecurity certification standards.
- Maintenance Providers:Smaller European fleet operators adopt portable diagnostic hardware subscriptions from specialists rather than capital-intensive permanent installations.
Contract value aggregates with rail operators; maintenance providers are climbing the fastest as condition-monitoring-as-a-service models proliferate.
Deployment:
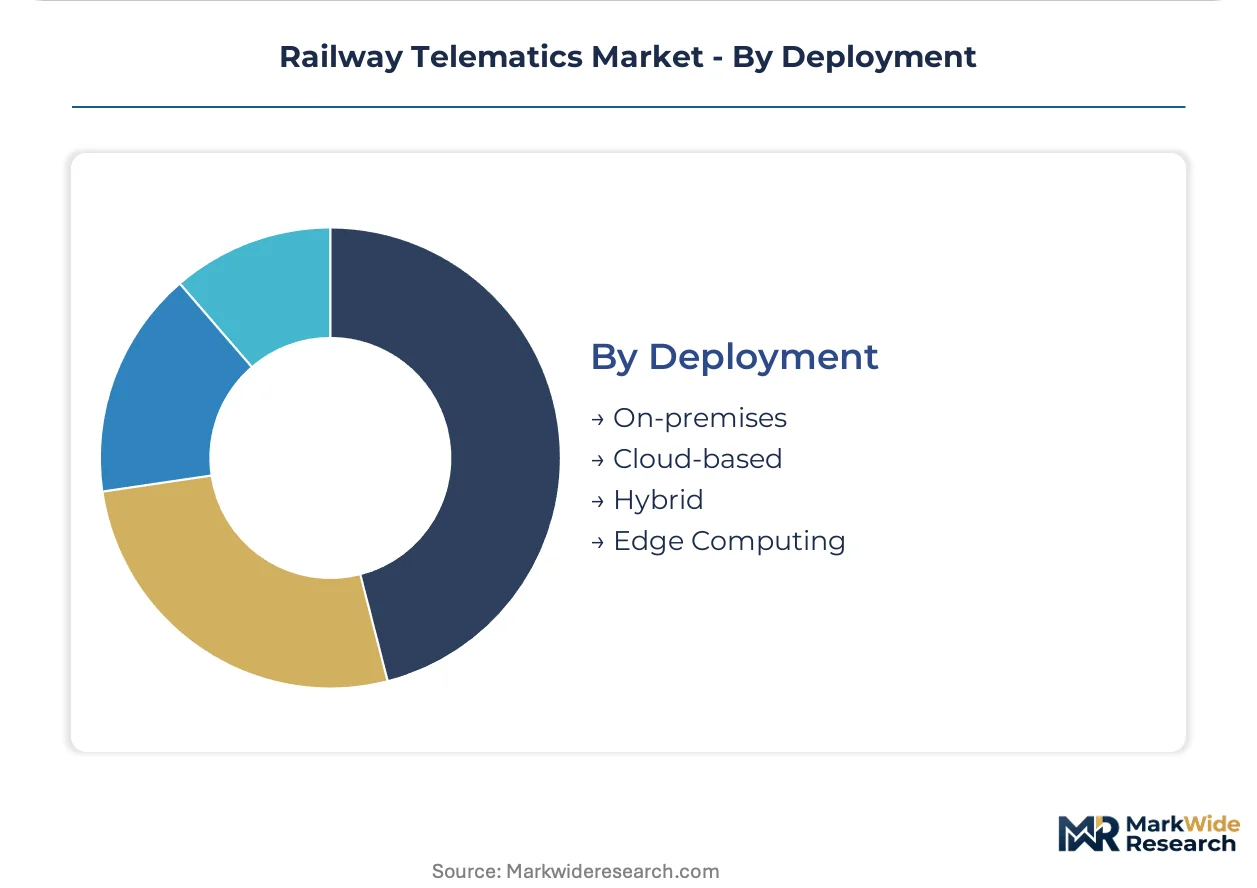
Maturity gradients separate proven centralized architectures from emerging edge-computing requirements demanded by millisecond-latency safety applications.
- Edge Computing:Real-time inference engines process collision avoidance and automatic train protection decisions locally without centralized server round-trips. The European Union Agency for Railways mandates TS-50701 cybersecurity certification for these safety-related subsystems, creating a two-tier supplier landscape where certified vendors capture integration contracts.
- Cloud-based:Scalable analytics infrastructure supports fleet-wide pattern recognition and digital twin simulations for component degradation modeling under varying load conditions.
- On-premises:Air-gapped server installations persist in jurisdictions with data sovereignty requirements or limited connectivity corridors.
- Hybrid:Architectures partition latency-sensitive safety functions to edge nodes while streaming historical telemetry to centralized warehouses.
Installed base remains concentrated in cloud-based deployments; edge computing architectures are gaining share fastest as real-time safety applications displace centralized processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes the most advanced telematics systems while the United States and China drive volume deployment across freight corridors. Manufacturing concentration clusters around industrial automation hubs in Bavaria and the Pearl River Delta.
United States
Class I railroads mandate axle-bearing temperature telemetry and pantograph-catenary monitoring as baseline fleet equipment under Federal Railroad Administration event recorder standards. The Chicago rail hub concentrates predictive maintenance platform deployment across BNSF and Union Pacific networks. Wabtec Corporation anchors long-term service contracts through integrated braking and telemetry portfolios.
Germany
Deutsche Bahn's digitization programs mandate IP-connected telemetry as procurement baseline for new rolling stock under EU Green Deal emissions compliance. The European Union Agency for Railways enforces ERTMS compatibility and TS-50701 cybersecurity certification for safety-related subsystems. Siemens AG dominates signaling-to-telematics integration from its Munich and Erlangen engineering centers.
China
The Dedicated Freight Corridor network generates greenfield demand for integrated signaling without legacy system burdens across 1,500 kilometers of electrified track. MIIT standards govern industrial IoT chipset certification for onboard sensor networks. Manufacturing clusters in the Yangtze River Delta supply vibration signature sensors and thermal profile monitoring hardware.
Japan
Shinkansen operators maintain centralized condition-monitoring databases accessible to METI auditors under Ministry of Land, Infrastructure, Transport and Tourism requirements. Hitachi Ltd. exemplifies the integrated industrial conglomerate archetype spanning signaling hardware and analytics platforms. The Kanto corridor around Tokyo anchors high-speed rail telematics R&D concentration.
India
The Dedicated Freight Corridor Corporation deploys greenfield telematics infrastructure across Western and Eastern corridor routes without legacy rolling stock retrofit costs. Indian Railways mandates GPS-based train tracking under Ministry of Railways circulars. Manufacturing activity clusters in Pune and Chennai for wayside monitoring equipment assembly.
Railway Telematics Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive rail portfolios. Consolidation pressure concentrates around signaling-to-telematics integration contracts where cybersecurity certification creates vendor lock-in. Two strategic archetypes dominate: integrated braking and control system suppliers, and portable diagnostic hardware specialists serving smaller fleet operators. M&A activity targets analytics software capabilities while geographic expansion focuses on India's freight corridor buildout.
Among European-based industrial groups, Siemens AG and Knorr-Bremse AG exemplify the diversified conglomerate archetype spanning safety-critical subsystems. Wabtec Corporation represents the North American integrated supplier model. Railnova occupies a specialist position serving maintenance providers and smaller operators through subscription-based portable diagnostics rather than capital-intensive permanent installations.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| Wabtec Corporation |
| Siemens AG |
| Orbcomm |
| Amsted Digital |
| Hitachi Ltd. |
| Robert Bosch GmbH |
| Railnova |
| Alstom SA |
| Others |
Cost & Logistics Intelligence
Industrial-grade sensor chipsets from Taiwan and South Korea foundries cascade through three pricing tiers as they reach North American freight operators, European infrastructure managers, and Indian greenfield projects. Hardware commoditization compresses margins at the component layer while software subscriptions and cybersecurity certification premiums concentrate value upstream.
Pricing Analysis
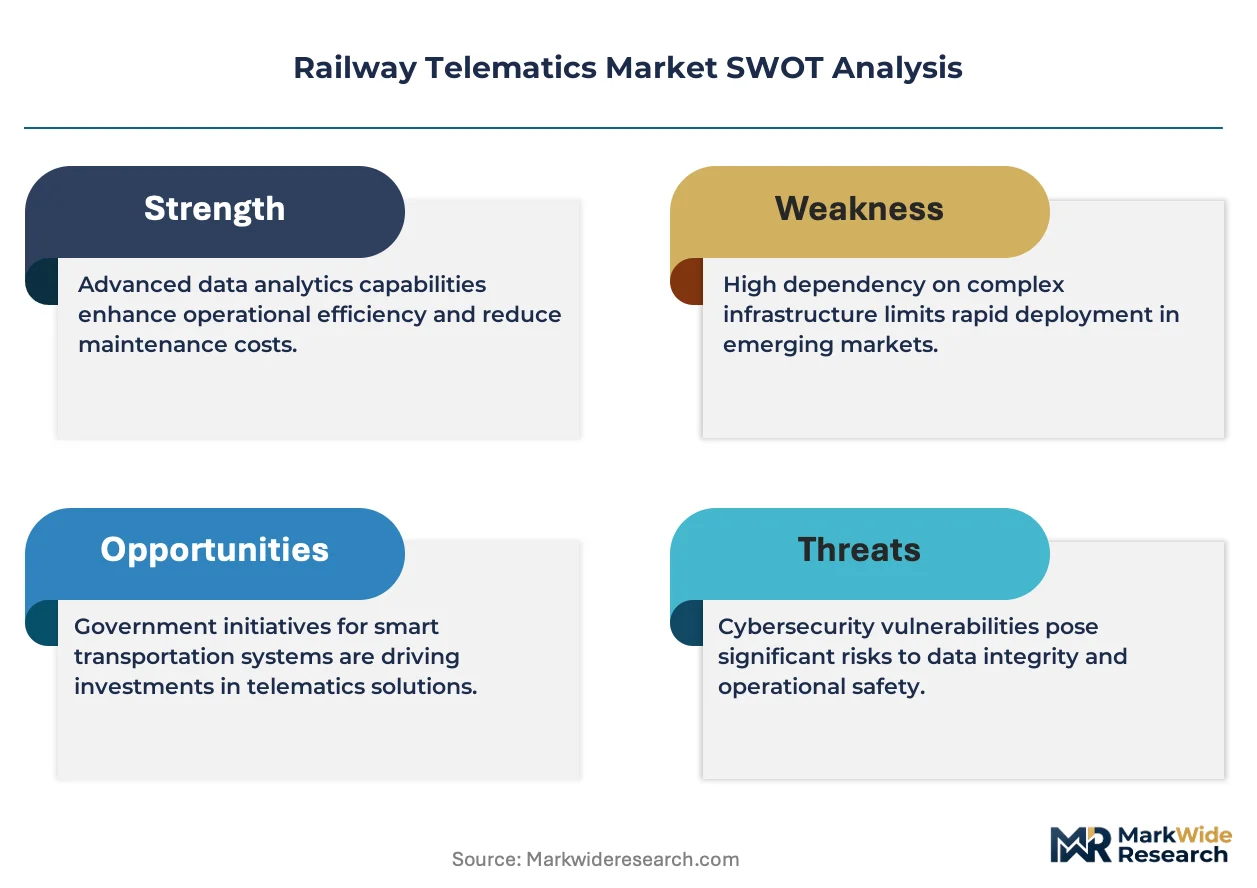
Cost-down pressure on non-certified hardware accelerates because semiconductor allocation constraints extend lead times for specialized industrial chipsets. Three-tier pricing structure across premium, standard, and economy levels separates TS-50701 cybersecurity-certified subsystems from uncertified diagnostic hardware and retrofit sensor bundles. Certification grade and volume scale drive price differentiation, with German and French infrastructure managers absorbing premiums for pre-certified components. Smaller European fleet operators exhibit highest price sensitivity, favoring portable diagnostic subscriptions from Railnova over capital-intensive permanent installations.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundries supplying vibration signature sensors and thermal profile monitoring chipsets. Manufacturing clusters in Germany, China, and the United States anchor final assembly of wayside monitoring equipment and onboard telemetry modules. The supply chain draws from rare earth elements for magnetic sensors, lithium-ion cells for edge-computing power backup, and specialized optical components for pantograph-catenary monitoring. Tariff exposure on industrial-grade semiconductors threatens margin stability for hardware vendors. Distribution runs through system integrators like Siemens and Wabtec who bundle long-term service contracts with initial equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The railway telematics sector is consolidating around cybersecurity-certified vendors as EU regulatory timelines exceed typical product development cycles, forcing uncertified hardware specialists toward non-safety applications or exit.
For Market Incumbents: Deepen backward integration into industrial-grade sensor chipset sourcing to insulate against Taiwan and South Korea foundry allocation constraints. Anchor long-term service contracts through integrated braking and telemetry portfolios to lock in fleet operator relationships across 10-year data service agreements. Defend against portable diagnostic specialists by accelerating TS-50701 certification for edge-computing subsystems before compliance deadlines compress procurement options. For New Entrants and Emerging Players: Launch via Condition Monitoring-as-a-Service subscriptions targeting smaller European fleet operators who lack capital for permanent installations. Penetrate India's Dedicated Freight Corridor greenfield deployments where absence of legacy rolling stock eliminates retrofit cost barriers. Target metered analytics tied to locomotive utilization hours, matching the unbundled procurement pattern visible across North American Class I railroads. For Investors and Strategic Acquirers: Deutsche Bahn's completion of IP-connected telemetry procurement baselines is the leading indicator that German procurement standards will propagate across EU infrastructure managers within the analysis window. Long-term viability favors diversified industrial conglomerates with captive rail portfolios and pre-certified component libraries. Watch for TS-50701 certification completion rates among mid-tier hardware vendors as the inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| TS-50701 Cybersecurity Certification | EU Agency for Railways mandates create two-tier vendor landscape separating certified integrators from retreating hardware specialists. |
| Edge Computing Architecture Deployment | Millisecond-latency safety applications displace centralized cloud processing for collision avoidance and automatic train protection. |
| Condition Monitoring-as-a-Service Launch | Portable diagnostic subscriptions from Railnova reshape competitive positioning for smaller European fleet operators. |
| India Dedicated Freight Corridor Entry | Greenfield 1,500-kilometer electrified network eliminates legacy system burdens for integrated signaling and telematics deployment. |
| Long-Term Data Service Agreement Unbundling | North American Class I railroads shift vendor revenue from capital expenditure toward metered subscriptions tied to utilization hours. |
Research Approach
Independent corroboration across primary interviews with fleet operations directors, infrastructure procurement managers, regulatory compliance officers, and maintenance service heads underwrites the qualitative findings. Secondary validation draws from Federal Railroad Administration event recorder standards filings, European Union Agency for Railways ERTMS compatibility directives, Ministry of Railways circulars from India, and customs data on industrial-grade sensor chipset trade flows. Bottom-up telematics hardware shipment analysis triangulates against top-down infrastructure investment tracking across the analysis window.
Historical reference periods anchor volume and value outputs across the projection horizon through segmented modeling of technology layers, application types, end-user categories, and deployment architectures. The analytical framework incorporates IoT sensor network penetration, cloud computing platform adoption rates, and edge-computing safety subsystem deployment. CAGRs derive from correlation with freight rail utilization trends, EU Green Deal compliance timelines, and semiconductor supply availability curves.
Semiconductor supply disruption, regulatory certification timeline compression, and satellite connectivity pricing volatility are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on infrastructure investment continuity and technology substitution patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Global Smart Locomotive Market
Railway
Locomotive Parking Brake Market
Railway
Rail Brace Market
Railway
France Connected Rail Market
Railway
South Korea Connected Rail Market
Railway
Road-Rail Vehicles Market
Railway
Global Train Control and Management Systems Market
Railway
Gearbox for Rail Vehicles Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Train Suspension System Market
Railway
Hydrogen Trains Market
Railway
Heritage Railways Trains Market
Railway
Automatic Train Supervision Market
Railway
Bullet Train Market
Railway
India Rail Freight Transport Market
Railway
Global Train Brake Market