
 Railcar Vehicle Toilet Market | 2026-2036
Railcar Vehicle Toilet Market Size, Share, and Industry Trends Forecast 2026-2036
Railcar Vehicle Toilet Market Insights
EN 15085 welding certification for rail vehicle bodies is redrawing supplier eligibility across the railcar toilet value chain. WABTEC leverages its integrated braking and sanitation platform to anchor North American retrofit demand. EVAC sustains Nordic market presence through vacuum system specialization for Arctic climate resilience. Zhuzhou CRRC Times Electric dominates domestic Chinese procurement through captive manufacturing scale and state rail project alignment.
A railcar vehicle toilet is a self-contained waste management fixture engineered for rolling stock, typically operating with vacuum assist between 3.5–5 bar differential pressure to evacuate waste into retention tanks at speeds exceeding 300 km/h. Its primary purpose is to maintain hygienic conditions for crew and passengers while eliminating discharge to trackbed under dynamic operating loads. Vacuum toilets command the largest installed base among product types due to water efficiency and compatibility with high-frequency service cycles, while composting variants represent the fastest-growing niche for heritage and scenic rail operators seeking zero-discharge compliance. Retrofit solutions outpace new installations in mature networks where rolling stock life extension programs defer capital replacement.
The EPA administers Clean Water Act provisions affecting rail yard effluent discharge limits, while the EU F-Gas Regulation constrains refrigerant choices in climate-controlled toilet modules for European rolling stock. China's MEE enforces municipal wastewater interface standards that vacuum system suppliers must certify for domestic rail corridors. Stakeholders should monitor divergence between regional flush-water specifications and emerging bio-technology validation protocols as fleet decarbonization targets reshape procurement criteria.
Market Dynamics
Vacuum waste systems are compressing the technology stack across railcar sanitation, forcing chemical toilet suppliers to recertify under tightened effluent protocols or exit fleet procurement cycles entirely.
Growth Catalysts
- High-speed rail fleet expansion:China's CRRC supply chain corridor is absorbing vacuum system capacity through state-aligned rolling stock programs, pulling component orders from adjacent Southeast Asian modernization initiatives.
- F-Gas Regulation compliance:European rolling stock operators are retrofitting climate-controlled toilet modules to meet refrigerant phase-down mandates, generating replacement demand for compliant vacuum-assisted fixtures.
- Water scarcity protocols:Arid-climate rail corridors in Australia and the Middle East are specifying zero-flush vacuum designs to reduce onboard water weight and extend range.
Market Restraints
- Stainless steel input volatility:Retention tank fabrication depends on austenitic grades subject to nickel price swings, compressing margins for mid-tier fabricators without long-term supply agreements.
- Single-source vacuum pump concentration:German and Japanese suppliers control high-reliability compressor architectures, exposing buyers to 16-24 week lead times during capacity constraints.
- Chemical toilet residual demand:Heritage and narrow-gauge operators in Eastern Europe and Latin America continue specifying chemical recirculating systems due to lower upfront capital requirements and minimal infrastructure retrofit.
Strategic Opportunities
- Indian Railways electrification corridors:The Dedicated Freight Corridor and Mumbai-Ahmedabad high-speed line are specifying EN 15085-certified sanitation modules, creating first-mover positioning for vacuum system integrators.
- Composting technology convergence:Heritage rail operators in the Alps and Rocky Mountains are piloting bio-digester toilets that eliminate retention tank weight, opening zero-discharge compliance paths for scenic routes.
- Digital fleet monitoring integration:IoT-enabled fill-level sensors and predictive maintenance platforms are unbundling from OEM supply, allowing aftermarket service providers to capture recurring revenue from operator IT budgets.
Industry Challenges
- EN 15085 welding certification scarcity:Rail-specific orbital welding qualifications limit supplier pool expansion, extending qualification timelines for new entrants by 12-18 months.
- Legacy rolling stock interface fragmentation:Retrofit installations must reconcile vacuum system pressure specifications with 40-year-old waste tank geometries, requiring custom adapter fabrication on 60% of refurbishment programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railcar Vehicle Toilet Market |
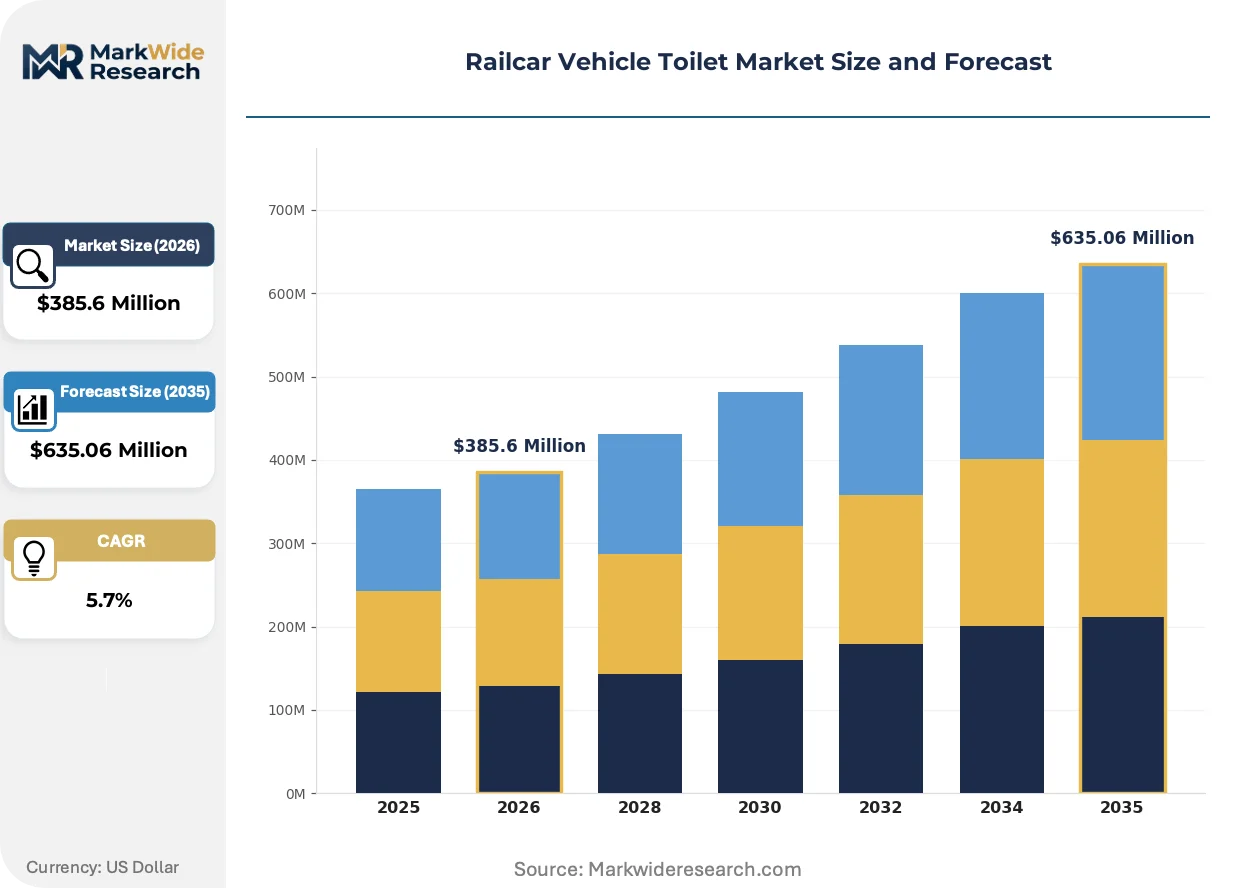
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $635.06 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Toilets, Chemical Toilets, Composting Toilets, Incinerating Toilets End User: Passenger Trains, Freight Trains, Maintenance Services, Rail Operators Technology: Waterless Solutions, Regenerative Systems, Pneumatic Systems, Bio-Technology Installation Type: New Installations, Retrofit Solutions, Modular Installations, Custom Builds |
| Companies Covered | WABTEC, EVAC, Huatie Tongda, Rolen Technologies & Products, Dowaldwerke, Glova Rails, Goko Seisakusho, Qingdao Victall Railway, Zhuzhou CRRC Times Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railcar Vehicle Toilet Market Trends and Innovations
Component-level innovation is compressing system footprints while regulatory harmonization efforts and operator procurement model evolution are restructuring how sanitation technology reaches fleet deployment.
Solid-state vacuum pump architecture is miniaturizing the pressure-generation subsystem from 15-liter to sub-4-liter displacements without flow-rate degradation. Japanese and Korean high-speed operators are specifying these compact units for distributed toilet configurations in double-deck rolling stock. The technology is miniaturizing spatial constraints in lavatory module design, allowing manufacturers to reclaim passenger seating density or expand accessibility features within fixed carbody envelopes.
The EU F-Gas Regulation is constraining refrigerant selections in climate-controlled toilet modules, forcing suppliers to validate CO2 heat pump alternatives or hydrocarbon blends for European corridor deployment. Rolling stock OEMs are redesigning HVAC-integrated sanitation pods to meet 2030 phase-down milestones. Eastern European retrofit programs are absorbing the highest compliance costs due to aged fleet bases and fragmented operator procurement coordination.
After-sales service unbundling is disrupting traditional OEM-captive maintenance models. Australian and North American freight operators are contracting directly with component specialists for vacuum pump overhaul and sensor calibration, bypassing rolling stock manufacturers. This pattern is most visible in privately operated intermodal corridors where asset ownership separates from fleet management, compressing OEM service attach rates by 15-20 percentage points in mature markets.
Railcar Vehicle Toilet Market Segmentation
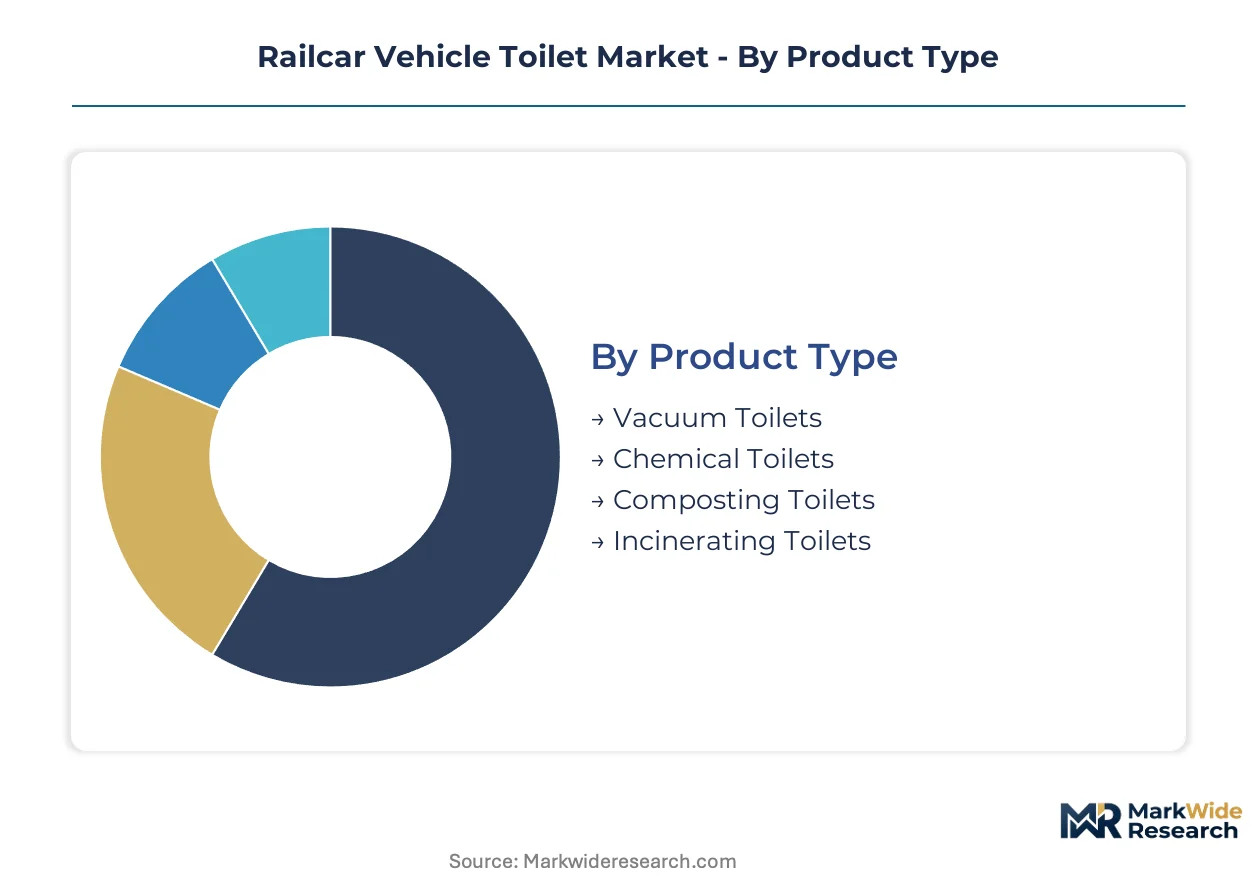
Railcar sanitation procurement splits across four intersecting dimensions. Technology choice dictates regulatory compliance paths, while installation type determines whether suppliers capture OEM attach rates or aftermarket service contracts.
Product Type:
Vacuum systems face intensifying substitution pressure from composting alternatives in heritage corridors, while chemical toilets confront outright phase-out under tightened effluent rules.
- Vacuum Toilets:These fixtures operate at 3.5–5 bar differential pressure to evacuate waste into retention tanks, achieving water consumption below 0.5 liters per flush. China's CRRC supply chain corridor absorbs the dominant share of global vacuum system output through state-aligned high-speed rail programs. EN 15085 welding certification requirements limit qualified tank fabricators, compressing supplier margins during nickel price volatility.
- Composting Toilets:Bio-digester architectures eliminate retention tank weight entirely through aerobic decomposition, enabling zero-discharge compliance for scenic routes in the Alps and Rocky Mountains. Heritage rail operators in North America and Central Europe pilot these systems to extend rolling stock range and reduce infrastructure dependency.
- Chemical Toilets:Recirculating blue-fluid systems persist in Eastern European narrow-gauge networks and Latin American regional services where capital constraints override effluent compliance timelines.
- Incinerating Toilets:High-temperature combustion units serve Arctic climate deployments where vacuum system reliability degrades below minus 40 degrees Celsius.
Vacuum toilets retain volume leadership; composting toilets hold the steepest expansion curve.
End User:
Passenger fleet operators concentrate procurement authority, while freight and maintenance segments fragment purchasing across decentralized asset owners.
- Passenger Trains:High-speed operators in Japan, South Korea, and China specify integrated sanitation-HVAC modules with F-Gas-compliant refrigerants. Double-deck configurations demand compact vacuum pump architectures to reclaim passenger density.
- Freight Trains:North American Class I railroads and Australian intermodal operators contract directly with component specialists for vacuum pump overhaul, bypassing OEM service networks. Crew cab sanitation represents a small but specification-intensive niche.
- Maintenance Services:Third-party refurbishment providers capture retrofit demand in mature European networks where rolling stock life extension programs defer capital replacement.
- Rail Operators:State-owned entities in India and Southeast Asia consolidate procurement for electrification corridors, creating first-mover positioning for EN 15085-certified integrators.
Passenger trains dominate absolute unit demand; freight operators are expanding most quickly through direct component sourcing.
Technology:
Waterless architectures displace legacy pneumatic systems in arid climate corridors, while bio-technology validation protocols remain fragmented across national regulators.
- Waterless Solutions:Zero-flush vacuum designs reduce onboard water weight by 200–400 kilograms per car, extending range for Australian and Middle Eastern operators. These systems specify solid-state vacuum pumps with sub-4-liter displacements.
- Regenerative Systems:Waste heat recovery from braking systems pre-heats retention tanks in Nordic deployments, reducing energy draw for climate-controlled modules.
- Pneumatic Systems:Compressed-air actuation persists in legacy Eastern European fleets where infrastructure retrofit capital is constrained.
- Bio-Technology:Anaerobic digester validation protocols diverge between EU ECHA guidance and China's MEE municipal wastewater interface standards, complicating cross-border certification.
Waterless solutions command the largest installed base; bio-technology is climbing the fastest as zero-discharge mandates proliferate.
Installation Type:
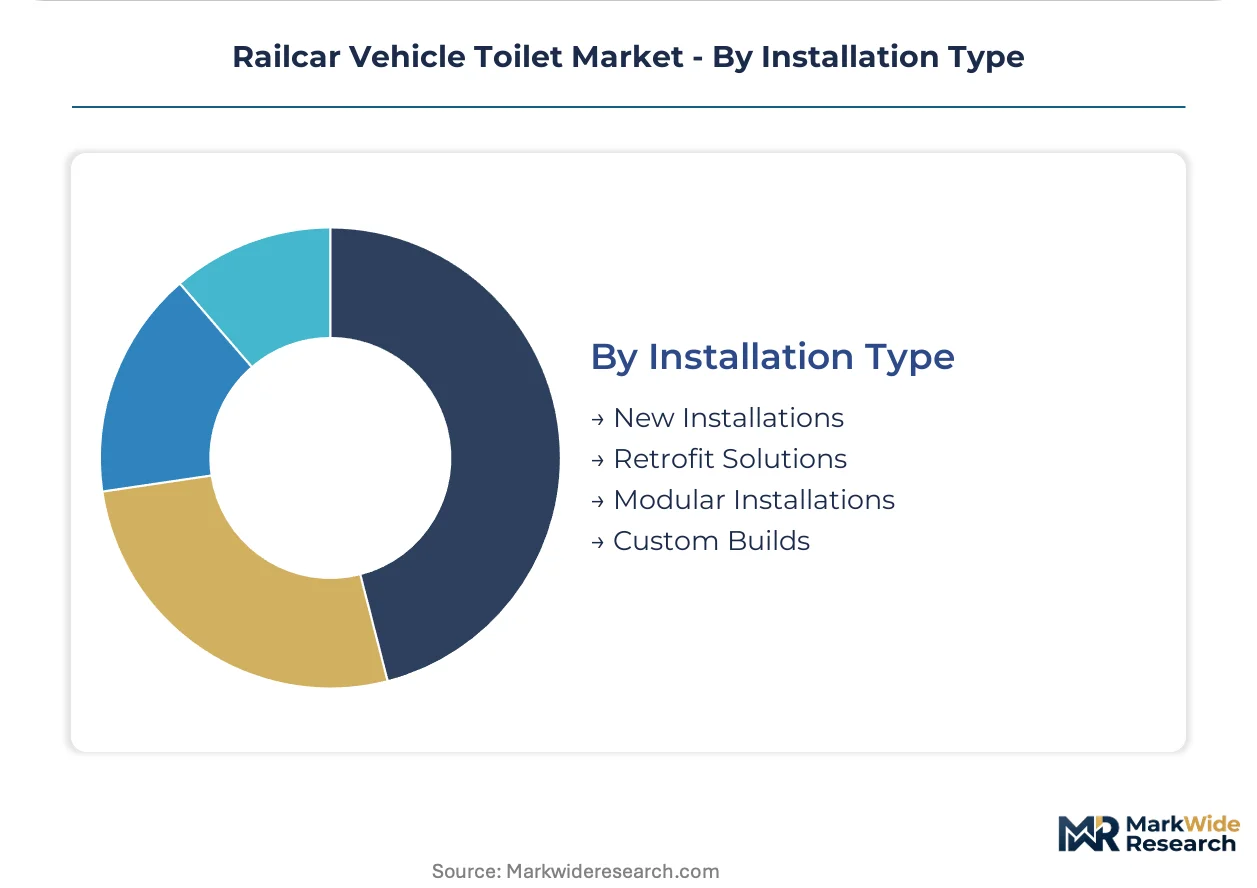
Retrofit programs outpace new build demand in saturated networks, while modular architectures compress field installation timelines for fleet operators.
- New Installations:OEM supply agreements for CRRC, Alstom, and Siemens rolling stock programs specify captive sanitation module procurement with 15–20 year service attach rates.
- Retrofit Solutions:Legacy rolling stock interface fragmentation forces custom adapter fabrication on the majority of refurbishment programs, extending project timelines. European F-Gas compliance retrofits absorb concentrated demand.
- Modular Installations:Pre-integrated lavatory pods reduce field commissioning from weeks to days, appealing to operators with compressed maintenance windows.
- Custom Builds:Narrow-gauge and heritage specifications require bespoke tank geometries and pressure calibrations outside standard product ranges.
Retrofit solutions capture the highest project volume; modular installations are gaining share fastest through commissioning efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE municipal wastewater interface standards are accelerating vacuum system certification timelines across state rail corridors. India's Dedicated Freight Corridor and electrification programs are absorbing EN 15085-certified sanitation modules. European F-Gas Regulation phase-down mandates are concentrating retrofit demand in Germany and Eastern European networks.
China
CRRC's supply chain corridor dominates vacuum system absorption through state-aligned high-speed rail programs. MEE effluent standards force domestic certification for retention tank interfaces. Zhuzhou and Qingdao manufacturing clusters supply captive output to adjacent Southeast Asian modernization initiatives.
India
The Mumbai-Ahmedabad high-speed line and Dedicated Freight Corridor specify EN 15085-certified sanitation modules for electrification corridors. Indian Railways' procurement consolidation creates positioning advantages for qualified integrators. Manufacturing activity concentrates in Gujarat and Maharashtra component hubs.
Germany
F-Gas Regulation refrigerant phase-down mandates drive climate-controlled toilet module retrofits across Deutsche Bahn's aged fleet base. KBA rail vehicle approvals constrain supplier eligibility for European corridor deployment. Industrial concentration in Baden-Württemberg and Bavaria anchors component fabrication.
United States
EPA Clean Water Act effluent limits shape rail yard discharge compliance for Class I railroad sanitation retrofits. Privately operated intermodal corridors fragment procurement across decentralized asset owners. Midwest and Southern rail manufacturing clusters absorb vacuum pump overhaul demand directly from operators.
Japan
METI rail technology standards and Shinkansen fleet renewal programs specify compact vacuum pump architectures for double-deck configurations. Solid-state pressure-generation subsystems miniaturize lavatory footprints. Industrial activity clusters in Nagoya and Osaka prefectures for rolling stock component supply.
Railcar Vehicle Toilet Market Competitive Landscape
Player mix skews toward integrated rolling stock suppliers and specialized vacuum system fabricators. Market structure concentrates around three strategic tiers: state-aligned OEMs with captive sanitation divisions, European specialists with EN 15085 certification depth, and regional component assemblers serving retrofit demand. Dominant competitive moves include backward integration into retention tank fabrication and technology licensing partnerships for solid-state vacuum architectures.
Among the integrated platform suppliers, WABTEC exemplifies the North American retrofit-focused archetype through its braking-sanitation convergence. EVAC occupies a position within the Nordic climate-resilience specialization tier. Zhuzhou CRRC Times Electric represents the state-aligned scale-driven archetype, anchoring domestic Chinese procurement through project alignment with national rail programs.
| Leading Market Players |
|---|
| WABTEC |
| EVAC |
| Huatie Tongda |
| Rolen Technologies & Products |
| Dowaldwerke |
| Glova Rails |
| Goko Seisakusho |
| Qingdao Victall Railway |
| Zhuzhou CRRC Times Electric |
| Others |
Pricing and Supply Chain Analysis
Solid-state vacuum pump displacement of legacy compressor architectures is redrawing procurement geography and compressing price premiums for compact pressure-generation subsystems. This substitution simultaneously concentrates supply authority in Japanese and Korean component clusters while eroding margins for European fabricators locked into 15-liter displacement designs.
Pricing Analysis
Certification level creates the primary spread across EN 15085 orbital welding grades, separating premium tank fabricators from uncertified competitors. Project-based contract structures dominate, with price differentiation anchored in welding qualification depth and refrigerant compliance tier for F-Gas-regulated modules. Cost compression in standard vacuum pump tiers is intensifying because Chinese state rail programs consolidate procurement volume. Heritage operators exhibit highest price sensitivity; high-speed rail OEMs prioritize certification reliability over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending component delivery timelines for European retrofit programs. Supply concentrates in China, Germany, and Japan for vacuum pump architectures, retention tank fabrication, and climate control integration. Raw material flows draw from austenitic stainless steel mills and rare-earth magnet suppliers for solid-state compressors. Single-source vulnerability in high-reliability compressor architectures exposes buyers to capacity bottlenecks. Distribution runs through rolling stock OEM captive networks and direct operator contracting in North American freight corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through state rail procurement consolidation in China and India, fragmenting supplier pricing authority across EN 15085-certified integrators and uncertified assemblers.
For Market Incumbents: Consolidate backward into retention tank fabrication to capture nickel price volatility margins and defend against Chinese state-aligned competitors. Deepen EN 15085 welding qualification depth to extend certification moats. Prioritize solid-state vacuum pump licensing partnerships to neutralize Japanese and Korean technology advantages. For New Entrants and Emerging Players: Differentiate on composting bio-digester architectures for Alpine and Rocky Mountain heritage routes where zero-discharge mandates outpace vacuum system adaptation. Target Indian electrification corridors for EN 15085 certification positioning. Pursue direct component supply contracts with Australian and North American freight operators bypassing OEM service networks. For Investors and Strategic Acquirers: The EU F-Gas Regulation phase-down reshapes the acquisition landscape toward refrigerant-compliant climate control integrators. Long-term viability favors specialists with dual certification depth across welding and HVAC integration. Monitor EN 15085 qualification queue lengths as inflection signal for supplier scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EN 15085 Certification Investment | Welding qualification depth locks out uncertified competitors from CRRC and Indian Railways procurement cycles. |
| Solid-State Vacuum Pump Licensing | Technology partnerships with Japanese and Korean specialists compress displacement footprints for double-deck configurations. |
| Retention Tank Backward Integration | In-house austenitic fabrication insulates margins from nickel price swings and supply agreement volatility. |
| F-Gas Compliant HVAC Integration | CO2 heat pump validation opens European retrofit demand as refrigerant phase-down milestones approach. |
| IoT Sensor Platform Development | Predictive maintenance unbundling captures recurring revenue from operator IT budgets in Australian and North American freight corridors. |
Research Methodology
Desk research of trade customs databases, rolling stock procurement registries, and welding certification authority records preceded structured interviews with rail OEM procurement directors, vacuum system engineering leads, EN 15085 certification auditors, and heritage rail operator maintenance chiefs. Primary intelligence combined with secondary validation from EPA effluent filings, EU F-Gas Regulation implementation reports, and China MEE municipal wastewater interface standards. Bottom-up unit deployment estimates triangulated against top-down rolling stock fleet projections.
Variance decomposition across technology substitution rates, regulatory compliance timelines, and raw material price corridors shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, installation category, end-user archetype, and regional regulatory cluster. CAGRs derived from fleet expansion schedules and retrofit penetration curves. Industry-specific inputs incorporated EN 15085 qualification queue dynamics and solid-state vacuum pump adoption trajectories in East Asian high-speed programs.
The analysis sits within stated boundaries; outcomes outside sustained state rail investment levels, stable nickel pricing corridors, or harmonized bio-digester validation protocols would require recalibration. Forecasts reflect documented assumptions regarding F-Gas phase-down adherence and Chinese domestic procurement preference continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Automatic Train Supervision Market
Railway
Global Train Lighting Market
Railway
Rail Glazing Market
Railway
Rail Bellows Market
Railway
Rolling Stocks Market
Railway
Rail Brake Frame Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
Smart Railways Market
Railway
India Rail Freight Transport Market
Railway
Locomotive Radiator Fan Market
Railway
Rail Transit Traction Converter Market
Railway
France Connected Rail Market
Railway
Railway Engine Market
Railway
Freight Cars Market
Railway
Railroad Brake Shoe Market
Railway
Railway System Market