
 Hydrogen Trains Market | 2026-2036
Hydrogen Trains Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Trains Market Intelligence
The pool of engineers with dual expertise in railway systems and high-pressure hydrogen fuel cell integration is collapsing the traditional divide between rolling stock and energy system development. Alstom leverages its first-mover advantage with extensive operational data from its Coradia iLint platform. Siemens competes directly through its Mireo Plus H family, focusing on modularity and efficiency for regional networks. Ballard Power Systems specializes in providing the core fuel cell modules to multiple train manufacturers.
Hydrogen trains are rail vehicles that use onboard fuel cells to convert hydrogen into electricity, which powers the traction motors. These systems store hydrogen in high-pressure tanks, typically on the roof, and produce water as their only emission. Within applications, commuter rail represents the primary use case, targeting the replacement of diesel multiple units on non-electrified lines. New fleet deployment is the main installation type, as retrofits face higher costs and complex integration hurdles compared to purpose-built rolling stock.
The EU Green Deal and its transport policies create direct incentives for public transit authorities to adopt hydrogen solutions. In parallel, China's dual carbon goals drive state-owned enterprises like CRRC to develop domestic hydrogen train technology, while infrastructure funding in the US supports pilot projects. Stakeholder decisions now hinge on securing long-term green hydrogen supply agreements to ensure the economic viability of new fleet investments.
Market Dynamics
The central force shaping the hydrogen train market is the imperative for decarbonization on non-electrified railway lines, driven by national climate policies. This creates a direct replacement demand for aging diesel multiple unit fleets, particularly within regional and commuter rail networks.
Growth Catalysts
- EU Green Deal Framework:Mandates for zero-emission transport solutions compel public transit authorities, especially in Germany and France, to invest in hydrogen fleets for regional networks to meet national targets.
- Technology Maturation:Advances in high-pressure hydrogen storage tanks and increased fuel cell power density are improving train range and operational performance, making them a viable alternative to diesel.
- National Decarbonization Pledges:China's dual carbon goals are stimulating state-led development of hydrogen train prototypes for domestic use, expanding the market's geographic footprint beyond its initial European focus.
Market Restraints
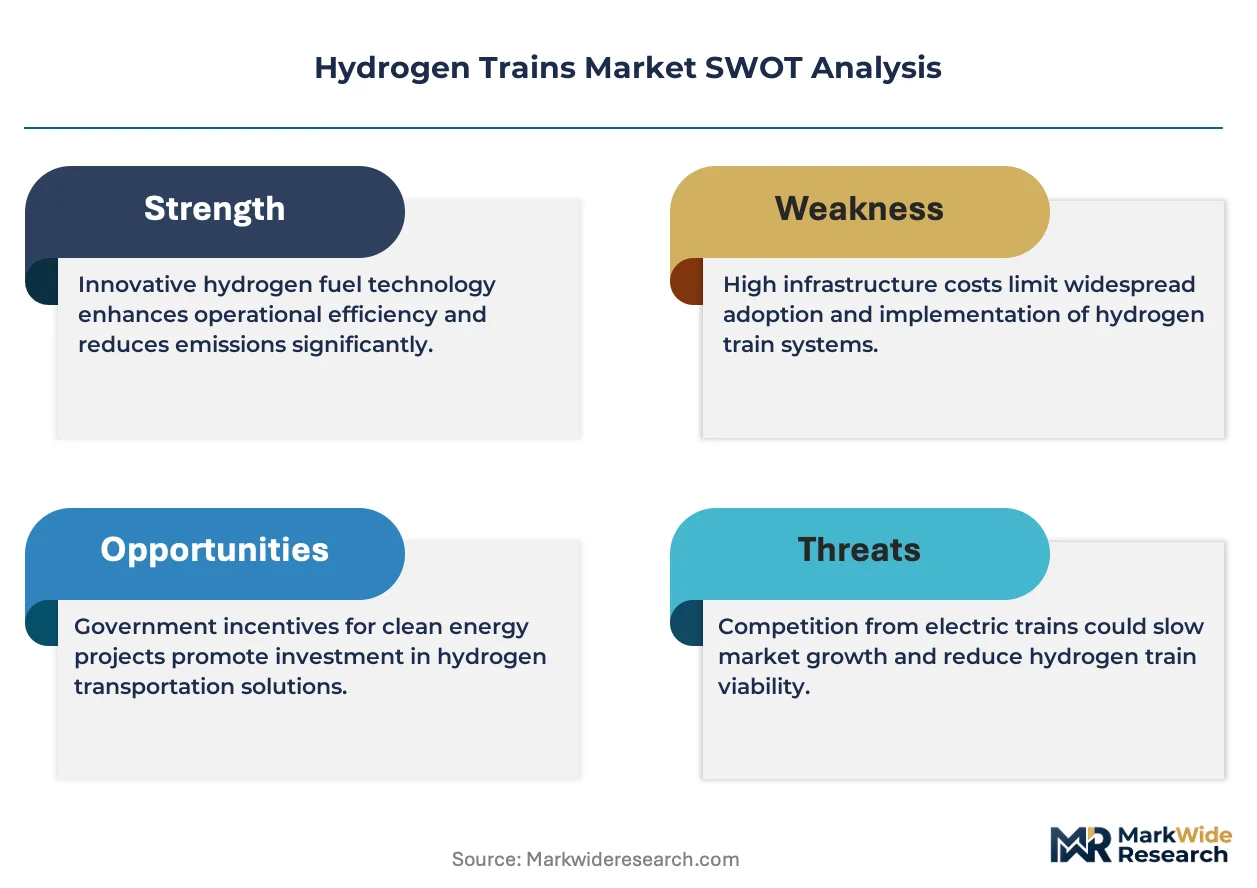
- Green Hydrogen Scarcity:The limited availability and historically high cost of certified green hydrogen create significant operational cost uncertainty and supply risk for rail operators planning long-term fleet deployment.
- Infrastructure Dependency:Hydrogen trains require dedicated refueling infrastructure at depots, a capital-intensive prerequisite that slows down deployment compared to leveraging existing electric or diesel infrastructure.
- High-Pressure System Complexity:Integrating high-pressure hydrogen storage systems into rolling stock presents unique engineering and safety certification challenges, distinct from traditional railway vehicle design and maintenance protocols.
Strategic Opportunities
- North American Pilot Programs:Infrastructure funding under policies like the US IRA supports pilot projects, creating an entry point for manufacturers to demonstrate viability in a market with extensive non-electrified lines.
- Retrofit Module Development:Designing standardized hydrogen power packs for retrofitting existing diesel fleets could open a new service-oriented market, though complex integration and recertification hurdles remain.
- Heavy-Haul Freight Application:Adapting fuel cell technology for long-distance, heavy-haul freight locomotives represents a future growth vector, moving beyond the current focus on passenger commuter rail.
Industry Challenges
- Specialized Engineering Talent:A shortage of engineers possessing combined expertise in both railway vehicle dynamics and high-pressure fuel cell systems constrains the pace of new product development and integration projects.
- Refueling Standardization:The lack of universal standards for hydrogen refueling nozzles, pressure protocols, and data communication between trains and depots complicates interoperability across different networks and suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Trains Market |
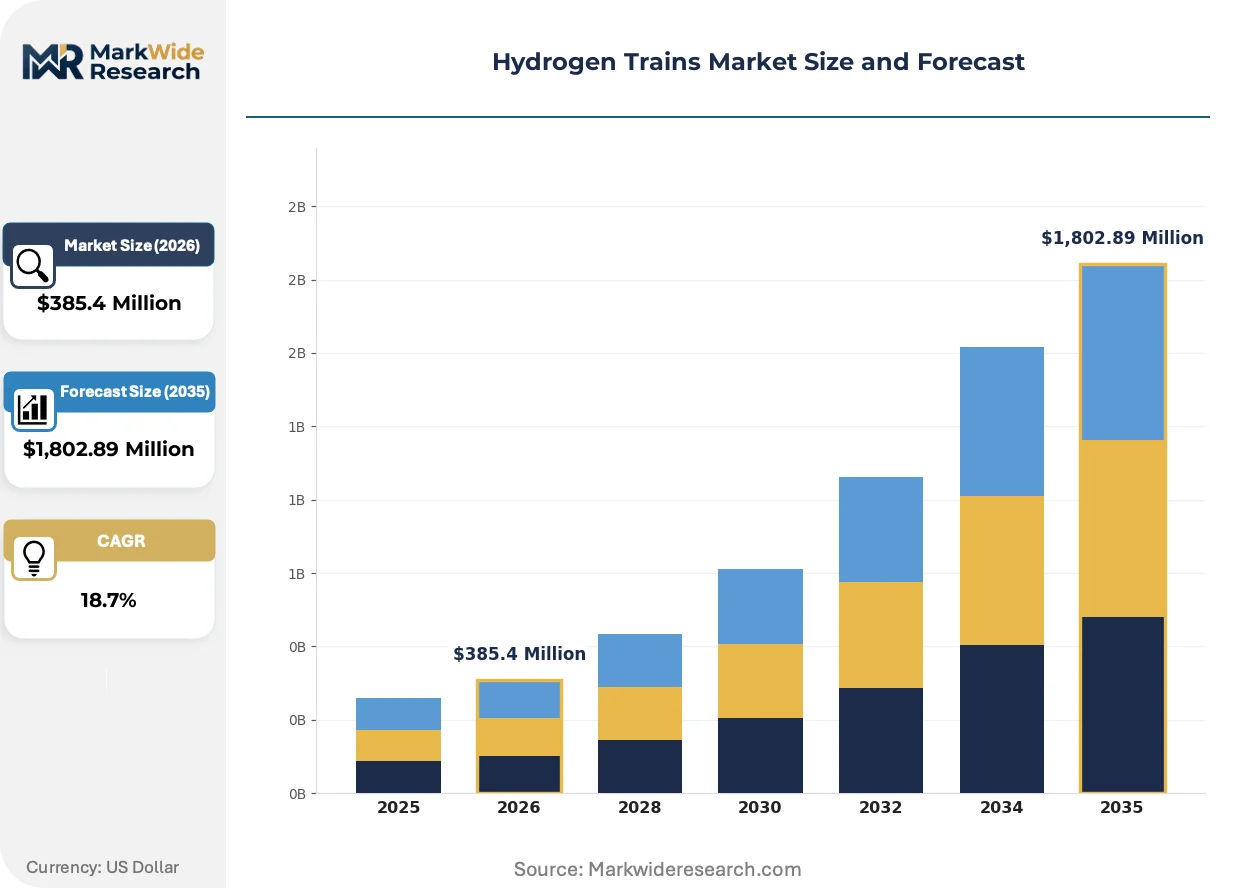
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Fuel Cell Electric, Hybrid Hydrogen, Battery Electric, Diesel-Hydrogen Blend Application: Commuter Rail, High-Speed Rail, Light Rail Transit, Freight Transport End User: Passenger Operators, Freight Carriers, Public Transit Authorities, Private Rail Companies Installation Type: New Fleet Deployment, Retrofit Conversion, Infrastructure Expansion, Pilot Projects |
| Companies Covered | Alstom, Siemens, Ballard Power Systems, CRRC Corporation, Hitachi, Stadler Rail, Bombardier Transportation, Wabtec Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Trains Market Strategic Shifts & Innovations
The market's focus is evolving from isolated pilot projects to the strategic development of scalable, networked deployments. This shift prioritizes the creation of integrated ecosystems that include guaranteed green hydrogen supply, refueling infrastructure, and long-term maintenance alongside the rolling stock itself.
Fuel cell powertrain design is a central area of innovation for train manufacturers. System integrators are rapidly adopting more efficient and compact modules to improve performance. The approach to powertrain architecture is bifurcating between fully integrated, purpose-built trains and modular, self-contained 'power packs' that can be adapted to multiple rolling stock platforms.
The EU's Renewable Energy Directive establishes strict criteria for what qualifies as green hydrogen, directly impacting fuel procurement strategies. This policy forces rail operators to verify the lifecycle emissions of their hydrogen supply to comply with funding and transport mandates. Public transit authorities in Germany and France are most affected, now structuring supply contracts around certified renewable fuels.
A shift towards 'transport-as-a-service' models is altering fleet acquisition strategies for public authorities. This approach disrupts the traditional capex-heavy procurement cycle where operators own the rolling stock outright. Instead, contracts may bundle the vehicles, maintenance, and fuel supply, which is most visible in regional German networks seeking to de-risk technology adoption.
Hydrogen Trains Market Segmentation
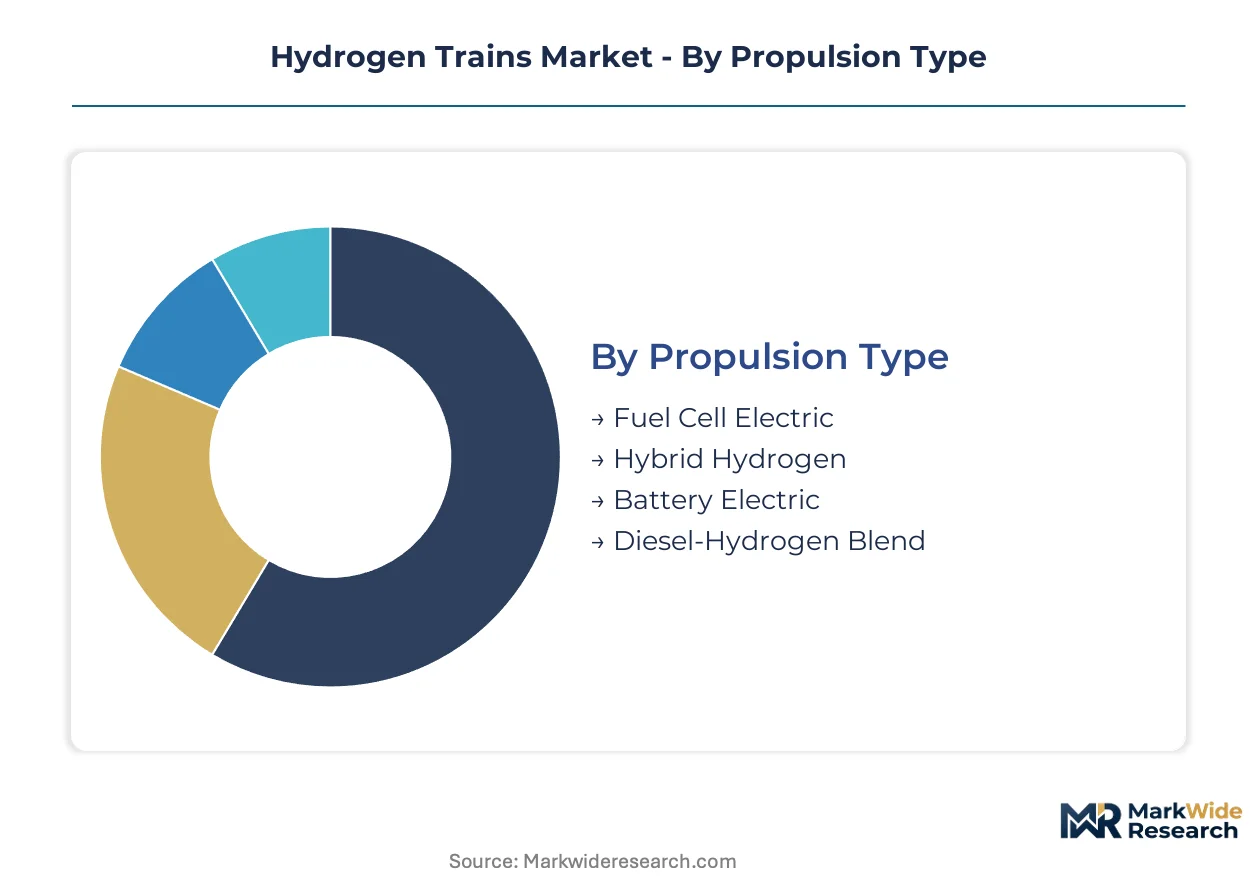
The hydrogen trains market segmentation clarifies how different technological approaches and operational applications drive adoption across diverse railway networks. Understanding these distinct categories helps stakeholders identify specific investment opportunities and target development efforts. This granular view highlights the varying pathways for decarbonizing rail transport.
Propulsion Type:
The channel mix for hydrogen train propulsion systems reflects the evolving technical maturity and operational preferences of rail operators.
- Fuel Cell Electric:These trains use onboard hydrogen fuel cells to generate electricity, directly powering traction motors and producing only water vapor emissions. Demand concentrates in Germany and France, where public transit authorities prioritize zero-emission solutions for regional non-electrified lines.
- Hybrid Hydrogen:This configuration combines hydrogen fuel cells with a battery energy storage system, optimizing power delivery and regenerative braking for enhanced efficiency. European operators are increasingly adopting hybrid systems to balance range requirements with peak power demands on commuter routes.
- Battery Electric:These units primarily run on electricity from onboard batteries, which can be recharged via hydrogen fuel cells or external power sources.
- Diesel-Hydrogen Blend:This type uses a mix of diesel and hydrogen in internal combustion engines, offering a transitional solution for reducing emissions in existing diesel fleets.
Fuel Cell Electric dominates installed base. Hybrid Hydrogen is where expansion concentrates.
Application:
Application segmentation delineates the specific operational contexts where hydrogen trains provide the most effective decarbonization solutions.
- Commuter Rail:These applications involve regional passenger services on non-electrified lines, often replacing diesel multiple units with frequent stops and moderate speeds. Demand for these trains is strong in European markets, particularly due to the EU Green Deal's mandates for zero-emission public transport.
- Freight Transport:This segment includes heavy-haul locomotives designed for long-distance cargo movement, requiring significant power output and extended operational ranges. Pilot projects in North America are exploring fuel cell technology for freight, leveraging existing rail infrastructure with extensive non-electrified sections.
- High-Speed Rail:This category focuses on very fast passenger services, where hydrogen solutions face challenges due to the high power demands and existing electrification infrastructure.
- Light Rail Transit:These systems serve urban and suburban areas with lower passenger capacities and speeds, often utilizing existing tram or light rail networks.
Commuter Rail applications drive current demand. Freight Transport is gaining share fastest.
End User:
End user segmentation highlights the distinct procurement behaviors and operational requirements of various railway system stakeholders.
- Public Transit Authorities:These government-backed entities oversee regional and municipal rail networks, often driven by decarbonization mandates and public funding initiatives. They are central to new fleet deployment in Germany and France, where the EU Green Deal provides direct incentives for hydrogen adoption.
- Passenger Operators:These companies manage passenger services on both public and private lines, balancing operational efficiency with environmental compliance and passenger experience. Their decisions hinge on securing long-term green hydrogen supply agreements to ensure economic viability.
- Freight Carriers:These organizations transport goods across extensive rail networks, seeking robust and cost-effective solutions for heavy-haul operations.
- Private Rail Companies:These entities own or lease rolling stock for specialized services, often prioritizing bespoke solutions and flexible operational models.
Public Transit Authorities lead initial procurement. Passenger Operators are aligning long-term fleet strategies with hydrogen availability.
Installation Type:
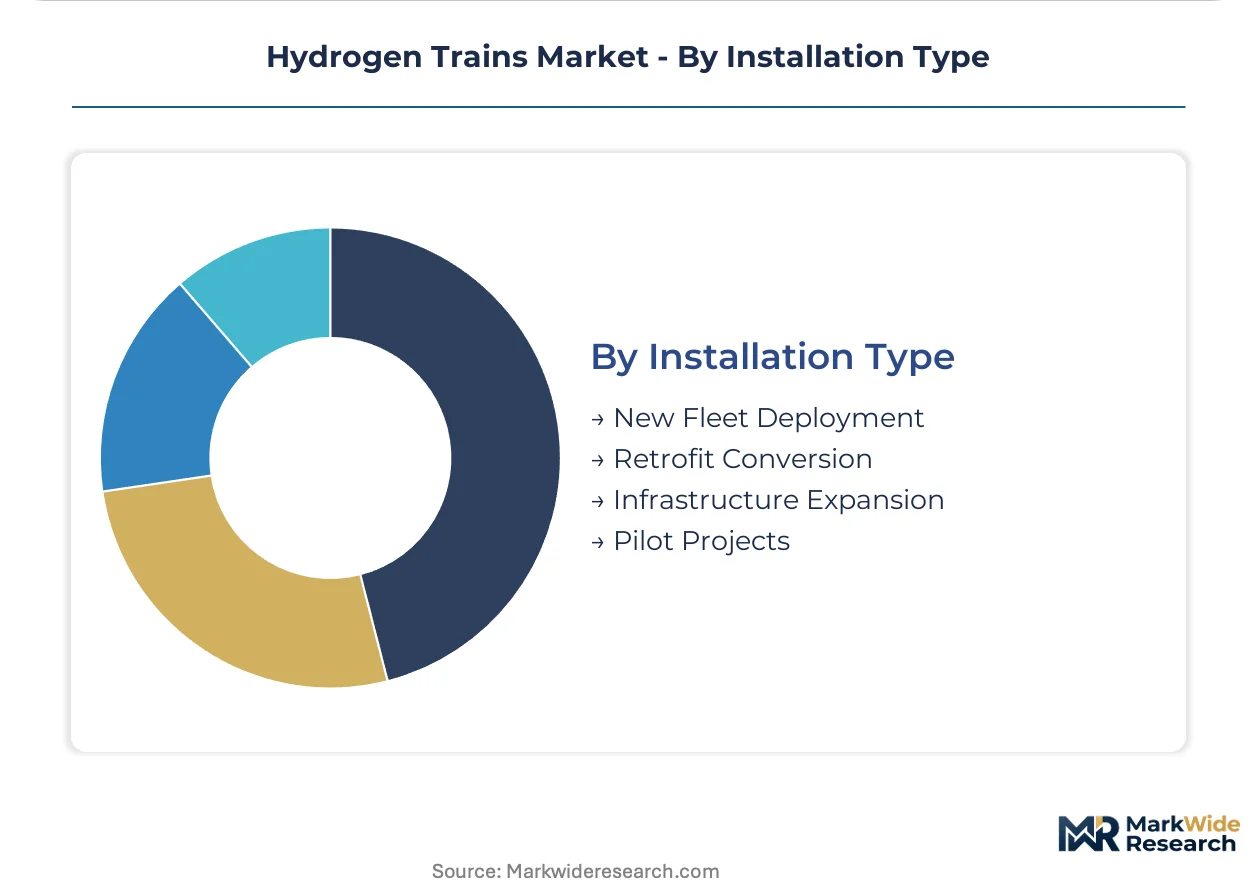
Installation type segmentation differentiates between the capital expenditure profiles and integration complexities associated with hydrogen train deployment.
- New Fleet Deployment:This involves acquiring purpose-built hydrogen trains for entirely new services or as direct replacements for aging diesel fleets, minimizing integration challenges. This type represents the primary installation method, as it avoids complex and costly modifications to existing rolling stock.
- Pilot Projects:These are limited-scale deployments designed to test the viability and performance of hydrogen train technology under specific operational conditions, often with government funding. Infrastructure funding in the US supports these initiatives, creating entry points for manufacturers to demonstrate system effectiveness.
- Retrofit Conversion:This segment includes modifying existing diesel trains to operate on hydrogen fuel cells, facing higher costs and significant engineering hurdles.
- Infrastructure Expansion:This refers to the development of new hydrogen production, storage, and refueling facilities required to support widespread train operations.
New Fleet Deployment drives current market volume. Pilot Projects are critical for future market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hydrogen trains market exhibits a consumption-mix differential, with European nations prioritizing commuter rail replacements while North America and China focus on broader applications including freight. This geographic divergence stems from varied policy landscapes and existing rail infrastructure. Public transit authorities in Germany and France are driving initial deployments.
Germany
Demand for hydrogen trains in Germany is driven by the imperative to decarbonize regional networks and replace aging diesel multiple units. The EU Green Deal provides significant impetus for public transit authorities to invest in zero-emission solutions. Regional networks in Lower Saxony are pioneering multiple hydrogen train deployments, demonstrating operational viability.
France
French rail operators are advancing hydrogen train adoption through national decarbonization goals and regional modernization initiatives. Policies stemming from the EU Green Deal compel public transit authorities to transition towards sustainable transport. The Occitanie region, for instance, actively supports the development of new hydrogen train corridors.
China
China's demand for hydrogen trains stems from its dual carbon goals, driving both emissions reduction and domestic technology development. State-owned enterprises receive direct incentives to develop zero-emission rail solutions for various applications. CRRC in Qingdao is a central hub for developing hydrogen train prototypes for the country's extensive rail network.
United States
The United States market is exploring hydrogen trains to replace diesel locomotives on its vast non-electrified rail lines. Infrastructure funding under the US IRA supports pilot projects and feasibility studies across different states. California is actively pursuing hydrogen train initiatives for both commuter services and potential freight applications.
United Kingdom
The United Kingdom's rail decarbonization strategy is creating demand for hydrogen trains on non-electrified routes. The government's net-zero targets encourage railway companies to explore clean traction solutions. The HydroFLEX project in Warwickshire successfully demonstrated hydrogen train capabilities for future deployment.
Hydrogen Trains Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape of the hydrogen trains market. This structure combines established rolling stock manufacturers with emerging fuel cell technology providers and system integrators. Strategic partnerships for green hydrogen supply and refueling infrastructure development represent a dominant competitive move. Geographic expansion into new regions with extensive non-electrified lines is also a key strategy, alongside technology licensing agreements.
Within the integrated rolling stock manufacturer tier, Alstom and Siemens exemplify companies leveraging extensive railway expertise to develop comprehensive hydrogen train platforms. Alstom, a French multinational, benefits from early operational data from its Coradia iLint platform. Siemens, a German conglomerate, competes directly with its Mireo Plus H family, focusing on modularity and efficiency for regional networks. Ballard Power Systems, a Canadian company, represents the specialist tier, providing core fuel cell modules to multiple train manufacturers, thereby anchoring a critical component of the value chain.
| Leading Market Players |
|---|
| Alstom |
| Siemens |
| Ballard Power Systems |
| CRRC Corporation |
| Hitachi |
| Stadler Rail |
| Bombardier Transportation |
| Wabtec Corporation |
| Thales Group |
| Others |
Cost & Logistics Intelligence
Hydrogen fuel cell technology substituting diesel multiple units simultaneously reshapes European rail supply geography and the economic viability of zero-emission transport. This shift necessitates new infrastructure investment and long-term fuel procurement strategies.
Pricing Analysis
Long-term offtake agreements for green hydrogen and fleet leasing define the primary pricing model for hydrogen trains. Price differentiation stems from the level of after-sales service bundling and the overall train performance specifications. Pricing softness in initial deployments reflects the high upfront capital expenditure and operator de-risking strategies. Public transit authorities, driven by decarbonization mandates, are less price-sensitive than private passenger operators focused on operational efficiency.
Supply Chain Analysis
Germany and France anchor the manufacturing of hydrogen train rolling stock, while Canada specializes in core fuel cell module production. The supply chain for hydrogen trains depends heavily on green hydrogen availability and high-pressure storage tank components. A structural risk is the single-source vulnerability for specialized fuel cell components from key suppliers. Distribution runs through direct sales channels from train manufacturers to public transit authorities and rail operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen trains market is a substitution defense play, with existing diesel fleets representing the primary threat that incumbents must strategically navigate.
For Market Incumbents: Shield market share by deepening vertical integration into hydrogen fuel cell manufacturing or securing long-term supply agreements for green hydrogen. This counters the threat of volatile hydrogen costs and emerging specialized fuel cell providers. Invest in modular train designs for regional networks to accelerate deployment and reduce customization expenses across diverse railway systems.
For New Entrants and Emerging Players: Differentiate on specialized engineering solutions for complex hydrogen system integration and niche applications. Target North American pilot projects, which offer a penetrable segment due to infrastructure funding under policies like the US IRA. A go-to-market angle involves offering comprehensive 'transport-as-a-service' models that bundle rolling stock, maintenance, and green fuel supply.
For Investors and Strategic Acquirers: The market sits at a nascent phase that favors first-mover advantage and technology consolidators. Long-term viability hinges on the successful scale-up of green hydrogen production and widespread refueling infrastructure buildout. Target acquisition archetypes include specialized fuel cell manufacturers or engineering firms with dual railway and hydrogen expertise. A signal to watch is the signing of large-scale, multi-year green hydrogen supply agreements by major European rail operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Supply Agreements | Secures operational viability and reduces long-term fuel cost uncertainty for rail operators. |
| Modular Fuel Cell Powertrain Development | Enhances adaptability across diverse rolling stock platforms and improves maintenance efficiency. |
| Refueling Infrastructure Partnerships | Accelerates deployment by overcoming capital-intensive prerequisites for widespread hydrogen adoption. |
| Dual-Expertise Engineering Talent Programs | Addresses the critical shortage of railway and high-pressure fuel cell integration specialists. |
| Pilot Project Expansion in North America | Establishes market presence and validates technology performance in new, extensive non-electrified regions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with robust secondary validation for this analysis. Stakeholders included public transit authority executives, rolling stock engineers, fuel cell technology developers, and railway infrastructure planners. Secondary data sources comprised government transport policies, industry association reports, and company financial filings. Bottom-up and top-down triangulation ensured data accuracy and forecast consistency.
The forecast horizon spans across the analysis window, utilizing a robust analytical framework to project market growth. Segmentation dimensions modeled include propulsion type, application, end user, installation type, and regional regulatory frameworks. Compound annual growth rates were derived through a regression analysis of historical market trends and projected technology adoption rates. Key forecast inputs include national decarbonization pledges and green hydrogen production capacities.
Material uncertainties — including geopolitical shifts affecting energy supply and unforeseen regulatory changes — sit outside the modeled envelope. Forecasts reflect assumptions regarding technological maturation and sustained government support for zero-emission transport. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Train Suspension System Market
Railway
Railroad Tie Market
Railway
Rail Damper Market
Railway
Solar Train Market
Railway
Europe Intermodal Terminals Market
Railway
Gangway for Railway Vehicles Market
Railway
Trams Market
Railway
Rail Composites Market
Railway
Railway Window Market
Railway
Rail Glazing Market
Railway
Locomotive Parking Brake Market
Railway
Connected Rail Market
Railway
Rail Bellows Market
Railway
Railway Braking System Market
Railway
Global High-Speed Train Seat Market
Railway
Global Hyperloop Train Market