
 Building Applied Photovoltaics (BAPV) Market | 2026-2036
Building Applied Photovoltaics (BAPV) Market Size, Share, and Industry Trends Forecast 2026-2036
Building Applied Photovoltaics (BAPV) Market Outlook
Module bundling with racking and inverter packages is repositioning procurement patterns for retrofit installers. First Solar leverages thin-film efficiency gains to anchor utility-scale retrofit portfolios. Onyx Solar Group LLC specializes in transparent photovoltaic glass for commercial facades. Heliatek GmbH competes with organic photovoltaic rolls designed for curved architectural surfaces.
Building Applied Photovoltaics denotes solar generation systems mounted onto existing building structures rather than integrated during construction, typically employing crystalline silicon cells with conversion efficiencies ranging from 18% to 22% and aluminum-framed modules secured via structural racking to offset grid electricity for occupied buildings. Monocrystalline technology leads installed capacity due to superior efficiency per square meter, while CIGS thin-film segments capture niche applications where weight constraints or flexible substrates matter. Commercial Structures generate the dominant share of project value, though Public Infrastructure applications are expanding fastest as municipal energy mandates tighten.
FERC net metering rules in the United States, EU Green Deal building renovation requirements, and Japan METI feed-in tariff adjustments collectively reshape project economics and interconnection standards across major markets. EMA and national building regulators in Europe enforce CE marking and fire safety classifications that filter non-compliant suppliers from retrofit tenders. Stakeholders must track evolving subsidy phase-out schedules and local content rules to time capacity commitments and supply chain positioning.
Market Dynamics
Retrofit mandates across Germany, Japan, and the United States are compressing installation timelines and forcing module suppliers to bundle racking and inverter packages into single procurement SKUs, restructuring how commercial developers source building envelope upgrades.
Growth Catalysts
- EU Green Deal building renovation requirements:Minimum renewable thresholds for major renovations in European Union member states are accelerating facade-integrated retrofit pipelines, particularly in Germany's commercial segment.
- Japan METI feed-in tariff adjustments:Revised compensation structures for building-mounted solar generation are improving project economics for commercial real estate owners evaluating envelope upgrades.
- Thin-film efficiency gains:Cadmium telluride and CIGS cell technologies are capturing niche applications where weight constraints or curved substrates limit crystalline silicon deployment.
Market Restraints
- Aluminum frame and racking cost volatility:Structural mounting hardware input prices fluctuate with commodity metal markets, compressing installer margins on fixed-price retrofit contracts.
- Polysilicon supply concentration:Crystalline silicon cell production depends on purified silicon feedstock concentrated in Chinese manufacturing clusters, creating geopolitical exposure for non-integrated module assemblers.
- Fire safety classification friction:CE marking and national building regulator fire ratings in Europe filter non-compliant suppliers from public infrastructure tenders, extending qualification timelines.
Strategic Opportunities
- Municipal energy mandates:Public infrastructure applications are expanding fastest as city-level renewable procurement targets tighten, creating dedicated retrofit budgets for government buildings.
- Transparent photovoltaic glass convergence:Building-integrated transparent modules combined with conventional curtain wall systems enable net-zero envelope designs without sacrificing daylighting performance.
- Organic photovoltaic substrate innovation:Heliatek GmbH and comparable developers are producing flexible organic rolls designed for curved architectural surfaces, opening heritage building applications where rigid modules fail.
Industry Challenges
- Façade engineering skill scarcity:Building envelope retrofit projects require specialized structural assessment and waterproofing expertise that conventional solar installers lack, extending project timelines.
- Interconnection standard fragmentation:FERC net metering rules in the United States vary by state utility jurisdiction, complicating standardized system designs for national installation fleets.
- Legacy electrical infrastructure compatibility:Older commercial buildings require service panel upgrades and load analysis before BAPV systems can achieve permitted capacity, adding soft costs to retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Applied Photovoltaics (BAPV) Market |
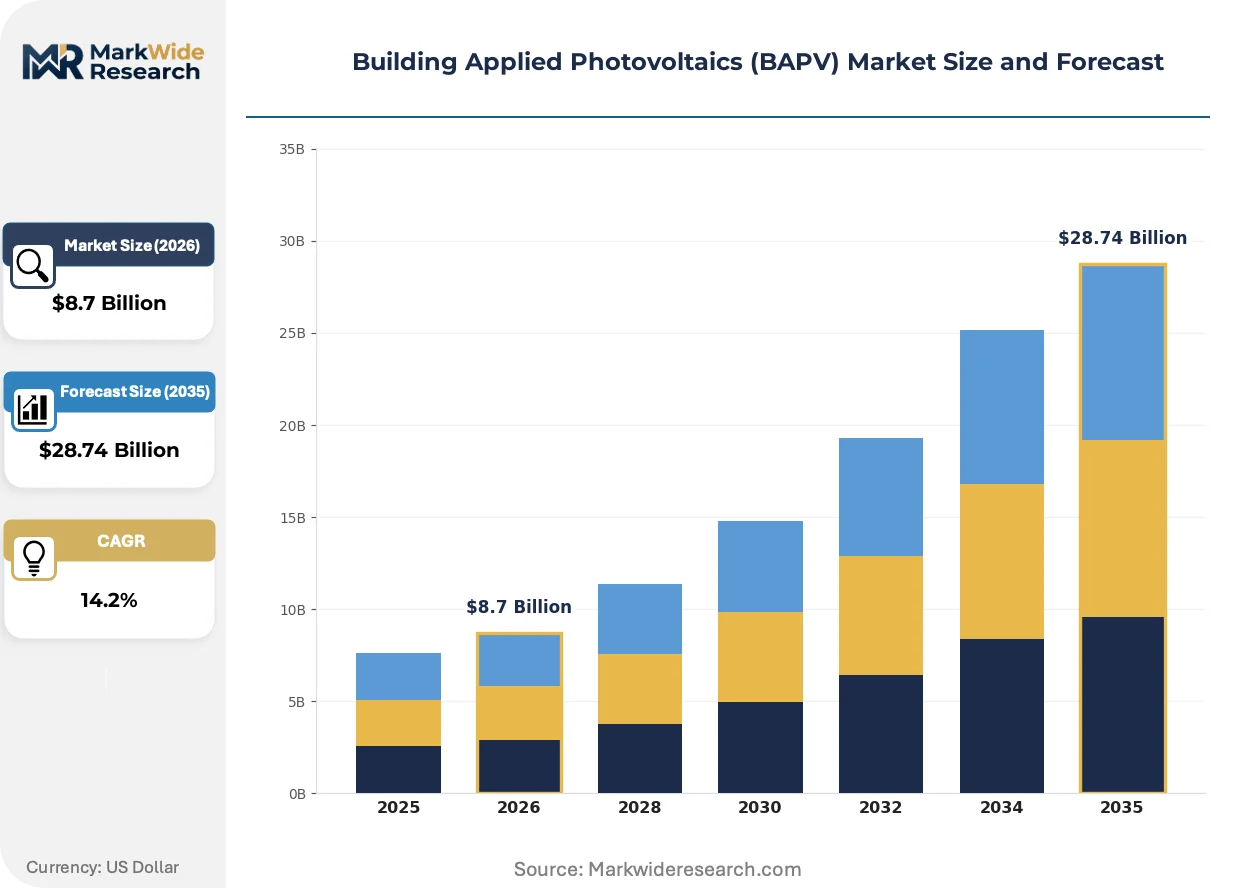
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent PV, BIPV Modules, Building-Integrated Modules, Energy Roofs Technology: CIS, CIGS, Monocrystalline, Polycrystalline Application: Residential Buildings, Commercial Structures, Industrial Facilities, Public Infrastructure End User: Developers, Contractors, Homeowners, Architects |
| Companies Covered | Onyx Solar Group LLC, First Solar, Heliatek GmbH, Centrosolar Group AG, OPVIUS, Ertex Solartechnik GmbH, Ascent Solar Technologies Inc, Sapa Solar, Sharp Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Applied Photovoltaics (BAPV) Market Strategic Shifts
Module bundling with balance-of-system components is restructuring procurement patterns, while regulatory tightening on building energy performance is accelerating technology substitution in commercial envelope retrofits.
Transparent photovoltaic glass is expanding into commercial curtain wall specifications as building owners seek net-zero operational carbon without sacrificing daylight penetration. Major real estate investment trusts in Germany and Japan are specifying transparent modules for lobby and atrium retrofits, compressing traditional opaque solar thermal and standard PV glass from high-visibility architectural zones. This convergence of energy generation and envelope aesthetics is expanding into heritage-sensitive districts where conventional rack-mounted systems face planning restrictions.
EU Green Deal renovation requirements under the Energy Performance of Buildings Directive are mandating renewable generation minimums for commercial renovations exceeding specific floor area thresholds. Member state transpositions are tightening enforcement timelines, forcing property developers to pre-qualify BAPV suppliers before demolition permits issue. Germany's federal building code amendments are most advanced, with facade-integrated systems now default specifications for Class A energy rating targets in major commercial retrofits.
Commercial real estate developers are consolidating vendor relationships around single-source module-racking-inverter packages, displacing component-by-component procurement that dominated early retrofit markets. National installation firms in the United States are negotiating master service agreements with thin-film suppliers to secure volume pricing for multi-building portfolios. This concentration is most visible in Japan, where METI-certified installers are vertically integrating into engineering procurement construction roles to capture margin from both hardware and installation labor.
Building Applied Photovoltaics (BAPV) Market Segmentation
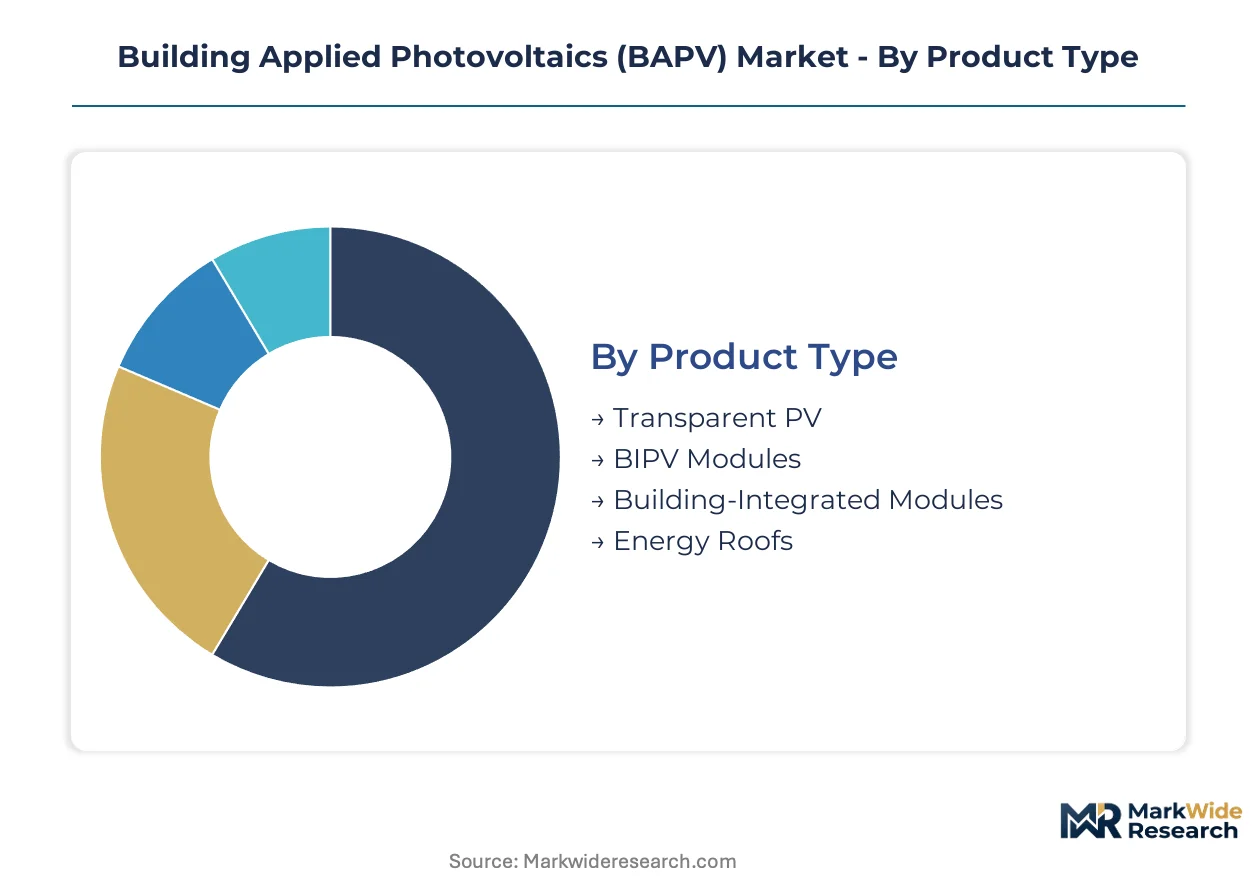
BAPV procurement patterns diverge sharply across product architectures and installation contexts. Technology choices determine structural loading limits and aesthetic integration possibilities. End-user sophistication levels dictate whether projects proceed through bundled turnkey contracts or fragmented component sourcing.
Product Type:
Module supply concentrates among crystalline silicon specialists retrofitting conventional curtain wall systems, while thin-film developers capture heritage and curved-surface niches where rigid substrates fail.
- Transparent PV:Photovoltaic glass with tunable light transmission coefficients enables daylight harvesting while offsetting HVAC loads. Demand clusters in Germany's commercial lobby and atrium retrofits where planning restrictions prohibit opaque systems.
- BIPV Modules:Conventional building-integrated photovoltaic panels replace standard facade cladding materials without secondary mounting hardware. Japanese commercial developers specify these for METI feed-in tariff eligibility on major renovation projects.
- Building-Integrated Modules:Fully integrated envelope systems where the photovoltaic layer serves as the primary weather barrier. Architects in heritage-sensitive districts specify these for planning compliance where visible rack-mounted arrays face rejection.
- Energy Roofs:Complete roof replacement systems combining insulation, waterproofing, and generation in single assemblies. German industrial retrofits favor these for Class A energy rating targets under federal building code amendments.
Today's leader: BIPV Modules. Tomorrow's challenger: Transparent PV.
Technology:
Cell chemistry determines efficiency-per-square-meter, weight loading, and substrate flexibility, with trade-offs between conversion performance and architectural adaptability driving selection patterns.
- Monocrystalline:Single-crystal silicon cells deliver conversion efficiencies between 18% and 22%, maximizing output per unit envelope area. Commercial structures in space-constrained urban cores specify these for rooftop and facade retrofits where area premiums dominate economics.
- CIGS:Copper indium gallium selenide thin-film technology achieves flexible deposition on lightweight substrates. Curved architectural surfaces and weight-constrained heritage buildings deploy these where aluminum-framed crystalline modules exceed structural limits.
- Polycrystalline:Multi-crystal silicon cells offer moderate efficiency at lower unit costs. Residential retrofits with less stringent area constraints specify these where budget sensitivity outweighs maximum output requirements.
- CIS:Copper indium selenide variants provide alternative thin-film chemistry with reduced gallium content. Niche applications in specialized architectural glass laminates exploit these for specific optical properties.
Monocrystalline commands installed capacity. CIGS gains share fastest in envelope-integrated segments.
Application:
Building typology determines scale economies, regulatory pathway, and interconnection complexity, with commercial assets offering the most standardized retrofit templates.
- Commercial Structures:Office buildings, retail centers, and hospitality assets generate dominant project value through portfolio-scale retrofits. Germany's federal building code amendments mandate renewable minimums for renovations exceeding floor area thresholds, compressing procurement timelines.
- Public Infrastructure:Government buildings, transit facilities, and municipal assets expand fastest as city-level renewable procurement targets tighten. Japanese municipal energy mandates create dedicated retrofit budgets for schools and administrative facilities.
- Industrial Facilities:Manufacturing plants and warehouses with large roof areas favor rack-mounted systems over envelope integration. Load-bearing assessments and waterproofing warranties complicate facade applications in this segment.
- Residential Buildings:Single-family and multi-family housing retrofits proceed through smaller-scale contractor networks. Homeowner decision-making centers on payback periods rather than envelope aesthetics or regulatory compliance.
Commercial Structures anchor revenue. Public Infrastructure offers steepest expansion trajectory.
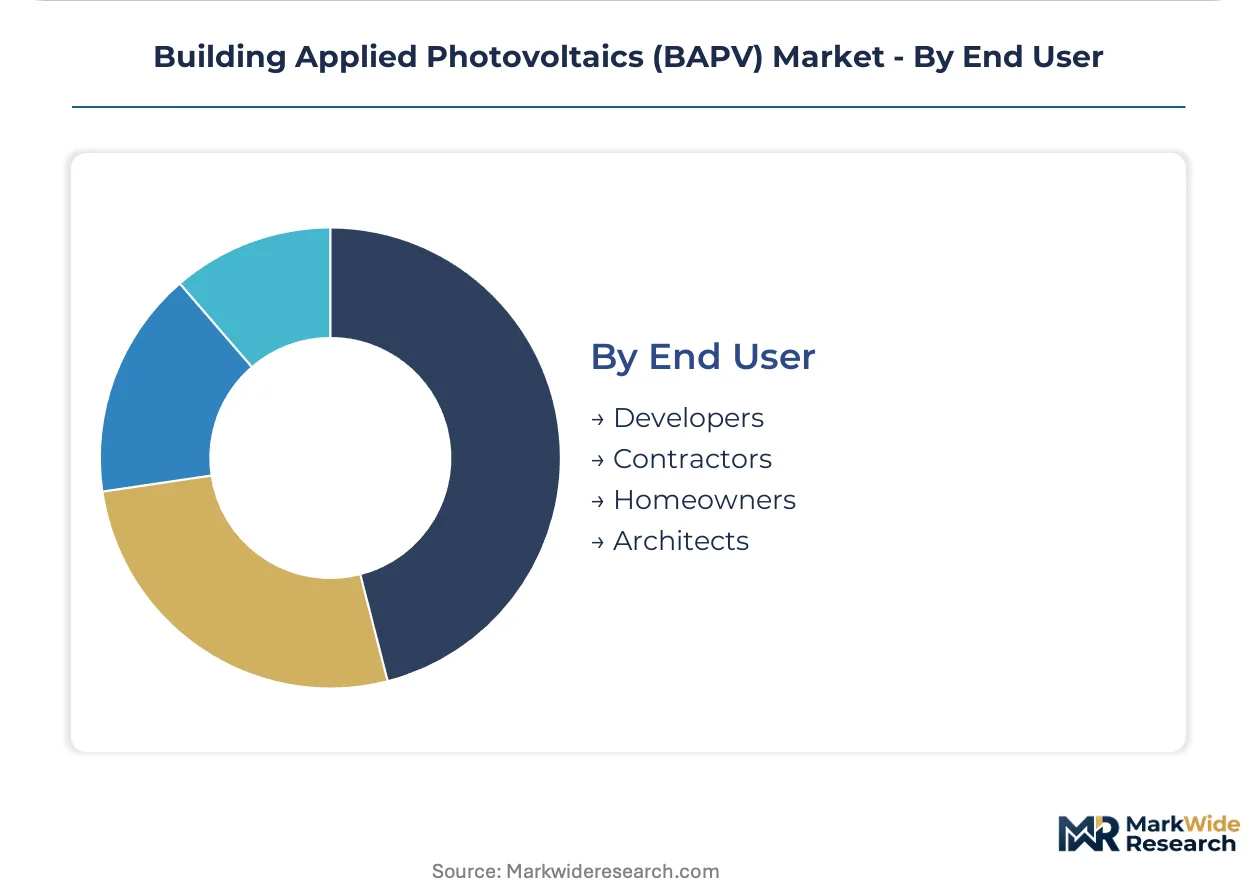
End User:
Procurement authority and technical capability vary dramatically across stakeholder types, determining whether projects advance through bundled EPC contracts or fragmented component sourcing.
- Developers:Commercial real estate investment trusts and property companies control capital allocation for portfolio-scale retrofits. These stakeholders negotiate master service agreements with module suppliers to secure volume pricing across multi-building programs.
- Architects:Design professionals specify envelope-integrated systems where aesthetic performance and planning compliance outweigh pure generation economics. Heritage-sensitive districts and high-visibility facades require their technical input on substrate compatibility and waterproofing integration.
- Contractors:Installation firms execute structural assessment, mounting system deployment, and electrical interconnection. Façade engineering skill scarcity among conventional solar installers extends project timelines and inflates soft costs.
- Homeowners:Individual residential decision-makers rely on regional installer networks for system design and permitting. Their procurement lacks the scale economies and technical sophistication of commercial counterparties.
Developers drive volume concentration. Architects determine specification winners in envelope-integrated segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Building Applied Photovoltaics technology first achieved commercial scale in Germany during the early 2000s, with facade-integrated systems pioneered by industrial engineering clusters along the Rhine-Ruhr corridor. From this European origin, deployment patterns now span three continents with distinct regulatory architectures and retrofit incentive structures.
Germany
Commercial real estate developers in Berlin, Hamburg, and Munich dominate Europe's largest BAPV retrofit pipeline. The federal building code amendments under the Energy Performance of Buildings Directive mandate renewable minimums for renovations exceeding floor area thresholds. The Rhine-Ruhr industrial corridor hosts engineering procurement construction firms that bundle module-racking-inverter packages for multi-building portfolio retrofits.
Japan
METI feed-in tariff adjustments have restructured compensation for building-mounted solar generation, improving project economics for commercial real estate owners in Tokyo, Osaka, and Nagoya. METI-certified installers in the Kanto region are consolidating into vertically integrated EPC roles to capture margin from hardware and installation labor. Municipal energy mandates create dedicated retrofit budgets for schools and administrative facilities across the Greater Tokyo Area.
United States
FERC net metering rules vary by state utility jurisdiction, with California, New York, and Massachusetts offering the most favorable interconnection standards for commercial envelope retrofits. Commercial real estate investment trusts in Manhattan, San Francisco, and Boston negotiate master service agreements with thin-film suppliers for multi-building portfolios. The Pacific Northwest and Northeast Corridor show fastest permit issuance timelines for facade-integrated systems.
China
Polysilicon supply concentration in Xinjiang and Sichuan manufacturing clusters creates upstream exposure for crystalline silicon module assemblers serving domestic retrofit demand. The Yangtze River Delta and Pearl River Delta contain the densest concentrations of curtain wall fabricators integrating photovoltaic glass into commercial building specifications. Dual carbon goals at the national level are filtering into provincial building energy codes across coastal manufacturing provinces.
Building Applied Photovoltaics (BAPV) Market Competitive Environment
Premium-margin players sit above commodity-margin players across architectural integration sophistication and envelope engineering capability. The vendor base separates into crystalline silicon specialists serving conventional retrofit volumes, thin-film developers capturing weight-constrained and curved-surface niches, and transparent glass innovators targeting high-visibility commercial zones. Three archetypes dominate: utility-scale retrofit portfolio anchors, facade-integrated envelope specialists, and flexible substrate innovators for heritage applications. Competitive moves concentrate on bundling hardware into single procurement SKUs and negotiating master service agreements for multi-building commercial portfolios.
Among thin-film and transparent glass specialists, First Solar, Onyx Solar Group LLC, and Heliatek GmbH occupy distinct positioning vectors. First Solar represents the utility-scale retrofit portfolio anchor archetype with cadmium telluride technology. Onyx Solar Group LLC exemplifies the transparent photovoltaic glass specialist tier targeting commercial lobby and atrium specifications. Heliatek GmbH anchors the flexible organic photovoltaic segment for curved architectural surfaces where rigid modules fail. These three firms illustrate how technology substrate choices determine addressable envelope geometries and planning compliance pathways.
| Leading Market Players |
|---|
| Onyx Solar Group LLC |
| First Solar |
| Heliatek GmbH |
| Centrosolar Group AG |
| OPVIUS |
| Ertex Solartechnik GmbH |
| Ascent Solar Technologies Inc |
| Sapa Solar |
| Sharp Solar |
| Others |
Value Chain & Pricing Dynamics
Commercial real estate investment trusts negotiating multi-building portfolio retrofits in Germany and Japan anchor pricing power toward bundled module-racking-inverter packages, compressing component-level margins and rewarding suppliers with captive manufacturing capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified envelope-integrated systems from conventional rack-mounted retrofits and commodity rooftop installations. Price differentiation hinges on CE marking compliance for EU tenders and METI certification for Japanese feed-in tariff eligibility, with premium tiers commanding structural engineering warranties. Cost compression in standard-tier crystalline silicon modules is intensifying because polysilicon supply volatility feeds through to fixed-price EPC contracts. Residential homeowners exhibit highest price sensitivity, while German commercial developers prioritize planning compliance and energy rating targets over unit economics.
Supply Chain Analysis
EU Green Deal local-content thresholds and Japan's METI-certified installer requirements are reshaping sourcing patterns toward domestic module assembly and regional racking fabrication. Polysilicon purification concentrates in Xinjiang and Sichuan manufacturing clusters, while aluminum extrusion for framing and structural mounting draws from Chinese and European smelters. Single-source vulnerability in purified silicon feedstock creates geopolitical exposure for non-integrated assemblers. Distribution runs through vertically integrated EPC contractors bundling hardware procurement with installation labor, displacing fragmented component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Building Applied Photovoltaics market functions as a regulatory compounder where EU Energy Performance of Buildings Directive mandates and Japan METI feed-in tariff structures mechanically expand retrofit demand regardless of underlying electricity price cycles.
For Market Incumbents: Hedge polysilicon supply exposure through backward integration into wafering capacity or long-term offtake agreements with Xinjiang and Sichuan producers. Capture margin compression from aluminum frame cost volatility by qualifying lightweight CIGS thin-film alternatives for weight-constrained heritage applications. For New Entrants and Emerging Players: Transparent photovoltaic glass for commercial lobby and atrium retrofits offers the most penetrable white-space segment, particularly in Germany's planning-restricted districts where opaque systems face rejection. Organic photovoltaic rolls for curved architectural surfaces unlock heritage building applications where rigid crystalline modules fail. Pursue architect-led specification capture through envelope engineering partnerships rather than installer channel competition. For Investors and Strategic Acquirers: Commercial real estate investment trusts with dedicated sustainability capital are the most active acquirer in this space, seeking captive EPC capabilities to control retrofit timelines and capture hardware margin. Target vertically integrated envelope specialists with in-house structural assessment and waterproofing expertise. Watch for municipal energy mandate acceleration in Japanese prefectures and German federal states as the inflection indicator for public infrastructure segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Supply | Mitigates Xinjiang concentration risk for crystalline silicon module assemblers serving EU tenders. |
| Envelope Engineering Certification Investment | CE marking and fire safety compliance filter non-qualified suppliers from German commercial retrofits. |
| Transparent PV Glass Product Line Launch | Captures German lobby and atrium specifications where planning restrictions prohibit opaque systems. |
| Master Service Agreement Negotiation | Locks volume pricing with Japanese METI-certified installers for multi-building commercial portfolios. |
| Organic Photovoltaic Substrate R&D Scale-Up | Heliatek GmbH and comparable developers target curved heritage surfaces where rigid modules fail. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with EPC contractors, facade engineers, commercial real estate developers, and regulatory affairs specialists at national building authorities with secondary validation against FERC filings, METI tariff schedules, EU Energy Performance of Buildings Directive transposition documents, and customs data on module imports. Bottom-up project pipeline tracking and top-down regulatory mandate sizing were triangulated to anchor volume estimates.
Segment-weighting approaches applied differential growth assumptions across technology types, building applications, and end-user procurement sophistication levels throughout the forecast period. The analytical framework modeled crystalline silicon versus thin-film substitution curves, commercial structure retrofit penetration rates, and public infrastructure mandate acceleration across regulatory jurisdictions. CAGRs were derived from installed capacity build-up trajectories and project value per square meter trends, with polysilicon supply availability and aluminum commodity pricing as key sensitivity inputs.
The model holds under continued EU Green Deal enforcement and Japan METI tariff stability; deviation in subsidy phase-out schedules or local-content rule tightening would shift supplier competitive positioning and regional demand distribution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Ground Mount PV Utility Market