
 Sandbags Market | 2026-2036
Sandbags Market Size, Share, and Industry Trends Forecast 2026-2036
Sandbags Market Analytics
Skilled textile-weaving labor availability in traditional manufacturing belts is unwinding as aging workforces retire without sufficient replacement pipelines. Cherokee Manufacturing leverages its vertical integration across fiber sourcing and bag stitching to maintain cost discipline. Palmetto Industries anchors its position through geographic dominance in southeastern US distribution corridors. HESCO Bastion Limited differentiates via technology leadership in rapid-deployment defensive barrier systems.
Sandbags are woven containers, typically constructed from jute, polypropylene, cotton, or burlap, designed to hold sand or soil at fill weights ranging from 50 kg to 200 kg for erosion control, flood mitigation, and military fortification. Polypropylene sandbags lead volume due to UV resistance and lower unit costs, while jute and burlap variants command premium positioning in environmentally regulated applications where biodegradability matters. Military applications represent the fastest-growing end-user channel as defense ministries replenish strategic reserves, whereas construction sites remain the mature, price-sensitive volume base.
The US Army Corps of Engineers sets fill-capacity and material-strength standards that shape procurement specifications for federal flood-control projects. EPA guidelines on stormwater runoff management indirectly drive demand for erosion-control deployments at commercial construction sites. OSHA workplace-safety rules govern handling protocols and lifting limits, influencing capacity preferences across industrial buyers. Stakeholders must monitor evolving defense-budget allocations and infrastructure-resilience legislation to anticipate procurement-cycle timing and specification shifts.
Market Dynamics
Defense ministries across NATO member states are accelerating strategic reserve replenishment cycles, compressing procurement timelines for rapid-deployment barrier systems while federal infrastructure mandates in the United States tighten material-strength specifications for flood-control applications.
Growth Catalysts
- US Army Corps of Engineers fill-capacity standards:Updated federal specifications for critical infrastructure projects mandate higher-performance materials, redirecting procurement toward certified suppliers capable of meeting elevated tensile-strength thresholds.
- Hurricane-season preparedness cycles:Gulf Coast state emergency management agencies maintain recurring bulk-order relationships with distributors, creating predictable demand windows for polypropylene and jute-woven containers.
- Polypropylene UV stabilization:Extended ultraviolet resistance in synthetic fiber formulations reduces replacement frequency for outdoor deployments, lowering total cost of ownership for military and municipal buyers.
Market Restraints
- Petroleum-based input volatility:Polypropylene resin prices fluctuate with crude oil derivatives, compressing margin stability for manufacturers without captive polymer sourcing.
- Skilled weaving labor scarcity:Traditional textile manufacturing belts in the southeastern United States face accelerating workforce attrition as aging operators retire without adequate apprenticeship pipelines.
- Jute supply concentration:Natural fiber sourcing depends on monsoon-dependent harvests in Bangladesh and India, exposing biodegradable product lines to weather-driven availability shocks.
Strategic Opportunities
- Biodegradable mandate expansion:EPA stormwater guidelines and state-level plastic restrictions in California and New York create preference windows for jute and burlap variants in environmentally sensitive watersheds.
- Modular barrier system integration:Convergence of geotextile engineering with collapsible wire-mesh frameworks enables rapid-deployment defensive configurations for expeditionary military units.
- Direct municipal procurement platforms:State emergency management agencies are bypassing distributor intermediaries through centralized digital procurement portals, shortening sales cycles for qualified vendors.
Industry Challenges
- OSHA material-handling compliance:Workplace safety rules governing lifting limits and repetitive-motion exposure require ergonomic redesign of fill-and-seal workflows at military depots and construction sites.
- ISO 9001 certification timelines:Defense procurement agencies increasingly require quality-management system accreditation, extending supplier qualification periods by 12-18 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandbags Market |
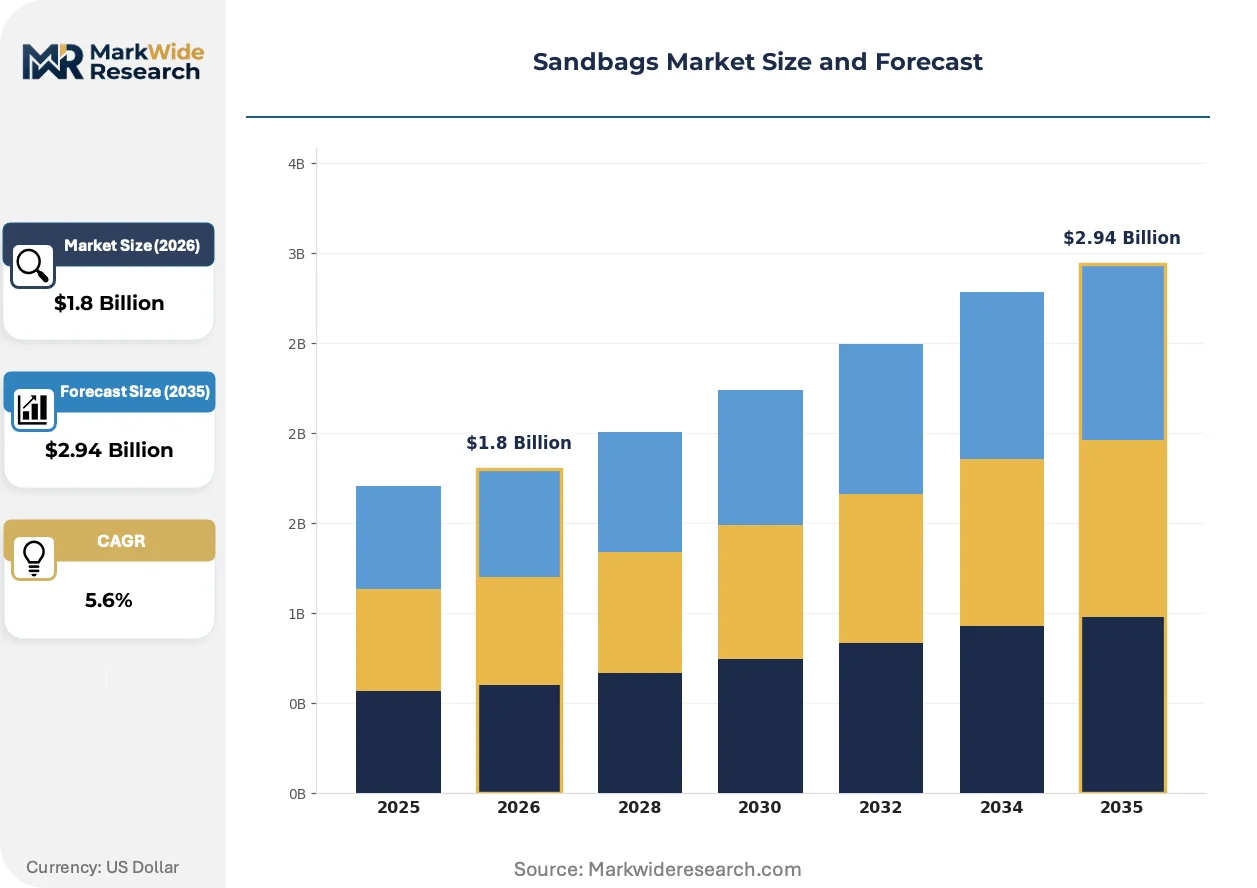
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jute Sandbags, Polypropylene Sandbags, Cotton Sandbags, Burlap Sandbags End User: Construction Sites, Military Applications, Flood Control, Emergency Services Capacity: 50 kg, 80 kg, 100 kg, 200 kg Manufacturing Stage: Raw Material Sourcing, Production, Quality Control, Distribution |
| Companies Covered | Sandbag Store LLC, LC Packaging UK Ltd, Cherokee Manufacturing, Palmetto Industries, One Ton Bag, Halsted Corporation, Lloyd Bag Company, HESCO Bastion Limited, Travis Perkins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandbags Market Evolving Landscape
Material science advances and procurement digitization are compressing traditional supply relationships while regulatory pressure on synthetic persistence opens positioning space for fiber alternatives.
Geotextile-reinforced sandbag composites are miniaturizing deployment logistics for military engineering units. The US Marine Corps Expeditionary Force has adopted collapsible barrier systems that reduce transport volume by two-thirds compared to conventional filled containers. This compression is miniaturizing forward-operating base construction timelines and reducing airlift dependency for rapid-response missions.
REACH restrictions on persistent organic pollutants in the European Union are tightening acceptable thresholds for synthetic fiber additives. Manufacturers serving NATO supply chains must reformulate UV stabilizers and colorants to maintain cross-border market access. German and French defense procurement agencies now require full material disclosure documentation, shifting competitive advantage toward suppliers with established chemical compliance infrastructure.
Bulk purchasing cooperatives among Gulf Coast county emergency management offices are consolidating previously fragmented municipal demand. Aggregated tender volumes now exceed single-source capacity for regional distributors, forcing qualification of secondary suppliers and compressing price negotiation cycles. Louisiana and Mississippi parish consortiums represent the most visible concentration of this procurement consolidation pattern.
Sandbags Market Segmentation
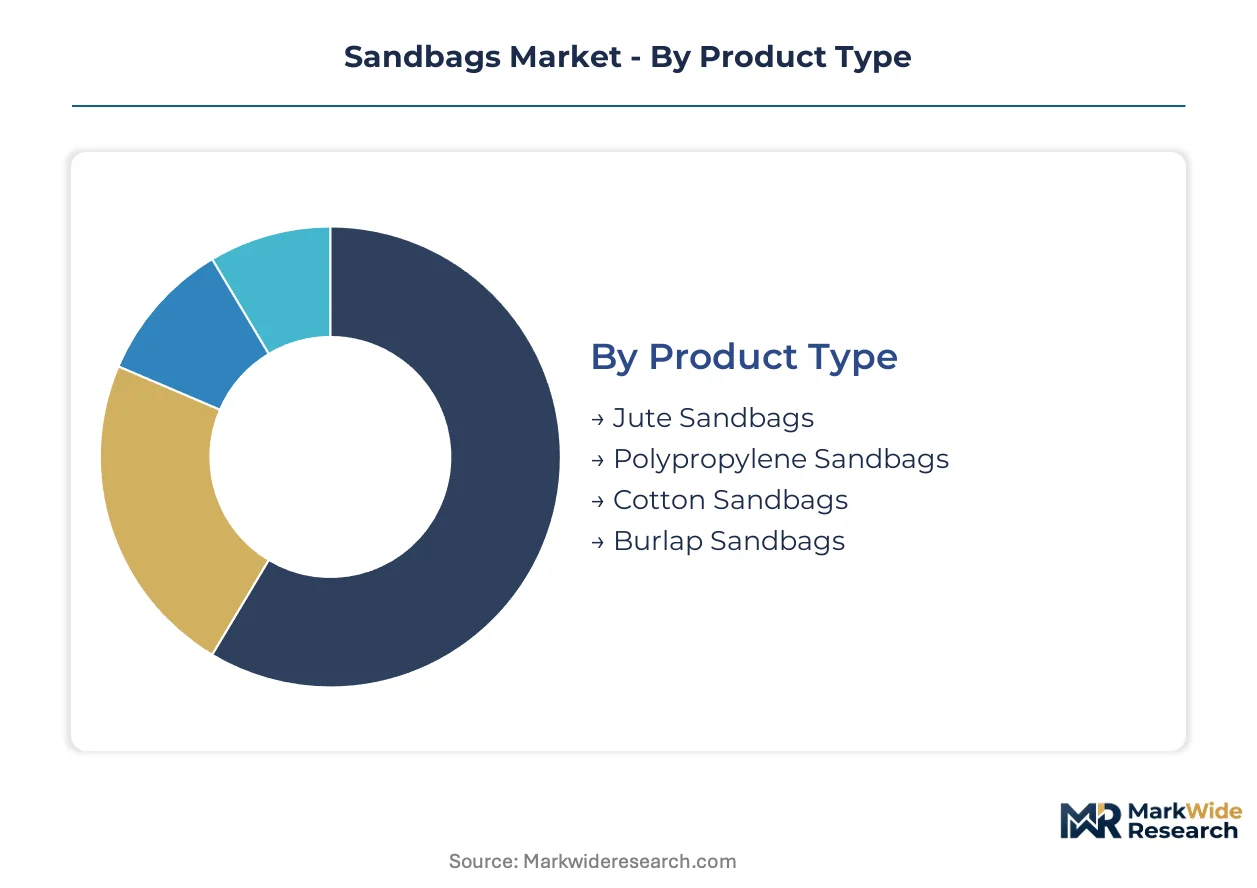
Sandbag procurement flows through distinct channel configurations depending on material composition, end-use criticality, and volume scale. Specification tiers separate military-grade certified supply from municipal emergency stockpiles and commercial construction spot-buying.
Product Type:
Channel-mix patterns diverge sharply across fiber categories. Polypropylene dominates distributor-led construction supply while jute and burlap flow through specialty environmental contractors. Military procurement channels maintain dual-source strategies across synthetic and natural fiber lines.
- Polypropylene Sandbags:Woven synthetic containers incorporate UV stabilizers for extended outdoor exposure. Demand concentrates in Gulf Coast hurricane preparedness programs and federal flood-control contracts where unit cost and durability outweigh biodegradability concerns.
- Jute Sandbags:Natural fiber construction provides soil-to-bag biodegradation within 12-24 months of deployment. EPA stormwater compliance in California and New York watersheds drives preference for jute variants in erosion-control applications near sensitive waterways.
- Cotton Sandbags:Short-staple woven construction offers intermediate biodegradation timelines between jute and synthetic alternatives. Heritage military specifications in select NATO depots sustain niche procurement volumes.
- Burlap Sandbags:Hessian weave construction delivers cost-competitive natural fiber performance for temporary flood diversion. Parish-level emergency management offices in Louisiana specify burlap for seasonal stockpiles with planned disposal cycles.
Polypropylene dominates installed base. Jute and burlap variants are where expansion concentrates as environmental regulations tighten.
End User:
Cost-tier segmentation separates price-sensitive volume buyers from specification-driven premium procurement. Construction sites optimize per-unit landed cost while military and emergency services prioritize performance certification and supply assurance.
- Military Applications:Rapid-deployment barrier systems require ISO 9001-certified manufacturing with full material traceability. Defense ministries across NATO member states are compressing procurement timelines for expeditionary engineering units.
- Flood Control:US Army Corps of Engineers specifications mandate elevated tensile-strength thresholds for critical infrastructure protection. Federal project approvals redirect procurement toward certified suppliers with documented quality-management systems.
- Construction Sites:Erosion-control deployments at commercial developments follow EPA stormwater runoff guidelines. OSHA material-handling rules govern lifting limits and repetitive-motion exposure on active job sites.
- Emergency Services:County-level emergency management agencies maintain recurring bulk-order relationships for hurricane-season readiness. Louisiana and Mississippi parish consortiums now aggregate demand through centralized digital procurement portals.
Flood control anchors volume throughput. Military applications are climbing the fastest as strategic reserve replenishment accelerates.
Capacity:
Volume-mix patterns reflect ergonomic constraints and deployment mechanization. Manual handling limits favor mid-weight specifications while mechanized military logistics accommodate heavier fill capacities.
- 50 kg:Single-operator lift capacity suits rapid manual deployment in emergency flood response. OSHA workplace-safety compliance drives preference for lighter specifications across municipal and construction buyers.
- 80 kg:Intermediate capacity balances fill efficiency with two-person handling protocols. Federal flood-control projects specify 80 kg as the standard unit for levee reinforcement and diversion channel construction.
- 100 kg:Mechanized placement enables higher fill density for permanent erosion-control installations. Commercial construction sites with equipment access specify 100 kg units for slope stabilization.
- 200 kg:Maximum capacity containers serve military defensive fortifications and critical infrastructure hardening. US Marine Corps Expeditionary Force logistics chains accommodate 200 kg units for forward-operating base construction.
80 kg specifications dominate federal procurement. 50 kg units are gaining share fastest as ergonomic compliance tightens across municipal buyers.
Manufacturing Stage:
Margin concentration varies across the value chain. Raw material sourcing and quality certification capture disproportionate returns while production and distribution face commoditization pressure.
- Raw Material Sourcing:Polypropylene resin procurement tracks petroleum derivative volatility. Jute fiber concentration in Bangladesh and India exposes supply to monsoon-dependent harvest variability.
- Production:Skilled textile-weaving labor scarcity in southeastern US manufacturing belts constrains capacity expansion. Cherokee Manufacturing maintains cost discipline through captive fiber sourcing and in-house bag stitching operations.
- Quality Control:ISO 9001 certification timelines extend supplier qualification periods by 12-18 months for defense procurement channels. Third-party testing documentation now accompanies all NATO-bound shipments.
- Distribution:Palmetto Industries anchors southeastern US corridor dominance through warehouse positioning near Gulf Coast demand clusters. Direct municipal procurement platforms are shortening sales cycles by bypassing distributor intermediaries.
Production and distribution dominate employment base. Quality control is where margin expansion concentrates as certification requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States federal procurement channels while European buyers extract compliance premiums for REACH-certified material disclosure. Gulf Coast emergency stockpiles and NATO defense replenishment cycles generate the dominant demand asymmetries.
United States
Federal flood-control contracts and Marine Corps expeditionary logistics drive procurement volume. US Army Corps of Engineers specifications mandate elevated tensile-strength thresholds that redirect orders toward certified suppliers. Louisiana and Mississippi parish consortiums aggregate county-level demand through centralized digital portals near New Orleans and Gulfport.
Germany
Bundeswehr strategic reserve replenishment and Rhine flood-management programs sustain industrial demand. ECHA REACH restrictions on persistent organic pollutants require reformulated UV stabilizers for NATO supply chain access. Manufacturing clusters in North Rhine-Westphalia coordinate chemical compliance documentation for cross-border defense procurement.
United Kingdom
Environment Agency flood resilience grants and Ministry of Defence barrier system contracts shape procurement patterns. EA specifications for temporary flood defense prioritize rapid-deployment logistics over unit cost minimization. Yorkshire and Humber estuary management authorities maintain pre-positioned stockpiles near Hull and Immingham.
India
Monsoon-dependent jute harvests in West Bengal and Bihar expose biodegradable product lines to weather-driven availability shocks. Bureau of Indian Standards certification for geotextile applications opens municipal infrastructure channels. Kolkata-based fiber processors coordinate export shipments to European environmental contractors.
Australia
Bureau of Meteorology seasonal flood outlooks trigger state emergency service pre-positioning orders along Queensland and New South Wales river systems. Infrastructure Australia resilience funding redirects toward certified erosion-control materials for transport corridor protection. Brisbane and Sydney metropolitan councils maintain cyclone-season stockpiles with 48-hour deployment protocols.
Sandbags Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with rapid-deployment barrier specialists commanding premium positioning against commodity woven-container fabricators. The vendor base separates into three tiers: defense-certified system integrators, vertically integrated regional manufacturers, and distributor-dependent spot suppliers. ISO 9001 accreditation and captive fiber sourcing represent the dominant competitive moves, compressing margins for non-certified entrants while extending qualification timelines.
Among southeastern US-based manufacturers, Cherokee Manufacturing exemplifies vertical integration across fiber sourcing and bag stitching operations. Palmetto Industries anchors geographic dominance through warehouse positioning near Gulf Coast demand clusters. HESCO Bastion Limited occupies the technology-specialist tier, representing rapid-deployment defensive barrier system leadership for NATO expeditionary units.
| Leading Market Players |
|---|
| Sandbag Store LLC |
| LC Packaging UK Ltd |
| Cherokee Manufacturing |
| Palmetto Industries |
| One Ton Bag |
| Halsted Corporation |
| Lloyd Bag Company |
| HESCO Bastion Limited |
| Travis Perkins |
| Others |
Value Network & Pricing Analysis
Polypropylene resin substitution for jute fiber simultaneously shifts supply geography toward Gulf Coast petrochemical corridors and compresses pricing economics for biodegradable alternatives. This input swap redirects procurement power toward synthetic fiber producers while elevating landed costs for natural fiber lines tethered to South Asian monsoon harvests.
Pricing Analysis
The customization-premium spread between ISO 9001-certified military-grade containers and standard municipal flood-control units reaches its widest point during hurricane-season procurement windows. Three-tier pricing structure across certified defense, federal infrastructure, and spot-buy construction tiers reflects quality-grade differentiation and volume-scale thresholds. Pricing pressure stems from petroleum-based input volatility eroding margin stability at polypropylene-dependent fabricators. Municipal emergency services exhibit highest price sensitivity, while NATO defense procurement channels prioritize performance certification over unit cost minimization.
Supply Chain Analysis
Inventory cycles compress to 48-hour deployment protocols for Gulf Coast parish consortiums while lead times extend to 12-18 months for ISO 9001 certification-dependent military contracts. Geographic supply concentration centers on Bangladesh and India for jute fiber, the United States Gulf Coast for polypropylene resin, and southeastern US manufacturing belts for woven container production. Raw material dependencies rest on crude oil derivatives, monsoon-dependent natural fiber harvests, and UV stabilizer chemical formulations. Single-source vulnerability concentrates in Bangladeshi jute processing capacity. Distribution runs through direct municipal procurement portals and defense-certified supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where ISO 9001 certification entrenchment creates switching costs that freeze out non-accredited competitors. Defense procurement timelines and federal flood-control specifications embed incumbent advantages through extended qualification periods.
For Market Incumbents: Shield certified supplier status by accelerating captive fiber sourcing investments before petroleum volatility destabilizes margin structures. Expand quality-control documentation infrastructure to satisfy German and French defense agencies' REACH-compliant material disclosure requirements. Consolidate southeastern US weaving capacity as skilled labor attrition accelerates.
For New Entrants and Emerging Players: ISO 9001 fast-track partnerships with established textile certification bodies unlock defense channel access within compressed timelines. Target Louisiana and Mississippi parish consortiums through centralized digital procurement portals as the most penetrable municipal segment. Pursue biodegradable mandate expansion in California and New York watersheds as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive fiber sourcing and in-house quality certification infrastructure. Long-term viability hinges on backward integration depth and geographic positioning near Gulf Coast demand clusters. Watch for EPA stormwater guideline expansion as the inflection signal accelerating biodegradable product line premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Certification Investment | Defense procurement channels require quality-management accreditation for NATO supply chain access. |
| Captive Fiber Sourcing Integration | Backward integration into polypropylene resin procurement insulates margin stability from petroleum volatility. |
| Direct Municipal Procurement Platform Entry | Louisiana and Mississippi parish consortiums bypass distributor intermediaries through centralized digital portals. |
| Biodegradable Product Line Expansion | EPA stormwater guidelines and state-level plastic restrictions create preference windows for jute and burlap variants. |
| Geographic Warehouse Positioning | Proximity to Gulf Coast hurricane preparedness demand clusters reduces logistics lead times for emergency stockpiles. |
Research Methodology
The analysis maps polypropylene sandbag, jute sandbag, cotton sandbag, and burlap sandbag sub-sectors, each validated through plant managers at woven container manufacturers, procurement leads at federal flood-control contractors, distribution channel partners in southeastern US corridors, and technical R&D directors at geotextile engineering firms. Primary interview insights triangulate against customs and trade data, US Army Corps of Engineers procurement filings, EPA stormwater guideline documentation, and SEC 10-K disclosures from publicly traded textile manufacturers. Bottom-up demand modeling and top-down supply capacity assessments cross-validate segment outputs.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, end-use application, fill capacity tier, and geographic procurement cluster dimensions. CAGRs derive from segment-level demand growth trajectories and supply capacity expansion rates. Forecast inputs incorporate defense budget allocation patterns, infrastructure resilience legislation timing, and monsoon-dependent jute harvest variability.
Underlying assumptions cover stable petroleum derivative pricing, continued ISO 9001 certification requirements for defense procurement, and EPA guideline enforcement trajectories, with deviation risk concentrated in crude oil volatility and South Asian weather shocks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Italy Feed Additives Market
Others
Mobile Social Networks Market
Others
Global Platform Trolley Market
Others
Chip Card Scanners Market
Others
Prunes Market
Others
Global Recruitment and Staffing Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Solar Panel Testers Market
Others
Global Supply Chain Risk Management Software Market
Others
Air Separation Plant Market
Others
Brazil Cane Sugar Market
Others
Stand-Up Pouch Valves Market
Others
Retail Media Platform Market
Others
Aircraft Lighting Market
Others
Android STB and TV Market
Others
Global Animal Feed Protein Ingredients Market