
 Trusted Platform Module (TPM) Market | 2026-2036
Trusted Platform Module (TPM) Market Size, Share, and Industry Trends Forecast 2026-2036
Trusted Platform Module (TPM) Market Analytics
Taiwanese foundry capacity for secure microcontrollers is rebalancing toward automotive-grade certifications. Infineon Technologies AG leverages its Munich fabrication network to sustain high-assurance supply lines for European OEMs. NXP Semiconductors anchors North American automotive TPM demand through its dedicated secure connectivity division. STMicroelectronics competes on cost-optimized discrete TPM variants for mid-volume IoT deployments.
A Trusted Platform Module is a hardware security coprocessor that stores cryptographic keys, platform measurements, and integrity credentials in tamper-resistant silicon, typically implementing the ISO/IEC 11889 standard specification. Its primary commercial purpose is to establish a hardware root of trust for endpoint authentication, secure boot sequences, and encrypted storage across computing devices. Discrete TPM modules command premium positioning in enterprise and government procurement channels where physical tamper evidence satisfies FIPS 140-2 validation requirements. Embedded TPM integration within system-on-chip architectures captures the fastest expansion trajectory as mobile and IoT device manufacturers prioritize board-space efficiency. Firmware TPM implementations face margin compression from open-source alternatives, yet sustain relevance in consumer electronics where cost floors dominate supplier selection.
The EU Cybersecurity Act and GDPR data-protection mandates compel hardware-backed encryption in devices processing personal data across member states. NIST SP 800-193 platform firmware resilience guidelines in the United States shape federal procurement specifications for supply-chain integrity. China's GB standards for commercial cryptography require domestic certification through the national cryptographic regulator for TPM products deployed in government and financial infrastructure. Stakeholders must monitor divergence between regional certification regimes when architecting unified product platforms for multinational deployment.
Market Dynamics
Enterprise IT infrastructure refresh cycles are compressing replacement timelines for legacy hardware, forcing simultaneous upgrades to security subsystems as organizations migrate toward zero-trust architectures. Cloud data center operators now specify root-of-trust components in procurement tenders, embedding TPM requirements upstream of device selection.
Growth Catalysts
- EU Cybersecurity Act mandates:Common Criteria certification requirements for hardware security modules sold across member states are pulling discrete TPM volumes into compliance-driven replacement cycles.
- Industrial automation corridors:Germany's Industry 4.0 deployments require hardware root-of-trust components for machine-to-machine authentication and firmware integrity verification.
- Automotive-grade secure microcontrollers:Taiwanese foundry capacity rebalancing toward AEC-Q100 certifications is expanding supply availability for connected vehicle platforms.
Market Restraints
- Silicon supply concentration:Secure microcontroller fabrication remains concentrated among three foundry groups, creating single-source vulnerability for fabless TPM designers.
- Certification timeline friction:FIPS 140-2 validation cycles extend 18-24 months, delaying product launches and freezing design iterations mid-process.
- Firmware TPM substitution:Open-source firmware implementations embedded in CPU microcode threaten pricing power at the consumer electronics tier.
Strategic Opportunities
- IoT edge device penetration:Mid-volume industrial sensor networks remain underpenetrated by hardware root-of-trust solutions, presenting greenfield deployment potential.
- China's GB cryptography standards:Domestic certification requirements for government and financial infrastructure create protected market space for locally certified suppliers.
- Post-quantum cryptography convergence:Lattice-based algorithm integration with existing TPM architectures offers differentiation ahead of NIST standardization completion.
Industry Challenges
- Cryptographic engineering talent scarcity:Specialized firmware developers capable of side-channel-resistant implementations command premium compensation and extended recruitment timelines.
- Multi-jurisdiction certification stacking:Products requiring simultaneous Common Criteria, FIPS, and domestic Chinese approvals face redundant evaluation costs and divergent technical interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trusted Platform Module (TPM) Market |
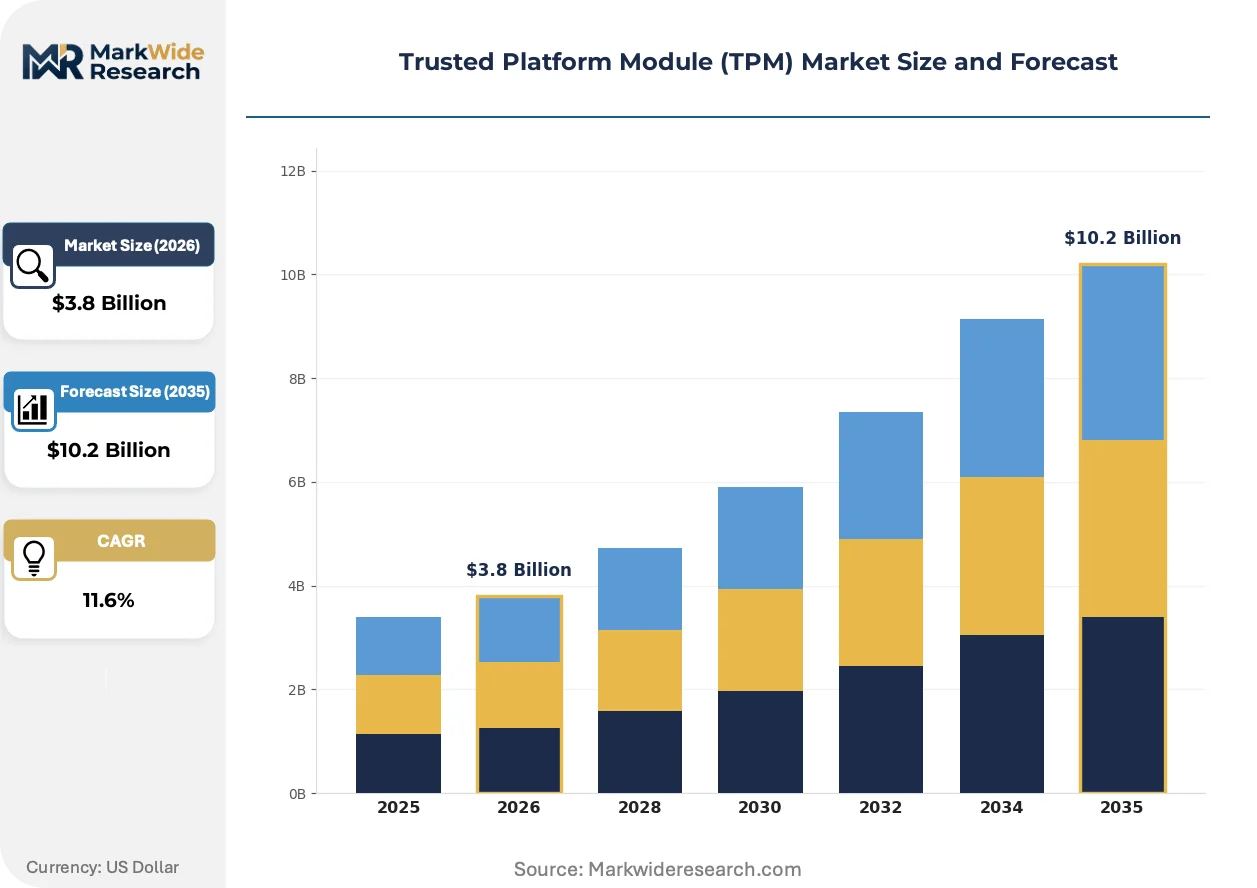
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete TPM, Embedded TPM, Firmware TPM, Software TPM Technology: Biometric Authentication, Encryption, Digital Signatures, Secure Boot Use Case: Data Protection, Network Security, Device Authentication, Payment Processing End User: Government, Healthcare, Financial Services, Education |
| Companies Covered | NXP Semiconductors, Nationz Technologies, Infineon Technologies AG, Texas Instruments, Intel Corporation, STMicroelectronics, Microchip Technology, Analog Devices, Nuvoton Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trusted Platform Module (TPM) Market Evolving Landscape
Hardware security architectures are fragmenting across integration levels as device manufacturers optimize for divergent cost, space, and assurance requirements. Three distinct technical trajectories now compete for design wins across end-use verticals.
Discrete TPM modules implementing ISO/IEC 11889 in standalone packages maintain dominance in enterprise and government procurement channels where physical tamper evidence satisfies high-assurance requirements. Server OEMs and federal integrators specify these components for secure boot and measured launch environments. The technology is expanding into cloud infrastructure edge nodes as operators extend hardware trust boundaries beyond central data halls.
NIST SP 800-193 platform firmware resilience guidelines in the United States are reshaping federal procurement specifications toward supply-chain integrity verification. Defense and civilian agencies now mandate firmware measurement and recovery capabilities in endpoint devices. Federal systems integrators are requalifying supplier bases to meet these requirements, compressing vendor selection timelines.
Certificate-driven procurement preferences are displacing specification-sheet comparison in European enterprise purchasing. Buyers now weight Common Criteria evaluation assurance levels above raw cryptographic performance metrics. German automotive and industrial OEMs have institutionalized this shift through supplier quality audits that privilege certified components.
Trusted Platform Module (TPM) Market Segmentation
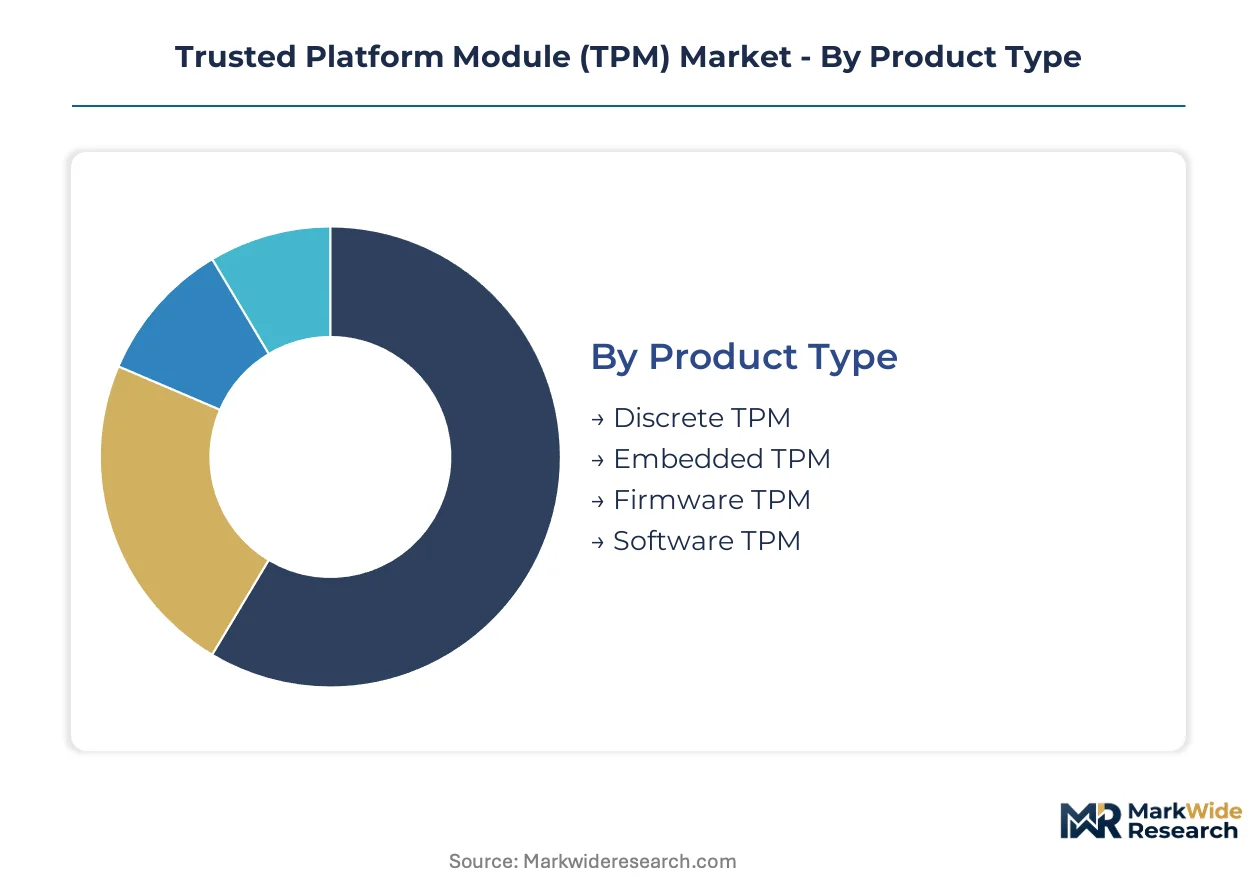
TPM architectures fragment across integration levels as device manufacturers balance assurance requirements against board-space constraints and unit economics. Procurement specifications diverge sharply between federal integrators demanding physical tamper evidence and consumer electronics OEMs prioritizing cost floors.
Product Type:
Secure microcontroller fabrication concentrates among three foundry groups, forcing product-type selection to hinge on supply security as much as technical specification.
- Discrete TPM:Standalone packages implementing ISO/IEC 11889 in dedicated silicon with physical tamper-evident packaging. Enterprise server procurement in Germany and U.S. federal channels specifies these components for FIPS 140-2 validation compliance, though 18-24 month certification cycles delay product launches.
- Embedded TPM:Integration within system-on-chip architectures eliminates discrete component count while preserving hardware root-of-trust functionality. Mobile and IoT device manufacturers in Taiwan and South Korea specify these for board-space efficiency, with automotive-grade AEC-Q100 certifications expanding supply availability.
- Firmware TPM:CPU microcode implementations without dedicated secure silicon. Consumer electronics OEMs specify these where cost floors dominate supplier selection, though open-source alternatives compress margins.
- Software TPM:Pure software emulation without hardware-backed key protection. Limited to development environments and legacy system compatibility layers where assurance requirements are minimal.
Today's leader: Discrete TPM. Tomorrow's challenger: Embedded TPM.
Technology:
Cost tiers separate premium cryptographic implementations from commoditized baseline functions.
- Biometric Authentication:Fingerprint and facial template matching with TPM-secured key derivation. Healthcare device manufacturers specify these for HIPAA-compliant workstation access in U.S. hospital networks.
- Encryption:AES and RSA hardware acceleration with side-channel-resistant implementations. Financial services infrastructure in Frankfurt and Singapore requires these for PCI-DSS compliance in payment terminals.
- Digital Signatures:ECDSA and RSA signature generation with protected private key storage. Government document signing systems specify these for non-repudiation in EU member state deployments.
- Secure Boot:Measured boot sequence verification with platform configuration register chaining. Industrial automation OEMs in Germany's Industry 4.0 corridor mandate these for firmware integrity verification.
Encryption commands current procurement volumes. Biometric Authentication climbs fastest as healthcare and financial endpoints converge.
Use Case:
Application-specific requirements drive divergent certification and performance specifications.
- Data Protection:Full-disk and file-level encryption with TPM-sealed keys. GDPR-mandated hardware-backed encryption for personal data processing drives specification across EU enterprise procurement.
- Network Security:VPN endpoint authentication and TLS certificate protection. Remote workforce infrastructure expansion in U.S. and German enterprises specifies these for zero-trust architecture compliance.
- Device Authentication:Platform attestation and identity credential binding. IoT sensor networks in industrial deployments require these for machine-to-machine trust establishment.
- Payment Processing:EMV and PCI-PTS compliant secure transaction processing. Point-of-sale terminal manufacturers specify these for regulatory compliance in retail and hospitality.
Data Protection anchors current demand. Network Security expands most quickly as distributed workforce models persist.
End User:
Customer-type segmentation reveals stark divergence in procurement sophistication and certification tolerance.
- Government:Federal and defense procurement with Common Criteria and FIPS 140-2 mandates. U.S. defense integrators and EU civilian agencies specify high-assurance discrete TPMs with extended validation cycles.
- Healthcare:HIPAA-regulated patient data protection with workstation and medical device security. U.S. hospital networks and EU health authorities drive demand for biometric-enabled authentication.
- Financial Services:PCI-DSS and banking regulator compliance for transaction security. Frankfurt and Singapore financial centers specify encryption-focused implementations for payment infrastructure.
- Education:Campus-wide device management and student data protection. K-12 and university procurement favors cost-optimized firmware implementations over hardware-backed alternatives.
Government procurement sets the assurance ceiling. Financial Services scales fastest as digital payment infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing TPM fabrication capacity toward jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between Common Criteria regimes and domestic Chinese approval processes are accelerating geographic specialization in secure microcontroller supply chains.
United States
Federal procurement mandates under NIST SP 800-193 are reshaping demand specifications for defense and civilian agencies. The Department of Defense and civilian integrators require FIPS 140-2 validated discrete TPMs with extended validation cycles. Silicon Valley and Austin technology corridors concentrate firmware development for cloud infrastructure edge nodes.
Germany
Industry 4.0 deployments across Bavaria and Baden-Württemberg mandate hardware root-of-trust components for machine-to-machine authentication. The EU Cybersecurity Act pulls discrete TPM volumes into compliance-driven replacement cycles through Common Criteria certification requirements. Munich anchors Infineon's fabrication network serving European OEMs with high-assurance supply lines.
China
GB standards for commercial cryptography require domestic certification through the national cryptographic regulator for government and financial infrastructure. Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate locally certified TPM production for protected market segments. Nationz Technologies exemplifies suppliers occupying this certification-mandated tier.
Taiwan
Foundry capacity rebalancing toward AEC-Q100 automotive-grade certifications is expanding supply availability for connected vehicle platforms. TSMC and UMC fabrication networks serve fabless TPM designers concentrated in Hsinchu Science Park. This capacity shift addresses silicon supply concentration risks among legacy secure microcontroller sources.
South Korea
Seoul Capital Area electronics OEMs specify embedded TPM integration within system-on-chip architectures for board-space efficiency. Samsung and SK hynix semiconductor ecosystems prioritize mobile and IoT device manufacturer requirements. Domestic demand concentrates on cost-optimized variants where certification tolerance permits firmware alternatives.
Trusted Platform Module (TPM) Market Competitive Landscape
European producers anchor the high-assurance tier; Asian specialists hold scale-driven embedded integration positions. The vendor base concentrates around three fabrication networks, creating structural interdependence between fabless designers and foundry capacity. Strategic archetypes include discrete TPM purists serving federal procurement, embedded integrators capturing mobile and automotive volume, and firmware implementers competing on cost floors. Dominant competitive moves center on certification stacking for multi-jurisdiction approval and foundry partnership securing for automotive-grade capacity allocation.
Among European-based fabricators, Infineon Technologies AG and STMicroelectronics exemplify the high-assurance archetype serving Common Criteria and FIPS 140-2 procurement channels. NXP Semiconductors anchors North American automotive TPM demand through secure connectivity specialization. These three entities represent distinct geographic anchoring strategies—German fabrication network proximity to EU regulatory bodies, Franco-Italian cost-optimization for mid-volume IoT, and Dutch-American transatlantic positioning for automotive OEM relationships.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Nationz Technologies |
| Infineon Technologies AG |
| Texas Instruments |
| Intel Corporation |
| STMicroelectronics |
| Microchip Technology |
| Analog Devices |
| Nuvoton Technology Corporation |
| Others |
Value Network & Pricing Analysis
Silicon wafer spot pricing volatility cascades through secure microcontroller fabrication into three distinct procurement tiers, compressing margins for fabless designers while amplifying pricing power for integrated foundry operators serving Common Criteria certification channels.
Pricing Analysis
Distributor markups of 15-25 percentage points separate volume direct-to-OEM contracts from spot procurement through authorized resellers. Pricing stratifies across FIPS 140-2 validated premium tiers, automotive-grade AEC-Q100 mid-tiers, and consumer firmware economy tiers. Cost compression in the economy tier intensifies because CPU vendors bundle firmware TPM at marginal cost. Federal integrators exhibit least price sensitivity; education procurement shows highest elasticity.
Supply Chain Analysis
Common Criteria and FIPS 140-2 qualification gating restricts qualified fabrication to Taiwan, Germany, and the United States. Secure microcontroller production draws from silicon wafers, AEC-Q100 certified packaging substrates, and side-channel-resistant IP libraries. Single-source vulnerability concentrates in Taiwanese foundry capacity for automotive-grade secure elements. Distribution runs through authorized distributors serving federal procurement channels and direct OEM contracts for high-volume mobile integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Trusted Platform Module market functions as a geographic-arbitrage play where EU Cybersecurity Act compliance costs in member states run 40 percentage points above China's GB certification pathway, creating divergent margin structures for multi-jurisdiction suppliers.
For Market Incumbents: To counter firmware TPM substitution from Intel and AMD CPU microcode integration, discrete TPM purists must deepen backward integration into secure microcontroller fabrication and accelerate post-quantum cryptography IP development ahead of NIST standardization. Foundry partnership securing for automotive-grade capacity allocation represents the critical defensive lever.
For New Entrants and Emerging Players: China's GB standards for commercial cryptography in government and financial infrastructure opens a window for locally certified suppliers to capture protected domestic market share. White-space targets include industrial IoT sensor networks in Germany's Industry 4.0 corridor and healthcare biometric authentication endpoints in U.S. hospital networks. A certification-first go-to-market angle bypasses incumbent brand advantages.
For Investors and Strategic Acquirers: Asymmetric upside sits with fabless designers holding automotive-grade AEC-Q100 qualifications and pending Common Criteria evaluations. Long-term viability hinges on certification stacking capabilities across three or more regulatory regimes. Watch NIST post-quantum standardization completion as the signal for architecture refresh cycles and replacement demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Integration | Lattice-based algorithm deployment ahead of NIST standardization captures federal procurement preference. |
| Automotive-Grade Certification Expansion | AEC-Q100 qualification opens connected vehicle platform supply to Tier 1 automotive suppliers. |
| Multi-Jurisdiction Certification Stacking | Simultaneous Common Criteria, FIPS 140-2, and GB approval enables unified product platforms for multinational OEMs. |
| Foundry Partnership Securing | Long-term capacity agreements with TSMC or UMC reduce single-source vulnerability for fabless designers. |
| Firmware TPM Differentiation | Side-channel-resistant implementations in CPU microcode preserve relevance against open-source alternatives. |
Research Methodology
Bottom-up enterprise IT procurement modeling reconciled against top-down secure microcontroller fabrication tracking forms the analytical core. Primary interviews with federal systems integrators, automotive platform engineers, cloud infrastructure procurement officers, and semiconductor supply chain managers combined with secondary validation against NIST SP 800-193 implementation guidance, EU Cybersecurity Act regulatory filings, and foundry capacity disclosures. Triangulation across these sources yields volume estimates segmented by integration level, certification tier, and end-use vertical.
Historical trendline analysis of discrete TPM, embedded TPM, and firmware TPM shipment patterns established baseline growth trajectories across the projection horizon. The analytical framework models product type, technology tier, use case application, and end-user industry dimensions. CAGRs derive from regression analysis against IT infrastructure refresh cycle timing, regulatory mandate effective dates, and automotive platform design win conversion rates. Forecast inputs include cloud data center capex trajectories and Industry 4.0 deployment schedules.
Revisions become necessary when NIST post-quantum standardization timelines shift, foundry capacity allocation prioritizes alternative semiconductor categories, or EU-China regulatory divergence widens certification cost gaps. A model refresh is warranted upon material change in federal procurement specification timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
8K Technology Market
Others
Canada 3D Printing Construction Market
Others
Pet Care Packaging Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Agitation System Market
Others
Global Hair Loss Treatment Products Market
Others
Industrial Air Pollution Control Solutions Market
Others
Cat Food and Snacks Market
Others
Profilometer Market
Others
UK Cat Food Market
Others
Fluorapatite Market
Others
Nutricosmetics Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Bio-Imaging Technologies Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
United States Cigarette Market