
 Iran Renewable Energy Market | 2026-2036
Iran Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Renewable Energy Market Foresight
Industrial off-takers is redrawing procurement patterns across Iran's renewable energy landscape as power-intensive manufacturers seek cost hedging against fossil fuel volatility. Mapna Group leverages its domestic turbine manufacturing base to anchor wind project development in northwestern provinces. SATBA competes for developer mindshare through feed-in tariff administration and grid access prioritization. TAVANIR sustains transmission infrastructure expansion to accommodate variable renewable injection.
Iran renewable energy encompasses electricity generation systems converting solar irradiance, wind kinetic energy, biomass combustion, and hydropower potential into grid-deliverable power, with photovoltaic modules typically rated at 300-550 Wp under standard test conditions and wind turbines scaled from 1.5 MW onshore units to multi-megawatt installations. Solar technology leads installed capacity additions due to Iran's 2800+ annual sunshine hours and declining module import costs. The application dimension tilts toward industrial consumers seeking behind-the-meter generation to offset natural gas dependency. Installation type concentration favors on-grid configurations where TAVANIR interconnection protocols permit, though off-grid hybrid systems gain traction in remote southeastern provinces lacking transmission reach.
SATBA administers renewable energy purchase guarantees while the Ministry of Energy enforces grid code compliance for generator interconnection, collectively shaping project bankability and technology selection criteria. Iran's national development plans embed renewable capacity targets that steer state-backed financing toward utility-scale solar and wind proposals. Stakeholders must monitor feed-in tariff adjustment frequency and foreign equipment sourcing restrictions that determine project returns and technology supply chain configuration.
Market Dynamics
SATBA's feed-in tariff recalibration is compressing developer returns while simultaneously accelerating utility-scale solar deployment in Tehran's corridor, forcing project sponsors to renegotiate equipment sourcing and debt tenors.
Growth Catalysts
- Solar Irradiance Endowment:Iran's 2800+ annual sunshine hours create generation economics that undercut fossil-fuel alternatives for industrial off-takers seeking behind-the-meter supply security.
- Feed-in Tariff Administration:SATBA's purchase guarantee mechanism provides revenue certainty that attracts domestic banking syndicates to utility-scale project finance.
- Steel and Cement Manufacturing:Power-intensive industrial clusters in Isfahan and Khuzestan are contracting solar arrays to hedge natural gas price volatility and grid instability.
Market Restraints
- Foreign Module Sourcing Restrictions:Import licensing protocols for photovoltaic panels constrain supply availability and extend project commissioning timelines.
- Transmission Bottlenecks:TAVANIR's grid interconnection queue delays in northwestern wind zones strand Mapna Group turbine capacity behind inadequate substation infrastructure.
- Dual-Fuel Generator Substitution:Industrial facilities retain diesel and heavy fuel oil backup systems that undercut renewable energy offtake commitments during grid emergencies.
Strategic Opportunities
- Southeastern Off-Grid Hybrid Systems:Remote provinces lacking transmission reach present first-mover potential for solar-plus-storage configurations serving agricultural processing loads.
- Biogas Agricultural Residue Conversion:Livestock and dairy operations in Mazandaran and Gilan generate feedstock for distributed generation units qualifying under SATBA's biomass tariff tier.
- Domestic Turbine Component Manufacturing:Mapna Group's supply chain localization creates captive sourcing advantages for wind project developers facing hard currency constraints.
Industry Challenges
- Grid Code Compliance Expertise:The Ministry of Energy's interconnection standards require specialized power systems engineering talent that remains concentrated in Tehran consulting firms.
- Foreign Equipment Financing:Project sponsors face letter-of-credit complications when sourcing inverters and tracking systems from East Asian suppliers under sanctions protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Renewable Energy Market |
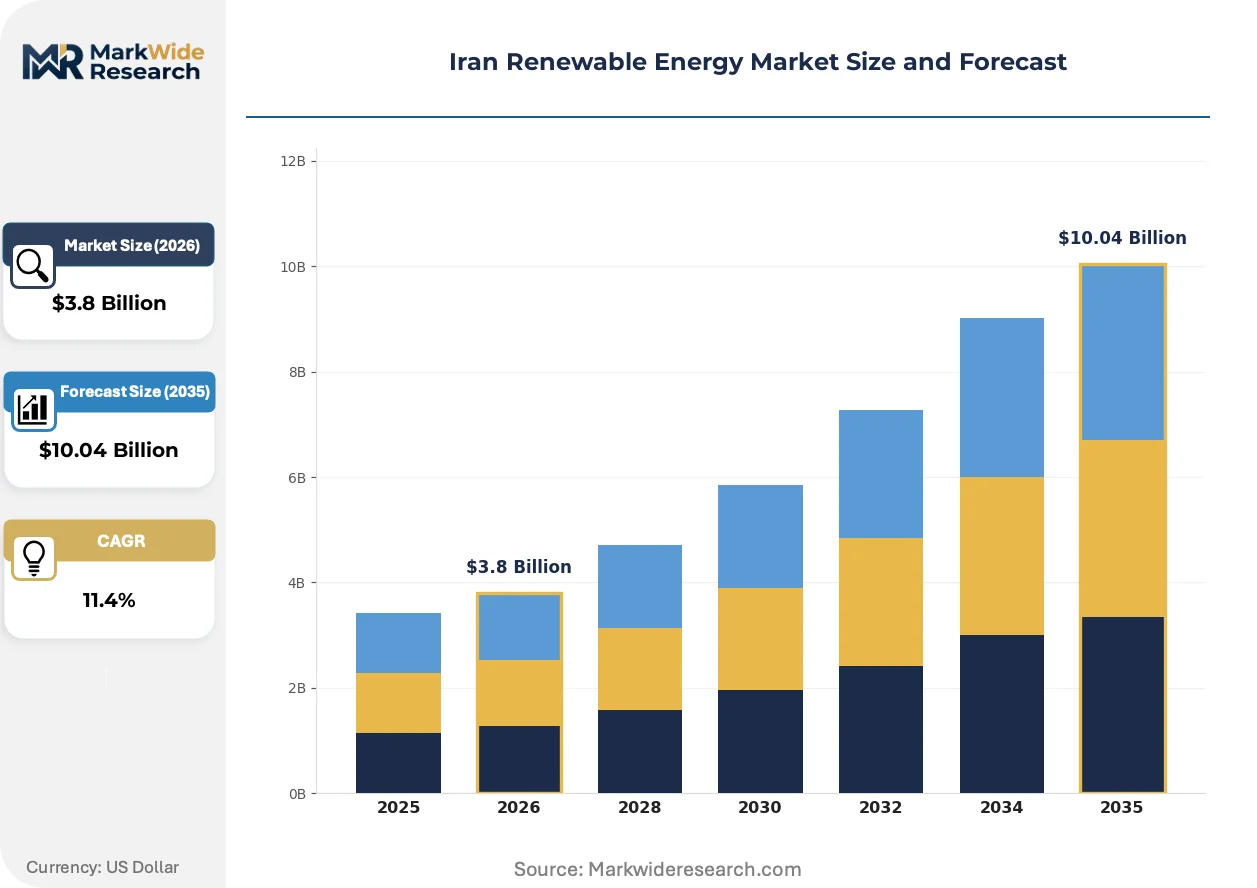
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower Application: Residential, Commercial, Industrial, Agricultural End User: Utilities, Developers, Government, Corporations Installation Type: On-grid, Off-grid, Hybrid, Community |
| Companies Covered | Rapano Energy, Behnotech Eng., Iran Renewable Energy Association, Sheedsun Co., ArtinA Renewable Energy, SUNA, TAVANIR, SATBA, Mapna Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Renewable Energy Market Shifts & Advancements
Technology convergence and procurement model evolution are reconfiguring how Iranian renewable energy projects secure equipment, structure revenue, and interconnect with TAVANIR's transmission network.
Bifacial photovoltaic modules are supplanting monofacial panels in utility-scale tenders across Tehran and Yazd provinces. Industrial off-takers with available land are specifying double-glass construction to capture albedo gains from desert terrain. This technology shift is compressing levelized cost thresholds and enabling developers to bid more aggressively into SATBA's competitive procurement rounds.
SATBA's tariff band restructuring is forcing project sponsors to optimize generation profiles around time-of-day pricing differentials. The revised framework rewards midday peak production with premium rates while penalizing overnight injection. Developers are responding by oversizing DC arrays relative to AC interconnection capacity to maximize capture of high-value irradiance hours.
Industrial consumers are consolidating renewable energy procurement through direct power purchase agreements rather than relying on utility-mediated supply. Steel and cement manufacturers in Isfahan are negotiating bilateral contracts with solar developers for dedicated behind-the-meter capacity. This behavioral shift is most visible in central Iranian manufacturing zones where grid reliability concerns compound fossil fuel price exposure.
Iran Renewable Energy Market Segmentation
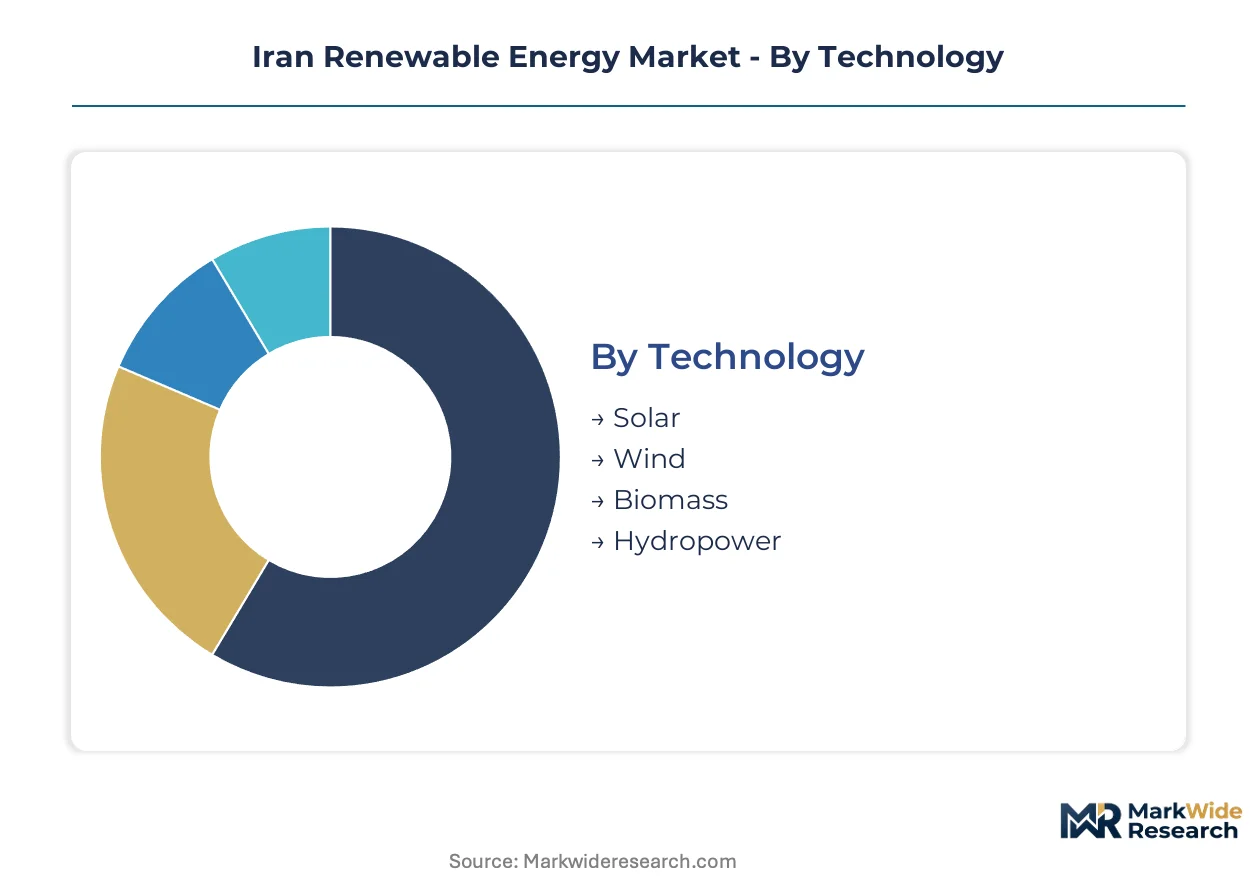
Segmentation in Iran's renewable energy market reveals how SATBA's tariff tiers and TAVANIR's interconnection protocols allocate capital across competing technologies and customer types. Understanding these divisions exposes where procurement power concentrates and which installation configurations unlock project bankability.
Technology:
Margin pools in Iran's renewable technology stack concentrate where domestic manufacturing capabilities intersect with import substitution policies and irradiance endowments.
- Solar:Photovoltaic systems rated at 300-550 Wp under standard test conditions dominate capacity additions. Tehran's utility-scale corridor and industrial zones in Isfahan anchor procurement, with bifacial modules capturing albedo gains from desert terrain to compress levelized costs.
- Wind:Turbine installations scaled from 1.5 MW onshore units to multi-megawatt configurations cluster in northwestern provinces. Mapna Group's domestic manufacturing base supplies Mapna Group turbine capacity, though TAVANIR transmission bottlenecks strand projects behind inadequate substation infrastructure.
- Biomass:Agricultural residue conversion systems qualify under SATBA's biomass tariff tier. Livestock and dairy operations in Mazandaran and Gilan generate feedstock for distributed generation units serving processing loads.
- Hydropower:Existing dam infrastructure provides baseload renewable capacity with limited expansion headroom. Retrofit opportunities concentrate on efficiency upgrades rather than greenfield development.
The dominant share belongs to Solar, while Wind is closing the gap fastest where transmission investment catches up to resource potential.
Application:
Application segmentation tracks how electricity consumers across Iran's economy deploy renewable assets to manage energy costs and supply security.
- Industrial:Power-intensive manufacturers in steel, cement, and petrochemicals anchor behind-the-meter procurement. Isfahan and Khuzestan clusters contract solar arrays to hedge natural gas price volatility and grid instability.
- Commercial:Retail and office buildings in Tehran metropolitan area specify rooftop installations under net metering arrangements. SATBA's revised time-of-day tariffs reward midday peak production with premium rates.
- Residential:Single-family and multi-unit dwellings access subsidized financing through state-backed programs. Deployment concentrates in affluent Tehran districts and Yazd province with high solar irradiance.
- Agricultural:Irrigation pumping and cold storage operations in water-stressed regions adopt off-grid hybrid systems. Remote southeastern provinces lacking transmission reach present first-mover potential for solar-plus-storage configurations.
Industrial applications command the largest project scale, though Agricultural installations are expanding most quickly in unserved territories.
End User:
End user categories reflect divergent risk appetites and capital access within Iran's constrained financing environment.
- Utilities:TAVANIR and provincial distribution companies procure utility-scale capacity through competitive tenders. Grid interconnection prioritization shapes developer consortium formation.
- Developers:Domestic project sponsors navigate foreign equipment financing complications and letter-of-credit constraints under sanctions protocols. Debt tenors compress as SATBA recalibrates feed-in tariffs.
- Government:Ministry of Energy and SATBA administer national development plan targets steering state-backed financing. Grid code compliance enforcement determines generator interconnection eligibility.
- Corporations:Industrial off-takers negotiate bilateral power purchase agreements for dedicated behind-the-meter supply. Direct contracting bypasses utility-mediated procurement.
Utilities retain control of grid-scale procurement pipelines, while Corporations are gaining share fastest through unbundled contracting.
Installation Type:
Installation configuration determines project economics through interconnection cost allocation and operational flexibility trade-offs.
- On-grid:Grid-tied systems dominate where TAVANIR transmission infrastructure permits. SATBA purchase guarantees provide revenue certainty attracting domestic banking syndicates.
- Off-grid:Standalone systems serve remote southeastern provinces lacking transmission reach. Solar-plus-storage configurations address agricultural processing loads beyond grid extension.
- Hybrid:Dual-source installations combine renewable generation with diesel backup. Industrial facilities retain heavy fuel oil systems that undercut renewable offtake during grid emergencies.
- Community:Shared renewable assets aggregate demand across multiple small consumers. Rural electrification programs and cooperative structures enable cost pooling.
On-grid configurations hold the installed base advantage, though Off-grid systems are climbing the fastest where transmission investment lags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iran exports electricity across its eastern border to Afghanistan and Pakistan through transmission corridors managed by TAVANIR, while grid interconnection discussions with neighboring states shape regional energy trade flows.
Tehran Province
Industrial manufacturers in steel and cement sectors anchor solar procurement demand. SATBA's feed-in tariff revisions prioritize grid interconnection for utility-scale projects. The Tehran metropolitan corridor concentrates developer activity around bifacial module installations serving behind-the-meter consumption.
Isfahan Province
Power-intensive manufacturing clusters seek cost hedging against natural gas price volatility. The Ministry of Energy enforces grid code compliance for generator interconnection eligibility. Steel producers in Isfahan city contract dedicated solar arrays through bilateral power purchase agreements.
Northwestern Provinces
Wind resource potential attracts Mapna Group turbine deployment. TAVANIR transmission infrastructure expansion lags behind generation capacity additions. Tabriz and surrounding zones strand wind projects behind inadequate substation infrastructure.
Southeastern Provinces
Remote agricultural operations adopt off-grid hybrid systems beyond transmission reach. SATBA's tariff framework excludes these territories from utility-scale procurement programs. Solar-plus-storage configurations serve irrigation pumping loads in water-stressed regions.
Mazandaran and Gilan
Livestock and dairy operations generate biomass feedstock for distributed generation. SATBA's biomass tariff tier qualifies agricultural residue conversion systems. Coastal provinces leverage biogas potential to offset grid dependency for processing facilities.
Iran Renewable Energy Market Competitive Landscape
Player mix skews toward state-affiliated entities and domestic engineering conglomerates. SATBA and TAVANIR anchor the institutional layer through tariff administration and transmission ownership. Mapna Group supplies turbine manufacturing capacity. Competitive moves center on equipment sourcing localization and debt tenor renegotiation amid feed-in tariff compression.
Among domestic engineering specialists, Mapna Group and Behnotech Eng. occupy positions within the equipment supply tier, while SATBA and TAVANIR represent the institutional infrastructure layer. Sheedsun Co. and ArtinA Renewable Energy exemplify project development archetypes navigating foreign module sourcing restrictions. Rapano Energy and SUNA sit within the emerging independent power producer segment.
| Leading Market Players |
|---|
| Rapano Energy |
| Behnotech Eng. |
| Iran Renewable Energy Association |
| Sheedsun Co. |
| ArtinA Renewable Energy |
| SUNA |
| TAVANIR |
| SATBA |
| Mapna Group |
| Others |
Supply & Pricing Matrix
SATBA's feed-in tariff certification tiers gate both equipment qualification and developer revenue simultaneously, compressing margins for projects unable to secure premium tariff bands while rewarding bifacial module deployments that maximize capture rates. This regulatory architecture forces procurement decisions toward higher-efficiency technologies that justify upfront cost premiums through enhanced tariff eligibility.
Pricing Analysis
Monofacial-to-bifacial module pricing gaps now span three distinct technology generations in utility-scale tenders, with double-glass construction commanding 15-20% premiums that albedo-capture economics justify in desert terrain. Price differentiation hinges on module efficiency certification under SATBA's technical standards and domestic content ratios that influence tariff band placement. Cost compression in standard-tier equipment is intensifying as Chinese module oversupply reaches Iranian buyers through third-country routing. Industrial off-takers in Isfahan exhibit highest price sensitivity, while utility-scale developers prioritize performance over unit cost to secure interconnection queue position.
Supply Chain Analysis
Strategic stockpiling of photovoltaic modules has displaced just-in-time procurement as developers buffer against import licensing delays and currency volatility. Manufacturing concentration centers on China for cells and modules, South Korea for inverters, and domestic assembly for Mapna Group turbine components. Polysilicon supply draws from Chinese producers, while tracking systems and power electronics rest on East Asian sourcing. Single-source vulnerability runs through hard-currency payment channels constrained by sanctions protocols. Distribution runs through Tehran-based EPC contractors that manage customs clearance and site logistics for provincial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's renewable energy market represents early-cycle expansion with industrial behind-the-meter adoption accelerating as natural gas price volatility compounds grid reliability concerns for power-intensive manufacturers.
For Market Incumbents: Secure module inventory positions through forward contracts with East Asian suppliers before tariff band recalibrations compress developer returns further. Mapna Group should anchor wind turbine servicing capabilities in Tabriz to preempt emerging EPC competitors from capturing northwestern O&M revenue streams. SATBA's interconnection prioritization protocols favor developers with established TAVANIR relationships, making channel control the critical defensive lever against new market entrants. For New Entrants and Emerging Players: Lead with off-grid hybrid system deployments in Sistan-Baluchestan Province where transmission infrastructure gaps exclude incumbent utility-scale competitors. Agricultural processing loads present the most penetrable customer segment, with solar-plus-storage configurations addressing irrigation pumping demand beyond grid extension timelines. Direct equipment financing partnerships with provincial agricultural cooperatives offer a differentiated go-to-market angle that bypasses Tehran-centric banking relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from state-affiliated engineering conglomerates seeking to monetize non-core renewable development subsidiaries amid fiscal consolidation pressures. Long-term viability hinges on SATBA's commitment to purchase guarantee mechanisms through the projection horizon. The signal to watch is feed-in tariff adjustment frequency: accelerated recalibration cycles would indicate revenue certainty erosion requiring portfolio reweighting toward industrial offtake contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Module Supply Agreement | Long-term offtake contracts with Chinese manufacturers insulate developers against import licensing volatility. |
| Grid Interconnection Partnership | Collaborative agreements with TAVANIR accelerate queue position for utility-scale solar corridor projects. |
| Domestic Turbine Manufacturing Scale-Up | Mapna Group's component localization reduces hard-currency exposure for northwestern wind developments. |
| Biogas Feedstock Integration | Agricultural residue supply contracts in Mazandaran unlock SATBA biomass tariff tier eligibility. |
| Industrial PPA Structuring | Bilateral power purchase agreements with Isfahan steel producers bypass utility-mediated procurement constraints. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SATBA regulatory filings, TAVANIR grid expansion disclosures, and Ministry of Energy development plan documents. Primary interviews engaged utility planning officers at provincial distribution companies, IPP project developers active in Tehran and Isfahan corridors, EPC contractors managing module import logistics, and industrial energy managers at steel and cement manufacturing clusters. Bottom-up capacity addition tracking triangulates against top-down national target assessments to validate market sizing.
Segmentation dimensions modeled span technology type, application vertical, end-user category, and installation configuration across the projection horizon. CAGRs derive from capacity deployment run rates, tariff band evolution scenarios, and interconnection queue velocity assumptions. Forecast inputs incorporate solar irradiance mapping data, wind resource assessments for northwestern zones, and industrial electricity demand projections from manufacturing sector surveys.
Forecasts assume regulatory continuity in SATBA tariff administration and Ministry of Energy grid code enforcement; material policy shifts would require re-modeling. Revision becomes warranted when foreign module sourcing restrictions tighten or TAVANIR transmission investment delays exceed substation infrastructure planning thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Romania Renewable Energy Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Wind Turbine Foundation Market