
 Solar Floating Pool Lights Market | 2026-2036
Solar Floating Pool Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Floating Pool Lights Market Insights
Multi-unit bundling is consolidating buyer choice as manufacturers package solar floating pool lights in seasonal assortments rather than single-piece offerings. Spin Master leverages its toy-and-game distribution infrastructure to secure shelf placement at mass retailers during spring reset periods. Bestway anchors its position through backward integration into PVC and thermoplastic molding operations for its inflatable and hard-sided pool accessory lines. Kokido specializes in European channel control, sustaining placement through dedicated pool service and maintenance dealer networks.
Solar floating pool lights are photovoltaic-powered luminaires designed to rest on water surfaces, typically incorporating monocrystalline or polycrystalline silicon cells with 5-12 lumens output and IP68-rated sealed housings for continuous submersion resistance; their commercial purpose centers on decorative illumination and nighttime safety marking for residential and hospitality aquatic environments. LED product configurations dominate unit economics due to minimal draw requirements and 50,000-hour operational lifespans, while remote controlled variants command premium positioning among resort facilities seeking programmable color sequencing. Thin-film technology segments face margin compression against crystalline alternatives but retain niche traction in garden pond applications where diffuse light output suffices and flexible form factors matter.
FCC certification governs radio-frequency remote control modules sold into the US market, while EU REACH compliance constrains phthalate content in floating housing plastics and CE marking mandates electrical safety validation for photovoltaic components sold across member states. EPA Energy Star eligibility for integrated solar charging systems shapes procurement criteria among US recreation centers receiving municipal sustainability funding. Stakeholders must monitor evolving battery chemistry regulations in target jurisdictions as lithium-ion restrictions tighten and solid-state alternatives reach commercial viability thresholds.
Market Dynamics
Monocrystalline photovoltaic cell efficiency gains are compressing charging windows while extending evening illumination duration, fundamentally altering the value proposition for residential pool owners who previously accepted shorter runtime trade-offs.
Growth Catalysts
- Backyard pool ownership expansion:Suburban residential development across Sun Belt states is generating concentrated demand for ambient aquatic lighting solutions that eliminate electrical cord hazards.
- EPA Energy Star procurement criteria:US recreation centers receiving municipal sustainability funding now mandate integrated solar charging systems, redirecting institutional purchasing toward certified products.
- Monocrystalline cell efficiency:Reduced charging time requirements enable smaller surface area designs that preserve aesthetic minimalism while maintaining lumen output.
Market Restraints
- Lithium-ion battery chemistry constraints:Evolving jurisdiction-level restrictions on lithium-ion transport and disposal are elevating compliance costs for manufacturers maintaining multi-regional product lines.
- Polycrystalline silicon margin compression:Thin-film technology segments face sustained price pressure from crystalline alternatives, constraining viable positioning outside garden pond niches.
- IP68 housing cost structure:Sealed thermoplastic molding requirements for continuous submersion resistance elevate bill-of-materials costs relative to terrestrial solar lighting equivalents.
Strategic Opportunities
- Hospitality programmable sequencing:Resort facilities seek remote-controlled variants with color-transition capabilities, creating premium positioning above standard residential offerings.
- EU REACH compliance differentiation:Phthalate-free housing formulations that exceed baseline regulatory thresholds enable positioning toward environmentally covenanted institutional buyers.
- Pool service dealer channel penetration:Dedicated maintenance networks represent underexploited distribution infrastructure for replacement and upgrade cycles in European markets.
Industry Challenges
- FCC certification timeline:Radio-frequency remote control modules require extended validation periods for US market entry, compressing seasonal launch windows.
- CE marking electrical safety validation:Photovoltaic component testing across member states introduces documentation complexity for products targeting pan-European distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Floating Pool Lights Market |
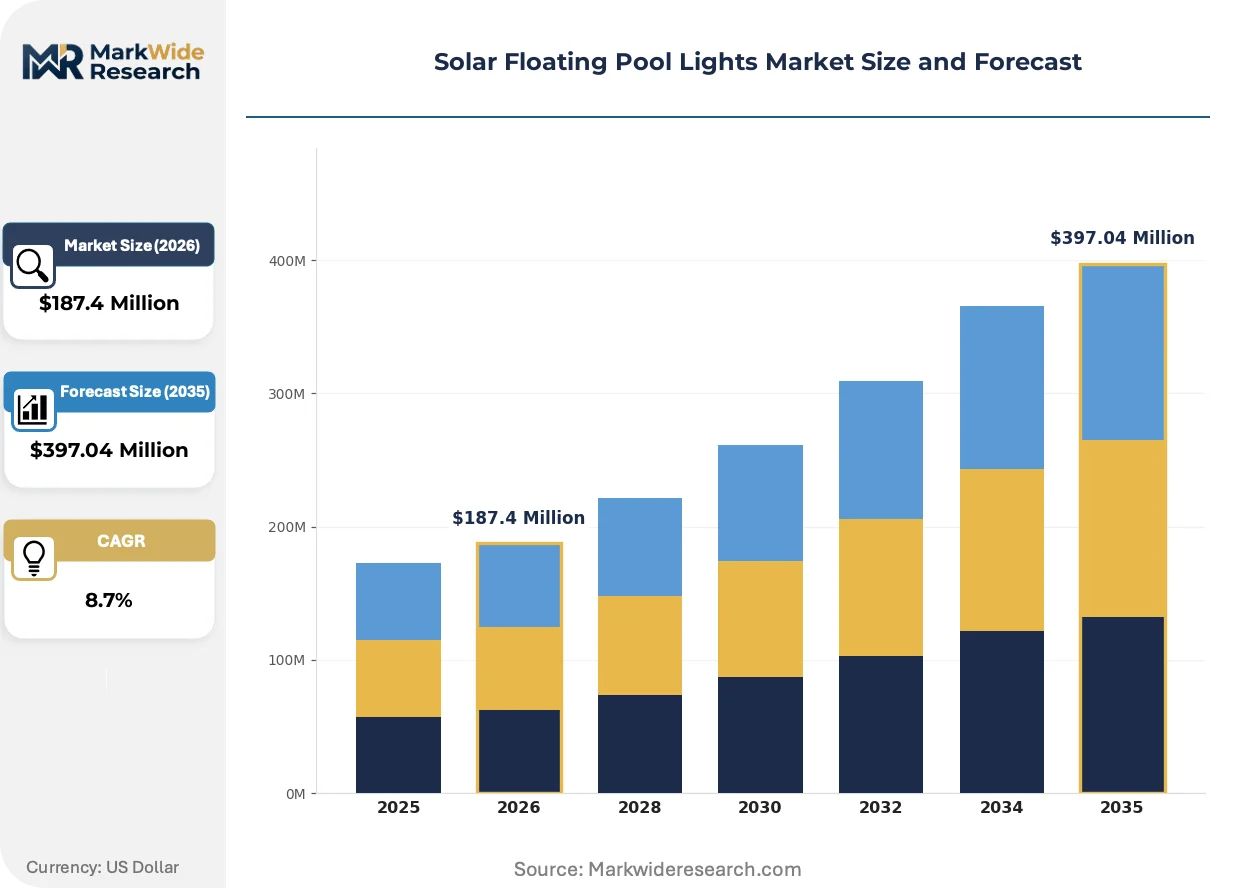
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Solar Panel Integrated, Battery Operated, Remote Controlled Technology: Monocrystalline, Polycrystalline, Thin-Film, Amorphous Silicon Application: Home Pools, Hotel Pools, Water Parks, Garden Ponds End User: Resort Facilities, Recreation Centers, Private Owners, Event Organizers |
| Companies Covered | Spin Master, Intex, Bestway, Kokido, Poolmaster, GAME Solar, Sunnydaze, Blue Wave Products, URPOWER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Floating Pool Lights Market Trends and Innovations
Product configuration and control interfaces are undergoing rapid specification shifts as buyer expectations migrate from static illumination toward programmable ambient systems. These developments are compressing traditional category boundaries between decorative and functional aquatic lighting.
LED product configurations are consolidating unit economics across the installed base due to minimal draw requirements and extended operational lifespans. Residential pool owners now specify these variants as default replacements for failed incandescent or halogen predecessors. The technology is consolidating supplier margins by reducing warranty exposure and enabling smaller battery form factors.
EU REACH constraints on phthalate content in floating housing plastics are forcing reformulation investments among manufacturers with European exposure. The industrial consequence is elevated raw material qualification costs for suppliers lacking pre-validated polymer supply chains. CE marking mandates for photovoltaic electrical safety are most acutely affecting mid-tier producers without captive testing laboratory relationships.
Mass retail spring reset periods now concentrate annual purchasing decisions into compressed eight-week windows. Pool owners increasingly defer replacement purchases until seasonal assortment visibility confirms product availability, displacing traditional hardware channel year-round stocking. This pattern is most visible in United States suburban markets where big-box seasonal space allocation determines competitive access.
Solar Floating Pool Lights Market Segmentation
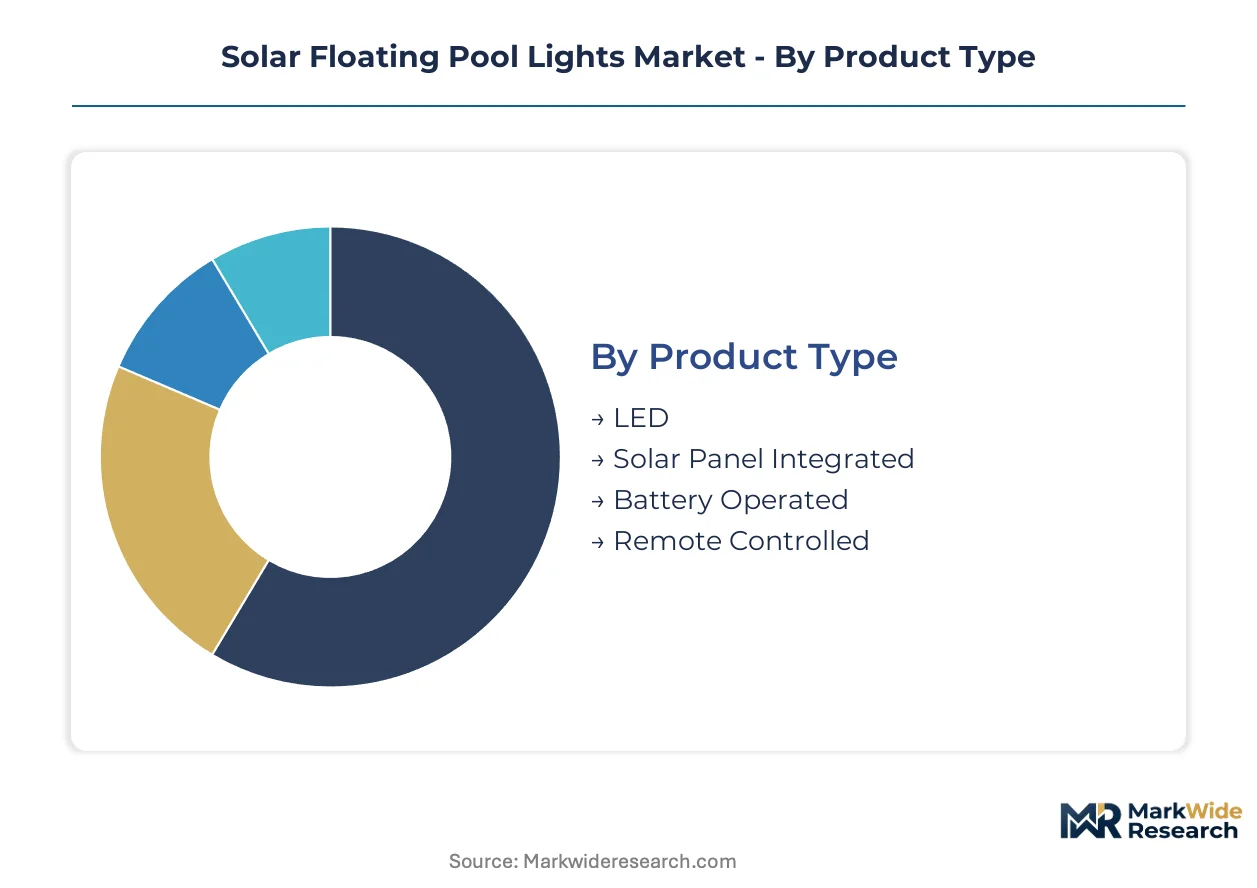
Segmentation in solar floating pool lights reveals how certification burdens, efficiency thresholds, and end-use durability requirements fragment supplier strategies across distinct technical and commercial boundaries. Each dimension carries unique regulatory weight and margin implications that shape competitive positioning.
Product Type:
FCC certification governs radio-frequency modules in remote-controlled variants, while CE marking applies universally to photovoltaic-integrated housings sold across EU member states.
- LED:Solid-state illumination with 50,000-hour operational lifespans and minimal current draw enables smaller battery form factors. Demand concentrates among US suburban pool owners replacing failed incandescent fixtures, driven by warranty reduction and energy efficiency procurement criteria.
- Solar Panel Integrated:Monocrystalline or polycrystalline cells fused directly into sealed housings eliminate external charging dependencies. Hotel pool operators in Sun Belt states specify these for uninterrupted evening illumination without electrical cord hazards.
- Battery Operated:Removable cell configurations suit replacement cycles in recreation center maintenance programs.
- Remote Controlled:Programmable color sequencing modules command premium positioning at resort facilities.
Leading the category by volume: LED. Growing fastest: Remote Controlled.
Technology:
Cell efficiency directly determines surface area requirements and aesthetic minimalism, creating tiered cost structures across crystalline and thin-film alternatives.
- Monocrystalline:Single-crystal silicon construction delivers highest conversion efficiency, compressing charging windows to 4-6 hours of direct sun. US residential installations favor these for extended evening runtime without enlarged floating profiles.
- Polycrystalline:Multi-crystal silicon offers moderate efficiency at reduced unit cost. Garden pond applications in European markets absorb volume here, constrained by diffuse output sufficiency and price-sensitive positioning.
- Thin-Film:Flexible cadmium-telluride or CIGS layers enable curved form factors. Niche traction persists in decorative water features where rigid crystalline panels disrupt visual continuity.
- Amorphous Silicon:Non-crystalline deposition suits low-light performance requirements in shaded pool environments.
Highest efficiency: Monocrystalline. Steepest expansion trajectory: Thin-Film in garden pond niches.
Application:
Durability specifications escalate with foot traffic and chemical exposure, separating consumer-grade from commercial-grade housing requirements.
- Home Pools:Residential installations prioritize IP68 submersion ratings and aesthetic minimalism over programmable features. Suburban Sun Belt communities generate concentrated replacement demand during spring reset periods.
- Hotel Pools:Hospitality operators mandate remote-controlled color sequencing for brand-aligned ambient programming. Resort facilities in Florida and Arizona specify premium variants with centralized management interfaces.
- Water Parks:High-velocity water exposure requires reinforced thermoplastic molding and redundant sealing.
- Garden Ponds:Smaller surface areas and decorative priorities accommodate lower-lumen thin-film configurations.
Dominant revenue concentration: Home Pools. Gaining share fastest: Hotel Pools.
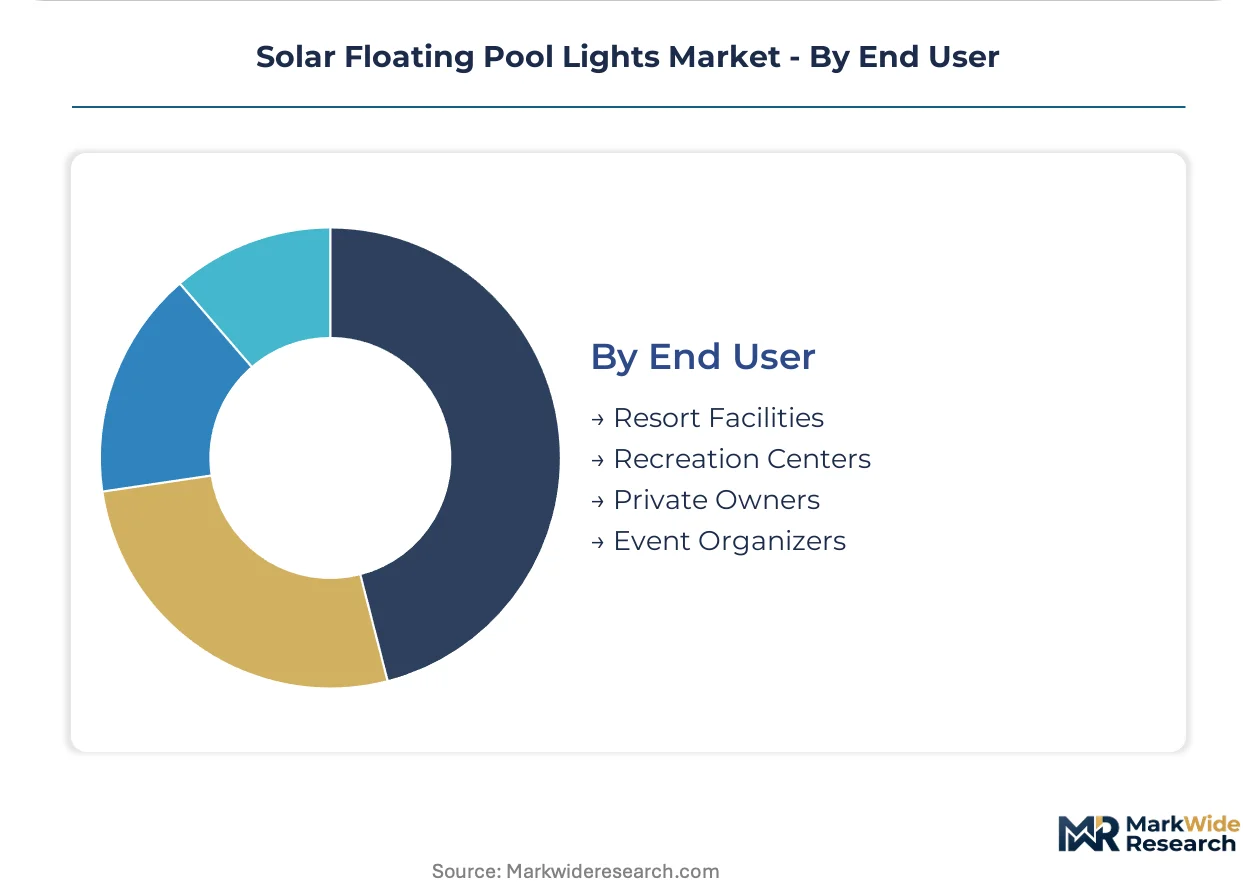
End User:
Procurement authority and replacement cycle timing vary sharply between institutional buyers with seasonal budgets and individual owners with event-driven purchasing patterns.
- Resort Facilities:Centralized purchasing departments specify programmable premium variants with multi-year operational lifespans. EPA Energy Star eligibility shapes procurement criteria for properties receiving municipal sustainability funding.
- Recreation Centers:Public-sector maintenance programs defer replacement decisions to fiscal year cycles with certified vendor requirements.
- Private Owners:Individual suburban households drive spring seasonal spikes through mass retail channel visibility.
- Event Organizers:Temporary installation requirements favor rental and disposable configurations for single-weekend deployment.
Largest installed base: Private Owners. Fastest procurement formalization: Resort Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sun Belt Opportunity Zones across Florida and Arizona concentrate backyard pool installations and drive ambient lighting procurement. Municipal sustainability funding programs in these zones accelerate solar-powered fixture adoption through rebate structures.
United States
Suburban residential development across Florida, Texas, and Arizona generates concentrated demand for cord-free aquatic illumination. EPA Energy Star procurement criteria redirect institutional purchasing toward certified solar charging systems at recreation centers receiving municipal funding. Phoenix and Orlando metropolitan clusters anchor replacement cycle timing to mass retail spring reset periods.
Germany
EU REACH compliance on phthalate content shapes housing material selection for pool accessories entering the single market. CE marking mandates for photovoltaic electrical safety validate product entry across member states. Bavaria's recreational facility operators prioritize extended operational lifespans in procurement specifications.
China
Monocrystalline photovoltaic cell manufacturing clusters in Jiangsu and Zhejiang provinces supply component inputs to downstream assemblers. GB standards for electrical safety govern domestic product circulation. Shenzhen-based exporters navigate FCC certification timelines for radio-frequency modules targeting US seasonal launch windows.
Australia
High backyard pool ownership rates in Queensland and New South Wales sustain replacement demand for submersion-rated lighting fixtures. State-level sustainability procurement guidelines at public aquatic facilities favor solar-integrated configurations. Sydney's hospitality sector specifies programmable color sequencing for resort pool ambient programming.
United Kingdom
Post-Brexit UKCA marking requirements run parallel to retained CE standards for electrical safety validation. Garden pond applications in Southeast England absorb lower-lumen thin-film configurations for decorative water features. London's hotel operators import premium remote-controlled variants through dedicated pool service dealer networks.
Solar Floating Pool Lights Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Toy-and-game distributors leverage seasonal retail infrastructure against dedicated pool accessory manufacturers with captive molding operations. Three archetypes dominate: mass-market consumer goods conglomerates, specialized aquatic equipment fabricators, and solar lighting component integrators. Competitive moves concentrate on backward integration into thermoplastic molding and exclusive dealer network penetration.
Among North American consumer goods conglomerates, Spin Master exemplifies mass-market distribution leverage through toy-and-game retail relationships. Bestway anchors the specialized aquatic equipment tier with in-house PVC and thermoplastic molding capabilities for pool accessory lines. Kokido occupies a position within European channel control specialists, sustaining placement through dedicated pool service and maintenance dealer networks.
| Leading Market Players |
|---|
| Spin Master |
| Intex |
| Bestway |
| Kokido |
| Poolmaster |
| GAME Solar |
| Sunnydaze |
| Blue Wave Products |
| URPOWER |
| Others |
Pricing and Supply Chain Analysis
Backward integration into thermoplastic molding operations anchors both supply security and margin control for specialized aquatic equipment fabricators, insulating premium-positioned manufacturers from raw material volatility while compressing production lead times relative to outsourced competitors. This captive production capability enables pricing discipline during seasonal demand spikes when spot-market resin costs fluctuate.
Pricing Analysis
Expedited delivery premiums command substantial markups during mass retail spring reset windows when compressed eight-week purchasing cycles eliminate buffer inventory options. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified remote-controlled variants from basic LED configurations and unbranded imports, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from polycrystalline silicon margin compression against monocrystalline alternatives. Private owners in suburban Sun Belt communities exhibit highest price sensitivity, while resort facilities demonstrate lowest sensitivity due to brand-aligned ambient programming requirements.
Supply Chain Analysis
Domestic-content mandates in US municipal sustainability funding programs are reshaping sourcing patterns for recreation center procurement, favoring assemblers with North American final-assembly footprints. Monocrystalline photovoltaic cell production concentrates in China, South Korea, and Taiwan, while thermoplastic housing molding localizes near end-markets to minimize freight costs on volumetric components. Raw material dependencies span lithium-ion battery cells, IP68-rated sealing compounds, and monocrystalline silicon wafers. Single-source vulnerability in photovoltaic cell supply creates exposure to export licensing restrictions. Distribution runs through mass retail seasonal resets, dedicated pool service dealer networks, and hospitality procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FCC certification timelines and EU REACH phthalate constraints erect barrier-to-entry moats favoring incumbents with pre-validated supply chains and captive testing laboratory relationships.
For Market Incumbents: Hedge against lithium-ion chemistry regulatory shifts by qualifying solid-state battery suppliers before jurisdiction-level transport restrictions tighten. Defensive consolidation through exclusive dealer network penetration in European pool service channels protects replacement cycle capture from mass retail commoditization. For New Entrants and Emerging Players: Direct-to-consumer digital channels bypass concentrated mass retail gatekeeper control, enabling margin capture absent shelf placement fees. White-space targets concentrate in garden pond thin-film niches and event organizer temporary deployment segments, with subscription-based seasonal rental models as the penetrable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified consumer goods conglomerates seeking aquatic leisure category expansion. Long-term viability favors targets with backward-integrated molding operations and validated FCC/CE certification portfolios. The signal to watch is municipal sustainability funding program expansion accelerating institutional procurement formalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoplastic Molding | Captive IP68 housing production insulates margins from resin spot-price volatility during seasonal demand spikes. |
| FCC Certification Pre-Validation Investment | Early radio-frequency module testing compresses US market entry timelines ahead of spring reset windows. |
| EU REACH-Compliant Housing Reformulation | Phthalate-free polymer qualification opens institutional procurement channels with environmental covenants. |
| Pool Service Dealer Network Expansion | Exclusive European maintenance channel placement captures replacement cycles displaced from hardware retail. |
| Hospitality Programmable Sequencing Development | Resort-grade color-transition capabilities command premium positioning above standard residential offerings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pool accessory procurement managers, thermoplastic molding operations directors, mass retail category buyers, and hospitality facilities engineers. Secondary validation drew from EPA Energy Star certification databases, FCC equipment authorization records, EU REACH substance registration lists, and import-export trade statistics. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across crystalline and thin-film technology segments.
Data-stream reconciliation across photovoltaic cell efficiency trajectories, seasonal purchasing pattern indices, and certification timeline distributions shaped the analytical framework. Segmentation dimensions modeled include product configuration, cell technology type, end-use application, and procurement authority structure. CAGRs derived from fitted growth curves calibrated to replacement cycle timing and municipal funding program expansion rates. Forecast inputs incorporated monocrystalline efficiency gain curves and lithium-ion regulatory restriction probability assessments.
Inputs from EPA, FCC, and ECHA regulatory databases were available through the study window; gaps in real-time dealer network inventory positioning introduce uncertainty bands around seasonal demand spike magnitude estimates. Forecasts reflect documented assumptions regarding Sun Belt residential development continuity and solid-state battery commercialization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Solar Farm Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Sweden Renewable Energy Market