
 Solar Street Lighting Market | 2026-2036
Solar Street Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Street Lighting Market Analysis
The EU Green Deal is decoupling fossil-dependent street lighting from public procurement eligibility across member states. Fonroche Lighting leverages captive solar engineering to dominate French municipal retrofit programs. Leadsun anchors Asia-Pacific distribution through localized battery-integrated pole manufacturing. Greenshine New Energy specializes in off-grid highway installations across North American secondary road networks.
Solar street lighting comprises autonomous photovoltaic-powered illumination systems incorporating monocrystalline or polycrystalline panels, lithium-iron-phosphate or gel-cell batteries, MPPT charge controllers, and high-efficacy LED arrays rated typically between 3000K and 6000K color temperature, engineered to replace grid-tied sodium vapor or metal halide luminaires in outdoor public spaces. LED product segments command the dominant margin pool due to phosphor-conversion efficiency gains and 50,000-hour operational lifespans, while IoT Integrated technology segments represent the fastest-expanding structural category as remote dimming and predictive maintenance protocols reduce OPEX for municipalities. Battery segments remain the most cost-sensitive dimension, with lithium-ion chemistry displacing lead-acid configurations in premium installations.
FCC Part 15 governs wireless control emissions for smart-enabled U.S. installations, while India's CEA mandates technical standards for standalone solar systems connected to state highway infrastructure. The EU AI Act introduces algorithmic transparency requirements for automated lighting control systems processing pedestrian or vehicular sensor data. Stakeholders must monitor how procurement codes in multiple jurisdictions redefine minimum local content thresholds for panel and battery assembly.
Market Dynamics
Municipal procurement codes across India, Vietnam, and France are decoupling fossil-dependent street lighting from public eligibility, forcing integrators to requalify around captive solar engineering and local content thresholds.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic module cost compression accelerates pole-mounted LED deployment by domestic lighting integrators in smart city corridors.
- Battery chemistry advancement:Lithium-iron-phosphate configurations displace lead-acid in premium installations, extending operational lifespans and reducing replacement cycles.
- EU Green Deal procurement exclusions:Fossil-dependent street lighting loses eligibility across member states, redirecting municipal retrofit budgets toward autonomous photovoltaic systems.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in East Asia create input cost volatility and geopolitical exposure for integrators sourcing storage components.
- Technical limitation in low-latitude performance:Monocrystalline panel efficiency degradation under tropical humidity and dust accumulation compresses energy yield in Southeast Asian highway networks.
- Regulatory friction from EU AI Act:Algorithmic transparency requirements for automated lighting control systems processing pedestrian sensor data extend certification timelines and compliance costs.
Strategic Opportunities
- Vietnam's provincial highway networks:Underpenetrated secondary road infrastructure outside Ho Chi Minh City and Hanoi corridors offers first-mover positioning for off-grid installation specialists.
- IoT-MPPT convergence:Remote dimming protocols integrating with maximum power point tracking controllers enable predictive maintenance revenue streams and recurring software attach rates.
- FCC Part 15 wireless emissions framework:Smart-enabled U.S. installations gain accelerated type-approval pathways, opening municipal retrofit programs to connected pole architectures.
Industry Challenges
- Electrochemical systems integration:Matching lithium-iron-phosphate discharge curves with LED driver electronics and MPPT algorithms requires scarce power electronics engineering talent.
- CEA technical standard compliance:India's Central Electricity Authority mandates for standalone solar systems connected to state highway infrastructure impose extended testing protocols that compress bidding windows.
- Legacy sodium vapor retrofit compatibility:Existing pole foundations and spacing geometries designed for high-pressure sodium luminaires constrain LED array photometric distribution without civil reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Street Lighting Market |
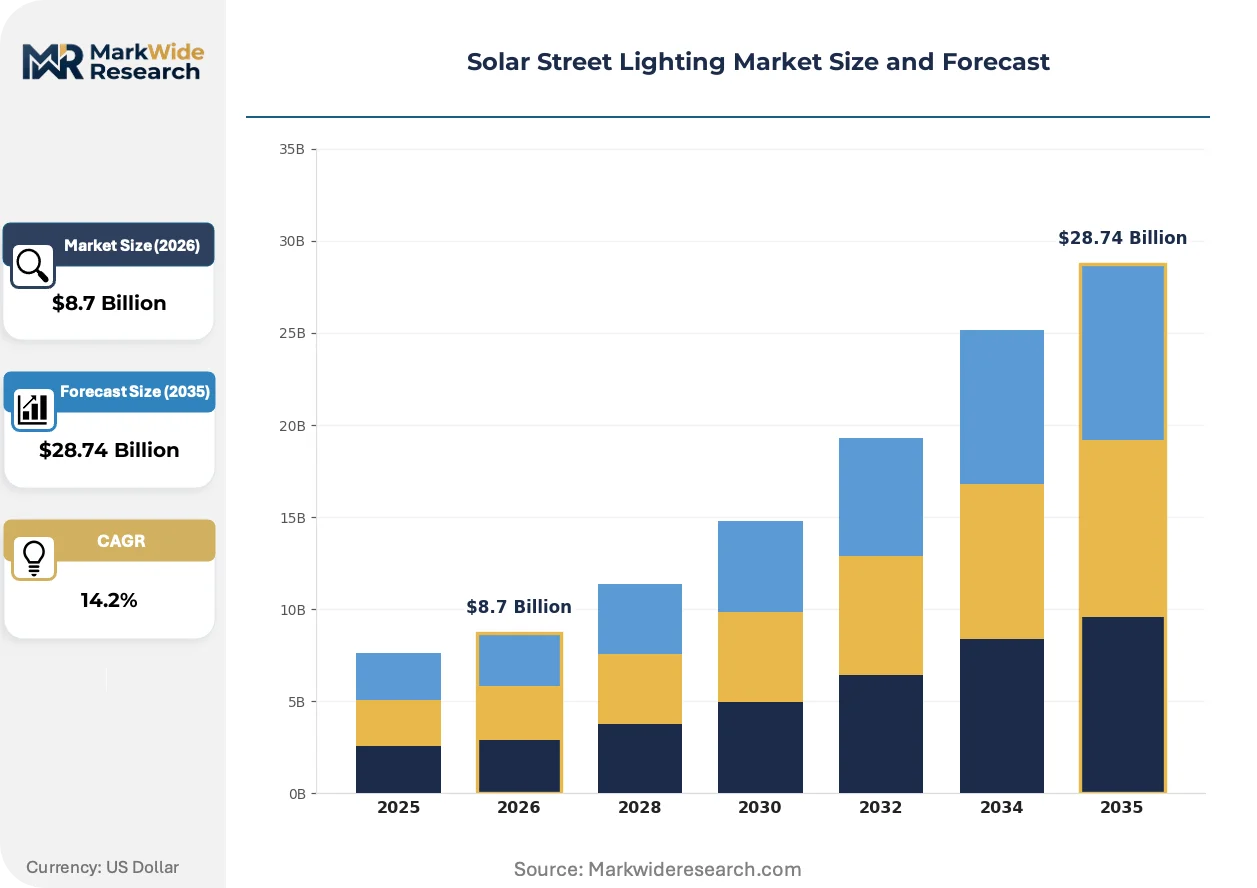
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Solar Panel, Battery, Controller Installation Type: Surface Mounted, Pole Mounted, Wall Mounted, Embedded End User: Municipalities, Commercial Properties, Residential Areas, Highways Technology: Off-Grid, Hybrid, IoT Integrated, Smart Control |
| Companies Covered | Cmoonlight, First Light Technologies, Sunna Design, Leadsun, Solar Street Lights USA, Fonroche Lighting, ADNLITE, EnGoPlanet, Greenshine New Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Street Lighting Market Emerging Trajectories
Active reshaping in solar street lighting centers on three vectors: photovoltaic-battery-electronics convergence tightening system integration, regulatory frameworks hardening algorithmic accountability, and municipal procurement compressing vendor qualification around lifecycle service capabilities.
Maximum power point tracking controllers are converging with cloud-based remote management platforms to enable real-time dimming adjustments based on pedestrian detection and traffic flow patterns. French municipal retrofit programs now specify predictive maintenance protocols as mandatory bid elements. This convergence is compressing vendor margins on hardware while expanding recurring revenue pools for software-integrated service providers.
The EU AI Act introduces mandatory algorithmic transparency documentation for automated lighting control systems processing vehicular or pedestrian sensor data. Industrial consequence requires integrators to maintain technical file repositories demonstrating bias testing and decision-log explainability. Smart-enabled installations across German and French urban corridors face the most acute compliance burden, with some municipalities delaying procurement until certification pathways clarify.
Municipal buyers are unbundling after-sales service from capital equipment procurement, shifting toward performance-guarantee contracts with 10-year operational responsibility clauses. This disrupts traditional equipment-only vendors and elevates integrators with captive maintenance networks. The pattern concentrates in India's smart city corridors and Vietnam's provincial highway programs, where public works departments lack in-house electrochemical systems expertise.
Solar Street Lighting Market Segmentation
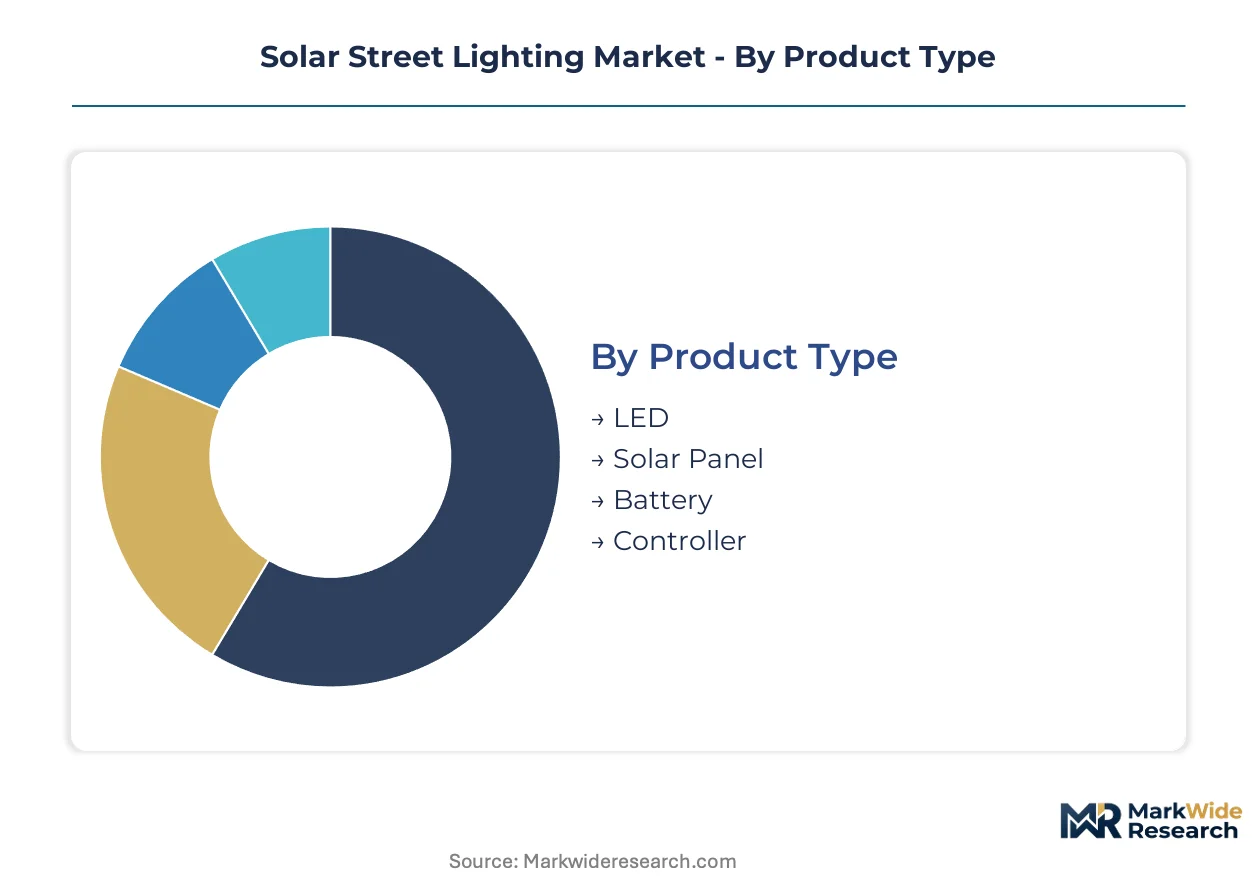
Segmentation in solar street lighting reveals how hardware specifications, mounting configurations, and connectivity architectures reshape procurement patterns. Municipal buyers unbundle capital equipment from lifecycle service contracts, forcing vendors to qualify across multiple technical dimensions simultaneously.
Product Type:
Technology specifications determine margin pools and replacement cycle economics across photovoltaic-battery-electronics assemblies.
- LED:Phosphor-conversion efficiency gains and 50,000-hour operational lifespans concentrate municipal retrofit budgets on high-efficacy arrays rated between 3000K and 6000K color temperature. Demand clusters in India's smart city corridors where local content requirements favor domestic luminaire assembly.
- Battery:Lithium-iron-phosphate chemistry displaces lead-acid configurations in premium installations, extending operational lifespans and compressing replacement cycles. Procurement in Vietnam's provincial highway networks prioritizes electrochemical systems with tropical humidity tolerance.
- Solar Panel:Monocrystalline and polycrystalline configurations capture ambient photovoltaic conversion for autonomous operation.
- Controller:MPPT charge controllers optimize energy harvest efficiency across variable irradiance conditions.
Mature deployment sits with LED arrays. Newer deployment is concentrated in lithium-iron-phosphate battery integration.
Installation Type:
Mounting geometry constraints from legacy infrastructure shape civil engineering requirements and installation cost structures.
- Pole Mounted:Dominant configuration for municipal highway and arterial road networks, leveraging existing pole foundations where spacing geometries accommodate LED photometric distribution. Southeast Asian infrastructure budgets accelerate procurement of pole-integrated systems with captive battery enclosures.
- Surface Mounted:Low-profile installations for pedestrian plazas and parking structures where below-grade electrical infrastructure is cost-prohibitive.
- Wall Mounted:Retrofit applications for building perimeter security and alleyway illumination.
- Embedded:Ground-recessed luminaires for landscape integration and pathway marking.
Volume concentrates in pole-mounted systems. Margin expansion tracks toward surface-mounted specialty applications.
End User:
Customer procurement sophistication varies sharply across public sector, commercial, and residential demand pools.
- Municipalities:Public works departments dominate volume through performance-guarantee contracts with 10-year operational responsibility clauses. EU Green Deal procurement exclusions across France and Germany redirect fossil-dependent retrofit budgets toward autonomous photovoltaic systems.
- Highways:State transportation authorities mandate technical standards for standalone solar systems connected to arterial infrastructure. India's CEA compliance requirements impose extended testing protocols that compress bidding windows for highway integrators.
- Commercial Properties:Corporate facility managers seek off-grid solutions for parking and perimeter security.
- Residential Areas:Homeowner association and gated community demand for pathway and street illumination.
Procurement sophistication peaks with municipalities. Fastest contract velocity appears in highway authorities.
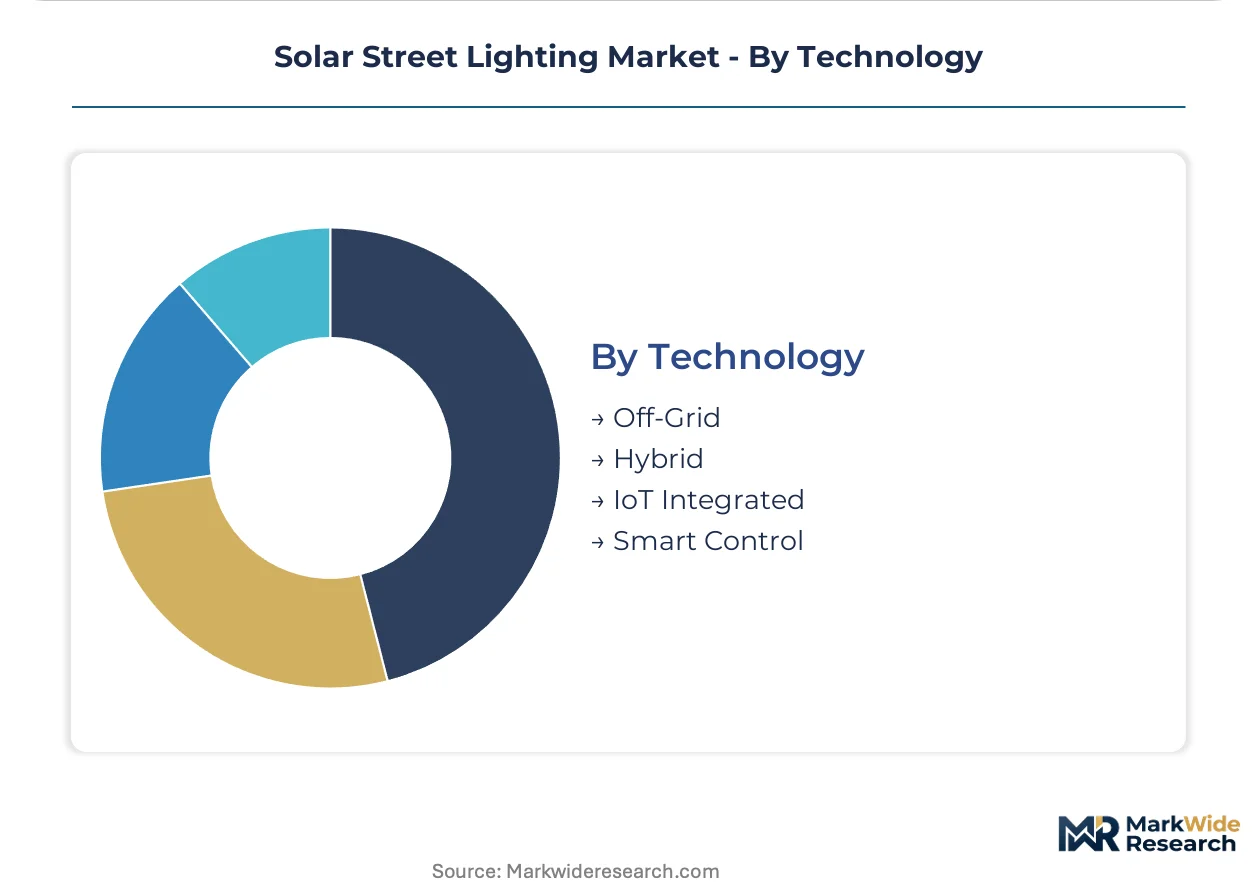
Technology:
Connectivity architecture separates commodity hardware from software-integrated service revenue streams.
- IoT Integrated:Remote dimming protocols converging with cloud-based management platforms enable predictive maintenance revenue streams. EU AI Act algorithmic transparency requirements for automated lighting control systems processing pedestrian sensor data extend certification timelines for smart-enabled installations.
- Smart Control:Automated dimming adjustments based on pedestrian detection and traffic flow patterns reduce OPEX for municipalities. FCC Part 15 wireless emissions framework accelerates type-approval pathways for connected pole architectures in U.S. municipal retrofit programs.
- Off-Grid:Fully autonomous operation without grid interconnection for remote and underpenetrated secondary road infrastructure.
- Hybrid:Grid-tied backup configurations for critical illumination corridors.
Revenue recurrence concentrates in IoT-integrated architectures. Steepest expansion trajectory tracks with smart control systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for solar manufacturing compresses module costs for domestic lighting integrators. Vietnam's provincial highway networks accelerate procurement of pole-mounted LED systems. France's EU Green Deal procurement exclusions redirect municipal retrofit budgets toward autonomous photovoltaic installations.
India
Smart city corridors in Delhi, Mumbai, and Bangalore concentrate demand for IoT-integrated pole systems. The CEA mandates technical standards for standalone solar systems connected to state highway infrastructure. Gujarat and Tamil Nadu host domestic module assembly clusters serving lighting integrators with compressed procurement cycles under PLI incentives.
Vietnam
Provincial highway networks outside Ho Chi Minh City and Hanoi corridors drive first-mover positioning for off-grid specialists. National infrastructure budgets prioritize electrochemical systems with tropical humidity tolerance. Da Nang and Can Tho emerge as procurement hubs for secondary road retrofit programs.
France
Municipal retrofit programs specify predictive maintenance protocols as mandatory bid elements. The EU AI Act imposes algorithmic transparency requirements for automated lighting control systems processing pedestrian sensor data. Lyon and Marseille urban corridors face acute compliance burdens as certification pathways clarify.
United States
FCC Part 15 accelerates type-approval pathways for smart-enabled municipal retrofit programs. Secondary road networks across North America prioritize off-grid highway installations. California and Texas transportation authorities unbundle after-sales service from capital equipment procurement.
Germany
EU Green Deal procurement exclusions decouple fossil-dependent street lighting from public eligibility. The EU AI Act extends certification timelines for smart-enabled installations processing vehicular sensor data. Berlin and Frankfurt urban corridors delay procurement until algorithmic transparency documentation requirements stabilize.
Solar Street Lighting Market Vendor Landscape
European producers anchor one tier; Asia-Pacific specialists hold manufacturing scale advantages. The vendor base separates into captive solar engineering integrators, localized battery-integrated pole manufacturers, and off-grid highway installation specialists. Strategic moves concentrate on geographic expansion into underpenetrated provincial networks and backward integration into lithium-iron-phosphate battery assembly.
Among French-based lighting integrators, Fonroche Lighting occupies a position within captive solar engineering archetypes. Leadsun represents the Asia-Pacific distribution model through localized manufacturing positioning. Greenshine New Energy exemplifies North American off-grid specialization for secondary road networks. These three anchors illustrate how procurement code fragmentation favors integrators with regional compliance depth and lifecycle service capabilities.
| Leading Market Players |
|---|
| Cmoonlight |
| First Light Technologies |
| Sunna Design |
| Leadsun |
| Solar Street Lights USA |
| Fonroche Lighting |
| ADNLITE |
| EnGoPlanet |
| Greenshine New Energy |
| Others |
Supply Flow & Price Mechanics
LED-lithium-battery integration tiers separate premium captive-engineering vendors from commodity assembly operations, with that bifurcation compressing margins on standardized pole systems while amplifying pricing power for predictive maintenance bundling in French and Indian municipal contracts.
Pricing Analysis
Short-lead-time premiums dominate municipal procurement, with Indian smart city integrators commanding 15-20% markups for CEA-compliant systems against spot-market Vietnamese battery-integrated poles. Three-tier pricing structure across premium, standard, and economy levels tracks lithium-iron-phosphate chemistry grade, MPPT controller efficiency, and local content certification under India's PLI scheme. Cost compression in monocrystalline modules is intensifying because Gujarat and Tamil Nadu assembly clusters expanded captive wafer capacity. Highway authorities exhibit lowest price sensitivity due to 10-year performance-guarantee contract structures, while provincial Vietnamese buyers negotiate aggressively on battery replacement cycle terms.
Supply Chain Analysis
Dual-sourcing mandates from French and German municipal buyers require qualified panel suppliers from India and Vietnam alongside Chinese lithium-cell providers, complicating vendor qualification for integrators serving EU Green Deal retrofit programs. Raw material dependencies center on polysilicon ingots, lithium carbonate, and phosphor-converted LED dies. Single-source vulnerability concentrates in East Asian battery cell production, where geopolitical friction threatens input cost stability. Distribution runs through regional lighting integrators with captive installation crews, bypassing traditional electrical wholesale channels for pole-mounted system deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar street lighting sits in a technology-transition phase where lithium-iron-phosphate battery chemistry is displacing lead-acid configurations, forcing legacy vendors to requalify electrochemical systems integration capabilities or cede premium municipal contracts.
For Market Incumbents: Lock in predictive maintenance revenue streams by embedding IoT-MPPT convergence into French and Indian performance-guarantee contracts before algorithmic transparency requirements under the EU AI Act harden certification barriers. Backward integration into lithium-iron-phosphate cell assembly in Gujarat or Tamil Nadu clusters defends margin position against Vietnamese pole-integrated battery manufacturers expanding into smart city corridors. For New Entrants and Emerging Players: Launch via off-grid installation specialization targeting Vietnam's provincial highway networks outside Ho Chi Minh City and Hanoi corridors, where electrochemical systems expertise scarcity among public works departments creates first-mover positioning. White-space concentration sits with tropical-humidity-tolerant battery enclosures for Da Nang and Can Tho secondary road retrofits, leveraging direct municipal contracting relationships rather than distributor-dependent channel structures. For Investors and Strategic Acquirers: Re-rating potential sits with captive solar engineering integrators given EU Green Deal procurement exclusions redirecting fossil-dependent retrofit budgets toward autonomous photovoltaic systems across French and German urban corridors. Acquisition target archetypes include regional battery-integrated pole manufacturers with CEA compliance depth and 10-year service contract backlogs. Signal to watch is stabilization of EU AI Act certification pathways, which would unlock delayed procurement in Berlin and Frankfurt smart lighting programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium-Iron-Phosphate Assembly | Captive battery supply secures margin control against East Asian cell price volatility. |
| IoT-MPPT Platform Convergence | Remote dimming protocols enable recurring software revenue from Indian smart city contracts. |
| CEA Compliance Certification Investment | Extended testing protocol mastery compresses bidding windows for highway integrators. |
| Provincial Highway Network Expansion | Da Nang and Can Tho corridors offer underpenetrated off-grid installation demand. |
| EU AI Act Technical File Development | Algorithmic transparency documentation unlocks delayed French and German municipal procurement. |
Methodological Framework
Multi-period observation of module cost compression, battery chemistry displacement rates, and municipal procurement code revisions anchored the trend analysis, supplemented by interviews with lighting integrators, public works procurement officers, electrochemical systems engineers, and MPPT controller manufacturers. Secondary validation drew from CEA technical standards filings, EU Green Deal procurement exclusion notices, FCC Part 15 type-approval databases, and PLI scheme beneficiary disclosures. Bottom-up project pipeline aggregation and top-down infrastructure budget allocation analysis were triangulated against vendor shipment data.
Segment-weighting across product type, installation configuration, end-user procurement sophistication, and connectivity architecture informed value distribution modeling throughout the forecast period. CAGRs were derived from installation volume trajectories and average system value compression curves. Industry-specific inputs included lithium-iron-phosphate cell price indices, monocrystalline panel efficiency degradation rates under tropical humidity conditions, and smart city tender award velocity from Indian municipal corporation disclosures.
Supply chain disruption, regulatory certification delays, and battery chemistry substitution velocity are the dominant revision risks to modeled outcomes. Deviation in East Asian lithium-cell export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Sweden Renewable Energy Market