
 Electric Vehicle Quick Charging Station Market | 2026-2036
Electric Vehicle Quick Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Quick Charging Station Market Insights
A widening capital-intensity divergence between players is reorganizing competitive hierarchies in the Electric Vehicle Quick Charging Station space. Tesla leverages its proprietary Supercharger network and captive vehicle base to dominate highway corridor placement. ABB sustains technology leadership through high-power grid integration systems up to 350 kW. ChargePoint competes across multiple installation types, anchoring its position through software-layer control over charging session management.
An electric vehicle quick charging station is a fixed infrastructure asset that converts grid alternating current to direct current at power ratings typically spanning 50 kW to 350 kW, delivering replenishment to battery electric vehicles in 15 to 45 minutes for commercial and fleet applications. DC fast charging occupies the dominant margin pool due to higher hardware costs and utility interconnection complexity, while ultra-fast charging at 350 kW represents the fastest-expanding technology tier as automakers deploy 800-volt architectures. Fleet charging installations are gaining structural weight as logistics operators electrify depot operations and negotiate demand-charge management with utilities.
The US Federal Highway Administration, the EU Alternative Fuels Infrastructure Regulation, and China's National Energy Administration are shaping deployment mandates, subsidy eligibility, and grid-connection standards that dictate market access timelines. Product certification under IEC 61851 and UL 2594 frameworks determines hardware interoperability and safety compliance across jurisdictions. Stakeholders must monitor utility rate reform proceedings and battery degradation warranties to calibrate charging power curves and site selection criteria.
Market Dynamics
The 800-volt battery architecture migration by automakers is compressing charging session durations and forcing infrastructure upgrades across highway corridors and fleet depots.
Growth Catalysts
- National Energy Administration mandates:China's grid integration requirements for ultra-fast charging along state highway networks are accelerating equipment procurement timelines.
- Logistics electrification:Fleet operators negotiating demand-charge management with utilities are scaling depot-based fast charging installations.
- Inflation Reduction Act tax credits:The US federal incentive structure for charging infrastructure is shortening deployment payback periods across interstate corridors.
Market Restraints
- Copper and silicon carbide cost volatility:Power electronics input prices fluctuate with commodity markets, compressing hardware margins.
- Utility interconnection queues:Grid connection approval timelines in California and Texas extend 18-24 months, delaying site activation.
- Transformer supply concentration:North American electrical equipment manufacturing capacity constraints limit rapid scaling.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives create localized supply chain footholds for charging hardware.
- Vehicle-to-grid convergence:Bidirectional charging protocols unlock grid services revenue streams for station operators.
- Germany's Deutschlandnetz program:Federal fast-charging network tenders offer 15-year operational contracts to infrastructure investors.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized skill sets for 350 kW thermal management and grid synchronization command premium compensation.
- IEC 61851-23 certification timelines:Multi-jurisdiction safety testing extends product launch schedules by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Quick Charging Station Market |
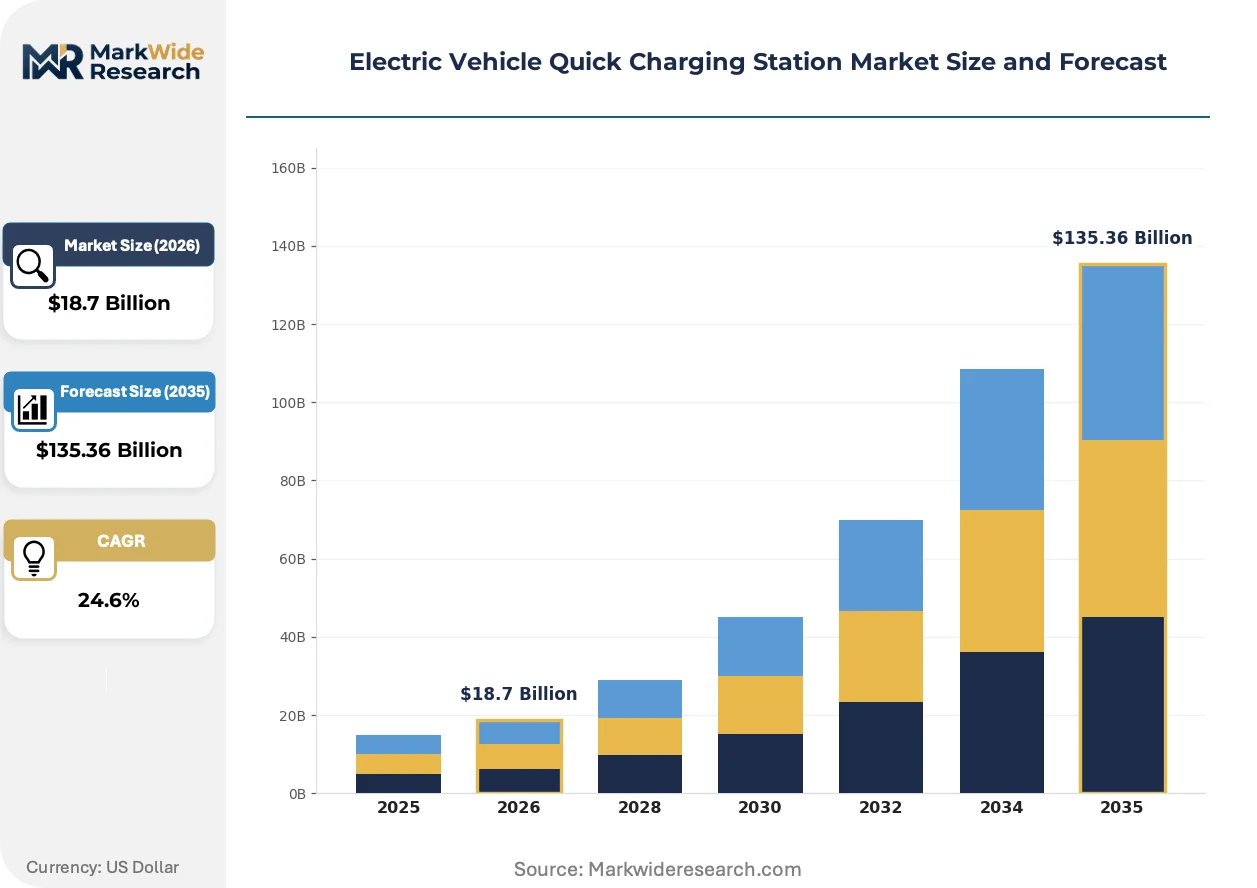
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Technology: DC Fast Charging, AC Charging, Wireless Charging, Ultra-Fast Charging Installation Type: Public Charging, Residential Charging, Commercial Charging, Fleet Charging End User: Individual Consumers, Automotive OEMs, Fleet Operators, Charging Network Providers Power Rating: 50 kW, 150 kW, 350 kW, Others |
| Companies Covered | Tesla, ChargePoint, ABB, EVgo, EVBox, Wallbox, Blink Charging, Electrify America, Star Charge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Quick Charging Station Market Trends and Innovations
Hardware efficiency gains and software-defined charging management are compressing operational costs while enabling new revenue models for station operators.
Silicon carbide power modules are replacing insulated-gate bipolar transistors in DC fast chargers, cutting conversion losses by one-third. Fleet operators in Germany and the Netherlands are specifying SiC-based units for 24-hour depot operations. The technology is miniaturizing thermal management footprints, allowing 350 kW output from cabinet sizes previously housing 150 kW systems.
The EU Alternative Fuels Infrastructure Regulation mandates minimum coverage density along trans-European transport corridors by 2025. Member states must install charging pools at 60-kilometer intervals on core network roads. Highway service area operators in France and Poland are consolidating procurement to meet binding deployment schedules.
Logistics buyers are unbundling charging hardware from software subscriptions, forcing equipment vendors to compete on interoperability. Fleet management platforms now aggregate session data across multiple network operators. This pattern is most pronounced in California, where large trucking operators maintain active relationships with three or more charging service providers.
Electric Vehicle Quick Charging Station Market Segmentation
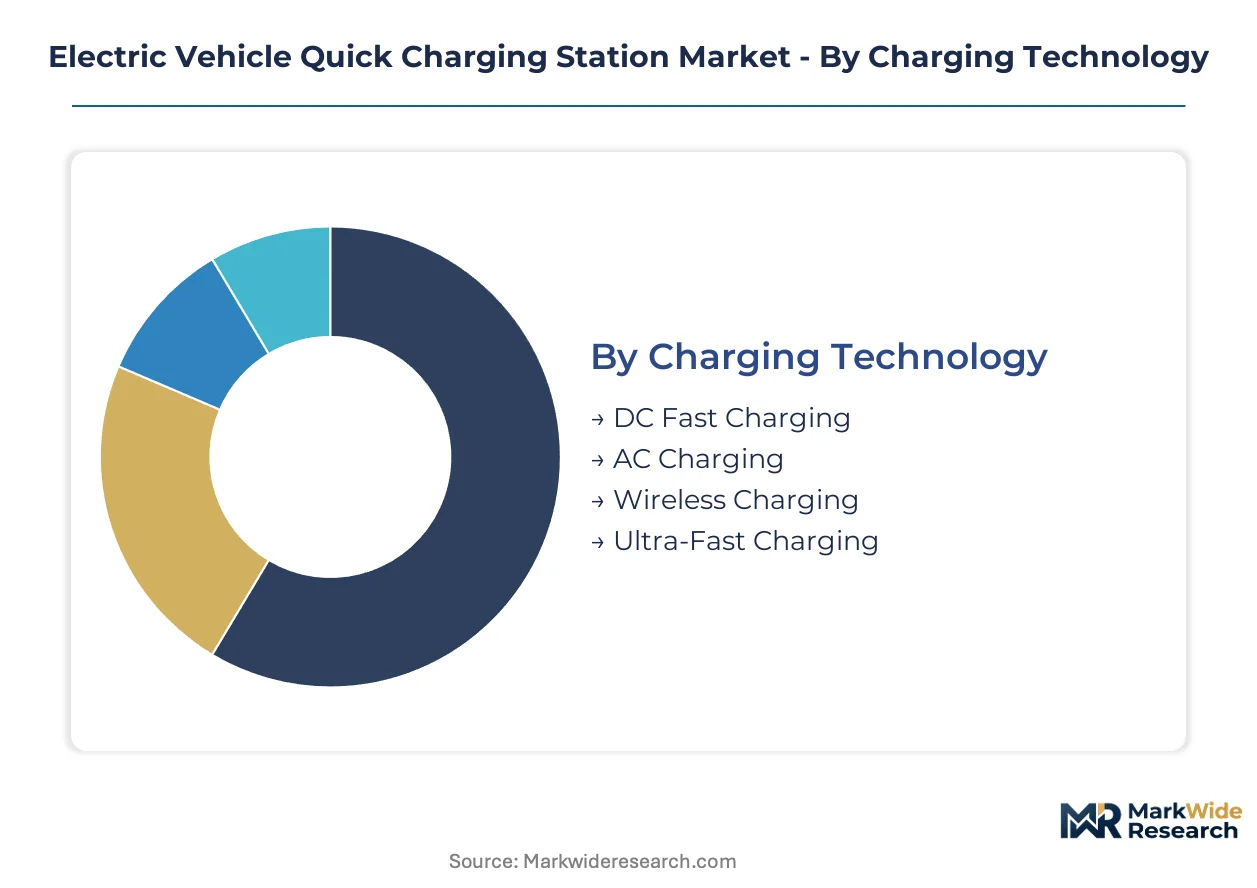
Segmentation in the Electric Vehicle Quick Charging Station market reveals distinct procurement patterns across fleet operators, highway corridor developers, and depot-based logistics buyers. Each segment carries different power density requirements, utility interconnection complexity, and software integration demands that reshape vendor selection criteria.
Charging Technology:
Hardware flows through three primary channel configurations: direct OEM supply for fleet depots, distributor networks for public installations, and integrated EPC contracts for highway corridor projects.
- DC Fast Charging:Converts grid AC to vehicle DC at 50-350 kW through onboard power electronics. Fleet operators in California and Texas negotiate demand-charge management structures around these installations, with utility interconnection queues extending 18-24 months.
- Ultra-Fast Charging:Delivers 350 kW output through liquid-cooled cable systems and 800-volt architectures. Germany's Deutschlandnetz program and China's National Energy Administration mandates are accelerating procurement of these systems along trans-European and national highway networks.
- AC Charging:Lower-power alternating current systems for destination charging with simpler grid connections.
- Wireless Charging:Inductive power transfer systems with embedded roadway or parking pad configurations.
DC Fast Charging dominates installed base. Ultra-Fast Charging is where expansion concentrates.
Installation Type:
Margin profiles diverge sharply across installation categories, with fleet depots capturing operational efficiencies through demand-charge optimization while public highway sites carry higher land and permitting costs.
- Fleet Charging:Depot-based installations serving logistics electrification with 24-hour operational profiles. German and Dutch operators specify silicon carbide power modules for thermal efficiency, negotiating direct utility rate structures.
- Public Charging:Highway corridor and urban destination sites with high utilization visibility. The US Inflation Reduction Act tax credits shorten deployment payback periods across interstate corridors, accelerating site development timelines.
- Commercial Charging:Workplace and retail parking installations with moderate utilization rates.
- Residential Charging:Single-family and multi-unit dwelling installations at lower power ratings.
Fleet Charging captures the steepest expansion trajectory. Public Charging maintains the largest revenue pool.
End User:
Procurement authority is consolidating among entities with direct utility relationships and multi-site operational scale.
- Fleet Operators:Logistics and transit buyers with dedicated depot infrastructure and demand-charge management expertise. California trucking operators maintain active relationships with three or more charging service providers, unbundling hardware from software subscriptions.
- Charging Network Providers:Independent operators aggregating session data across multiple hardware vendors. These entities specify interoperability requirements under IEC 61851 and UL 2594 certification frameworks.
- Automotive OEMs:Vehicle manufacturers securing captive charging access for their customer bases.
- Individual Consumers:Residential and destination charging users with limited procurement scale.
Fleet Operators drive volume concentration. Charging Network Providers are gaining procurement influence fastest.
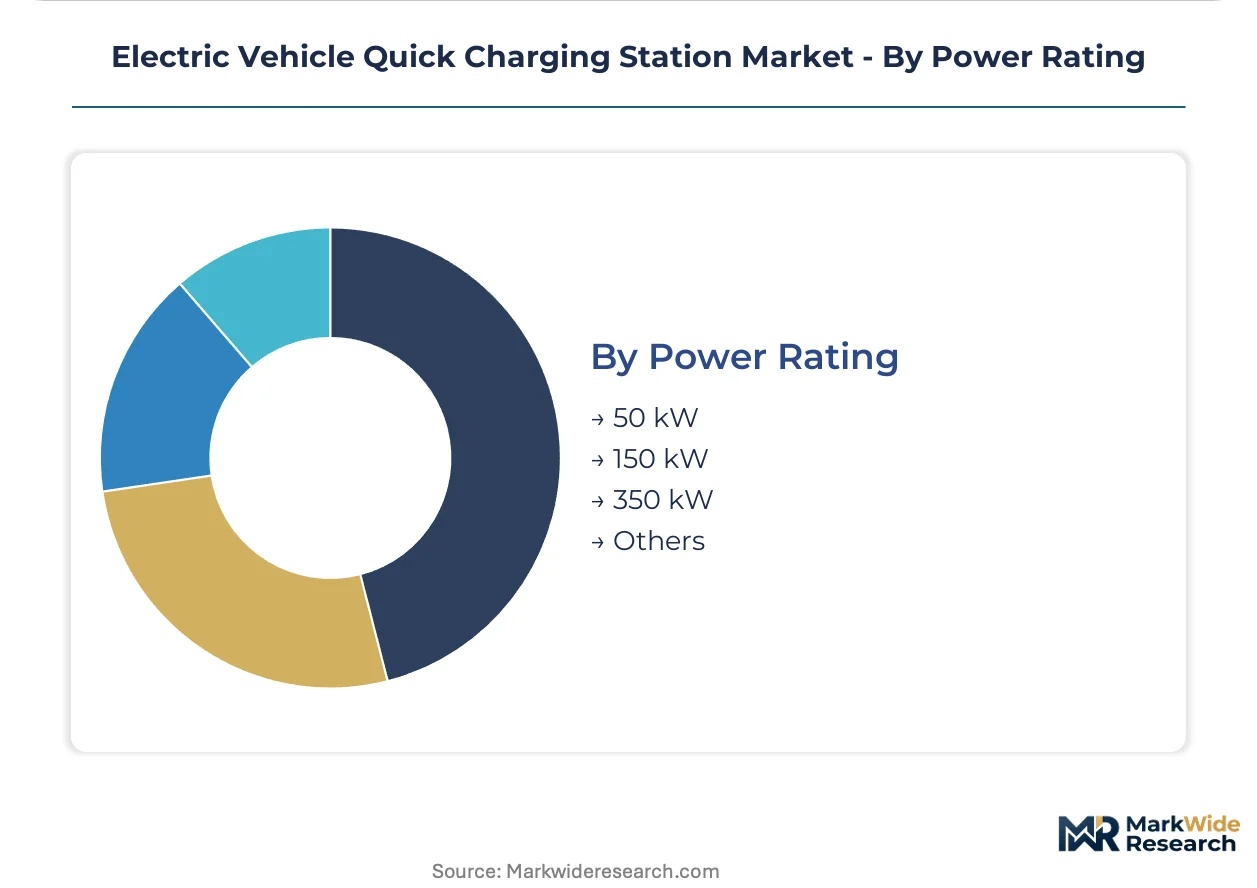
Power Rating:
Site electrical infrastructure and battery architecture compatibility determine power tier selection across customer segments.
- 350 kW:Ultra-high output systems requiring dedicated transformer capacity and liquid-cooled thermal management. China's state highway mandates and European AFIR corridor requirements are accelerating deployment of this tier.
- 150 kW:Mid-tier systems balancing installation cost with session throughput for mixed-use commercial sites.
- 50 kW:Entry-level fast charging with simpler grid connections and lower capital requirements.
- Others:Emerging power classes including 250 kW and 400 kW experimental configurations.
350 kW systems anchor technology roadmaps. 150 kW maintains the broadest addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Electric Vehicle Quick Charging Station market tilts heavily toward Chinese manufacturers, while European and North American operators absorb premium hardware costs and extended utility interconnection timelines.
China
State-backed grid integration mandates from the National Energy Administration are accelerating ultra-fast charging rollouts along national highway networks. The dual carbon goals framework channels subsidy eligibility toward 350 kW systems with liquid-cooled thermal management. Shenzhen and Shanghai anchor manufacturing clusters where silicon carbide power module production is scaling to serve domestic and export demand.
United States
Fleet operators in California and Texas are negotiating demand-charge management structures with utilities as electrification targets tighten. The Inflation Reduction Act tax credits for charging infrastructure are compressing deployment payback periods across interstate corridors. Los Angeles and Dallas-Fort Worth metropolitan areas concentrate depot-based fast charging installations serving logistics electrification.
Germany
The Deutschlandnetz program offers 15-year operational contracts to infrastructure investors deploying trans-European corridor coverage. KBA type-approval requirements and EU Alternative Fuels Infrastructure Regulation mandates are shaping procurement specifications for highway service area operators. Bavaria and North Rhine-Westphalia host industrial clusters where fleet operators specify silicon carbide-based units for 24-hour depot operations.
India
The PLI scheme for auto components is creating localized supply chain footholds for charging hardware manufacturers targeting price-sensitive fleet segments. Central Electricity Authority grid-connection standards are harmonizing with IEC 61851 frameworks to accelerate site activation timelines. Maharashtra and Gujarat industrial corridors are attracting domestic manufacturing investments for power electronics assembly.
Netherlands
Logistics buyers are unbundling charging hardware from software subscriptions, forcing equipment vendors to compete on interoperability metrics. EU AFIR corridor requirements are binding deployment schedules for trans-European transport network coverage. The Eindhoven region and Randstad logistics hubs concentrate fleet charging procurement authority among operators with multi-site operational scale.
Electric Vehicle Quick Charging Station Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated OEM-affiliated networks controlling highway corridor placement while independent hardware vendors compete on power density and grid synchronization capabilities. The market exhibits tiered concentration: a narrow top tier of vertically integrated network operators, a broad mid-tier of equipment specialists, and a fragmented base of regional installation contractors. Two strategic archetypes dominate—captive vehicle-base networks leveraging proprietary connector standards, and open-network hardware vendors competing on interoperability certification. Competitive moves concentrate on strategic partnerships with fleet operators and geographic expansion through distributor networks.
Among the captive-network archetype, Tesla exemplifies vertical integration from vehicle production through charging infrastructure deployment. ABB and ChargePoint occupy positions within the open-network equipment tier, with the former representing European engineering heritage in high-power grid integration and the latter illustrating North American software-layer differentiation across multiple installation types. These three anchors demonstrate how competitive positioning splits between proprietary ecosystem control and interoperability-based market access.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVgo |
| EVBox |
| Wallbox |
| Blink Charging |
| Electrify America |
| Star Charge |
| Others |
Pricing and Supply Chain Analysis
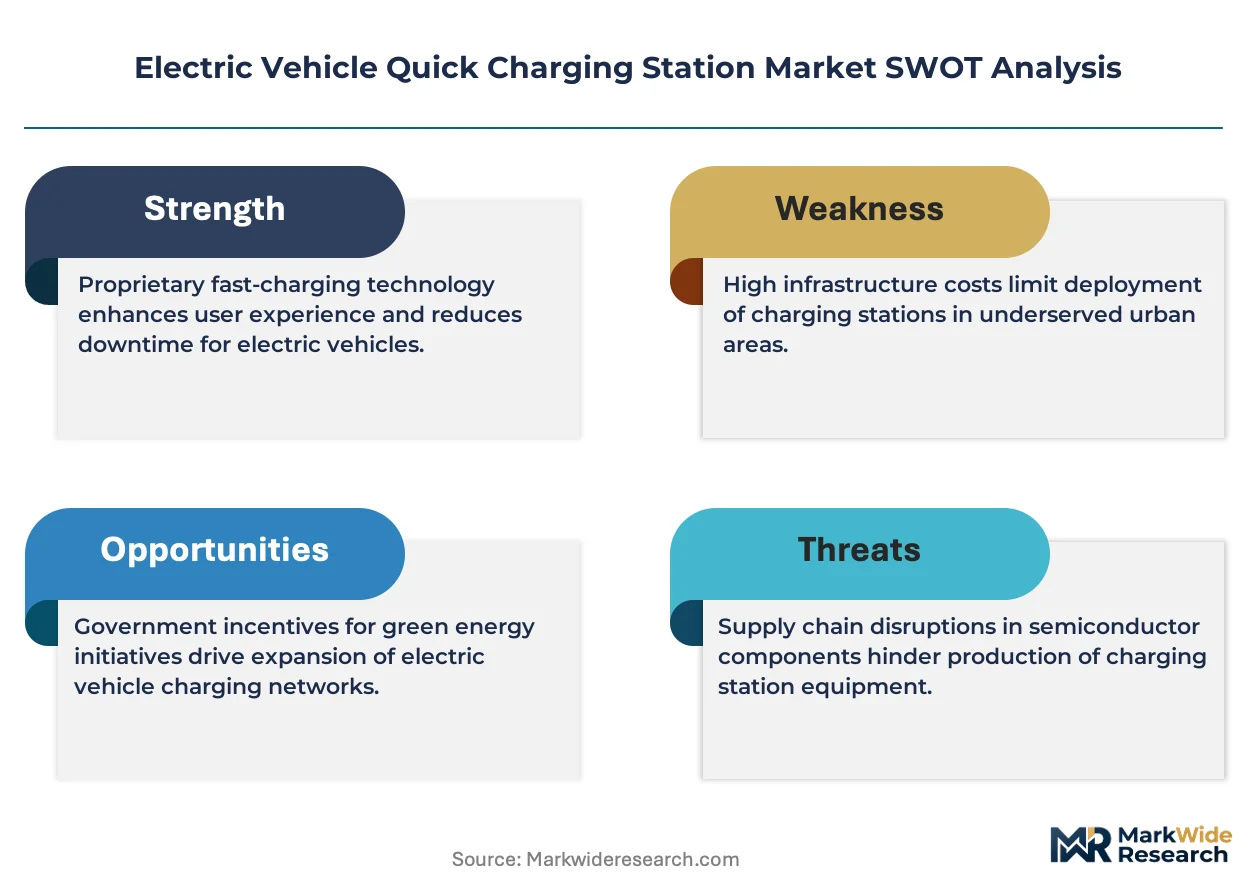
UL 2594 and IEC 61851 certification tiers simultaneously gate supplier qualification and stratify hardware pricing across the Electric Vehicle Quick Charging Station market, with certified vendors commanding configured-to-order premiums while uncertified manufacturers compete on spot pricing for commodity depot installations.
Pricing Analysis
Configured-to-order pricing for 350 kW liquid-cooled systems carries 40-60% premiums over standard 150 kW cabinet configurations. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-based units with demand-charge management software from basic hardware without grid synchronization capabilities. Price differentiation hinges on certification grade and thermal management sophistication. Cost compression in mid-tier hardware is intensifying because Chinese manufacturers are scaling silicon carbide module production. Fleet operators in California exhibit highest price sensitivity due to multi-vendor procurement strategies, while highway corridor developers in Germany show lowest sensitivity given 15-year operational contract security.
Supply Chain Analysis
China and Germany anchor power electronics manufacturing, with Shenzhen and Shanghai clusters scaling silicon carbide wafer processing while Bavaria hosts precision thermal management assembly. The supply chain draws from Chilean copper concentrate, Malaysian semiconductor packaging, and Japanese ceramic substrate suppliers. Single-source vulnerability concentrates in 350 kW liquid-cooled cable systems where two European vendors control liquid cooling IP. Distribution runs through direct OEM supply for fleet depots, distributor networks for public installations, and integrated EPC contracts for highway corridor projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle Quick Charging Station market is entering a cyclical recovery phase as utility interconnection queue clearance accelerates and silicon carbide cost curves bend downward, releasing pent-up fleet electrification demand deferred during transformer supply constraints.
For Market Incumbents: Consolidate technology leadership through captive silicon carbide supply agreements and accelerated UL 2594 certification investments to defend against emerging Chinese hardware vendors. Prioritize backward integration into power module assembly to offset commodity volatility in copper and rare earth inputs. Lock long-term transformer procurement contracts with North American electrical equipment manufacturers before capacity constraints tighten further.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for auto components to establish localized manufacturing footholds serving price-sensitive fleet segments in Maharashtra and Gujarat industrial corridors. Target Germany's Deutschlandnetz tender pipeline where 15-year operational contracts reduce customer acquisition costs. Pursue software-layer differentiation through fleet management platform integration rather than competing head-to-head on hardware power density.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ultra-fast charging infrastructure as 350 kW deployment scales, favoring asset-light software and service providers over heavy hardware manufacturers. Five-to-ten year viability favors operators with locked utility rate structures and multi-site fleet relationships. Target acquisition archetypes include charging network providers with active IEC 61851 interoperability certification and established demand-charge management expertise. Monitor utility interconnection queue clearance velocity as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures thermal efficiency advantages for 350 kW systems against IGBT-based competitors. |
| Utility Rate Structure Lock | Freezes demand-charge exposure for fleet depot operators in California and Texas corridors. |
| IEC 61851-23 Certification Acceleration | Compresses product launch timelines by 8-12 months for European highway corridor eligibility. |
| Fleet Management Platform Integration | Captures software subscription revenue as logistics buyers unbundle hardware from services. |
| Transformer Manufacturing Partnership | Bypasses North American electrical equipment capacity constraints delaying site activation. |
Research Methodology
Initial hypotheses were tested against primary input from charging network operations executives, fleet procurement directors, utility interconnection planners, and power electronics engineering leads and refined through secondary validation against SEC filings from publicly traded infrastructure operators, FERC interconnection queue databases, EU Alternative Fuels Infrastructure Regulation compliance filings, and customs records for silicon carbide module trade flows. Bottom-up installation unit economics were triangulated against top-down market sizing derived from national highway network electrification mandates.
Variance decomposition across the projection horizon isolates volume drivers by charging technology tier, installation type, power rating class, and regional regulatory framework intensity. Segmentation dimensions modeled include DC fast versus ultra-fast charging architectures, fleet depot versus public highway deployment modes, and 50 kW through 350 kW power tiers. CAGRs were derived from installed base growth trajectories calibrated to automaker 800-volt platform rollout schedules and state-backed grid integration mandate timelines.
Material uncertainties — copper and silicon carbide commodity price swings, utility interconnection approval delays, and battery degradation warranty recalibrations — sit outside the modeled envelope. Forecasts reflect assumptions about sustained policy support through the Inflation Reduction Act and Deutschlandnetz program structures. Recalibration cycles align with material shifts in transformer manufacturing capacity and 350 kW system certification velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market