
 Two Wheel Electric Vehicle Charger Market | 2026-2036
Two Wheel Electric Vehicle Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheel Electric Vehicle Charger Market Insights
The price-performance gap between premium and commodity two-wheel electric vehicle chargers is hardening as fast-charging protocols and thermal management systems separate high-reliability units from basic residential models. ABB Ltd leverages its industrial power-electronics heritage to dominate high-voltage DC charging installations for commercial fleets. Gogoro Inc anchors its position through proprietary battery-swapping networks that integrate charger hardware with subscription energy services. Tata Power Company Limited sustains geographic dominance across Indian metropolitan markets through utility-scale charging infrastructure partnerships.
Two-wheel electric vehicle chargers are power-electronic devices that convert grid AC or stored DC energy into controlled current suitable for lithium-ion battery packs, typically operating at 48V–72V with outputs ranging from 0.5kW residential units to 10kW+ fleet-grade systems. Their primary purpose is to restore vehicle range while preserving cell-cycle life through temperature-regulated charge curves and communication protocols like CAN bus or ISO 15118. Fast charger deployments command the steepest margin pools where DC technology enables sub-one-hour replenishment for commercial operators. Smart charging segments are gaining structural momentum as grid-integrated load management and dynamic pricing reshape total cost of ownership for fleet managers. Standard charger categories retain volume leadership in private garage installations across price-sensitive emerging markets.
India's CEA mandates charger interoperability standards under its EV charging infrastructure guidelines, while the BIS certification framework enforces electrical safety and electromagnetic compatibility for domestic sales. The EU F-Gas Regulation indirectly shapes thermal management design choices for charger cooling systems deployed across European markets. Stakeholders must monitor how battery-swapping standards versus conductive charging protocols crystallize into competing regulatory regimes that will determine hardware compatibility and market access rules.
Market Dynamics
The two-wheel electric vehicle charger market is undergoing a protocol fragmentation battle between conductive charging standards and battery-swapping architectures, with commercial fleet operators forcing hardware manufacturers into dual-compatibility investments that reshape R&D allocation and margin structures.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic battery and charger manufacturing are accelerating localized supply chain buildout and reducing import dependency for critical power-electronics components.
- Last-mile delivery electrification:Commercial fleet operators across Southeast Asia are deploying dedicated charging infrastructure at logistics hubs and dark stores, creating guaranteed offtake for high-reliability fleet-grade systems.
- SiC MOSFET adoption:Silicon carbide power semiconductors are enabling higher switching frequencies and thermal efficiency in compact charger designs, particularly for space-constrained urban installations.
Market Restraints
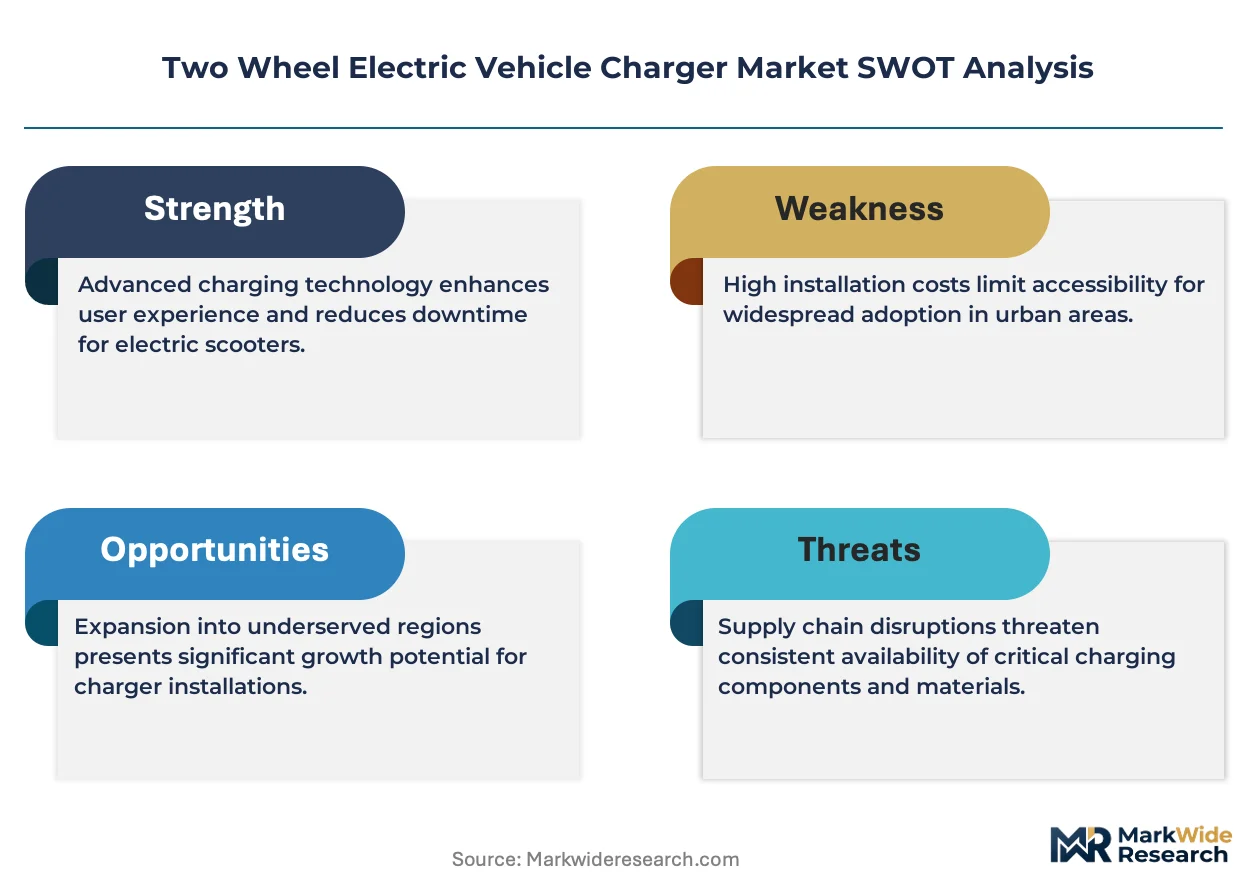
- Copper and rare-earth price volatility:Input costs for magnetics and thermal management components fluctuate with commodity cycles, compressing margins on fixed-price municipal tenders.
- Semiconductor foundry concentration:Power-electronics fabrication capacity clusters in Taiwan and mainland China, exposing charger manufacturers to geopolitical supply disruptions.
- Interoperability certification delays:India's BIS and CEA testing queues create six-to-nine-month approval backlogs that stall product launches and freeze working capital.
Strategic Opportunities
- Vietnam's Red River Delta corridor:Motorcycle electrification mandates in Hanoi and Hai Phong are outpacing installed charging capacity, creating first-mover advantages for network operators.
- Vehicle-to-load integration:Bidirectional charging capabilities that power tools or home appliances during outages are opening premium residential segments beyond basic mobility applications.
- Dynamic tariff optimization:Smart chargers with utility-integrated load management can capture time-of-use arbitrage, transforming hardware into recurring revenue platforms for fleet managers.
Industry Challenges
- Power-electronics engineering talent scarcity:Specialized skills in thermal modeling, EMI compliance, and firmware development for battery management systems command premium compensation that strains mid-tier manufacturers.
- Legacy grid infrastructure retrofit costs:Distribution transformer upgrades and last-mile cabling extensions in dense urban cores require coordination with utility operators that delays site activation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheel Electric Vehicle Charger Market |
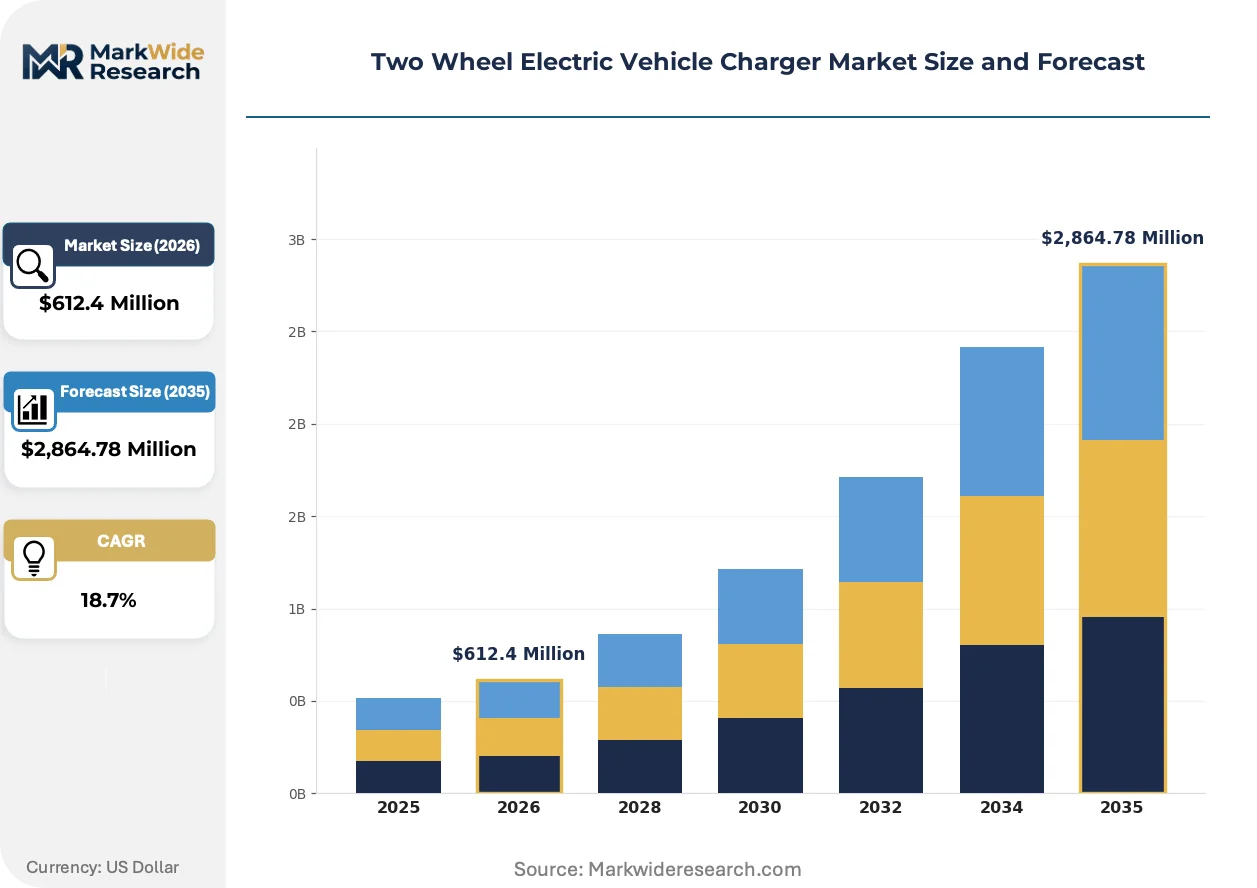
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Charger, Standard Charger, Portable Charger, Home Charger Technology: AC Charging, DC Charging, Inductive Charging, Smart Charging End User: Individual Users, Commercial Fleets, Rental Services, Workshops Installation: On-Street, Off-Street, Private Garages, Public Charging Stations |
| Companies Covered | ChargePoint Inc, ABB Ltd, Delta Electronics Inc, Schneider Electric SE, Tata Power Company Limited, Gogoro Inc, SUN Mobility Pvt Ltd, Ather Energy Pvt Ltd, Ola Electric Mobility Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheel Electric Vehicle Charger Market Trends and Innovations
Power-electronics architecture, regulatory mandates for interoperability, and procurement model evolution are converging to reshape competitive positioning in two-wheel charging infrastructure. Hardware differentiation is compressing toward thermal performance and protocol flexibility rather than raw power output.
GaN-based power conversion is consolidating as the dominant topology for sub-3kW residential chargers, replacing silicon MOSFETs with higher-efficiency wide-bandgap devices that reduce passive component size and enable wall-mounted form factors. Tier-1 suppliers in Taiwan and South Korea have scaled GaN module production for consumer electronics, and this manufacturing base is extending into two-wheel charger designs for cost-sensitive Asian markets. The technology is consolidating supplier tiers by forcing commodity manufacturers to license proprietary driver ICs or exit the residential segment entirely.
The EU F-Gas Regulation is restricting hydrofluorocarbon refrigerants used in liquid-cooled fast chargers above 6kW, compelling manufacturers to redesign thermal management around CO2-based heat pumps or forced-air systems with larger fin arrays. This regulatory pressure elevates engineering costs for European-bound products but creates compliance barriers that protect incumbent industrial power-electronics specialists with existing refrigerant-transition experience. Fleet-grade charger portfolios destined for EU markets are absorbing the bulk of redesign expenditure.
Fleet procurement is fragmenting from single-vendor hardware contracts toward multi-source agreements with performance-based service-level commitments. Large delivery operators in Indonesia and the Philippines now specify uptime guarantees and mean-time-to-repair clauses rather than unit pricing, transferring operational risk to charger providers. This shift concentrates contract awards with vertically integrated vendors capable of nationwide spare-parts logistics and field service networks.
Two Wheel Electric Vehicle Charger Market Segmentation
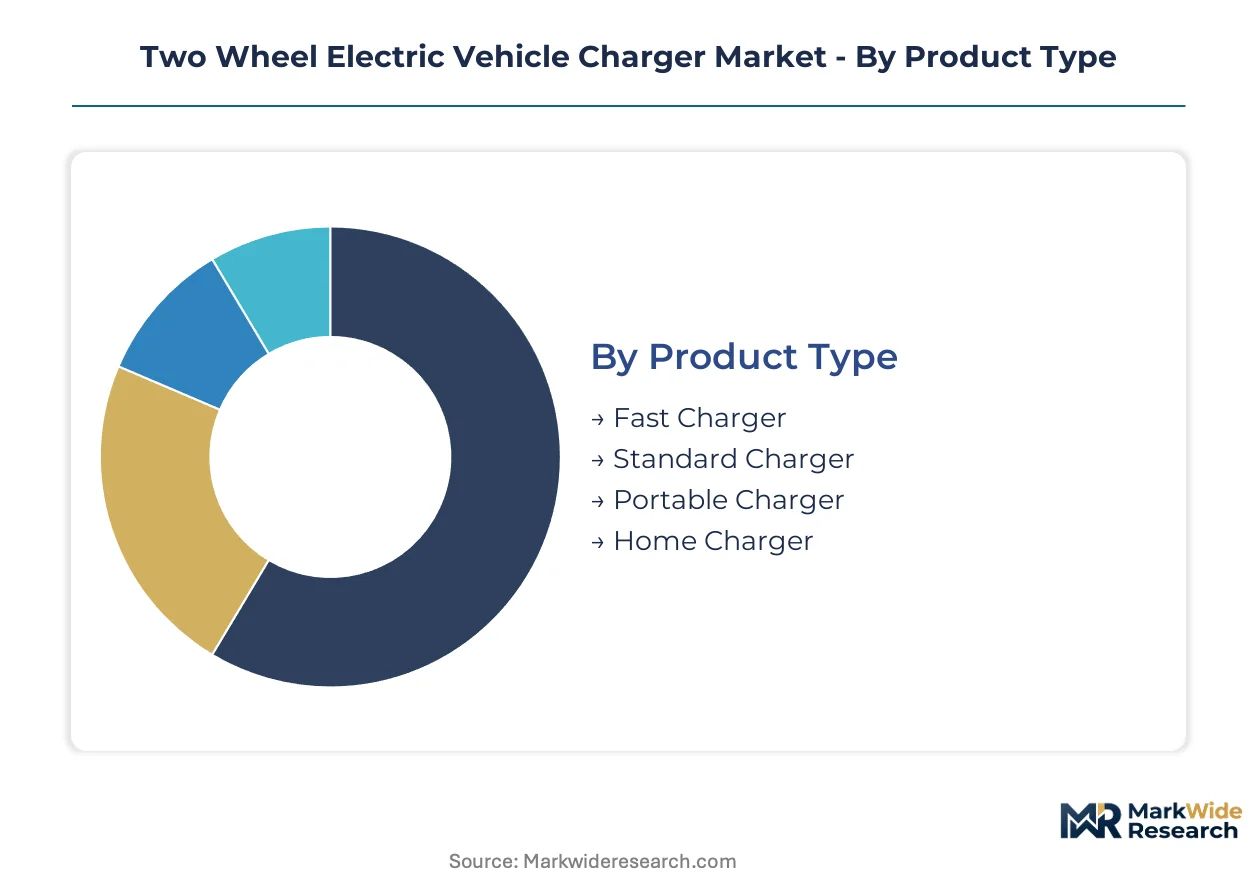
Two-wheel electric vehicle charger segmentation reveals how hardware specifications, deployment contexts, and user economics create distinct margin pools. Upgrade cycles vary dramatically across product tiers, with fleet operators replacing units every 3-4 years versus 7-10 year residential lifespans.
Product Type:
Replacement cycles accelerate where commercial uptime requirements collide with thermal degradation of power electronics, creating aftermarket revenue concentration in high-utilization segments.
- Fast Charger:These units deliver 6kW-10kW+ DC output with active liquid cooling and CAN bus communication for fleet management integration. Demand concentrates in Vietnam's Red River Delta logistics corridors where delivery operators mandate sub-one-hour replenishment cycles.
- Standard Charger:Wall-mounted AC units operating at 0.5kW-3kW dominate residential garage installations across Indian metropolitan markets. BIS certification requirements and copper magnetics costs squeeze margins on fixed-price municipal tenders.
- Portable Charger:Compact 48V-72V converters with interchangeable plug standards serve rental services and intercity commuters. Weight constraints limit thermal management to passive cooling.
- Home Charger:Fixed-installation units with smart metering integration capture time-of-use arbitrage for grid-connected residential users. Form factors prioritize wall-mount compatibility in space-constrained urban housing.
Standard Charger sits at the top of the volume ranking, with Fast Charger climbing the fastest.
Technology:
Cost tier stratification separates premium wide-bandgap semiconductor designs from silicon-based commodity hardware, with procurement patterns diverging between fleet operators and individual consumers.
- AC Charging:Grid-tied rectification with onboard vehicle inverters dominates residential and workplace installations. India's CEA interoperability mandates are accelerating protocol standardization across domestic manufacturers.
- DC Charging:Off-board power conversion enables higher current delivery without vehicle weight penalties. Fleet-grade deployments in Indonesia absorb the bulk of SiC MOSFET adoption.
- Inductive Charging:Wireless power transfer through magnetic coupling eliminates connector wear in rental service environments. Efficiency losses and coil alignment requirements limit deployment to premium segments.
- Smart Charging:Load management firmware with utility communication protocols transforms hardware into grid-integrated assets. Dynamic tariff optimization creates recurring revenue platforms for fleet managers.
AC Charging commands the volume base, while Smart Charging gains share fastest through utility partnership programs.
End User:
Customer type determines procurement structure, with individual consumers prioritizing upfront cost against fleet operators negotiating performance-based service agreements.
- Individual Users:Residential owners purchasing through dealer networks or e-commerce channels. Price sensitivity concentrates demand in standard charger categories with basic safety certifications.
- Commercial Fleets:Last-mile delivery operators in Southeast Asia deploying hub-based charging infrastructure. Uptime guarantees and spare-parts logistics requirements favor vertically integrated vendors.
- Rental Services:Battery-swapping network operators requiring dual-compatibility hardware for conductive and swap-based replenishment. Gogoro's subscription energy model anchors procurement specifications.
- Workshops:Service centers maintaining diagnostic and rapid-charge capabilities for repair workflows. Diagnostic integration with vehicle battery management systems drives protocol requirements.
Individual Users generate the highest unit volumes, with Commercial Fleets expanding most quickly through dedicated infrastructure mandates.
Installation:
Geography of deployment shapes regulatory exposure and grid interconnection complexity, with public infrastructure facing stricter certification queues than private installations.
- On-Street:Curb-side units in Hanoi and Ho Chi Minh City require weatherproofing and vandal-resistant enclosures. Municipal permitting timelines extend deployment cycles.
- Off-Street:Parking facility installations in Indian commercial complexes leverage existing electrical infrastructure. Load management aggregation reduces per-station grid upgrade costs.
- Private Garages:Residential installations across Vietnam's urban corridors face distribution transformer capacity constraints in dense neighborhoods. Utility coordination delays site activation.
- Public Charging Stations:Networked hubs with multiple connector standards serve mixed vehicle fleets. EU F-Gas Regulation compliance elevates thermal management costs for European-bound products.
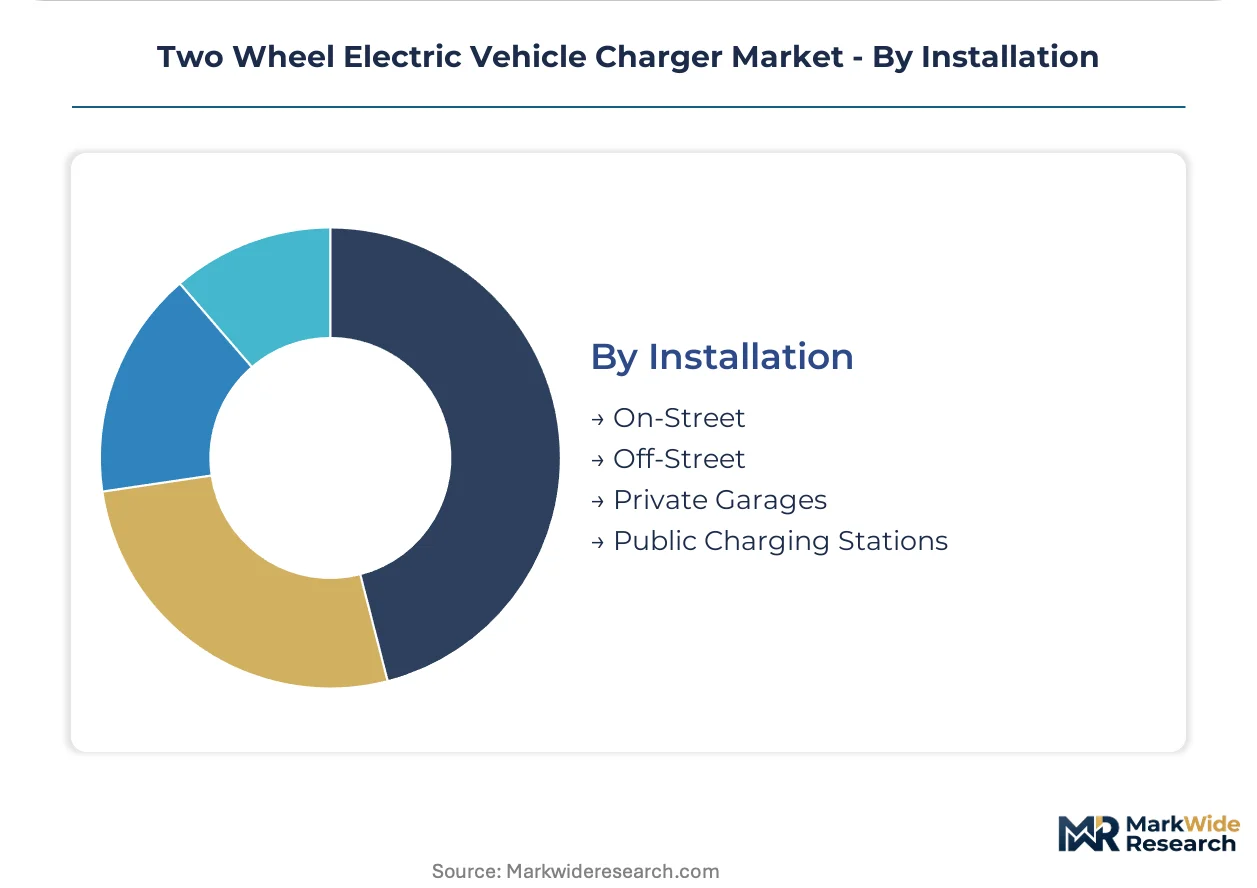
Private Garages lead installed base volume, with Public Charging Stations showing the steepest expansion trajectory through fleet electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power-electronics engineering talent clusters in Taiwan and mainland China anchor charger manufacturing, while Southeast Asian logistics corridors and Indian metropolitan markets concentrate deployment demand for fleet and residential systems.
India
Last-mile delivery operators in Bengaluru and Mumbai are electrifying two-wheeler fleets at pace, creating dedicated charging hub demand. The CEA mandates interoperability standards under EV charging infrastructure guidelines, while BIS certification enforces electrical safety for domestic sales. Maharashtra and Gujarat host manufacturing clusters where PLI scheme incentives are accelerating localized power-electronics production.
Vietnam
Motorcycle electrification mandates in Hanoi and Hai Phong are outpacing installed charging capacity, squeezing network availability for commercial operators. The Ministry of Transport issues technical regulations on electric vehicle infrastructure safety and grid connection protocols. The Red River Delta logistics corridor concentrates fleet-grade fast charger deployments for delivery electrification programs.
China
Silicon carbide foundry capacity in Shenzhen and Shanghai supplies wide-bandgap semiconductors for compact charger designs targeting export markets. MIIT oversees GB standards for conductive charging equipment and electromagnetic compatibility testing. The Yangtze River Delta manufacturing belt houses vertically integrated producers controlling magnetics, thermal management, and firmware development in-house.
Indonesia
Delivery platform operators in Jakarta and Surabaya are specifying uptime-guaranteed charging service contracts rather than hardware purchases. The national energy regulator sets technical standards for public charging station licensing and grid interconnection tariffs. Java's northern coastal logistics belt is absorbing fleet-grade DC charger installations at distribution centers and dark store locations.
Taiwan
GaN module fabrication expertise in Hsinchu Science Park feeds into sub-3kW residential charger designs for cost-sensitive Asian markets. The Bureau of Standards, Metrology and Inspection administers product safety certification for power-electronics equipment. Taoyuan and Tainan manufacturing zones concentrate contract assembly for brands sourcing reference designs from local semiconductor houses.
Two Wheel Electric Vehicle Charger Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the two-wheel electric vehicle charger market, with integrated foundry operators holding cost advantages in magnetics and thermal management while fabless specialists license driver IP for rapid product cycles. The vendor base separates into three tiers: industrial power-electronics heritage players with utility-scale project experience, battery-swapping network operators bundling hardware with subscription energy services, and commodity manufacturers serving price-sensitive residential channels. Dominant competitive moves include backward integration into semiconductor sourcing and strategic partnerships with fleet operators for dedicated infrastructure deployment.
Among industrial heritage players, ABB Ltd exemplifies the high-voltage DC charging installation archetype through its power-electronics legacy. Gogoro Inc occupies a position within the battery-swapping network tier, anchoring proprietary hardware-software integration. Tata Power Company Limited represents the utility-affiliated infrastructure model, leveraging regulatory relationships and grid-scale project execution capabilities across Indian metropolitan markets.
| Leading Market Players |
|---|
| ChargePoint Inc |
| ABB Ltd |
| Delta Electronics Inc |
| Schneider Electric SE |
| Tata Power Company Limited |
| Gogoro Inc |
| SUN Mobility Pvt Ltd |
| Ather Energy Pvt Ltd |
| Ola Electric Mobility Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor sourcing from Taiwan and mainland China anchors cost structures across charger tiers, with foundry relationships determining whether manufacturers capture margin in fast-charging segments or surrender pricing power to commoditized residential units. This upstream control separates fleet-grade suppliers absorbing SiC MOSFET premiums from assembly houses competing on copper magnetics costs alone.
Pricing Analysis
Hardware-software bundling separates subscription-based energy service providers from transactional equipment vendors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and thermal management sophistication, with BIS-certified fleet units commanding substantial premiums over uncertified residential imports. Price differentiation stems from after-sales service commitments and interoperability protocol breadth. Cost compression in standard charger tiers is intensifying because Indian municipal tenders fix unit pricing while copper and rare-earth input costs fluctuate. Individual residential buyers exhibit highest price sensitivity, while commercial fleet operators prioritize uptime guarantees over upfront hardware expenditure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated vehicle-charger pairings, while distributor networks serve fragmented residential replacement markets. Manufacturing concentrates in China's Yangtze River Delta, Taiwan's Hsinchu corridor, and Vietnam's northern industrial zones. Power semiconductors draw from Taiwan Semiconductor and mainland foundries; copper magnetics rest on Chilean and Indonesian concentrate; thermal management components hinge on Japanese aluminum extrusion. Single-source vulnerability in SiC wafer supply exposes charger manufacturers to allocation constraints during automotive demand surges. Distribution runs through utility-affiliated infrastructure partnerships in Indian metropolitan markets and battery-swapping network operators across Southeast Asian logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where India's PLI scheme and CEA interoperability mandates are accelerating domestic manufacturing capacity buildout and reshaping procurement specifications for fleet operators.
For Market Incumbents: Deploy backward integration into GaN and SiC semiconductor sourcing to defend margin position against fabless competitors dependent on foundry allocation cycles. Incumbents should lock long-term supply agreements with Taiwan and mainland Chinese foundries before automotive demand absorbs available wide-bandgap capacity. Certification investment in India's BIS queue acceleration represents a second defensive lever against import-dependent challengers facing six-to-nine-month approval backlogs.
For New Entrants and Emerging Players: Begin with Vietnam's Red River Delta corridor where motorcycle electrification mandates have outpaced installed charging capacity, creating first-mover network operator opportunities before incumbent logistics partnerships crystallize. Battery-swapping compatibility hardware for Gogoro-interoperable deployments offers a specific go-to-market angle that bypasses direct competition with ABB and Delta Electronics in conductive fast-charging infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for regional charging network operators because fleet procurement is fragmenting toward multi-source agreements with performance-based service-level commitments that favor scaled service organizations over pure hardware vendors. Acquisition targets should demonstrate captive utility relationships and spare-parts logistics capabilities. The inflection signal to monitor is BIS certification queue acceleration, which would release frozen working capital and validate domestic manufacturing thesis.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Sourcing | Captive semiconductor supply secures allocation priority during automotive demand spikes. |
| BIS Certification Pre-Approval Investment | Early queue positioning accelerates product launches ahead of import-dependent competitors. |
| Fleet Service-Level Agreement Pivot | Uptime guarantees transfer operational risk and lock multi-year revenue visibility. |
| Battery-Swapping Protocol Licensing | Dual-compatibility hardware captures Gogoro-interoperable network expansion. |
| Utility Partnership Deepening | Tata Power-style regulatory relationships secure grid interconnection priority. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations managers at Indonesian and Vietnamese delivery platforms, power-electronics procurement leads at Indian OEMs, thermal engineering directors at Taiwan semiconductor houses, and utility planning officers at Maharashtra and Gujarat distribution companies. Secondary validation drew from CEA charging infrastructure guidelines, BIS certification databases, MIIT GB standards filings, EU F-Gas Regulation implementation notices, and customs trade data for power-electronics component flows. Bottom-up installation tracking across Hanoi, Bengaluru, Jakarta, and Ho Chi Minh City triangulated against top-down power-electronics production estimates from foundry utilization disclosures.
Segment-weighting approaches distributed value and volume across product type tiers, technology categories, end-user archetypes, and installation contexts. The modeling period incorporated fast charger replacement cycles at three-to-four-year intervals versus seven-to-ten-year residential lifespans, with CAGRs derived from logistics electrification penetration curves and PLI scheme capacity buildout timelines. Forecast inputs included silicon carbide adoption rates in fleet-grade designs and GaN module cost-down trajectories from consumer electronics manufacturing scale.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan Strait semiconductor flows, abrupt battery chemistry shifts altering voltage and current requirements, and municipal permitting timeline compression in Vietnamese urban cores. Forecasts reflect assumptions regarding continued PLI scheme funding and BIS certification throughput capacity. Periodic stress-testing of base assumptions is recommended against copper price volatility and foundry allocation priority shifts toward automotive customers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Charging As a Service Market