
 Monoethanol Amine Market | 2026-2036
Monoethanol Amine Market Size, Share, and Industry Trends Forecast 2026-2036
Monoethanol Amine Market Analysis
Long-term offtake contracts for ethanolamine blends is restructuring how buyers secure volume commitments across the value chain. BASF SE leverages its Ludwigshafen integrated amine complex to sustain captive feedstock advantages. Dow Inc. anchors North American supply through its Freeport, Texas manufacturing base. Nouryon competes on specialty amine derivatives with controlled purity grades for pharmaceutical intermediates.
Monoethanol amine is a primary alkanolamine with the molecular formula C2H7NO, produced via the reaction of ethylene oxide with aqueous ammonia at elevated temperature and pressure; it functions as a versatile intermediate for surfactants, gas treatment solvents, and pharmaceutical synthesis. The ethanolamine blend category captures margin pools from custom ratio formulations tailored to refinery gas sweetening specifications. Detergents applications lead volume consumption due to established supply relationships with household and industrial cleaner manufacturers. Ether amine variants occupy faster-expanding niches in corrosion inhibitor formulations for oilfield chemicals.
The US EPA regulates monoethanol amine under the Toxic Substances Control Act, requiring manufacturers to submit pre-manufacture notices for new chemical modifications. REACH compliance in Europe mandates registration and hazard communication for ethanolamine imports above one tonne annually. China's MEE enforces emission standards on amine production facilities through its integrated permitting system. Stakeholders must monitor regulatory divergence between jurisdictions when designing unified product specifications for cross-border trade.
Market Dynamics
Long-term offtake contracts for ethanolamine blends are restructuring procurement relationships as surfactant formulators seek supply security amid feedstock volatility. The US Gulf Coast petrochemical corridor concentrates production capacity, creating interdependence between ammonia suppliers and amine manufacturers.
Growth Catalysts
- REACH registration mandates:European ethanolamine imports above one tonne annually require ECHA hazard communication, formalizing quality tiers that favor established producers with compliance infrastructure.
- Refinery gas sweetening specifications:Custom ratio ethanolamine blends capture margin pools as US Gulf Coast processors upgrade sulfur recovery units.
- Detergent sector procurement expansion:Household and industrial cleaner manufacturers are locking in multi-year volume commitments to secure surfactant intermediate supply.
Market Restraints
- Ethylene oxide feedstock volatility:Ammonia pricing swings and ethylene oxide availability constrain margin predictability for non-integrated producers.
- US Gulf Coast concentration risk:Hurricane exposure and pipeline dependencies create single-point vulnerability for North American supply.
- MEA substitution by DEA and TEA:Diethanolamine and triethanolamine variants compete in corrosion inhibitor and cement grinding aid applications.
Strategic Opportunities
- Pharmaceutical intermediate purity grades:Controlled-purity amine derivatives for active pharmaceutical ingredient synthesis command premium positioning.
- China MEE emission standard compliance:Integrated permitting system enforcement is consolidating production toward facilities with environmental upgrade capital.
- Ether amine oilfield formulations:Corrosion inhibitor demand from unconventional drilling operations is opening faster-expanding niche consumption.
Industry Challenges
- Process safety engineering talent scarcity:Ethylene oxide handling expertise requirements exceed available trained personnel for facility expansion.
- TSCA pre-manufacture notice timelines:US EPA review periods for new chemical modifications extend product development cycles.
- Cross-border specification harmonization:Divergent purity and labeling requirements between REACH, TSCA, and China's GB standards complicate unified product design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoethanol Amine Market |
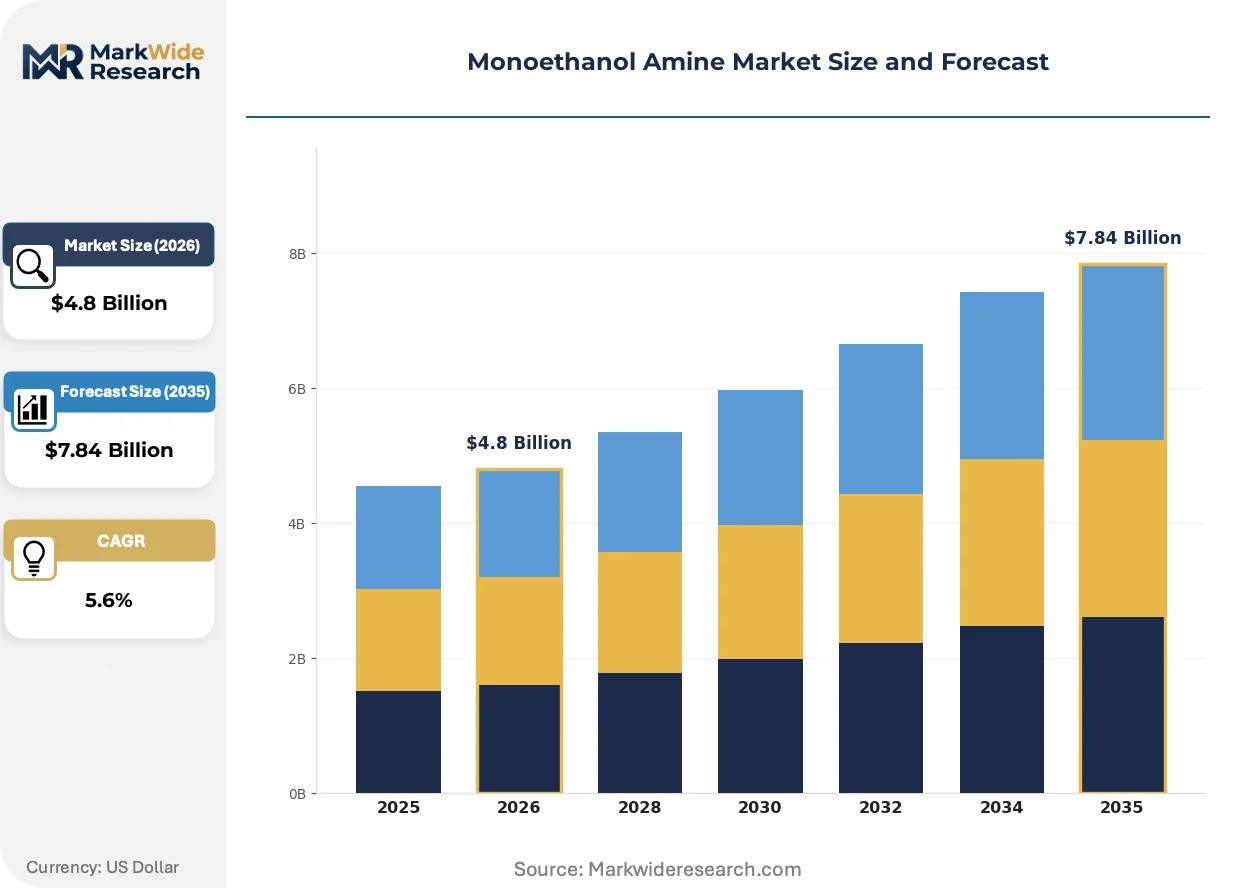
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
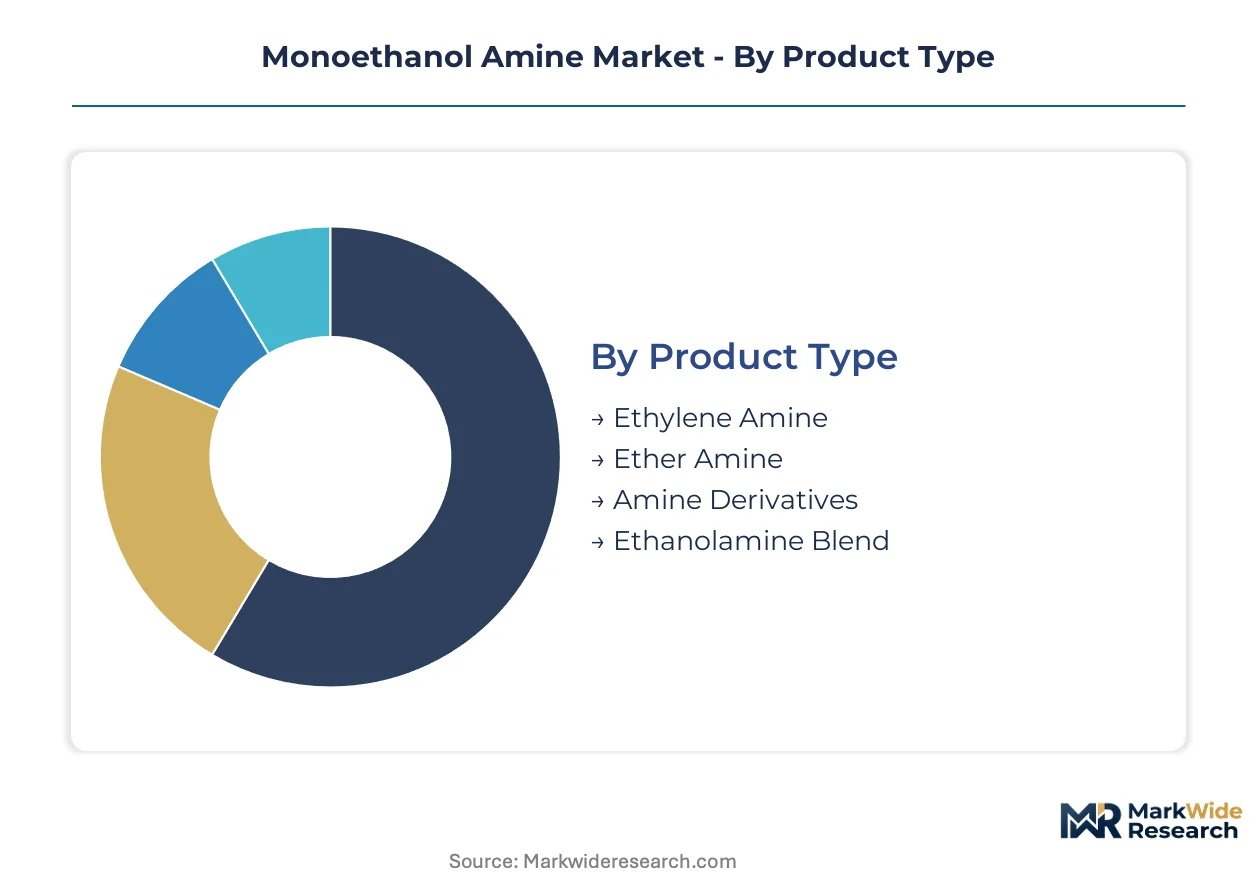
| Segmentation | Product Type: Ethylene Amine, Ether Amine, Amine Derivatives, Ethanolamine Blend Application: Detergents, Pharmaceuticals, Personal Care, Textiles End Use Industry: Agriculture, Construction, Chemicals, Oil & Gas Distribution Channel: Direct Sales, Wholesale, Online, Retail |
| Companies Covered | BASF SE, Dow Inc., Nouryon, Huntsman Corporation, SABIC, INEOS, Sasol Limited, LyondellBasell Industries N.V., Nippon Shokubai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoethanol Amine Market Emerging Trajectories
Process intensification and regulatory alignment are reshaping how monoethanol amine producers configure reaction systems and certify products for multi-jurisdictional trade. Technology vendors and chemical engineers are collaborating on modular unit designs that reduce capital deployment timelines.
Catalytic distillation integration is rewriting process economics for ethylene oxide ammonia reaction systems. Engineering contractors serving US Gulf Coast operators are specifying combined reaction-separation units that cut energy intensity. This convergence is compressing payback periods for capacity additions and favoring producers with in-house catalyst development capabilities.
REACH authorization procedures for ethanolamine category substances are tightening substance volume tracking requirements across European value chains. Downstream formulators must now document amine content in detergent and gas treatment products through the SCIP database. Specialty chemical distributors are restructuring logistics to segregate registered from non-registered inventory streams.
Specification-driven vendor consolidation is concentrating surfactant procurement decisions among fewer household cleaner manufacturers with internal toxicology assessment teams. Long-term supply agreements with fixed purity bands are displacing spot market purchases for standard-grade material. This pattern is most visible in German and Benelux detergent production clusters where ECHA compliance costs have already been absorbed.
Monoethanol Amine Market Segmentation
Monoethanol amine value chains fragment across product chemistry, application performance requirements, and procurement channel economics. Buyers prioritize different specifications depending on whether they formulate surfactants, synthesize active pharmaceutical ingredients, or blend corrosion inhibitors for oilfield operations.
Product Type:
Formulators select amine chemistry based on reactivity profiles, vapor pressure tolerances, and downstream compatibility with existing process equipment.
- Ethanolamine Blend:Custom-ratio formulations combine monoethanolamine with diethanolamine and triethanolamine to meet refinery gas sweetening specifications. US Gulf Coast processors specify these blends for sulfur recovery unit upgrades, locking in multi-year supply agreements with integrated producers.
- Ether Amine:Alkoxylated variants deliver superior hydrophobic-lipophilic balance for oilfield corrosion inhibitor applications. Unconventional drilling operations in Texas and North Dakota are expanding procurement of these specialty grades for high-pressure downhole conditions.
- Ethylene Amine:Higher nitrogen-content structures serve agricultural chemical intermediates and epoxy curing agents.
- Amine Derivatives:Functionalized compounds target pharmaceutical synthesis and personal care formulations with controlled purity requirements.
Ethanolamine blends lead volumes today; ether amine variants are gaining share fastest.
Application:
End-use performance standards dictate purity thresholds, certification requirements, and supplier qualification timelines.
- Detergents:Household and industrial cleaner manufacturers consume standard-grade monoethanolamine for surfactant intermediate production. German and Benelux formulators are consolidating procurement among suppliers with pre-established REACH registration infrastructure.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis demands controlled-purity grades with documented impurity profiles. FDA and EMA filing requirements extend supplier qualification cycles to 18-24 months for new amine sources.
- Personal Care:Cosmetic-grade specifications restrict residual ethylene oxide and 1,4-dioxane levels below 10 ppm.
- Textiles:Fiber processing and dye fixation applications favor amine derivatives with specific pH buffering characteristics.
Detergents anchor current demand; pharmaceutical applications are climbing the fastest.
End Use Industry:
Industry-specific regulatory exposure and capital intensity shape procurement contract structures and inventory holding patterns.
- Oil & Gas:Corrosion inhibitor formulators for upstream operations specify ether amine derivatives with demonstrated performance under CO2 and H2S exposure. Pipeline operators in the Permian Basin are expanding long-term offtake commitments to secure supply amid feedstock volatility.
- Chemicals:Intermediate producers for agrochemicals and water treatment chemicals purchase standard ethanolamine grades through annual volume contracts.
- Agriculture:Pesticide and herbicide synthesis consumes ethylene amine variants with specific nitrogen substitution patterns.
- Construction:Cement grinding aid applications compete between triethanolamine and diethanolamine formulations based on regional cost differentials.
Chemicals processing leads volumes today; oil and gas applications are expanding most quickly.
Distribution Channel:
Channel selection reflects order size, technical service requirements, and geographic proximity to production assets.
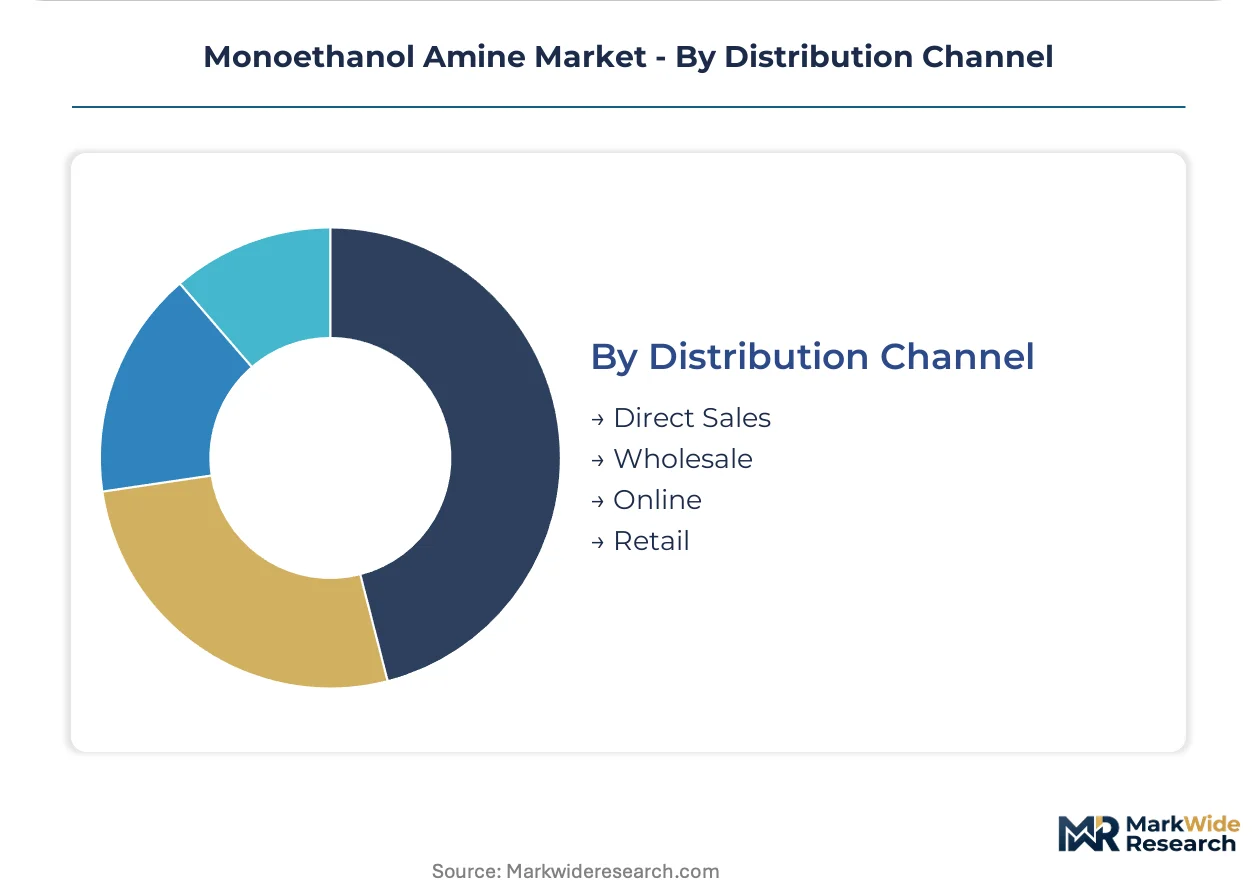
- Direct Sales:Large-volume surfactant and pharmaceutical manufacturers negotiate directly with Ludwigshafen and Freeport production complexes. These relationships include dedicated technical service support and quarterly purity certification.
- Wholesale:Regional distributors aggregate demand from mid-tier formulators lacking volume thresholds for direct producer contracts.
- Online:Specialty chemical marketplaces serve research institutions and pilot-scale operations requiring rapid small-lot fulfillment.
- Retail:Limited to consumer-facing applications through hardware and agricultural supply channels.
Direct sales dominate volume flows; online channels are gaining traction fastest among specialty buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's detergent sector absorbs more ethanolamine volume than France's pharmaceutical corridor, yet both face converging ECHA compliance timelines that favor integrated producers.
United States
Refinery gas sweetening upgrades along the Gulf Coast are locking in multi-year ethanolamine blend contracts. EPA's updated TSCA reporting requirements are extending product certification cycles for new chemical modifications. The Freeport, Texas manufacturing complex anchors North American supply through integrated ethylene oxide feedstock access.
Germany
Household cleaner manufacturers in the Benelux-German cluster are consolidating procurement among REACH-registered suppliers. ECHA's SCIP database mandates are forcing detergent formulators to document amine content across value chains. The Ludwigshafen chemical complex sustains captive feedstock advantages for integrated amine producers.
China
Agricultural chemical intermediates and construction-grade amine derivatives are absorbing expanding domestic capacity. MEE's integrated permitting system is consolidating production toward facilities with environmental upgrade capital. The Yangtze River Delta petrochemical corridor is concentrating new amine capacity near ethylene oxide supply nodes.
Saudi Arabia
Oilfield corrosion inhibitor demand from unconventional drilling operations is expanding ether amine procurement. SABIC's integrated petrochemical complexes leverage captive ethylene feedstock for cost-competitive amine production. The Eastern Province industrial corridor is positioning for export-oriented ethanolamine derivative manufacturing.
Japan
Pharmaceutical-grade amine specifications for active ingredient synthesis are tightening impurity profile requirements. METI's chemical substance management frameworks are aligning with REACH-equivalent hazard communication standards. The Osaka-Kobe chemical cluster maintains specialized capacity for controlled-purity amine derivatives.
Monoethanol Amine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical majors commanding detergent and gas treatment volumes while specialty houses capture pharmaceutical and oilfield niches. The market structure favors producers with captive ethylene oxide supply and established multi-jurisdictional regulatory infrastructure. Three archetypes dominate: integrated petrochemical conglomerates with backward ammonia integration, specialty amine houses focused on controlled-purity grades, and regional blenders serving refinery specifications. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with producers securing long-term offtake commitments to defend position amid feedstock volatility.
Among the integrated majors, BASF SE anchors European supply through its Ludwigshafen amine complex, while Dow Inc. represents the North American production base at Freeport, Texas. Nouryon occupies a position within the specialty tier, competing on derivative purity grades for pharmaceutical and personal care applications. These three exemplify how regulatory compliance infrastructure and captive feedstock access are concentrating competitive advantage among established producers.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Nouryon |
| Huntsman Corporation |
| SABIC |
| INEOS |
| Sasol Limited |
| LyondellBasell Industries N.V. |
| Nippon Shokubai Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade purity certification creates a pronounced bifurcation between premium and commodity monoethanol amine tiers, with this divergence manifesting in both contract pricing structures and the geographic routing of supply chains. REACH-registered European producers command substantial premiums through dedicated technical service relationships, while standard-grade material flows through more transactional wholesale channels anchored to US Gulf Coast production nodes.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade material as domestic producers achieve ethylene oxide integration. Contract-based long-term offtake agreements dominate detergent and gas treatment procurement, with price differentiation driven by certification grade and volume scale commitments. Cost compression in the standard tier is intensifying because of feedstock integration advantages at new Chinese facilities. Household cleaner manufacturers exhibit the highest price sensitivity, while pharmaceutical API synthesizers accept premium positioning for documented impurity profiles.
Supply Chain Analysis
REACH and TSCA qualification requirements gate supply relationships for European and North American pharmaceutical formulators, forcing vendor consolidation toward pre-registered producers. Production concentrates in the United States, Germany, and China, with ethylene oxide, ammonia, and catalyst systems serving as critical input dependencies. Single-source vulnerability runs through the US Gulf Coast corridor, where hurricane exposure threatens concentrated amine capacity. Distribution runs through direct sales relationships for large-volume surfactant and pharmaceutical manufacturers, supplemented by regional wholesale aggregators serving mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monoethanol amine markets offer margin expansion pathways through captive feedstock integration and pharmaceutical-grade certification premiums, with ethylene oxide backward integration emerging as the decisive cost-down driver across competitive tiers.
For Market Incumbents: Cement supply security through long-term ammonia offtake agreements and captive ethylene oxide capacity additions in the US Gulf Coast or Yangtze River Delta corridors. Defend against MEA substitution by DEA and TEA variants through formulation partnerships with refinery gas sweetening operators. Prioritize ECHA SCIP database compliance infrastructure to maintain access to German and Benelux detergent procurement consolidation. For New Entrants and Emerging Players: Begin with ether amine specialty grades for oilfield corrosion inhibitor applications, where unconventional drilling demand in the Permian Basin and North Dakota offers faster penetration than commoditized detergent intermediates. Target direct sales relationships with mid-sized pharmaceutical API manufacturers seeking alternative qualified suppliers to established Ludwigshafen and Freeport incumbents. Pursue joint development agreements with catalytic distillation technology vendors to compress capital deployment timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where environmental upgrade capital requirements under China's MEE integrated permitting system force smaller producers toward exit. Position acquisition screening around specialty amine houses with established pharmaceutical-grade purity capabilities and REACH registration infrastructure, as these assets command durable premium positioning. Watch for inflection signals in ethylene oxide feedstock volatility, which would accelerate vertical integration advantages among integrated petrochemical majors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock access at Freeport and Ludwigshafen insulates margin from ammonia pricing swings. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA filing support commands 18-24 month supplier qualification premiums in API synthesis. |
| Long-term Supply Agreement with Refinery Operators | US Gulf Coast sulfur recovery unit upgrades lock in multi-year ethanolamine blend volume commitments. |
| Catalytic Distillation Technology Adoption | Combined reaction-separation units cut energy intensity and compress capacity addition payback periods. |
| Joint Venture in Yangtze River Delta | Proximity to Chinese ethylene oxide nodes and MEE-compliant environmental infrastructure secures Asia-Pacific positioning. |
Methodological Framework
Multiple input streams — executive interviews with amine plant managers and surfactant procurement leads, trade data reconciliation, and SEC filing analysis — were reconciled to construct supply-demand balances across the value chain. Primary fieldwork encompassed discussions with technical R&D directors at integrated petrochemical complexes, distribution channel partners serving German detergent clusters, and regulatory affairs specialists navigating ECHA SCIP mandates. Secondary validation drew from customs records, ACC and Cefic industry reports, and EPA TSCA pre-manufacture notice filings. Bottom-up capacity and consumption estimates were triangulated against top-down trade flow analysis.
Segment-level projections across the modeling period applied differential growth assumptions by product chemistry, application performance tier, and regional regulatory cluster. Pharmaceutical-grade amine derivatives, ether amine oilfield formulations, and standard detergent intermediates were modeled as distinct demand streams with varying price elasticity profiles. CAGRs were derived from ethylene oxide feedstock availability trajectories, refinery capital expenditure cycles for gas sweetening upgrades, and REACH authorization timeline impacts on European import flows.
Caveats apply where ethylene oxide supply disruptions, hurricane-related production outages, or REACH substance volume tracking requirement changes could materially shift the outlook. Forecasts reflect assumptions regarding sustained shale gas economics supporting US Gulf Coast feedstock competitiveness and continued MEE enforcement consolidation in China. A model refresh is warranted upon material change in ethylene oxide-ammonia spread dynamics or ECHA authorization list revisions affecting ethanolamine category substances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Global Odor Control Systems Market