
 Global Sodium Lignosulfonate Market | 2026-2036
Global Sodium Lignosulfonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Lignosulfonate Market Foresight
Synthetic naphthalene sulfonate is expanding its displacement by sodium lignosulfonate in concrete admixture formulations, driven by cost volatility in petrochemical feedstocks and carbon footprint pressures. Borregaard LignoTech leverages its integrated forestry-chemical operations in Norway to sustain premium-grade powder output. Qingdao New World Material Co. Ltd. anchors volume supply through backward integration into regional pulp mills.
Sodium lignosulfonate is a water-soluble anionic polyelectrolyte derived from sulfite pulping of lignin, typically containing 4-8% sulfur by weight and functioning primarily as a dispersant, binder, and chelating agent across industrial processes. Its molecular weight distribution of 1,000-50,000 g/mol governs performance in cement particle dispersion and dye stabilization. Powder formulations command the largest revenue share due to superior shelf stability and freight efficiency, while liquid grades capture faster growth in ready-mix concrete operations where on-site dilution reduces handling costs. The construction end-use industry generates the deepest margin pools, though oil drilling applications in shale basins are gaining traction as operators seek biodegradable thinning agents.
EPA guidelines on construction runoff and EU REACH restrictions on formaldehyde-releasing admixtures are redirecting specification sheets toward bio-derived dispersants. China's MEE enforcement of dual carbon goals is tightening emissions at sulfite pulping facilities, constraining raw material availability for non-integrated producers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate grade certification requirements and supply chain reconfiguration needs.
Market Dynamics
Carbon accounting mandates across construction supply chains are compressing specification windows for petrochemical-derived admixtures, redirecting procurement authority toward bio-based dispersants with verified lifecycle footprints. This structural pivot is reshaping competitive positioning among sulfite pulping derivatives.
Growth Catalysts
- EU REACH formaldehyde restrictions:Construction formulators in Germany and France face mandatory substitution timelines for synthetic superplasticizers, accelerating sodium lignosulfonate qualification in ready-mix applications.
- Shale drilling fluid biodegradability mandates:EPA guidelines on drilling waste disposal in the Permian Basin are forcing operators toward lignin-derived thinning agents that meet toxicity reduction thresholds.
- China's dual carbon enforcement:MEE emissions audits at sulfite pulping facilities are tightening raw material flows, concentrating supply among integrated forestry-chemical operators with captive lignin streams.
Market Restraints
- Softwood pulp price volatility:Hemlock and spruce feedstock costs fluctuate with Canadian lumber export quotas, squeezing margin stability for non-integrated sodium lignosulfonate producers.
- Performance ceiling in high-strength concrete:Molecular weight distribution limits of standard-grade powders restrict adoption in UHPC formulations above 150 MPa, ceding share to polycarboxylate ethers.
- GB standard certification timelines:China's mandatory product registration for construction chemicals extends commercialization cycles by 18-24 months for imported grades.
Strategic Opportunities
- India's infrastructure PLI schemes:Government production-linked incentives for domestic specialty chemicals are opening import substitution pathways for lignosulfonate admixture manufacturing.
- Oilfield nanofluid convergence:Hybrid formulations combining sodium lignosulfonate with graphene oxide dispersants are penetrating deepwater drilling contracts in Brazil's pre-salt basins.
- CSRD supply chain disclosure rules:EU corporate sustainability reporting mandates are creating procurement preference for bio-based dispersants with auditable carbon footprints across construction value chains.
Industry Challenges
- Sulfite pulping chemist scarcity:Retirement waves among process engineers with lignin extraction expertise are constrering technical service capacity for grade customization.
- Multi-jurisdiction certification fragmentation:Divergent admixture standards between EPA, ECHA, and China's SAMR are forcing parallel testing regimens that duplicate R&D expenditure.
- Legacy concrete mixer fleet incompatibility:Older batching plants in emerging markets lack precision dosing equipment for powder dispersants, requiring liquid formulation development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Lignosulfonate Market |
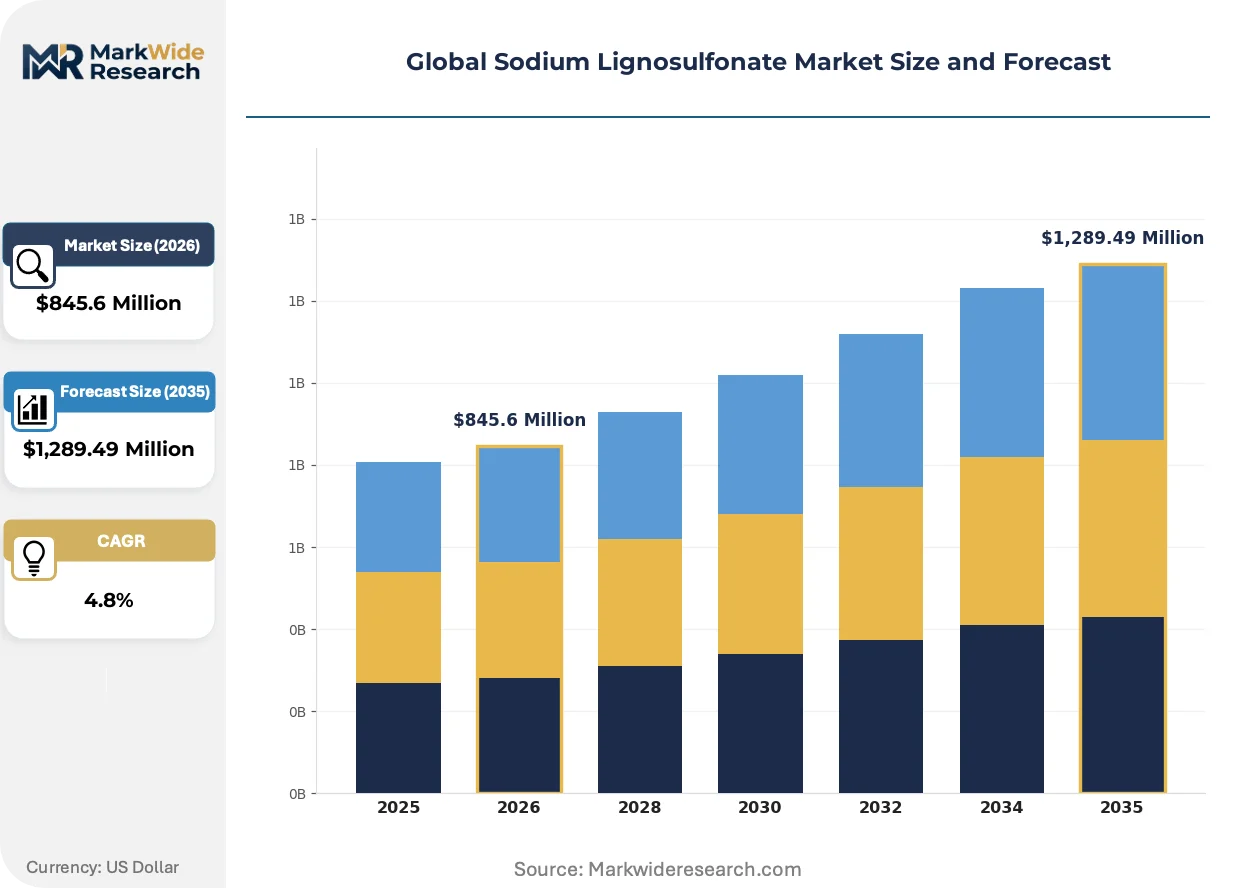
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,289.49 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granular, Pellet Application: Animal Feed, Concrete Additive, Dust Control, Oil Drilling, Leather Processing Form: Standard Grade, Technical Grade, Industrial Grade, Chemical Grade End Use Industry: Construction, Agriculture, Energy Production, Pulp & Paper |
| Companies Covered | Nippon Paper Industries Co. Ltd., Tembec Inc., Borregaard LignoTech, Qingdao New World Material Co. Ltd., Rayonier Advanced Materials, Sappi, Domsjö Fabriker AB, Green Agrochem, Shenyang Xingzhenghe Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Lignosulfonate Market Shifts & Advancements
Specification engineering is displacing commodity trading as the dominant commercial logic, with performance guarantees and carbon disclosure documentation now preceding price negotiation in major construction tenders.
Ultrafiltration fractionation of lignosulfonate molecular weights is expanding into high-value niche applications. Specialty grades with narrow 5,000-15,000 g/mol distributions command premium positioning in ceramic suspension and pesticide formulation markets. Japanese dye manufacturers are adopting these refined fractions for azo pigment stabilization, compressing reliance on synthetic naphthalene dispersants.
EPA construction runoff guidelines are tightening sediment control mandates at federal infrastructure sites. General contractors on Department of Transportation projects must document biodegradable admixture content in stormwater management plans. Sodium lignosulfonate formulations are capturing specification share in bridge deck and highway paving contracts across the southeastern United States.
Direct mill-to-mixer distribution contracts are consolidating procurement authority among national ready-mix chains. Large concrete producers in Texas and Florida are bypassing traditional chemical distributors to secure volume commitments with integrated pulp processors. This channel compression is squeezing regional admixture blenders and forcing specialization in technical service rather than logistics.
Global Sodium Lignosulfonate Market Segmentation
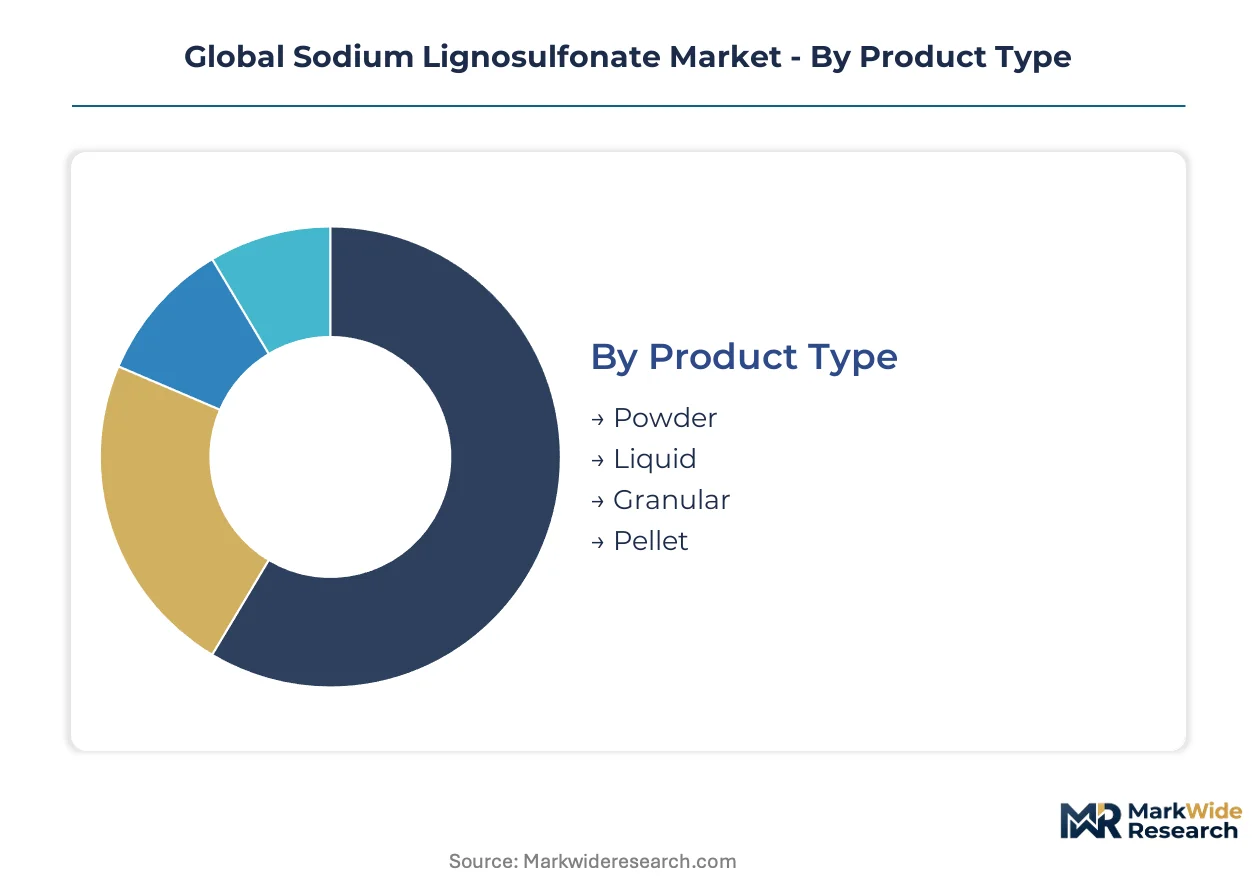
Formulation chemistry and logistics economics split procurement decisions across sodium lignosulfonate grades. Buyers weigh shelf stability against dilution costs, while regulatory compliance varies sharply by end-use application.
Product Type:
Freight economics and batching infrastructure drive format selection more than molecular performance.
- Powder:Spray-dried formulations with moisture content below 8% dominate long-haul distribution to ready-mix concrete plants. Superior shelf stability supports inventory consolidation at depots in Germany and Texas. Volume sits with powder; growth tilts toward liquid.
- Liquid:Aqueous solutions at 40-50% solids concentration eliminate dust exposure and enable direct pump injection at batching sites. Adoption is climbing fastest among urban concrete producers in São Paulo and Mumbai seeking automated dosing compatibility.
- Granular:Intermediate moisture content suits regional feed compounders requiring dust-free handling without dilution infrastructure. Brazilian poultry integrators specify granular for amino acid complexing in vitamin premixes.
- Pellet:Compressed lignosulfonate with binders targets dust suppression applications on mining haul roads in Western Australia's Pilbara region.
Format choice tracks batching plant vintage and labor cost structures rather than performance premiums.
Application:
Specification intensity and certification burden separate commodity buyers from specialty formulators.
- Concrete Additive:Dispersant action at 0.2-0.5% cement weight enables water reduction in C25-C50 strength grades. German ready-mix chains specify sodium lignosulfonate for federal highway contracts under REACH-compliant tender requirements. Volume concentrates here; expansion is steepest in oil drilling.
- Oil Drilling:Biodegradable thinning agents for water-based mud systems meet EPA toxicity thresholds in Permian Basin disposal permits. Deepwater operators in Brazil's pre-salt fields qualify lignosulfonate for synthetic-based mud dilution.
- Animal Feed:Pellet binding and nutrient encapsulation serve compound feed mills in Iowa and Shandong province, though amino acid competition from synthetic methionine constrains pricing power.
- Dust Control:Surface binding on unpaved roads and mine tailings captures seasonal demand from Australian coal terminals and Chilean copper haul routes.
- Leather Processing:Tanning auxiliary applications in Italian tanneries face substitution pressure from synthetic polymers with lower COD discharge profiles.
Construction additive volume anchors revenue; drilling fluid qualification opens the steepest expansion trajectory.
Form:
Impurities tolerance and documentation depth define procurement tiers across industrial buyers.
- Standard Grade:Unfractionated molecular weight distribution with 4-8% sulfur content serves bulk concrete and feed applications where performance variance is manageable. Chinese sulfite pulping mills in Shandong and Heilongjiang anchor supply.
- Technical Grade:Ultrafiltered fractions with reduced ash and carbohydrate residues command specification in ceramic suspensions and pesticide dispersants. Japanese dye manufacturers source technical grade for azo pigment stabilization.
- Industrial Grade:Intermediate purity for dust suppression and road stabilization where color consistency and heavy metal limits are secondary to unit cost.
- Chemical Grade:Refined specifications with batch certificates for pharmaceutical excipient and food additive applications in EU-regulated markets.
Standard grade captures shipment tonnage; technical grade captures margin expansion.
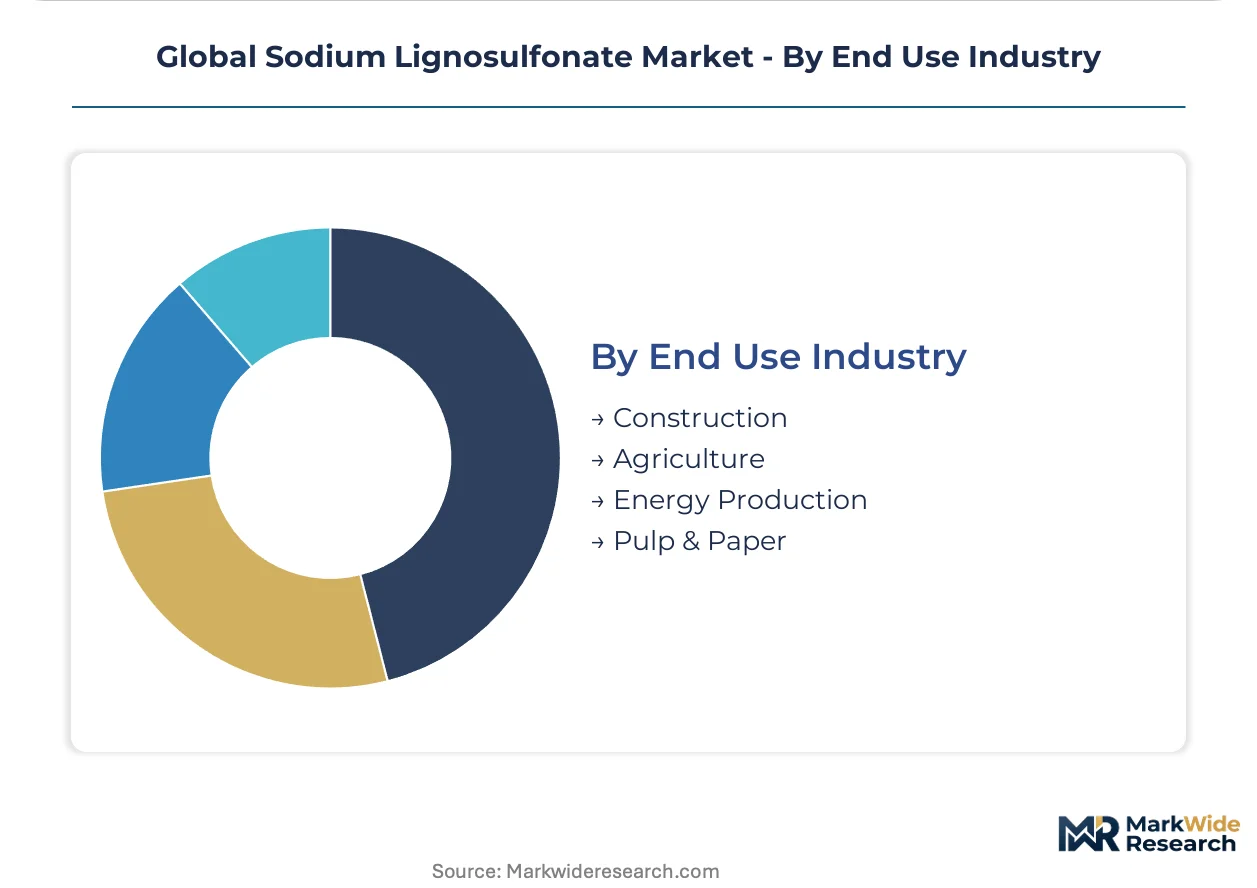
End Use Industry:
Capital cycle timing and sustainability disclosure mandates reshape sector prioritization.
- Construction:Federal infrastructure spending in the United States and China's highway expansion sustain admixture volume. CSRD reporting requirements in France and the Netherlands are embedding lifecycle carbon data into ready-mix procurement specifications.
- Agriculture:Feed pellet binding and soil conditioning drive seasonal offtake from compounders in the US Corn Belt and Brazilian soy frontier.
- Energy Production:Oilfield drilling and coal dust suppression generate project-based demand tied to exploration budgets and mining output cycles.
- Pulp & Paper:Captive consumption by integrated sulfite mills for internal dispersant use limits merchant market exposure.
Construction absorbs the heaviest volume flows; energy applications show the most volatile growth swings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the heaviest demand flows for sodium lignosulfonate, absorbing volume from its infrastructure pipeline and dominant pulp processing base. Four additional markets shape regional dynamics through distinct regulatory and industrial configurations.
China
Massive highway expansion and high-speed rail construction sustain admixture consumption across C25-C50 concrete grades. MEE enforcement of dual carbon goals tightens emissions at Shandong and Heilongjiang sulfite pulping facilities. Qingdao anchors merchant supply through backward integration into regional pulp mills.
United States
Federal infrastructure spending on bridge decks and highway paving drives specification share in the Southeast and Texas markets. EPA construction runoff guidelines mandate biodegradable admixture documentation on Department of Transportation projects. Houston and Dallas-Fort Worth ready-mix chains consolidate procurement through direct mill contracts.
Germany
REACH formaldehyde restrictions force mandatory substitution timelines for synthetic superplasticizers in ready-mix applications. Federal highway tenders embed lifecycle carbon data into procurement specifications. The Rhine-Ruhr industrial corridor concentrates formulation expertise among integrated forestry-chemical operators.
Brazil
Pre-salt deepwater drilling contracts qualify lignosulfonate for synthetic-based mud dilution as operators meet biodegradability mandates. São Paulo urban concrete producers adopt liquid formulations for automated dosing compatibility. The southeastern mining belt generates seasonal dust suppression demand from Pilbara-style haul routes.
India
Government production-linked incentives for domestic specialty chemicals open import substitution pathways for lignosulfonate admixture manufacturing. BIS certification requirements extend commercialization cycles for construction chemical registration. Mumbai and Delhi-NCR infrastructure projects absorb powder formulations through regional distributors.
Global Sodium Lignosulfonate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated forestry-chemical operators commanding premium-grade positioning while regional pulp mills anchor volume supply. Three archetypes define competitive structure: captive lignin processors with sulfite pulping integration, merchant chemical specialists with fractionation capabilities, and regional distributors with logistics consolidation. M&A activity concentrates among pulp processors seeking downstream chemical assets, while capacity expansion focuses on ultrafiltration fractionation for technical-grade output.
Within the integrated processor tier, Borregaard LignoTech exemplifies captive supply chain configuration through its Norwegian forestry-chemical operations, while Nippon Paper Industries Co. Ltd. occupies a position among Asia-Pacific pulp-based producers. Qingdao New World Material Co. Ltd. anchors Chinese volume supply. These three represent distinct geographic and structural archetypes rather than direct competitors across identical specification tiers.
| Leading Market Players |
|---|
| Nippon Paper Industries Co. Ltd. |
| Tembec Inc. |
| Borregaard LignoTech |
| Qingdao New World Material Co. Ltd. |
| Rayonier Advanced Materials |
| Sappi |
| Domsjö Fabriker AB |
| Green Agrochem |
| Shenyang Xingzhenghe Chemical Co. Ltd. |
| Others |
Supply & Pricing Matrix
CSRD supply chain disclosure mandates across EU construction value chains are forcing specification engineers to document lifecycle carbon footprints before price negotiation, compelling integrated forestry-chemical operators to capture premium positioning while squeezing merchant traders on margin.
Pricing Analysis
Volume concentrates in standard-grade powder shipments to Chinese and German ready-mix concrete plants, while margin expansion accrues to ultrafiltered technical grades for Japanese dye stabilization and ceramic suspension applications. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and molecular weight fractionation depth, with REACH-compliant documentation commanding substantial premia. Pricing pressure stems from softwood pulp feedstock volatility tied to Canadian lumber export quotas, compressing returns for non-integrated producers. Regional distributors in emerging markets exhibit highest price sensitivity due to legacy batching plant incompatibility with precision dosing equipment.
Supply Chain Analysis
India's PLI scheme domestic-content requirements are redirecting sourcing patterns toward locally manufactured admixture grades, disrupting traditional import flows from Chinese sulfite pulping mills. Supply concentrates in China, Norway, and the United States, with captive lignin streams from integrated forestry-chemical operations anchoring premium-grade output. Raw material flows draw from hemlock and spruce feedstock, sulfite pulping chemicals, and ultrafiltration membrane systems. Single-source vulnerability persists at Shandong and Heilongjiang pulping facilities where MEE emissions audits constrain merchant market availability. Distribution runs through direct mill-to-mixer contracts consolidating procurement authority among national ready-mix chains in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where regulatory certification burdens and feedstock integration requirements are systematically eliminating non-specialized traders without fractionation capabilities or captive pulp supply.
For Market Incumbents: Lock in backward integration into regional softwood pulp assets to secure lignin stream priority amid tightening MEE emissions enforcement in Shandong province. Deepen ultrafiltration fractionation capacity for technical-grade output targeting Japanese dye manufacturers and Brazilian pre-salt drilling contractors, insulating margin pools from commodity powder competition.
For New Entrants and Emerging Players: Enter via India's infrastructure PLI scheme production-linked incentives to establish domestic admixture manufacturing without confronting entrenched Chinese supply chains. Target liquid formulation development for São Paulo and Mumbai urban concrete producers seeking automated dosing compatibility, bypassing powder-grade incumbents' freight economics advantage.
For Investors and Strategic Acquirers: The window for entry favors integrated forestry-chemical operators with captive sulfite pulping assets and established REACH certification pathways over merchant traders exposed to feedstock volatility. Acquisition candidates displaying ultrafiltration fractionation expertise and direct mill-to-mixer distribution contracts warrant priority evaluation. Monitor CSRD disclosure mandate adoption rates across French and Dutch ready-mix procurement specifications as inflection signal for bio-based dispersant demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Captive lignin supply secures priority feedstock allocation amid tightening MEE emissions enforcement. |
| Ultrafiltration Fractionation Capacity Addition | Technical-grade output commands premium positioning in Japanese dye stabilization and ceramic suspension markets. |
| Direct Mill-to-Mixer Distribution Contracts | Bypassing regional distributors consolidates procurement relationships with Texas and Florida ready-mix chains. |
| REACH Certification Investment | Formaldehyde restriction compliance enables qualification in German federal highway tender specifications. |
| Liquid Formulation Development | Automated dosing compatibility opens São Paulo and Mumbai urban concrete producer segments. |
Research Methodology
Multi-period observation of sulfite pulping capacity utilization, REACH registration timelines, and CSRD disclosure adoption rates anchored the trend analysis, supplemented by interviews with technical R&D directors at integrated forestry-chemical operators, procurement leads at German ready-mix concrete chains, plant managers at Shandong sulfite mills, distribution channel partners in Texas and Florida, and EPA compliance officers on Department of Transportation projects. Secondary validation drew from ECHA registration databases, Chinese MEE emissions audit disclosures, SEC 10-K filings of pulp processors, customs and trade data on lignosulfonate shipments, and Cefic specialty chemical reports. Bottom-up segment sizing triangulated against top-down construction chemical market estimates.
Segment-weighting across formulation type, application intensity, and grade certification tier informed the analytical framework, with growth trajectories modeled across the projection horizon. CAGRs derived from elasticity analysis against construction spending cycles, oilfield exploration budgets, and pulp processing capacity expansion. Industry-specific forecast inputs incorporated EPA drilling waste disposal guideline revisions and EU Green Deal procurement mandate propagation rates through member state implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE enforcement intensity shifts or polycarboxylate ether breakthroughs in UHPC formulations exceeding 150 MPa. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Global Methylal Market