
 Tetrafluoroethane (R134A) Refrigerant Market | 2026-2036
Tetrafluoroethane (R134A) Refrigerant Market Size, Share, and Industry Trends Forecast 2026-2036
Tetrafluoroethane (R134A) Refrigerant Market Intelligence
A divergence in backward integration into key raw materials like hydrofluoric acid is bifurcating competitive positioning within the supply base. Producers based in China, including Dongyue Group and Zhejiang Juhua, leverage significant manufacturing scale and direct feedstock control to manage costs. In contrast, firms such as Chemours and Honeywell International differentiate through branded product lines and extensive distribution networks in highly regulated markets.
Tetrafluoroethane, or R134a, is a hydrofluorocarbon (HFC) refrigerant with the chemical formula CH2FCF3, known for its non-ozone-depleting properties. It functions as a working fluid in automotive air conditioning systems and commercial refrigeration equipment. The automotive AC application remains a dominant volume segment, driven by servicing the existing vehicle fleet. Demand from end users like cold storage facilities for commercial refrigeration is also significant.
Market access and product longevity are shaped by environmental regulations targeting high-GWP refrigerants. Mandates like the European Union's F-Gas Regulation and programs under the United States EPA are accelerating the transition to lower-GWP alternatives like hydrofluoroolefins. Consequently, refrigerant manufacturers and HVAC contractors must navigate a complex landscape of regional phase-down schedules and evolving equipment standards.
Market Dynamics
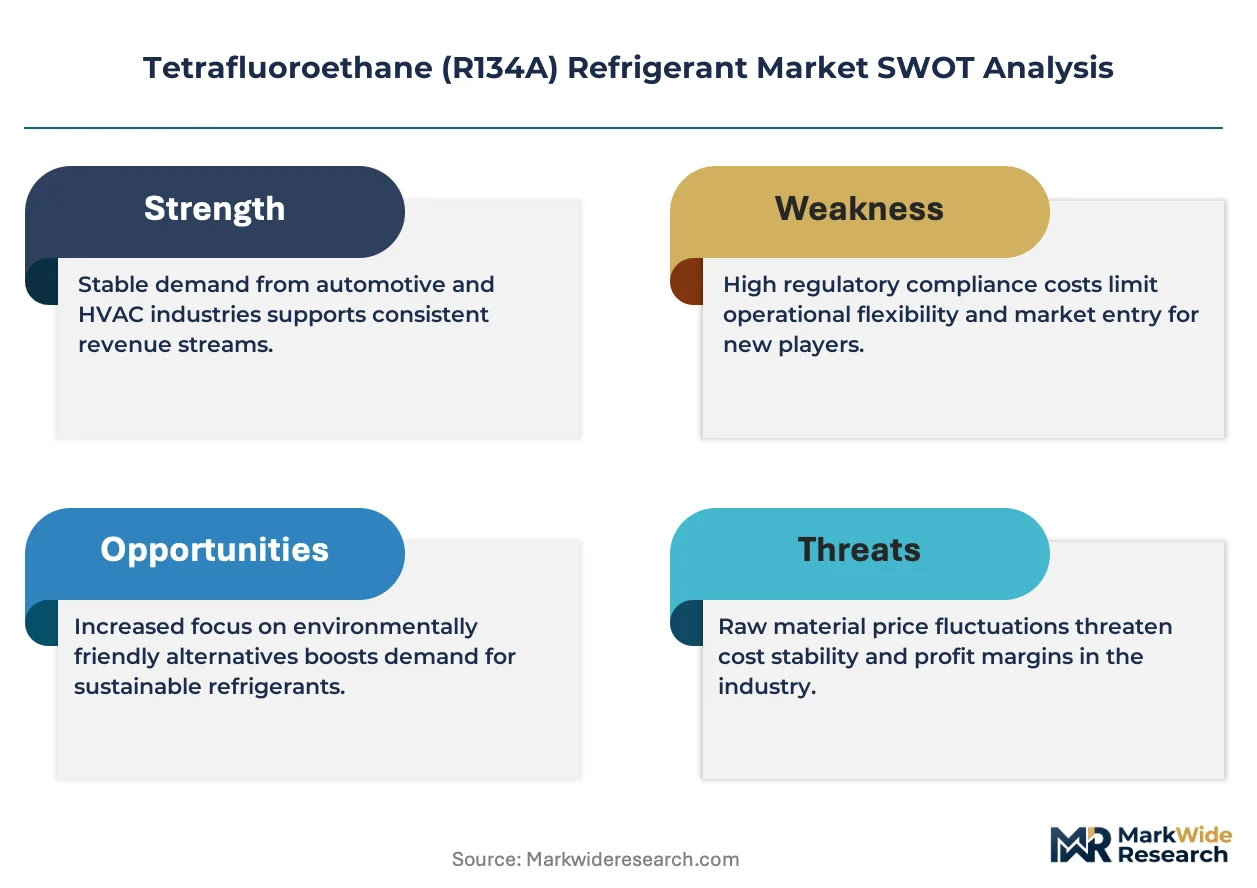
The central dynamic shaping the market is the global regulatory phase-down of high-GWP hydrofluorocarbons. This pressure, codified in treaties like the Kigali Amendment and national laws like the EU F-Gas Regulation, creates a fundamental tension between servicing legacy equipment and transitioning to next-generation alternatives.
Growth Catalysts
- Automotive Aftermarket Service:Demand is sustained by the vast global fleet of vehicles equipped with R134a-based air conditioning systems, which require periodic servicing and refilling throughout their operational lifespan.
- Cold Chain Expansion in India:The expansion of food processing, pharmaceutical storage, and organized retail in India creates consistent demand for R134a in new commercial refrigeration and transport refrigeration installations.
- Specialty Propellant Applications:Use of high-purity R134a as a non-flammable propellant in medical devices, particularly metered-dose inhalers for asthma, provides a stable, non-cyclical source of demand.
Market Restraints
- Regulatory Production Quotas:Mandates under the US EPA's AIM Act and the European Union's F-Gas Regulation progressively reduce the volume of virgin R134a that can be produced or imported, directly constraining supply.
- Direct Substitution by HFOs:The commercialization of hydrofluoroolefins like R1234yf and HFO-based blends provides a lower-GWP alternative that is displacing R134a in new automotive and refrigeration equipment.
- Feedstock Price Volatility:The market is exposed to price fluctuations for key raw materials, especially hydrofluoric acid, which can impact production costs and compress manufacturer margins.
Strategic Opportunities
- Refrigerant Reclamation Services:The phase-down of virgin production creates a significant business opportunity for the recovery, purification, and recertification of used R134a, establishing a circular economy for the refrigerant.
- Servicing Demand in Developing Economies:Markets across Africa and parts of Southeast Asia with longer HFC phase-down timelines present a long-tail opportunity to supply R134a for servicing existing equipment.
- High-Purity Grades for Electronics:Manufacturing specialized, high-purity grades of R134a for use as a cleaning solvent or etchant gas in the semiconductor industry offers a pathway to higher-margin, niche applications.
Industry Challenges
- Counterfeit Refrigerant Proliferation:The rising cost and restricted supply of legitimate R134a encourage a black market for illegally imported or dangerously mislabeled products, posing risks to equipment and service technicians.
- Complex Compliance Tracking:HVAC contractors and distributors face the operational burden of navigating a patchwork of different regional and national HFC phase-down schedules, quotas, and record-keeping requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetrafluoroethane (R134A) Refrigerant Market |
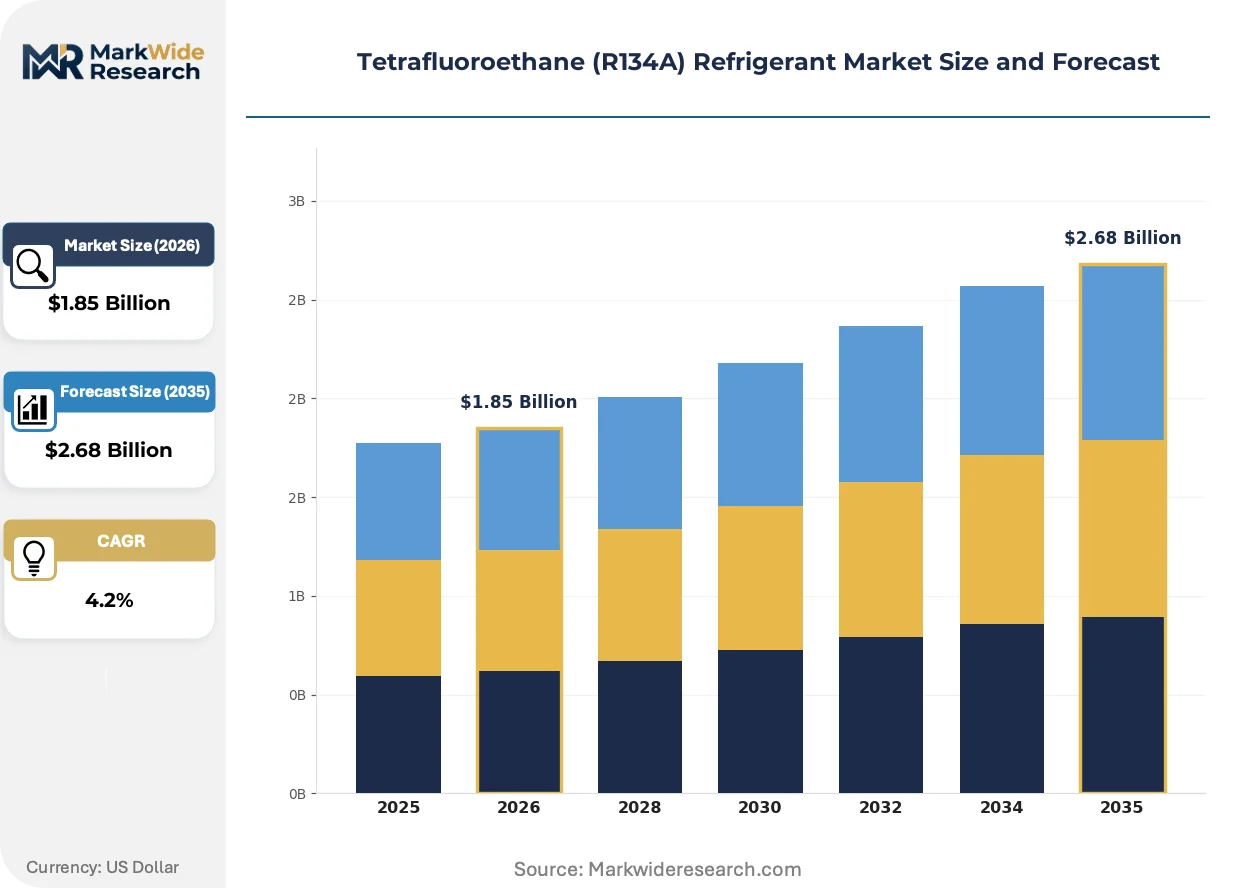
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure R134a, Blended R134a, Hydrofluoroolefins, Hydrochlorofluorocarbons, Others Application: Automotive AC, Commercial Refrigeration, Residential Cooling, Industrial Process Cooling, Cryogenics End User Industry: Vehicle Manufacturers, Cold Storage Facilities, HVAC Contractors, Pharmaceutical Producers, Food Processing Plants Packaging Type: Cylinders, Bulk Containers, Refrigerant Canisters, Drums |
| Companies Covered | Dongyue Group, Zhejiang Juhua, Chemours, Gujarat Fluorochemicals, SRF Limited, Arkema, Sinochem Lantian, Honeywell International, Daikin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetrafluoroethane (R134A) Refrigerant Market Strategic Shifts & Innovations
Regulatory pressures and the economic realities of a massive installed equipment base are driving parallel innovations. The market is simultaneously focused on developing next-generation, low-GWP alternatives while also creating a circular economy for the existing R134a supply through advanced reclamation.
The development of hydrofluoroolefins (HFOs) and HFC/HFO blends serves as a direct, lower-GWP replacement for R134a. Automotive manufacturers have widely adopted these new refrigerants in vehicle production to comply with environmental standards set by agencies like the EPA and under EU directives. This technological shift is bifurcating the refrigerant supply chain between a market for new equipment using HFOs and a distinct aftermarket servicing legacy R134a systems.
Implementation of the Kigali Amendment to the Montreal Protocol establishes the definitive global framework for phasing down HFC consumption. This treaty compels signatory countries to enact domestic quota systems and restrictions, exemplified by the American Innovation and Manufacturing (AIM) Act in the United States. The automotive service and commercial refrigeration sectors are most affected, as they must manage dwindling virgin supply and invest in recovery equipment.
End-user behavior is evolving from simple transactional purchasing toward adopting comprehensive refrigerant lifecycle management. This change disrupts traditional distribution by creating demand for reclamation services, where used R134a is recovered from systems, purified to AHRI-700 standards, and resold as certified reclaimed product. This circular model is most advanced in the European Union and United States, where stringent quotas make reclaimed gas a critical supply source.
Tetrafluoroethane (R134A) Refrigerant Market Segmentation
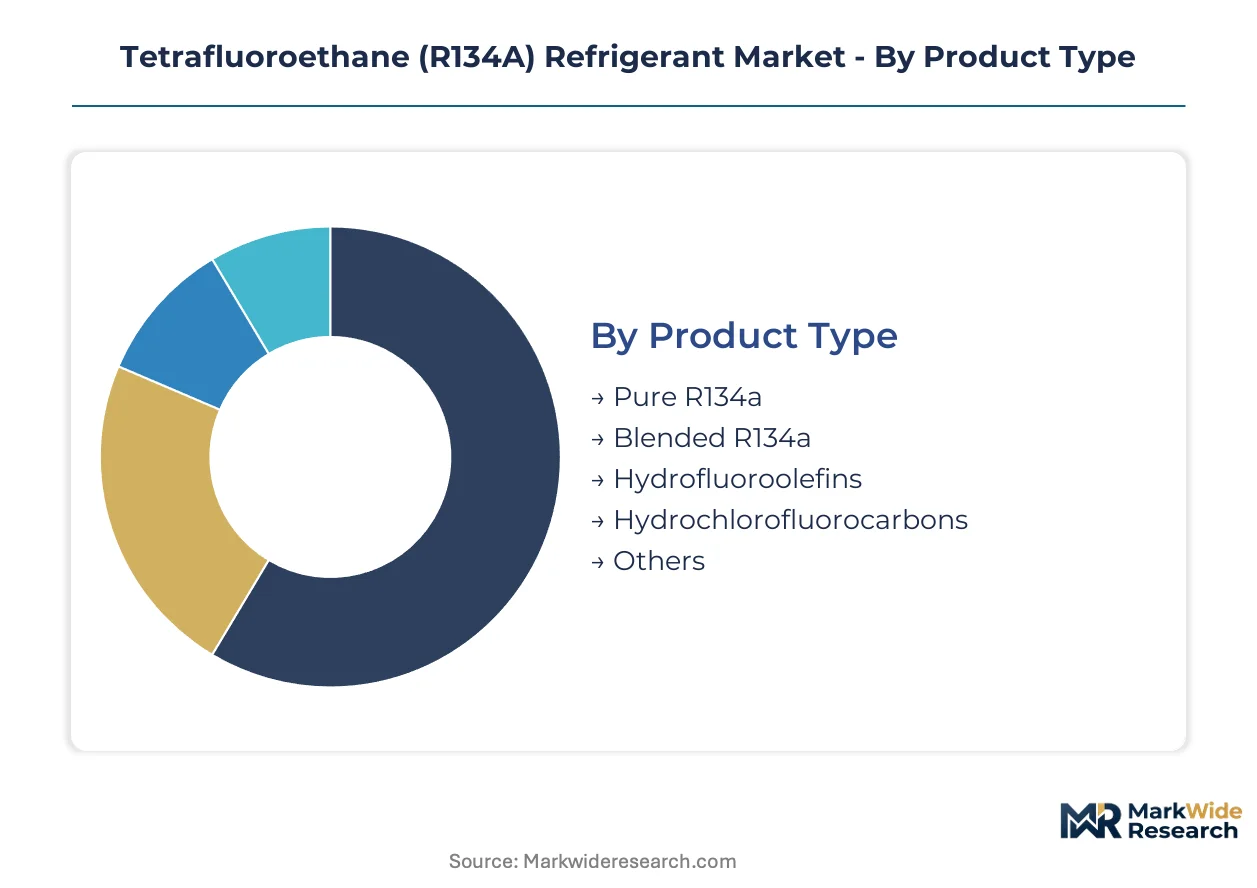
The Tetrafluoroethane (R134A) Refrigerant Market is analyzed through distinct segments, providing a granular view of demand drivers and competitive dynamics. This segmentation helps stakeholders understand the varied requirements across different applications and end-user industries. It also highlights the impact of evolving environmental regulations on product preferences.
Product Type:
Regulatory differentiation fundamentally shapes the product type landscape, with global mandates progressively restricting high-GWP refrigerants. This pressure influences both production and consumption patterns across regions like the European Union and the United States.
- Pure R134a:This hydrofluorocarbon (HFC) is a non-ozone-depleting refrigerant with a global warming potential of 1430. Demand is sustained by the vast installed base of automotive air conditioning systems and commercial refrigeration equipment requiring service and aftermarket refilling.
- Hydrofluoroolefins:These are next-generation refrigerants, such as R1234yf, characterized by ultra-low global warming potentials. Adoption is accelerating in new automotive platforms and certain commercial refrigeration applications to comply with stringent environmental standards from agencies like the US EPA.
- Blended R134a:These formulations combine R134a with other refrigerants to achieve specific performance characteristics or to slightly reduce overall GWP. They offer transitional solutions for some existing refrigeration systems.
- Hydrochlorofluorocarbons:HCFCs like R22 are ozone-depleting substances being phased out globally under the Montreal Protocol. Their use is now largely restricted to servicing legacy equipment in developing economies.
- Others:This category includes various specialty gases and experimental refrigerants not falling into the primary classifications. These often serve niche industrial or research applications.
Established volume favors Pure R134a; emerging adoption favors Hydrofluoroolefins.
Application:
Market dominance within applications is driven by the sheer scale of installed equipment and varying regulatory pressures across sectors. Each application presents unique demands for refrigerant properties and supply chain logistics.
- Automotive AC:This segment involves the use of R134a as the primary refrigerant in vehicle air conditioning systems. Servicing the global fleet of R134a-equipped vehicles creates consistent aftermarket demand, particularly in regions with longer phase-down timelines.
- Commercial Refrigeration:R134a is extensively used in supermarket display cases, cold storage warehouses, and transport refrigeration units. Expansion of cold chain infrastructure, especially in India, drives demand for new installations and ongoing maintenance.
- Residential Cooling:This application includes R134a use in domestic refrigerators, freezers, and some smaller residential air conditioning units. Regulatory transitions are pushing this segment towards lower-GWP alternatives for new equipment.
- Industrial Process Cooling:Large-scale industrial chillers and process cooling systems utilize R134a for temperature control in manufacturing and chemical processes. These systems often require significant refrigerant volumes.
- Cryogenics:R134a can be used in some low-temperature refrigeration systems and specific cryogenic applications, although less common than other refrigerants. This segment represents a specialized, high-purity demand.
The largest share is held by Automotive AC, while Commercial Refrigeration exhibits significant expansion in developing markets.
End User Industry:
Customer type and procurement patterns define the end-user industry segmentation, reflecting diverse purchasing behaviors and technical requirements. The compliance burden varies significantly across these industries due to equipment lifespan and regulatory oversight.
- HVAC Contractors:These professionals are crucial for installing, maintaining, and servicing R134a-based air conditioning and refrigeration systems. They represent a significant channel for aftermarket refrigerant sales and reclamation services.
- Cold Storage Facilities:Operators of large cold storage warehouses and distribution centers consume R134a for their extensive refrigeration infrastructure. Their procurement often involves bulk quantities and long-term supply agreements.
- Vehicle Manufacturers:OEMs specify and initially charge R134a into new vehicles, though this is transitioning to HFOs for new production. This segment's demand is primarily for initial fill.
- Pharmaceutical Producers:The pharmaceutical industry uses R134a in metered-dose inhalers as a non-flammable propellant. This application demands high-purity grades and maintains stable, non-cyclical demand.
- Food Processing Plants:These facilities rely on R134a for various cooling and freezing processes essential for food preservation and safety. Their demand is consistent with food production volumes.
Service providers are critical for HVAC Contractors demand, with Cold Storage Facilities representing consistent industrial consumption.
Packaging Type:
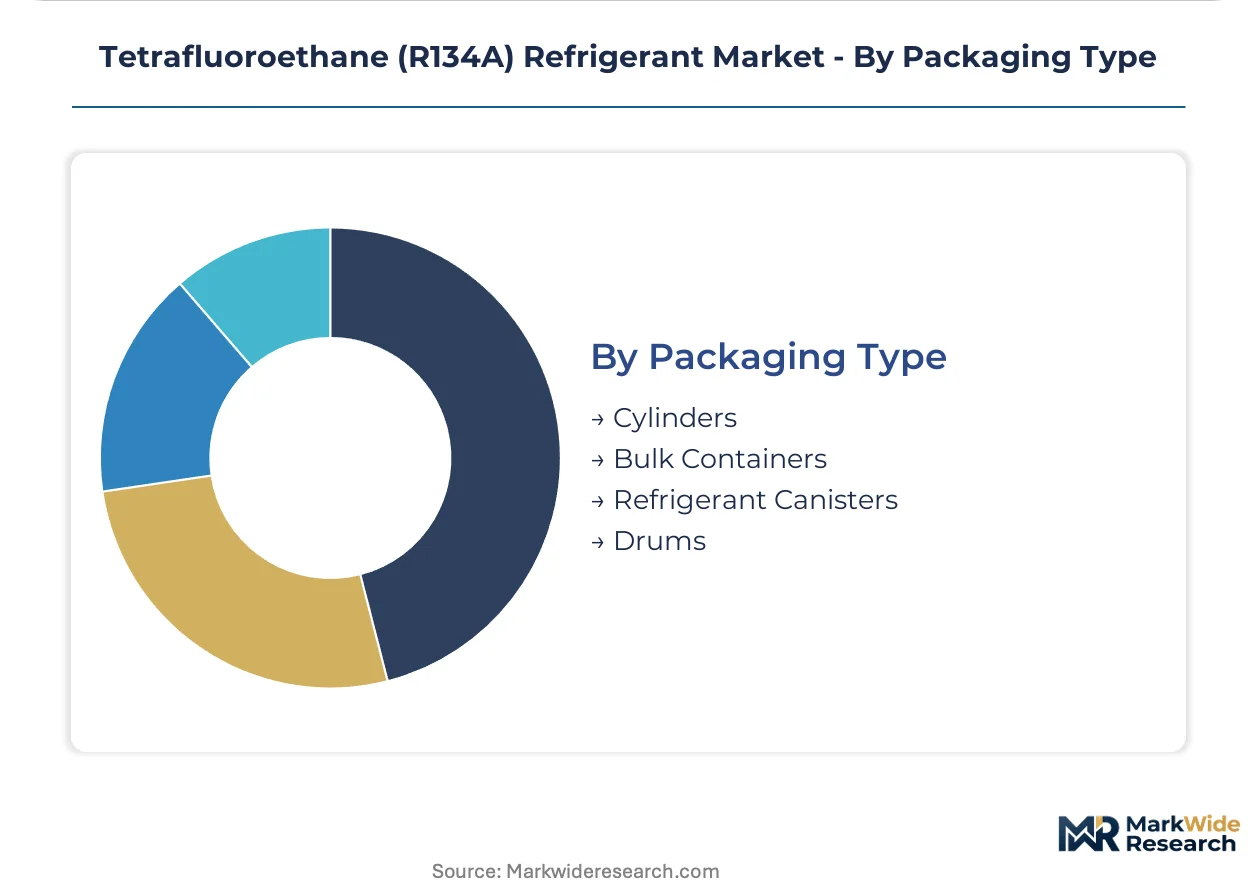
The scale of use and logistical efficiency dictate preferences across packaging types, impacting distribution channels and cost structures. Different packaging solutions cater to specific market needs, from large industrial users to individual service technicians.
- Bulk Containers:These large vessels, including ISO tanks and ton cylinders, are used for transporting significant volumes of R134a. They cater primarily to large industrial users and major distributors, offering the most cost-effective per-unit transport.
- Cylinders:R134a is commonly distributed in various size cylinders (e.g., 30 lb, 50 lb, 125 lb) for commercial and industrial use. These are standard for HVAC contractors and smaller refrigeration service providers, balancing volume with portability.
- Refrigerant Canisters:Smaller, often disposable, canisters are typically used for DIY automotive AC recharging or small residential appliance servicing. They offer convenience for low-volume, infrequent use.
- Drums:Intermediate in size between cylinders and bulk containers, drums provide a cost-effective solution for medium-volume users. They are often utilized by larger service companies or smaller industrial sites.
Large-scale users prefer Bulk Containers for economic efficiency, while Cylinders cater to varied service needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for R134a varies significantly across global markets. Mature economies with stringent environmental regulations exhibit lower price sensitivity for reclaimed refrigerants due to limited virgin supply. Conversely, developing nations often prioritize cost-effectiveness for servicing existing equipment, leading to higher price sensitivity.
United States
The United States sustains demand for R134a in its vast automotive aftermarket and commercial refrigeration sectors. The US EPA's AIM Act establishes production quotas, driving a shift toward reclaimed refrigerants. Major metropolitan areas like Los Angeles and New York require compliance with strict HFC management protocols for HVAC contractors.
Germany
Germany's demand for R134a stems from maintaining existing commercial refrigeration and industrial process cooling systems. The EU F-Gas Regulation significantly restricts virgin R134a supply, promoting reclamation. Industrial hubs in the Rhine-Ruhr region are actively transitioning to lower-GWP alternatives for new equipment.
China
China represents a significant R134a market, driven by its large automotive manufacturing base and domestic appliance sector. While current regulations allow substantial production, future phase-down schedules under the Kigali Amendment will impact supply. Production centers in Zhejiang leverage direct feedstock control to manage costs effectively.
India
India's rapid cold chain expansion and growing commercial refrigeration sector create consistent R134a demand. Government initiatives supporting food processing and pharmaceutical storage sustain this need. Major urban centers like Bangalore are seeing increased installations of R134a systems for new cold storage facilities.
Tetrafluoroethane (R134A) Refrigerant Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the R134a market. The supply base bifurcates into large-scale, vertically integrated producers and specialized firms focusing on high-value applications. Strategic archetypes include commodity manufacturers with direct feedstock access and brand-focused distributors in regulated markets. Dominant competitive moves involve securing upstream raw material supply and expanding distribution networks for market penetration.
At the scale-driven end, Chinese manufacturers like Dongyue Group and Zhejiang Juhua exemplify producers with significant manufacturing scale and direct feedstock control. These firms leverage their integrated operations to manage production costs effectively. In contrast, companies such as Chemours occupy a position focused on branded product lines and extensive distribution capabilities, particularly within highly regulated markets. These players differentiate through product quality and established market access, catering to segments requiring compliance and reliability. This bifurcation reflects the varied strategic priorities across the global supply chain.
| Leading Market Players |
|---|
| Dongyue Group |
| Zhejiang Juhua |
| Chemours |
| Gujarat Fluorochemicals |
| SRF Limited |
| Arkema |
| Sinochem Lantian |
| Honeywell International |
| Daikin |
| Others |
Cost & Logistics Intelligence
Scale economies inherent in hydrofluorocarbon production, particularly across Asian manufacturing hubs, establish significant price floors for virgin R134a. This manufacturing scale dictates global supply concentration and influences overall pricing dynamics for the refrigerant, especially in less regulated markets.
Pricing Analysis
Aftermarket service revenue streams drive lifetime value for R134a, shaping transactional pricing for smaller volumes. The dominant pricing model combines commodity spot pricing for virgin R134a with contract-based long-term offtake agreements for large industrial users. Price differentiation stems from quality grade, brand premium for established players like Chemours, and the regulatory status of reclaimed versus virgin product. Pricing pressure stems from regulatory production quotas under the US EPA AIM Act and the EU F-Gas Regulation, which constrain virgin supply. Developing economies in Africa and parts of Southeast Asia exhibit the most price-sensitive buyer behavior for servicing existing equipment.
Supply Chain Analysis
Just-in-time inventory strategies are common for virgin R134a, while strategic stockpiling occurs ahead of regulatory phase-down deadlines. Geographic supply concentration centers on China, with manufacturers like Dongyue Group, and India, with Gujarat Fluorochemicals, dominating production. Key raw material dependencies include hydrofluoric acid and chloroform, which are critical feedstock inputs. Regulatory restrictions on virgin production and import quotas create a structural supply chain risk. Distribution runs through a network of specialized refrigerant distributors and HVAC contractors for aftermarket sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tetrafluoroethane (R134a) Refrigerant Market is undergoing significant disruption driven by the global phase-down of high-GWP substances. This regulatory inflection, particularly the Kigali Amendment, reshapes market dynamics towards low-GWP alternatives and a circular economy for existing refrigerants.
For Market Incumbents:Fortify existing market share by investing in advanced reclamation technologies for R134a to secure supply in regulated markets. Diversify product portfolios into next-generation hydrofluoroolefins (HFOs) to mitigate the threat of direct substitution from environmental mandates. This strategy addresses the global phase-down of high-GWP refrigerants and the proliferation of lower-GWP HFOs. Capacity addition for HFO production in strategic regions like the EU and US, alongside certification investment for reclaimed products, provides a strong lever.
For New Entrants and Emerging Players:Differentiate on specialized reclamation services, targeting the growing demand for certified reclaimed R134a in mature markets. Focus on high-purity grades for niche applications like medical propellants or semiconductor cleaning. Servicing demand in developing economies, particularly across Africa and Southeast Asia, offers long-tail opportunities due to extended phase-down timelines. Partner with HVAC contractors and cold chain operators to establish efficient refrigerant recovery and purification networks as a go-to-market angle.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors companies with diversified portfolios spanning both legacy R134a reclamation and new HFO production over the next 5-10 years. Target mid-sized firms specializing in refrigerant reclamation technology or those with strong distribution networks in underserved developing markets. The acceleration of HFO adoption rates in new automotive and commercial refrigeration equipment across major economies is the signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in HFO Production Capacity | Secures future market position against regulatory phase-downs of high-GWP R134a in the EU. |
| Expand Refrigerant Reclamation Services | Addresses virgin R134a supply constraints and creates a circular economy for HVAC contractors. |
| Secure Hydrofluoric Acid Feedstock Supply | Mitigates raw material price volatility and strengthens cost leadership for Chinese producers. |
| Develop High-Purity R134a Grades | Captures higher-margin demand in pharmaceutical propellant and semiconductor etching applications. |
| Form Distribution Partnerships in Emerging Markets | Accesses growing commercial refrigeration and automotive aftermarket demand in India. |
Research Approach
Operator-level perspectives from HVAC contractors, cold storage facility operators, pharmaceutical procurement specialists, and automotive OEM engineers anchored the qualitative base. Primary interviews combined with secondary validation informed both bottom-up and top-down market sizing. US EPA reports, EU F-Gas Regulation documents, industry association publications like AHRI, and customs trade data served as crucial secondary sources.
Sensitivity analysis was applied to key market drivers to construct a robust analytical framework across the projection horizon. Segmentation dimensions modeled included product type, application, end-user industry, packaging type, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends, demand projections, and anticipated regulatory impacts. Global vehicle production forecasts and cold chain infrastructure investment in India served as critical forecast inputs.
Material uncertainties — unforeseen geopolitical shifts or rapid technological breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement and adoption rates of alternatives. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Lime Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Heat Transfer Fluids Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Shea Olein Market