
 South Korea Sealants Market | 2026-2036
South Korea Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Sealants Market Analytics
Subscription-based technical service contracts for applied sealant systems is rebalancing how Korean manufacturers monetize long-term customer relationships. KCC SILICONE CORPORATION leverages its domestic production network to anchor supply security for domestic construction conglomerates. Dow competes through specialized aerospace-grade formulations that meet Korean Air and LIG Nex1 procurement standards. Henkel AG & Co. KGaA differentiates via adhesive-sealant hybrid platforms serving Hyundai Motor Group assembly lines.
Sealants are polymeric materials formulated to block fluids, dust, and gases through elastomeric adhesion to substrates, with silicone variants typically exhibiting Shore A hardness of 20-50 and elongation at break exceeding 400% for joint-movement accommodation. These materials serve critical functions in waterproofing building envelopes, bonding dissimilar automotive panels, and encapsulating electronic components against thermal cycling. Silicone sealants occupy the dominant revenue position owing to superior UV stability and temperature resistance demanded by Korean infrastructure codes. Polyurethane alternatives represent the fastest-expanding category in automotive underbody applications where paint compatibility and vibration damping converge. Epoxy segments concentrate margin pools in electronics surface-mounting applications around Suwon and Pyeongtaek semiconductor fabs.
MFDS chemical substance registration requirements and KOSHA industrial safety standards govern workplace exposure limits and product hazard classifications for sealant formulations distributed domestically. South Korea's Green Building Certification System and Seoul Metropolitan Government air quality ordinances progressively restrict solvent content, redirecting R&D expenditure toward waterborne and silyl-modified polymer chemistries. Buyers should track how forthcoming amendments to the Act on the Registration and Evaluation of Chemicals affect import pathways for European and North American specialty sealant suppliers.
Market Dynamics
MFDS chemical substance registration and Seoul Metropolitan Government air quality ordinances are compressing formulation timelines while redirecting R&D budgets toward waterborne chemistries. This regulatory pressure is converging with the Green New Deal carbon targets to reshape competitive positioning around low-VOC capabilities.
Growth Catalysts
- Green Building Certification System mandates:Seoul's tightening envelope performance standards drive silicone sealant specification for high-rise commercial projects. Building codes now require documented thermal cycling resistance.
- Gyeonggi Province electronics clustering:Semiconductor fabs around Suwon and Pyeongtaek generate concentrated demand for epoxy encapsulants with precision dispensing compatibility. Surface-mount packaging densities favor high-purity formulations.
- Hyundai Motor Group assembly integration:Adhesive-sealant hybrid platforms are displacing mechanical fasteners in electric vehicle battery pack sealing. Paint shop compatibility requirements favor silyl-modified polymer alternatives.
Market Restraints
- Petrochemical feedstock volatility:Silicone precursor costs fluctuate with methanol and silicon metal pricing. Formulators lack long-term purchase agreements for specialty silane intermediates.
- Import pathway concentration:European and North American specialty sealant suppliers face extended MFDS registration timelines. The Act on the Registration and Evaluation of Chemicals creates procedural friction for new entrants.
- Polyurethane substitution ceiling:Automotive underbody applications demand paint compatibility that silicone cannot match. UV degradation limits exterior structural bonding use cases.
Strategic Opportunities
- Busan maritime infrastructure renewal:Port expansion and offshore wind installations create demand for salt-spray-resistant formulations. Marine-grade specifications remain underpenetrated by domestic suppliers.
- Subscription technical service models:Applied sealant system contracts allow manufacturers to capture lifecycle value beyond initial product sales. Construction conglomerates favor bundled performance guarantees.
- KOSHA workplace safety alignment:Industrial safety standard updates favor pre-certified product lines. Early compliance creates specification advantages in factory maintenance segments.
Industry Challenges
- Formulation chemist scarcity:Waterborne and silyl-modified polymer expertise concentrates at senior levels. Universities produce fewer polymer science graduates with sealant-specific training.
- Certification timeline compression:MFDS hazard reclassification cycles outpace product reformulation schedules. Registration dossier preparation consumes 18-24 months for novel chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Sealants Market |
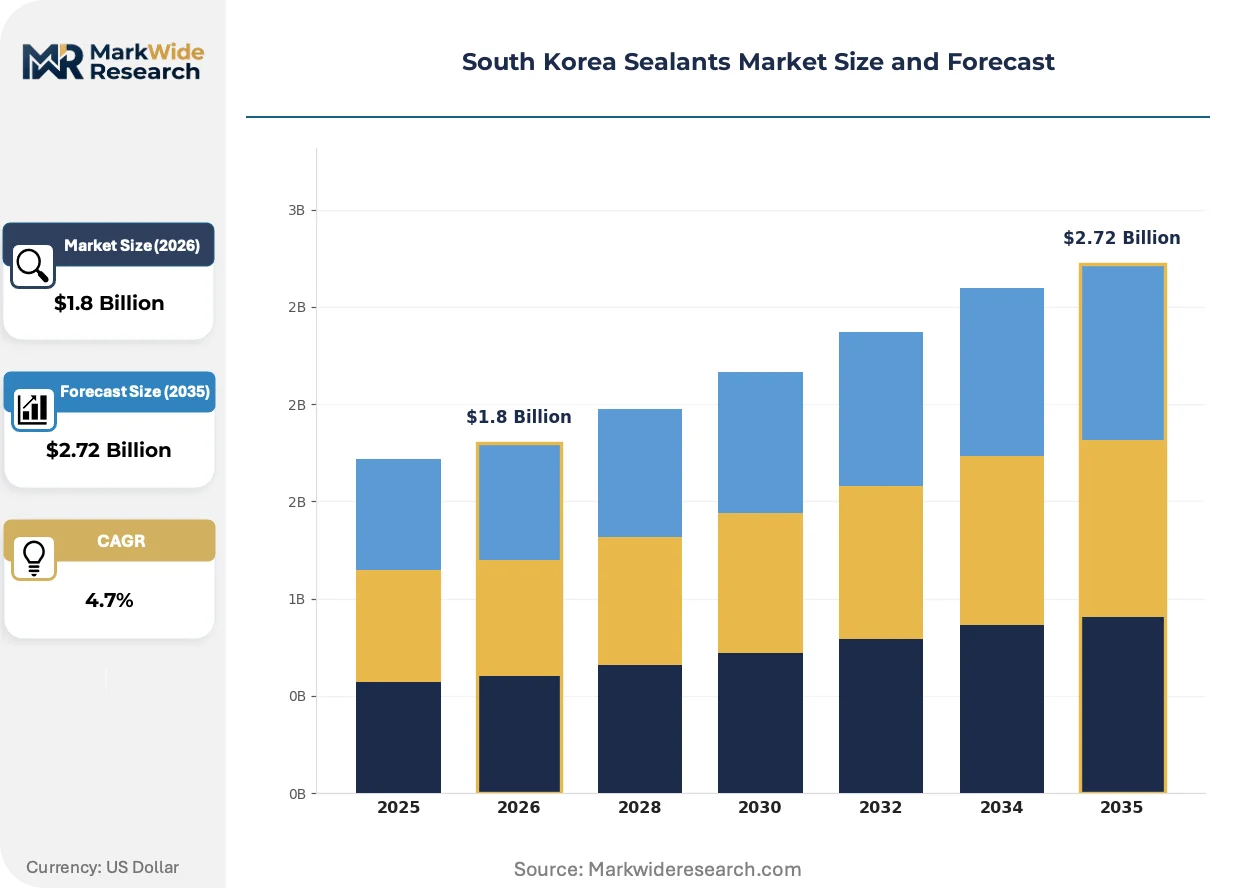
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Epoxy End User: Construction, Automotive, Aerospace, Electronics Application: Sealing Joints, Surface Mounting, Insulation, Weatherproofing Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | KCC SILICONE CORPORATION, Dow, Henkel AG & Co. KGaA, 3M, Sika AG, Shin-Etsu Chemical Co., Ltd., Soudal Holding N.V., OKONG Corp., TOPSEAL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Sealants Market Evolving Landscape
Waterborne and silyl-modified polymer chemistries are displacing solvent-based systems as the primary R&D focal point. Formulation priorities now center on achieving equivalent performance with reduced volatile organic compound profiles.
Silyl-modified polymer sealants combine silicone durability with polyurethane paint compatibility. Hyundai Motor Group suppliers are adopting these hybrids for battery enclosure sealing at accelerated qualification timelines. This technology is converging with automated dispensing systems to enable single-platform solutions across multiple automotive assembly steps.
Seoul Metropolitan Government air quality ordinances progressively restrict solvent content in construction materials. The Green Building Certification System now assigns scoring weight to low-emission sealant specifications. Commercial building developers in Seoul and Busan are responding by embedding VOC limits into procurement templates ahead of national mandate expansion.
Construction conglomerates are unbundling after-sales technical service from product supply contracts. Korean contractors now specify multi-year performance monitoring agreements for critical envelope joints. This pattern is most visible in Seoul high-rise residential towers where water ingress liability drives demand for documented installation quality and periodic inspection protocols.
South Korea Sealants Market Segmentation
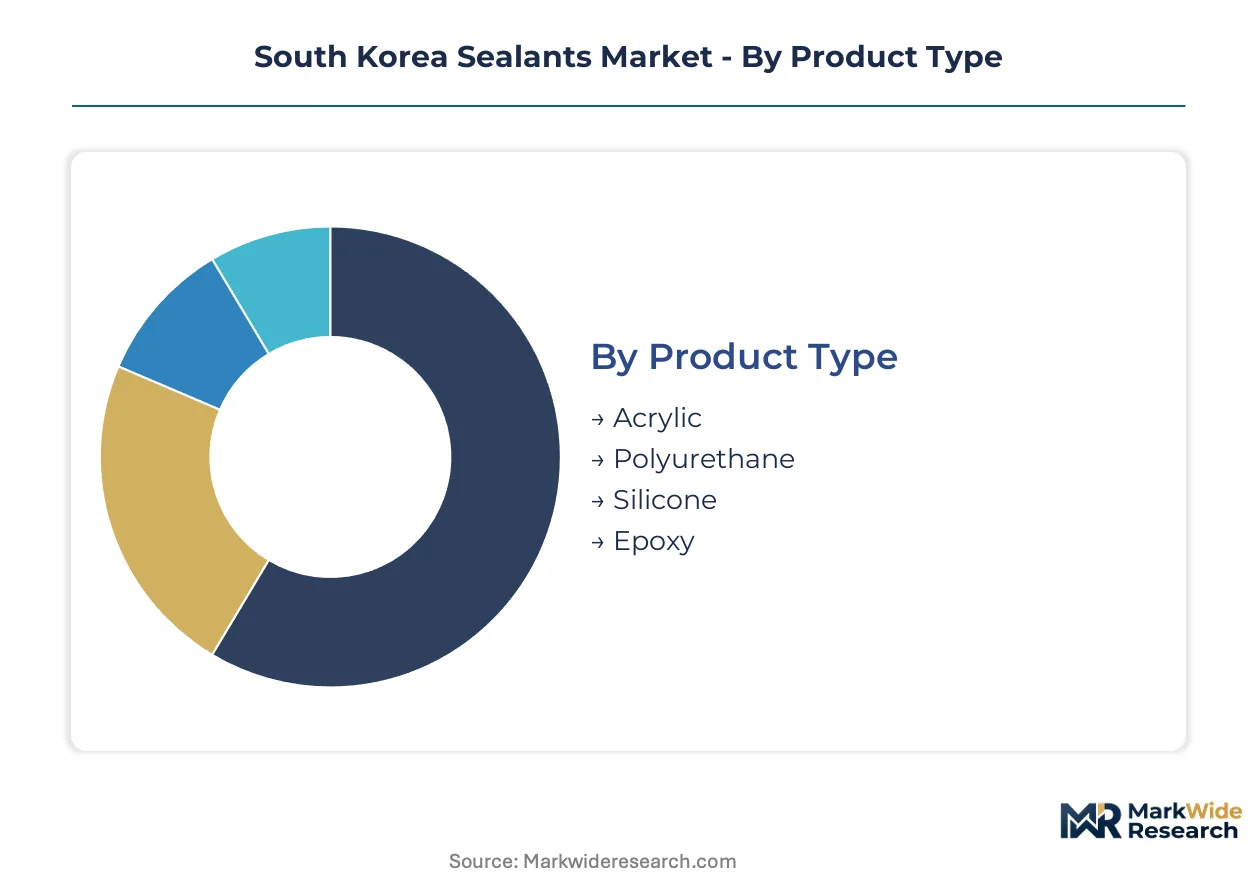
Segmentation in the South Korea sealants market reveals how formulation chemistry, end-use specifications, and procurement pathways create distinct competitive arenas. Understanding these divisions helps suppliers align R&D investments with where specification power and margin pools actually concentrate.
Product Type:
Replacement cycles for high-performance sealants are shortening as building codes and automotive specifications tighten, pushing demand toward formulations with documented durability guarantees.
- Silicone:These formulations deliver Shore A hardness of 20-50 with elongation exceeding 400%, enabling joint-movement accommodation in Seoul high-rise envelopes. Seoul Metropolitan Government air quality ordinances and Green Building Certification System mandates drive specification for UV-stable, thermally resistant grades in commercial construction.
- Polyurethane:Paint-compatible chemistries with vibration-damping characteristics dominate automotive underbody applications where silicone alternatives fail. Hyundai Motor Group assembly lines favor these formulations for battery pack sealing and structural bonding in electric vehicle platforms.
- Acrylic:Waterborne acrylic systems serve interior sealing applications with lower movement accommodation requirements. Cost-sensitive residential renovation projects in Gyeonggi Province specify these for non-structural joint filling.
- Epoxy:High-purity encapsulants with precision dispensing compatibility protect semiconductor components against thermal cycling. Suwon and Pyeongtaek electronics fabs generate concentrated demand for surface-mount packaging applications.
Volume placements concentrate in silicone; the faster expansion belongs to polyurethane.
End User:
Cost tier differentiation separates specification-grade formulations from commodity alternatives, with procurement authority residing at very different organizational levels across these verticals.
- Construction:Building envelope waterproofing and structural glazing drive bulk consumption. Seoul and Busan commercial high-rises require documented thermal cycling resistance under tightening Green Building Certification System standards.
- Automotive:Adhesive-sealant hybrid platforms displace mechanical fasteners in electric vehicle assembly. Paint shop compatibility requirements at Hyundai Motor Group facilities favor silyl-modified polymer alternatives over conventional silicones.
- Electronics:Semiconductor fabs around Suwon and Pyeongtaek demand ultra-high-purity encapsulants. Surface-mount packaging densities favor formulations with precision dispensing compatibility and minimal ionic contamination.
- Aerospace:Korean Air and LIG Nex1 procurement standards specify aerospace-grade formulations with extreme temperature tolerance. Salt-spray resistance requirements for maritime patrol aircraft create specification barriers for domestic suppliers.
Construction holds the largest volume position; electronics shows the steepest specification upgrade trajectory.
Application:
Application-driven segmentation reflects how performance requirements vary with joint geometry, substrate combination, and environmental exposure severity.
- Weatherproofing:Exterior envelope sealing against moisture and air infiltration dominates commercial building specifications. Seoul Metropolitan Government ordinances progressively restrict solvent content, redirecting demand toward low-VOC silicone and silyl-modified alternatives.
- Sealing Joints:Movement-capable formulations accommodate thermal expansion in curtain wall systems and infrastructure. High-rise residential towers in Seoul drive demand for documented installation quality and periodic inspection protocols.
- Surface Mounting:Precision dispensing of epoxy encapsulants protects semiconductor die and passive components. Gyeonggi Province electronics clustering concentrates demand for high-purity formulations with automated assembly compatibility.
- Insulation:Thermal and acoustic barrier applications in building envelopes and transportation equipment favor closed-cell foam-backed sealant tapes. Energy efficiency codes expand addressable scope for these systems.
Weatherproofing commands premium pricing; surface mounting gains share fastest from semiconductor capacity expansion.
Distribution Channel:
Customer type and purchase scale determine channel preference, with large contractors and industrial buyers bypassing intermediaries while smaller users rely on stocked availability.
- Direct Sales:Construction conglomerates and automotive OEMs negotiate multi-year supply agreements with embedded technical service components. Bundled performance guarantees and lifecycle monitoring contracts characterize these relationships.
- Distributors:Regional stocking points serve mid-tier contractors and maintenance operations requiring rapid availability. Technical support capabilities differentiate distributor value beyond logistics.
- Wholesale:Volume-oriented channels supply commodity-grade sealants for residential renovation and small commercial projects. Price transparency pressures margins in this tier.
- Online Retail:E-commerce platforms capture DIY and small contractor demand for standardized pack sizes. Product selection favors well-known brands with clear technical documentation.
Direct sales capture the highest value per kilogram; distributors maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity concentrates in the Seoul Capital Area and Busan-Ulsan corridor, while consumption spreads across five industrial clusters with distinct specification requirements. Regional demand patterns reflect the geographic distribution of construction, automotive, and electronics manufacturing.
Seoul Capital Area
Commercial high-rise construction drives silicone sealant specification for building envelopes. Seoul Metropolitan Government air quality ordinances progressively restrict solvent content in construction materials. Gangnam and Yeouido districts generate concentrated demand for Green Building Certification System-compliant formulations.
Busan-Ulsan
Maritime infrastructure renewal and offshore wind installations create demand for salt-spray-resistant sealants. Port expansion projects favor marine-grade specifications with documented durability guarantees. Hyundai Heavy Industries and shipyard clusters anchor procurement for specialized formulations.
Gyeonggi Province
Semiconductor fabs around Suwon and Pyeongtaek generate concentrated demand for epoxy encapsulants. Surface-mount packaging densities favor high-purity formulations with precision dispensing compatibility. Samsung and SK Hynix supply chains drive specification standards for ionic contamination limits.
Daegu-Gyeongbuk
Textile and machinery manufacturing creates maintenance-driven demand for industrial sealants. KOSHA workplace safety standards govern factory floor applications. Daegu metropolitan area supports regional distribution networks serving mid-tier industrial buyers.
Daejeon-Sejong
Government research complexes and public construction projects drive specification-grade procurement. Sejong administrative city development embeds green building requirements into public tenders. Korea Institute of Science and Technology anchors applied research partnerships with sealant formulators.
South Korea Sealants Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and application engineering tiers. The market structure consolidates around domestic chemical conglomerates with captive silane supply, mid-scale European specialists with aerospace credentials, and diversified adhesives manufacturers serving automotive assembly integration. Strategic archetypes include integrated petrochemical players, application-focused service bundlers, and technology licensors. Capacity expansion and subscription-based technical service contracts represent the dominant competitive moves reshaping customer relationships.
Among Korea-based chemical conglomerates, KCC SILICONE CORPORATION anchors domestic production networks. Dow and Henkel AG & Co. KGaA occupy positions exemplifying multinational specialists with aerospace and automotive credentials respectively. These three represent distinct archetypes: integrated domestic supply security, aerospace-grade formulation expertise, and adhesive-sealant hybrid platform development.
| Leading Market Players |
|---|
| KCC SILICONE CORPORATION |
| Dow |
| Henkel AG & Co. KGaA |
| 3M |
| Sika AG |
| Shin-Etsu Chemical Co., Ltd. |
| Soudal Holding N.V. |
| OKONG Corp. |
| TOPSEAL |
| Others |
Value Network & Pricing Analysis
Captive silane production at KCC SILICONE CORPORATION anchors both supply security and pricing power for domestic construction conglomerates. This backward integration into silicone precursors insulates Korean formulators from methanol and silicon metal volatility while compressing procurement timelines for high-volume envelope projects.
Pricing Analysis
Margin tightening in standard-grade silicone traces to wholesale channel commoditization and price transparency pressures. Three-tier pricing structure across premium, standard, and economy levels separates Green Building Certification System-compliant formulations with documented thermal cycling resistance from commodity alternatives. Construction conglomerates negotiating direct sales contracts show lowest price sensitivity due to bundled technical service components, while residential renovation contractors in Gyeonggi Province exhibit highest sensitivity to per-unit differentials.
Supply Chain Analysis
Domestic-content mandates under Seoul Metropolitan Government procurement guidelines are reshaping sourcing toward KOSHA-certified domestic production networks. Silane intermediates and specialty epoxy resins draw from South Korea, Japan, and Germany, with semiconductor-grade encapsulants resting on ultra-high-purity feedstocks from Shin-Etsu Chemical facilities. Single-source vulnerability concentrates in aerospace-grade formulations where Dow's specialized supply chains face limited qualified alternatives. Distribution runs through direct sales for automotive OEMs and construction conglomerates, with regional distributors serving mid-tier factory maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea sealants market is becoming a vertical-integration race as formulators pursue captive control over silicone precursor supply to defend margin pools against petrochemical feedstock volatility.
For Market Incumbents: Anticipate MFDS hazard reclassification cycles by accelerating waterborne formulation pipelines ahead of regulatory deadlines. Secure long-term silane supply agreements to offset methanol price volatility, and embed subscription-based technical service contracts to lock out competitors from Seoul high-rise envelope specifications. For New Entrants and Emerging Players: Regional distributors serving Daegu-Gyeongbuk industrial maintenance segments offer the most penetrable channel architecture for specialty formulations without MFDS registration timelines. Target Busan maritime infrastructure renewal specifications where salt-spray-resistant marine grades remain underpenetrated by domestic suppliers, and lead with KOSHA pre-certification to accelerate specification adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking silicone formulation capabilities. Five-to-ten-year viability hinges on waterborne and silyl-modified polymer patent portfolios rather than commodity capacity. Monitor amendments to the Act on the Registration and Evaluation of Chemicals as the critical inflection signal for import pathway viability and domestic acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | KCC SILICONE CORPORATION's captive supply secures margin pools against methanol volatility for construction envelope specifications. |
| Waterborne Formulation Transition | Green New Deal carbon targets and Seoul Metropolitan Government ordinances compel R&D redirection toward low-VOC chemistries. |
| Subscription Technical Service Contracts | Applied sealant system agreements capture lifecycle value beyond initial sales for Seoul high-rise residential towers. |
| KOSHA Pre-Certification Investment | Early compliance with industrial safety standard updates creates specification advantages in factory maintenance segments. |
| Silyl-Modified Polymer Platform Development | Hyundai Motor Group battery pack sealing demands drive hybrid formulations combining silicone durability with paint compatibility. |
Research Methodology
Trade publications, customs records, and MFDS registration databases formed the secondary backbone for supply-side mapping and regulatory pathway analysis. Primary interviews with sealant formulation chemists, procurement leads at Hyundai Motor Group and Samsung Electronics, construction project managers, and KOSHA compliance officers validated demand assumptions and specification trends. Bottom-up volume estimates triangulated against top-down chemical industry consumption data across the analysis window.
Historical trendline analysis of silicone, polyurethane, and epoxy consumption patterns informed projection frameworks segmented by chemistry type, end-use vertical, application method, and regional industrial cluster. CAGRs derived from regression analysis of construction permit volumes, semiconductor fab capacity announcements, and automotive production schedules. Forecast inputs incorporated Green Building Certification System mandate expansion timelines and MFDS registration queue projections.
Several conditions sit outside the modeled scope, including unforeseen petrochemical feedstock disruptions, abrupt MFDS hazard reclassifications, and trade policy shifts affecting Japanese or German specialty chemical imports. Forecasts reflect assumptions about regulatory implementation pace and industrial cluster expansion continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Mirror Adhesive Market