
 Global Alteplase Market | 2026-2036
Global Alteplase Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alteplase Market Foresight
The alteplase market is restructuring around a sharp split between originator-grade thrombolytics and emerging biosimilar alternatives. Boehringer Ingelheim International GmbH leverages its recombinant tissue plasminogen activator heritage to sustain premium positioning across European stroke centers. Genentich anchors North American hospital formulary access through established Activase protocols. F. Hoffmann-La Roche Ltd. competes on manufacturing scale and cold-chain reliability for emergency deployment.
Alteplase is a recombinant human tissue plasminogen activator (tPA) produced via Chinese hamster ovary cell culture, catalyzing fibrin-specific conversion of plasminogen to plasmin for clot dissolution in acute ischemic events. The injection solution segment dominates hospital emergency departments where rapid reconstitution determines treatment windows for acute ischemic stroke. Pre-filled syringe formats are gaining fastest traction in mobile stroke units and air-ambulance settings where preparation time compresses. Lyophilized powder retains margin concentration in cost-sensitive markets where longer shelf stability offsets reconstitution delays.
FDA thrombolytic guidance and EMA biosimilar comparability standards shape product development pathways and market access timelines for new entrants. WHO Essential Medicines List inclusion and ISO 13485 quality management requirements further constrain manufacturing scale-up for regional suppliers. Stakeholders must monitor biosimilar interchangeability rulings and evolving stroke-triage AI integration that could compress treatment decision windows and reshape emergency procurement patterns.
Market Dynamics
Biosimilar pathway harmonization between FDA and EMA is compressing development timelines while originator manufacturers defend stroke-center formulary positions through cold-chain reliability guarantees and protocol integration.
Growth Catalysts
- EMA-FDA biosimilar comparability guidance:Aligned standards accelerate abbreviated approval pathways, reducing clinical trial redundancy for second-generation thrombolytics.
- Mobile stroke unit deployment:Pre-hospital thrombolytic administration in Germany, Japan, and the United States extends treatment windows beyond hospital arrival.
- Chinese hamster ovary cell culture optimization:Yield improvements in recombinant tPA production lower per-dose manufacturing costs for emergency stockpiling.
Market Restraints
- Plasma-derived raw material volatility:Fibrinogen and albumin price swings from US and European plasma collection centers squeeze margin predictability.
- Single-source cold-chain dependency:Concentrated lyophilized powder production in Switzerland and Germany creates geographic vulnerability for Asia-Pacific emergency access.
- Mechanical thrombectomy substitution:Endovascular clot retrieval in comprehensive stroke centers reduces alteplase dosing frequency for large-vessel occlusions.
Strategic Opportunities
- Brazil ANVISA accelerated review:Emerging market regulatory streamlining opens access to underpenetrated Latin American stroke networks.
- AI-powered stroke triage integration:Machine learning imaging analysis at Cleveland Clinic and Karolinska Institutet compresses door-to-needle decision windows.
- Pre-filled syringe ambulance deployment:Paramedic-administered formats bypass hospital pharmacy reconstitution delays in rural Australia and Canada.
Industry Challenges
- ISO 13485 quality management talent scarcity:Biologics manufacturing expertise concentrates in Basel and Boston, constraining facility expansion.
- Lyophilized-batch release timeline compression:Stability testing protocols create 18-24 month lag between production and market availability.
- Interchangeability ruling uncertainty:FDA biosimilar substitution guidelines remain unresolved, blocking automatic pharmacy-level switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alteplase Market |
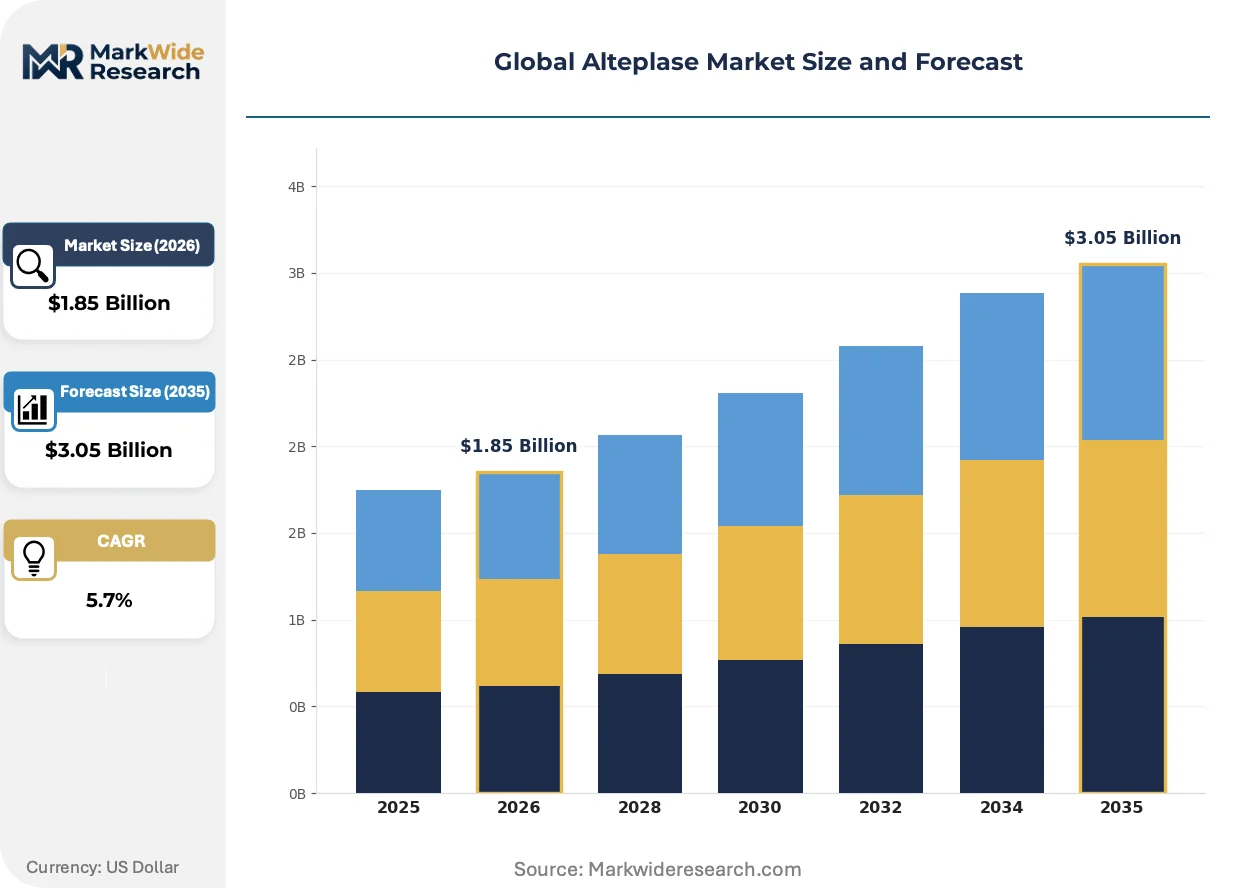
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lyophilized Powder, Injection Solution, Pre-filled Syringe, Sterile Powder Application: Acute Ischemic Stroke, Pulmonary Embolism, Acute Myocardial Infarction, Deep Vein Thrombosis End User: Hospitals, Emergency Care Centers, Specialized Clinics, Rehabilitation Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Boehringer Ingelheim International GmbH, Genentech, F. Hoffmann-La Roche Ltd., Kyowa Kirin Co., Ltd., Mitsubishi Tanabe Pharma Corporation, Microbix Biosystems, medac GmbH, MOCHIDA PHARMACEUTICAL CO., LTD., Taj Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alteplase Market Shifts & Advancements
Stroke care decentralization is redrawing competitive boundaries. Technologies that compress treatment initiation windows and regulatory frameworks that accelerate biosimilar entry are restructuring procurement priorities across emergency medicine.
Lyophilized powder reconstitution automation is absorbing preparation error risk in high-volume stroke centers. Robotic mixing systems at Hamburg University Hospital and Massachusetts General Hospital standardize concentration accuracy while reducing pharmacy technician workload. This technology is absorbing variability that previously justified originator premium pricing.
EU MDR post-market surveillance requirements are tightening thrombolytic batch tracking obligations. Device-drug combination regulations now mandate unique device identification for pre-filled syringe formats, extending compliance timelines by 12-18 months. German and French notified bodies are prioritizing stroke-device certifications, creating queue advantages for early filers.
Hospital consortium purchasing is consolidating emergency medicine procurement decisions. Integrated delivery networks in Texas and California now negotiate stroke-protocol bundles spanning imaging, thrombolytics, and mechanical thrombectomy devices. This concentration shifts vendor selection authority from individual physicians to supply chain committees, rewarding manufacturers with broad portfolio depth.
Global Alteplase Market Segmentation
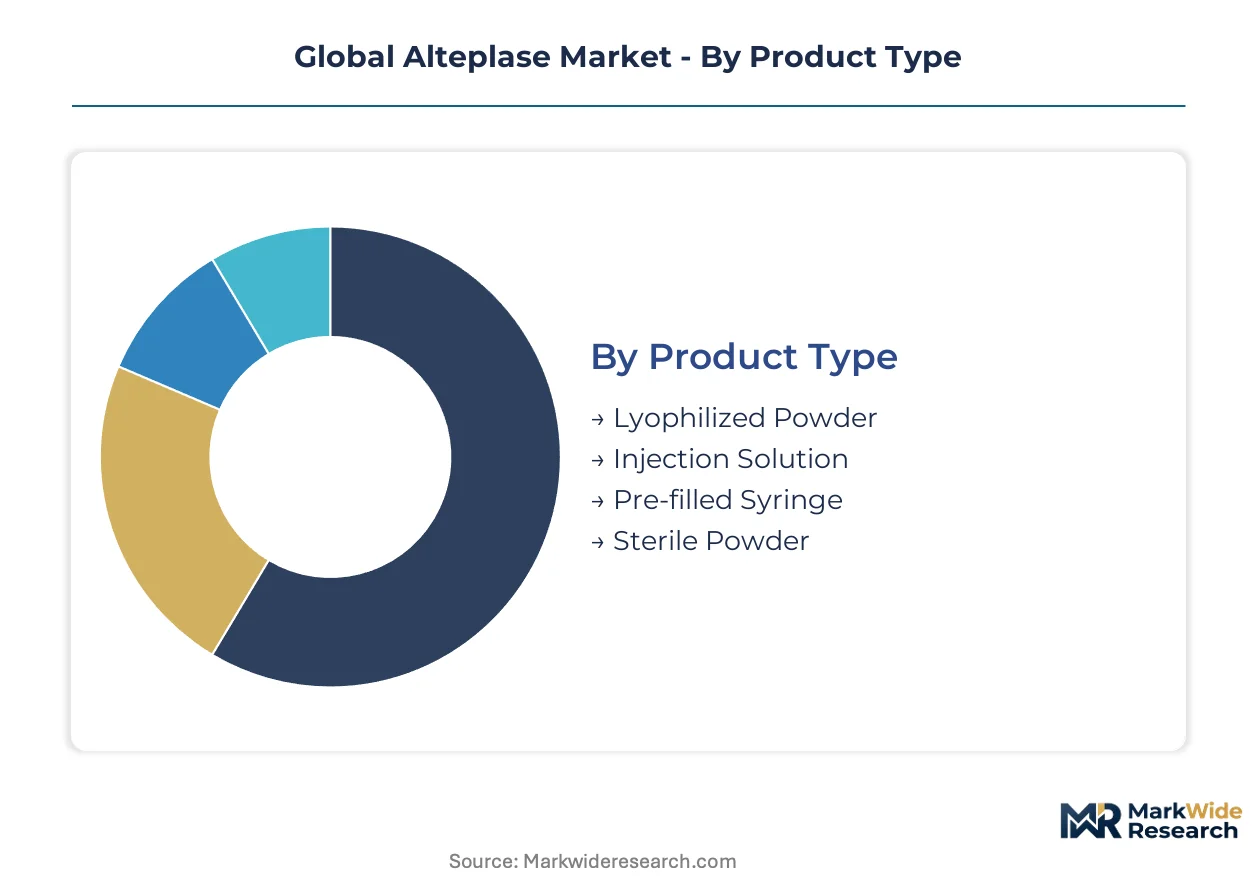
Alteplase procurement patterns diverge sharply across formulation formats, clinical settings, and distribution pathways. Understanding these segment boundaries clarifies where manufacturers must defend premium positioning versus where biosimilar penetration accelerates fastest.
Product Type:
Hospital buyers segment by preparation speed versus shelf stability trade-offs, with emergency protocols dictating format selection.
- Injection Solution:Ready-to-administer liquid formulation eliminates reconstitution delays in hospital emergency departments. Demand concentrates in comprehensive stroke centers across the United States, Germany, and Japan where door-to-needle time targets compress below 60 minutes.
- Pre-filled Syringe:Unit-dose packaging enables paramedic administration in mobile stroke units and air-ambulance fleets. Growth tilts toward rural Australia and Canadian provinces where transport distances to stroke centers exceed 100 kilometers.
- Lyophilized Powder:Freeze-dried format extends cold-chain stability for stockpiling in cost-sensitive markets.
- Sterile Powder:Bulk packaging serves high-volume compounding pharmacies with robotic reconstitution capability.
Volume sits with injection solution; growth tilts toward pre-filled syringe.
Application:
Clinical indication determines dosing protocol complexity and reimbursement tier alignment.
- Acute Ischemic Stroke:Time-critical administration within 4.5 hours of symptom onset drives emergency protocol standardization. Concentrated demand in metropolitan stroke networks of the United States, Germany, and Japan with established telestroke infrastructure.
- Acute Myocardial Infarction:Adjunct to primary PCI in catheterization laboratories with established thrombolytic backup protocols. Demand clusters in cardiac centers where door-to-balloon time targets leave narrow windows for pharmacological rescue.
- Pulmonary Embolism:Systemic thrombolysis for hemodynamically unstable patients in intensive care settings.
- Deep Vein Thrombosis:Reserved for massive iliofemoral clot burden with threatened limb viability.
Stroke applications command the steepest expansion trajectory as protocol penetration deepens.
End User:
Facility type determines formulary control points and purchasing consortium membership.
- Hospitals:Integrated delivery networks in Texas and California negotiate stroke-protocol bundles spanning imaging, thrombolytics, and mechanical thrombectomy devices. Committee-based procurement shifts vendor selection from individual physicians to supply chain authorities.
- Emergency Care Centers:Freestanding emergency departments in United States suburban markets seek rapid-turnover thrombolytic formats with minimal pharmacy overhead.
- Specialized Clinics:Outpatient anticoagulation management centers handle post-thrombolytic monitoring.
- Rehabilitation Centers:Long-term stroke recovery facilities maintain minimal alteplase inventory for recurrent event protocols.
Hospital purchasing concentration dominates volume; emergency care centers expand most quickly as freestanding models proliferate.
Distribution Channel:
Cold-chain reliability requirements and emergency access speed shape channel preference hierarchies.
- Hospital Pharmacies:Captive distribution within stroke-center networks ensures 24-hour availability with temperature-controlled storage. Swiss and German manufacturing clusters feed directly into European hospital pharmacy consortia.
- Direct Sales:Manufacturer-to-hospital contracts for high-volume stroke centers bypass distributor markups and enable protocol integration services. Prevalent in Japanese metropolitan stroke networks with consolidated purchasing authorities.
- Retail Pharmacies:Limited outpatient prescription fulfillment for rare post-discharge scenarios.
- Online Pharmacies:Minimal penetration due to cold-chain shipping complexity and emergency timing constraints.
Hospital pharmacy volume remains dominant; direct sales gain share fastest as integrated networks consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors European alteplase manufacturing through concentrated recombinant tPA production facilities serving hospital networks across the continent.
United States
Comprehensive stroke centers in Boston and Houston drive thrombolytic protocol standardization with door-to-needle targets below 60 minutes. FDA thrombolytic guidance shapes biosimilar development timelines for emergency deployment formats. The Cleveland Clinic anchors AI-powered stroke triage integration that compresses treatment decision windows.
Germany
Mobile stroke unit deployment in Hamburg and Berlin extends pre-hospital thrombolytic administration beyond traditional hospital arrival windows. EMA biosimilar comparability standards accelerate abbreviated approval pathways for second-generation products. The Rhine-Ruhr corridor concentrates lyophilized powder production serving European emergency stockpiling requirements.
Japan
Metropolitan stroke networks in Tokyo and Osaka consolidate purchasing authority through direct manufacturer-to-hospital contracts. PMDA streamlines review pathways for recombinant tPA formats with established stroke protocols. The Kansai region anchors cold-chain distribution infrastructure for island-wide emergency access.
China
Expanding acute stroke networks in Shanghai and Beijing drive hospital formulary expansion for thrombolytic therapy. NMPA harmonizes biosimilar standards with international reference products to accelerate market entry. The Yangtze River Delta concentrates contract manufacturing capacity for regional supply security.
Brazil
Underpenetrated stroke networks in São Paulo and Rio de Janeiro present expansion opportunities for thrombolytic protocol adoption. ANVISA accelerated review pathways reduce regulatory lag for emergency medicine categories. The Southeast region anchors distributor consolidation for hospital pharmacy cold-chain reliability.
Global Alteplase Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and cold-chain reliability guarantees. The vendor base concentrates around originator heritage positions in stroke-center formulary access and emerging biosimilar challengers pursuing EMA-FDA pathway harmonization. Three archetypes dominate: recombinant heritage specialists defending protocol integration, biosimilar manufacturers exploiting abbreviated approval timelines, and regional distributors capturing emergency procurement concentration. Competitive moves center on M&A for manufacturing scale and strategic partnerships for mobile stroke unit deployment.
Among European heritage specialists, Boehringer Ingelheim International GmbH and F. Hoffmann-La Roche Ltd. occupy positions reflecting recombinant tPA manufacturing lineage and hospital network integration depth. Genentech anchors North American formulary presence through established stroke protocol relationships. These three exemplify the premium-tier positioning that biosimilar challengers must displace through cold-chain reliability matching and reconstitution speed equivalence.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Genentech |
| F. Hoffmann-La Roche Ltd. |
| Kyowa Kirin Co., Ltd. |
| Mitsubishi Tanabe Pharma Corporation |
| Microbix Biosystems |
| medac GmbH |
| MOCHIDA PHARMACEUTICAL CO., LTD. |
| Taj Pharma |
| Others |
Supply & Pricing Matrix
EMA post-market surveillance mandates gate qualified supply access and premium-tier pricing power, as stroke centers demand cold-chain reliability documentation that only ISO 13485-certified facilities can deliver. This regulatory filter concentrates margin capture among heritage manufacturers while biosimilar challengers absorb certification delays.
Pricing Analysis
Door-to-needle time guarantees anchor value-based pricing for stroke protocol bundles, with comprehensive centers in Boston and Hamburg paying premiums for sub-60-minute performance commitments. Three-tier pricing structure across originator, biosimilar, and compounded formats stratifies by reconstitution speed and cold-chain pedigree. Cost compression in lyophilized powder segments intensifies as Brazilian and Chinese regulators accelerate biosimilar entry. Emergency care centers exhibit highest price sensitivity; mobile stroke units in Germany and Japan show lowest sensitivity due to protocol integration lock-in.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and German lyophilized powder production clusters serving Asia-Pacific emergency access. Manufacturing draws from Chinese hamster ovary cell banks concentrated in Basel and Boston, with fibrinogen and albumin inputs tethered to US and European plasma collection volatility. Tariff exposure on temperature-controlled logistics equipment threatens distributor margin stability. Distribution runs through hospital pharmacy consortia in integrated delivery networks, bypassing traditional wholesale channels for stroke-center formulary control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with cold-chain custody from CHO cell culture to ambulance deployment emerging as the decisive margin lever.
For Market Incumbents: Anchor stroke-center formulary positions through robotic reconstitution system partnerships at Hamburg University Hospital and Massachusetts General Hospital. Defend against mechanical thrombectomy substitution by embedding alteplase into comprehensive protocol bundles spanning imaging and endovascular rescue. Prioritize backward integration into plasma-derived raw material sourcing to neutralize fibrinogen price volatility.
For New Entrants and Emerging Players: The premium-to-economy price gap in lyophilized powder formats opens penetration pathways in Brazilian and Southeast Asian stroke networks. Target underpenetrated freestanding emergency departments in United States suburban markets with pre-filled syringe offerings bypassing hospital pharmacy overhead. Pursue ANVISA accelerated review to compress regulatory lag versus EMA-FDA pathway competitors.
For Investors and Strategic Acquirers: FDA biosimilar interchangeability rulings are the leading indicator that automatic pharmacy-level switching will reshape procurement concentration. Five-to-ten year viability favors manufacturers with captive CHO cell line production and established stroke-protocol integration. Monitor EU MDR device-drug combination certification queues as signal for competitive positioning durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA-FDA biosimilar harmonization compresses clinical trial redundancy for second-generation thrombolytics. |
| Manufacturing Scale-Up | CHO cell culture yield improvements at Basel facilities lower per-dose costs for emergency stockpiling. |
| Hospital System Partnership | Integrated delivery networks in Texas consolidate stroke-protocol procurement across imaging and thrombolytic bundles. |
| Software Companion Development | AI-powered stroke triage at Cleveland Clinic compresses door-to-needle decision windows for protocol integration. |
| Reimbursement Strategy | WHO Essential Medicines List inclusion unlocks national procurement tenders in emerging stroke networks. |
Research Methodology
Independent corroboration across hospital formulary directors, regulatory affairs leads at EMA-notified bodies, and cold-chain logistics specialists underwrites the qualitative findings. Primary interviews with stroke-center pharmacy managers, GPO contracts administrators, and mobile stroke unit paramedics combined with secondary validation from FDA thrombolytic guidance documents, EMA biosimilar comparability assessments, and hospital procurement databases. Bottom-up demand modeling across formulation formats triangulates against top-down manufacturer capacity disclosures.
Rate-of-change decomposition segments volume and value trajectories across injection solution, pre-filled syringe, and lyophilized powder formats throughout the forecast period. Modeled dimensions span acute ischemic stroke versus myocardial infarction applications, hospital versus emergency care center end users, and direct sales versus pharmacy distribution channels. CAGRs derive from treatment protocol penetration curves, biosimilar approval velocity assumptions, and mechanical thrombectomy substitution elasticities.
Underlying measurement precision varies by segment; United States and Germany stroke network data carry tighter precision than emerging market estimates. Forecasts reflect documented assumptions on regulatory pathway harmonization timing and plasma-derived input cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Brazil Diabetes Drugs Market